
 AI in Clinical Trials Market | 2026-2036
AI in Clinical Trials Market Size, Share, and Industry Trends Forecast 2026-2036
AI in Clinical Trials Market Insights
The gap between large pharmaceutical sponsors and mid-size biotech buyers is collapsing as cloud-native platforms democratize access to advanced analytics. IQVIA Inc. leverages its real-world data infrastructure to anchor enterprise-scale deployments across multiple therapeutic areas. Saama competes through specialized data integration layers that accelerate study startup timelines. Deep6.ai differentiates with NLP-driven patient-trial matching that reduces screening failure rates.
AI in clinical trials encompasses machine learning algorithms, natural language processing engines, and computer vision systems applied to protocol design, patient identification, data quality management, and regulatory submission workflows. These technologies process unstructured clinical records, imaging data, and genomic information to reduce trial duration and improve outcome predictability. Machine learning applications currently lead deployment volume, while natural language processing is expanding fastest as sponsors automate adverse event extraction from source documents. Cloud-based delivery dominates new implementations, though hybrid architectures persist among sponsors with legacy data governance requirements.
The FDA, EMA, and WHO are tightening evidentiary standards for AI tools supporting regulatory decision-making, requiring algorithmic transparency and validation documentation that shapes vendor development roadmaps. The FDA's draft guidance on AI-enabled medical devices creates compliance thresholds that filter smaller platform providers from enterprise procurement shortlists. EMA's qualification opinion pathway for novel methodologies adds a European validation layer for multinational sponsors. Stakeholders must monitor evolving evidentiary requirements across jurisdictions to align platform investments with regulatory acceptance criteria.
Market Dynamics
Cloud-native platforms are collapsing the capability gap between large pharmaceutical sponsors and mid-size biotech buyers, redistributing competitive leverage across the sponsor base and compressing traditional vendor tiering structures.
Growth Catalysts
- FDA Draft Guidance on AI-Enabled Medical Devices:The agency's algorithmic transparency requirements are filtering vendor pools and accelerating qualification investments among enterprise-scale platform providers.
- Natural Language Processing Engines:NLP-driven adverse event extraction from unstructured clinical records is automating pharmacovigilance workflows and compressing regulatory submission preparation timelines.
- Boston and San Francisco Clusters:Concentrated pharmaceutical R&D hubs in these metropolitan areas are generating dense demand for patient-trial matching and protocol optimization tools.
Market Restraints
- EMA Qualification Opinion Pathway:The European validation layer for novel methodologies adds procedural friction and extends vendor development roadmaps for multinational sponsors.
- Legacy Data Governance Architectures:Hybrid infrastructure requirements among established sponsors constrain pure cloud deployments and inflate integration costs.
- Algorithmic Validation Documentation:WHO evidentiary standards for AI-supported regulatory decision-making impose resource-intensive documentation burdens on platform developers.
Strategic Opportunities
- Computer Vision Systems:Convergence with imaging data pipelines for endpoint adjudication and biomarker quantification opens underdeveloped application areas in oncology and ophthalmology trials.
- Genomic Information Integration:Machine learning applications processing combined clinical and genomic datasets are creating white space in precision medicine trial designs.
- Real-World Data Infrastructure:Cloud-native platforms leveraging distributed health record networks can penetrate mid-size biotech segments previously excluded from enterprise analytics.
Industry Challenges
- Computational Biology Talent Scarcity:Shortages of professionals bridging clinical domain knowledge and machine learning engineering are constraining platform development velocity.
- Interoperability Standards Fragmentation:Absence of unified data exchange protocols between electronic health record systems and trial management platforms complicates patient identification workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI in Clinical Trials Market |
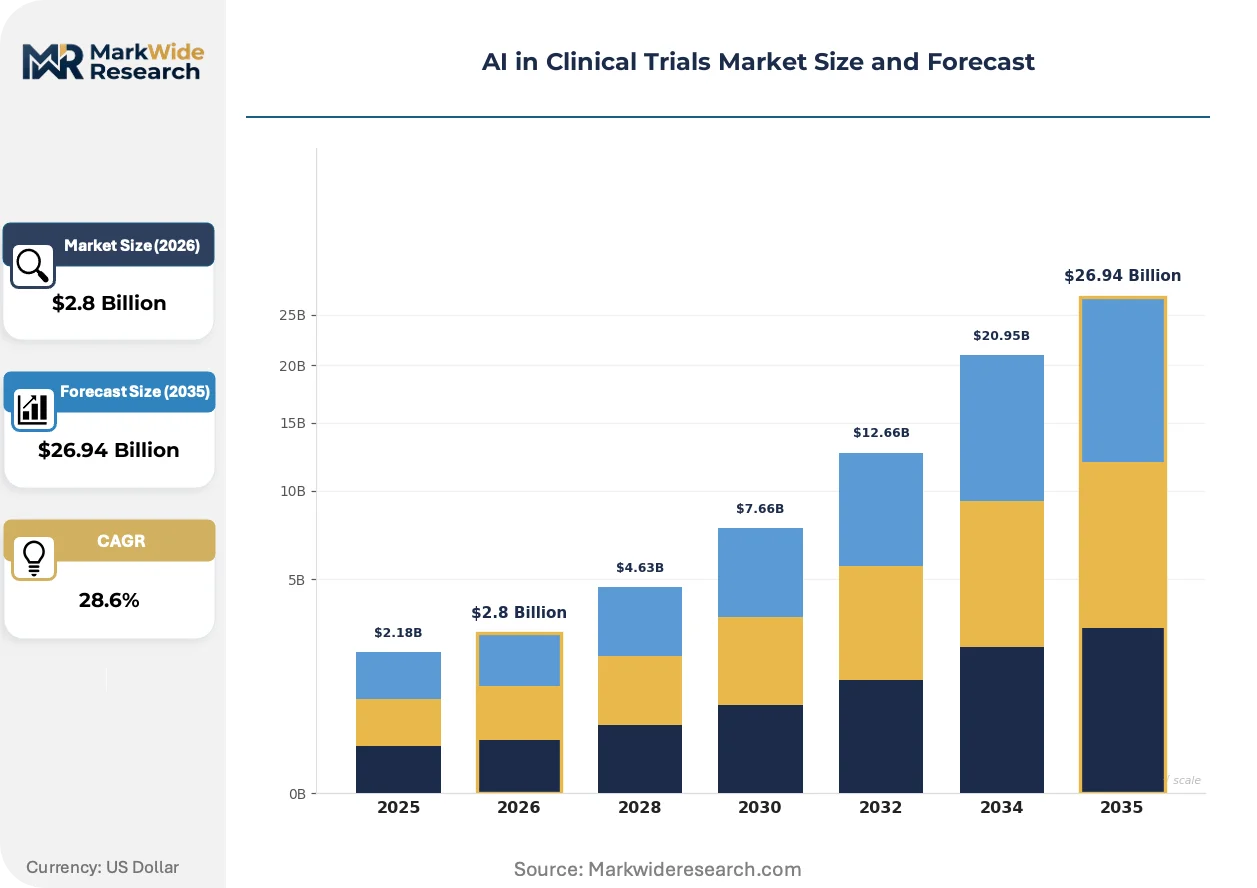
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $26.94 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Patient Recruitment, Data Analysis, Outcome Prediction, Clinical Monitoring Technology: Machine Learning, Natural Language Processing, Computer Vision, Data Mining End User: Pharmaceutical Companies, Biotech Firms, Research Organizations, Academic Institutions Delivery Mode: Cloud-Based, On-Premise, Hybrid, Software as a Service |
| Companies Covered | IQVIA Inc., Saama, Dassault Systèmes (Medidata), Phesi, AiCure, Deep6.ai, Unlearn.ai, Tempus AI, IBM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI in Clinical Trials Market Trends and Innovations
Machine learning deployment patterns are restructuring how sponsors source, validate, and operationalize AI tools across the clinical development lifecycle.
Natural language processing for patient-trial matching is fragmenting traditional site-based recruitment models. Mid-size biotech sponsors are adopting NLP engines at accelerated pace to reduce screening failure rates. This technology is fragmenting centralized site networks by enabling direct-to-patient identification through health record parsing.
REACH regulatory frameworks in Europe are tightening chemical and data governance standards that indirectly affect AI training dataset provenance requirements. Industrial consequence includes mandatory documentation of data lineage for algorithms supporting regulatory submissions. Multinational sponsors with European trial footprints are restructuring vendor qualification criteria to preempt compliance gaps.
Subscription-based platform access is displacing perpetual license models among biotech buyers with variable trial pipelines. Channel disruption concentrates in the United States where venture-backed sponsors prioritize operational flexibility over capital deployment. This shift is most visible in Boston and San Francisco metropolitan clusters where platform providers now lead with usage-based pricing structures.
AI in Clinical Trials Market Segmentation
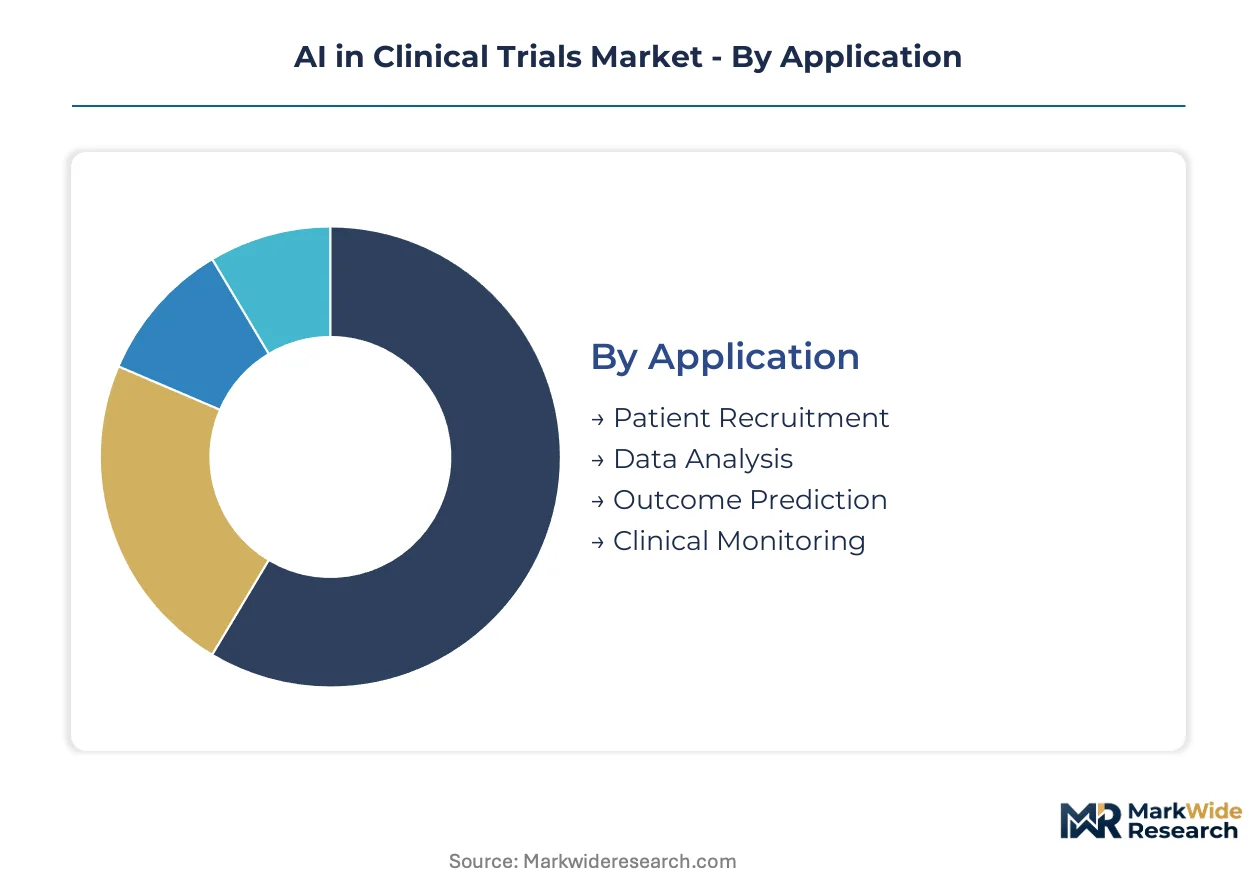
Segmentation in the AI clinical trials market reveals how regulatory requirements, data sovereignty constraints, and sponsor scale reshape technology procurement patterns. Understanding these dimensions exposes where vendor qualification thresholds concentrate and which deployment architectures satisfy multinational compliance obligations.
Application:
FDA algorithmic transparency requirements and EMA qualification opinions create divergent validation burdens across use cases, filtering which applications reach enterprise deployment at scale.
- Patient Recruitment:NLP engines parse unstructured electronic health records to match patients against protocol criteria, reducing screening failures. Demand clusters in Boston and San Francisco metropolitan areas where biotech density accelerates adoption of direct-to-patient identification tools.
- Data Analysis:Machine learning pipelines process multimodal datasets—imaging, genomic, clinical—to identify efficacy signals and safety patterns. Sponsors with European trial footprints face REACH-mandated data lineage documentation that inflates integration costs for algorithms trained on proprietary datasets.
- Outcome Prediction:Predictive models forecast trial success probabilities and patient response rates based on historical biomarker trajectories.
- Clinical Monitoring:Real-time adverse event detection from wearable sensors and patient-reported outcomes.
Established volume favors Data Analysis; emerging adoption favors Patient Recruitment.
Technology:
Cost tier differentiation separates enterprise-grade validated platforms from exploratory tools, with regulatory documentation burdens determining which technologies cross from pilot to production deployment.
- Machine Learning:Supervised and unsupervised algorithms trained on curated clinical datasets for endpoint prediction and protocol optimization. Cloud-native architectures dominate new implementations, though hybrid deployments persist among sponsors with HIPAA-compliant legacy infrastructure requirements.
- Natural Language Processing:Engines extract structured data from unstructured clinical narratives, automating pharmacovigilance and eligibility screening. WHO evidentiary standards for AI-supported regulatory decision-making impose documentation intensity that favors vendors with established validation frameworks.
- Computer Vision:Image analysis systems for endpoint adjudication in oncology and ophthalmology trials.
- Data Mining:Pattern recognition across real-world data repositories to identify comparator cohorts and historical controls.
Machine Learning anchors current procurement budgets; Natural Language Processing climbs the fastest as sponsors automate adverse event extraction workflows.
End User:
Customer type determines contract structure, with pharmaceutical sponsors demanding perpetual enterprise licenses and biotech buyers prioritizing subscription flexibility.
- Pharmaceutical Companies:Large sponsors deploy AI across therapeutic area portfolios with centralized governance and vendor qualification programs. FDA draft guidance on AI-enabled medical devices filters procurement shortlists to platforms with algorithmic transparency documentation.
- Biotech Firms:Mid-size sponsors adopt cloud-native platforms through usage-based pricing to match variable trial pipelines. Venture-backed companies in United States metropolitan clusters lead this shift away from capital-intensive perpetual licenses.
- Research Organizations:Contract research organizations integrating AI tools into service offerings for sponsor clients.
- Academic Institutions:University medical centers applying AI to investigator-initiated studies with limited commercial validation requirements.
Pharmaceutical Companies concentrate procurement volume; Biotech Firms gain share fastest as platform access democratizes.
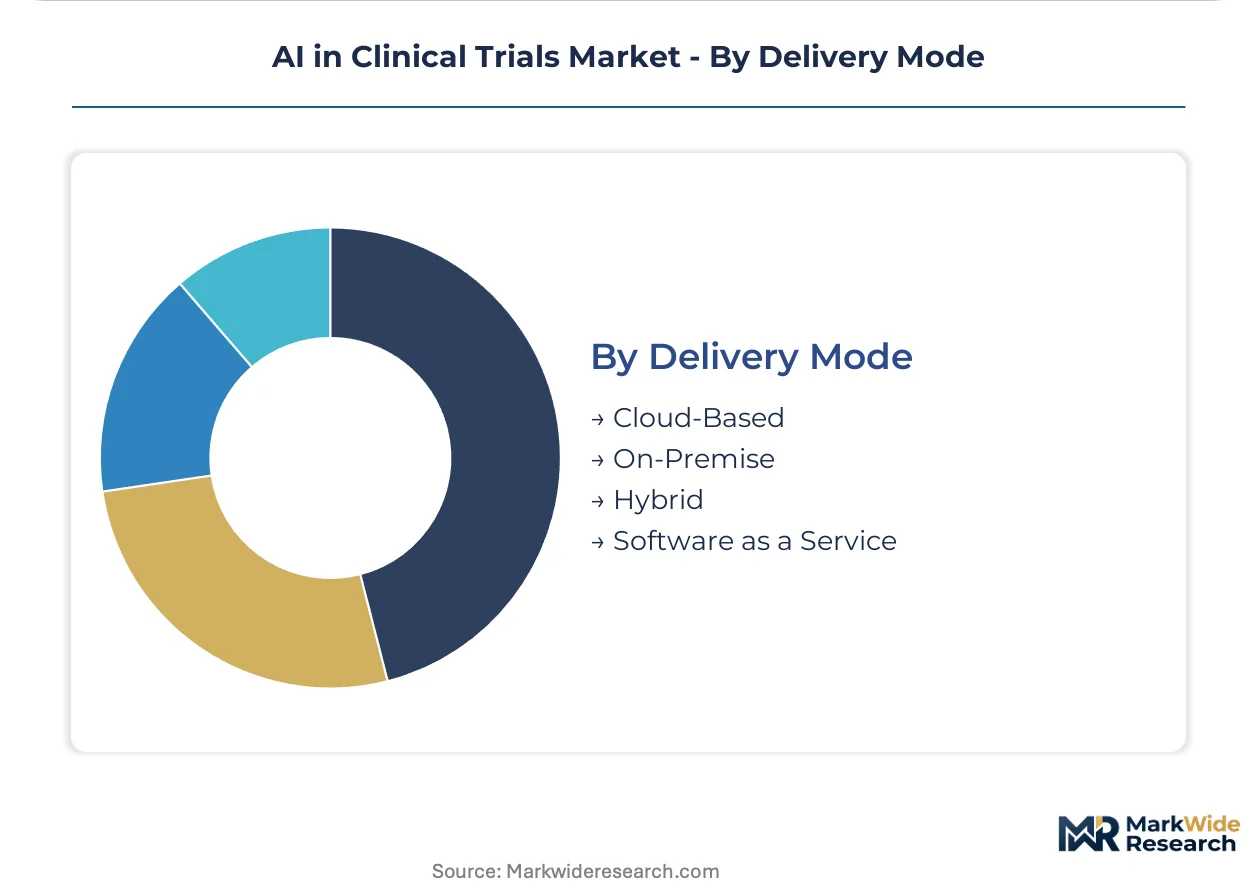
Delivery Mode:
Data governance maturity and jurisdictional privacy requirements fragment deployment architecture preferences across sponsor types.
- Cloud-Based:Fully managed SaaS architectures with elastic compute for variable trial workloads. United States-based sponsors with HIPAA Business Associate Agreements dominate this segment, though European GDPR constraints limit pure cloud adoption for cross-border trials.
- Software as a Service:Subscription access to validated AI modules without infrastructure ownership. Biotech sponsors in Boston and San Francisco metropolitan areas prioritize this model for operational flexibility over capital deployment.
- Hybrid:Split architectures keeping sensitive patient data on-premise while leveraging cloud compute for model training.
- On-Premise:Self-managed deployments satisfying stringent data residency requirements in specific jurisdictions.
Software as a Service captures emerging biotech demand; Hybrid architectures retain entrenched position among established pharmaceutical sponsors with legacy governance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vendor development roadmaps cluster around pharmaceutical R&D hubs where regulatory proximity accelerates qualification investments. FDA algorithmic transparency requirements and EMA qualification opinions filter which platforms reach production deployment.
United States
FDA draft guidance on AI-enabled medical devices creates compliance thresholds that reshape procurement shortlists. HIPAA Business Associate Agreements dominate cloud deployment architectures among sponsors. Boston and San Francisco metropolitan areas generate dense demand for patient-trial matching tools as biotech density accelerates direct-to-patient identification adoption.
Germany
EMA qualification opinion pathways add European validation layers that extend vendor development timelines for multinational sponsors. REACH regulatory frameworks tighten data governance standards affecting AI training dataset provenance documentation. The Rhine-Ruhr pharmaceutical corridor concentrates platform provider qualification investments to preempt compliance gaps.
Switzerland
Swissmedic alignment with FDA and EMA standards positions the country as a regulatory bridge for algorithm validation. Data residency requirements favor hybrid cloud architectures among established sponsors with legacy governance frameworks. Basel's pharmaceutical cluster anchors enterprise-scale deployments across multiple therapeutic areas.
United Kingdom
MHRA post-Brexit regulatory autonomy creates parallel validation requirements for AI-supported regulatory decision-making. GDPR constraints limit pure cloud adoption for cross-border trials with European footprints. London's biotech venture ecosystem drives subscription-based platform access among mid-size sponsors prioritizing operational flexibility.
China
NMPA evolving standards for AI-enabled medical devices reshape vendor entry strategies into the domestic market. Dual carbon goals accelerate cloud-native platform adoption to reduce on-premise infrastructure energy footprints. Shanghai and Beijing pharmaceutical hubs concentrate demand for protocol optimization and patient identification tools.
AI in Clinical Trials Market Competitive Landscape
Concentration sits with enterprise-scale platform providers possessing established validation frameworks and real-world data infrastructure. The vendor base stratifies across three tiers: global CRO-affiliated platforms, specialized AI-native vendors, and cloud-native challengers. Two dominant competitive moves are reshaping positioning—strategic partnerships between AI vendors and electronic health record networks, and portfolio diversification into adjacent regulatory submission workflows.
Among the CRO-affiliated tier, IQVIA Inc. and Dassault Systèmes occupy positions anchored by real-world data infrastructure and enterprise-scale deployment capabilities. Within the AI-native specialist segment, Deep6.ai and Saama exemplify vendors competing through differentiated data integration layers and NLP-driven matching engines. These company groupings represent the archetype boundaries where qualification investments and regulatory documentation capabilities determine procurement outcomes.
| Leading Market Players |
|---|
| IQVIA Inc. |
| Saama |
| Dassault Systèmes (Medidata) |
| Phesi |
| AiCure |
| Deep6.ai |
| Unlearn.ai |
| Tempus AI |
| IBM |
| Others |
Pricing and Supply Chain Analysis
FDA algorithmic transparency requirements gate both vendor qualification and pricing tier differentiation in the AI clinical trials market, compressing margins for platforms lacking validation documentation while enabling premium positioning for compliant providers. This regulatory filter simultaneously constrains supply-side participation and stratifies price realization across the sponsor base.
Pricing Analysis
FDA draft guidance on AI-enabled medical devices dictates the pricing tier structure by mandating algorithmic validation documentation that smaller vendors cannot cost-effectively produce. Three-tier pricing structure across premium, standard, and economy levels separates enterprise-grade platforms with EMA qualification opinions from exploratory tools lacking regulatory documentation. Cost compression in the standard tier is intensifying because cloud-native challengers are undercutting legacy perpetual-license models. Biotech firms with variable trial pipelines exhibit highest price sensitivity, while pharmaceutical companies prioritize compliance over cost.
Supply Chain Analysis
Inventory cycles for AI training datasets and validation compute resources run 4-6 months longer than typical software procurement timelines due to data lineage documentation requirements. Supply concentrates in the United States for cloud infrastructure and regulatory proximity, Germany for EMA-aligned validation services, and Switzerland for hybrid governance architectures. Platform development draws from curated clinical record repositories, genomic databases, and imaging data pipelines. Single-source vulnerability sits with proprietary real-world data networks controlled by established CRO-affiliated vendors. Distribution runs through direct enterprise sales for pharmaceutical sponsors and subscription marketplaces for biotech buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AI clinical trials market functions as a service-attach opportunity where subscription-based platform access and ongoing validation support expand faster than perpetual license revenue. Recurring revenue from algorithm retraining and regulatory documentation updates now outpaces initial deployment fees.
For Market Incumbents: Fortify algorithmic transparency documentation and EMA qualification pathways to defend against cloud-native challengers undercutting on price. Deepen backward integration into proprietary real-world data networks to lock out competitors lacking comparable training dataset scale. Prioritize certification investment in REACH-compliant data governance to preempt European compliance gaps. For New Entrants and Emerging Players: Lead with NLP-driven patient-trial matching tools targeting mid-size biotech sponsors in Boston and San Francisco metropolitan clusters where incumbent platforms are overengineered for smaller trial volumes. White space sits in computer vision systems for oncology endpoint adjudication and genomic information integration for precision medicine trials. Go-to-market through usage-based pricing models that match variable pipeline cash flows. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed AI-native specialists possessing FDA-aligned validation frameworks but lacking enterprise-scale deployment infrastructure. Long-term viability hinges on regulatory documentation capabilities becoming scarcer as EMA and WHO standards tighten. Watch for inflection signals in multinational sponsor procurement shortlists where algorithmic transparency documentation filters vendor pools.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Documentation Investment | FDA algorithmic transparency compliance enables enterprise procurement shortlist inclusion. |
| Real-World Data Network Partnership | Electronic health record integration accelerates patient-trial matching velocity. |
| EMA Qualification Pathway Pursuit | European validation layer secures multinational sponsor contracts. |
| Cloud-Native Platform Migration | Usage-based pricing captures biotech demand with variable trial pipelines. |
| Computer Vision Capability Buildout | Oncology and ophthalmology imaging endpoints open underdeveloped application areas. |
Research Methodology
A standing panel of clinical operations executives, regulatory affairs leads, data science directors, and biotech CFOs provided ongoing calibration across the primary research phase. This practitioner input combined with FDA filing databases, EMA qualification opinion records, ClinicalTrials.gov protocol repositories, and venture financing disclosures enabled bottom-up and top-down triangulation of platform adoption rates and pricing dynamics.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including application type, technology category, sponsor scale, and delivery architecture. CAGRs were derived from algorithmic deployment velocity curves and sponsor procurement cycle analysis. Forecast inputs incorporated regulatory guidance publication timelines and cloud infrastructure expansion patterns.
Forecasts assume regulatory continuity in FDA, EMA, and WHO evidentiary regimes; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Research
Global Clinical Trial Supply Market
Clinical Research
North America Clinical Trials Market
Clinical Research
Clinical Trials Market
Clinical Research
Pharmacovigilance Outsourcing Market
Clinical Research
Global Clinical Trial Supply Management Market
Clinical Research
US Virtual Clinical Trials Market
Clinical Research
Patient-Reported Outcome Data Monetization Market
Clinical Research
Global in Silico Clinical Trials Market
Clinical Research
AI-Assisted Clinical Trial Protocol Design Market
Clinical Research
Non-Alcoholic Steatohepatitis Clinical Trials Market
Clinical Research
Clinical Data Analytics Market
Clinical Research
Biomarker Discovery Outsourcing Services Market
Clinical Research
Real World Evidence Linkage Services Market
Clinical Research
Generative AI in Clinical Trials Market
Clinical Research
Asia-Pacific Contract Research Organization Market
Clinical Research
Omics-Based Clinical Trials Market