
 Outdoor Commercial Grills Market | 2026-2036
Outdoor Commercial Grills Market Size, Share, and Industry Trends Forecast 2026-2036
Outdoor Commercial Grills Market Analytics
NSF/ANSI Standard 4 certification for commercial cooking equipment is unwinding the competitive set, forcing smaller fabricators to retool or exit. Crown Verity leverages its Canadian manufacturing base to sustain NSF-certified output across North American hospitality channels. Blackstone competes through high-volume production of portable griddle systems aimed at food truck operators. Magikitch'n anchors its position with permanent-installation gas lines engineered for municipal fire code compliance.
Outdoor commercial grills are thermostatically controlled cooking appliances fabricated from 304-grade stainless steel, designed to sustain continuous operation at surface temperatures exceeding 500°F for protein and vegetable preparation in revenue-generating foodservice environments. Gas grills dominate the product type landscape due to instantaneous ignition and precise temperature modulation demanded by high-throughput restaurant kitchens. Wood pellet grills represent the fastest-growing product category as smoke-flavor profiles differentiate barbecue-centric concepts in competitive dining markets. The end-user dimension shows food trucks and catering services gravitating toward portable units while hotels favor built-in models that integrate with poolside and rooftop amenity designs.
NSF International standards, the EPA's volatile organic compound emission guidelines for charcoal combustion, and local fire marshal ordinances collectively shape product design and market access across the United States. The EPA thresholds for particulate matter from solid-fuel cooking equipment are pushing manufacturers toward gas and electric alternatives in urban jurisdictions with air quality management districts. Stakeholders must monitor evolving municipal outdoor dining ordinances and energy transition timelines to align product portfolios with compliance trajectories and infrastructure availability.
Market Dynamics
NSF/ANSI Standard 4 certification is compressing the competitive set by forcing smaller fabricators to retool or exit, while EPA volatile organic compound thresholds accelerate the shift from charcoal to gas and electric alternatives in urban air quality districts.
Growth Catalysts
- Texas-California-Florida Patio Dining Concentration:Year-round outdoor revenue operations in these three states drive replacement cycles and sustain demand for thermostatically controlled 304-grade stainless steel units. Foodservice operators prioritize surface temperatures exceeding 500°F for high-throughput protein preparation.
- Wood Pellet Smoke-Flavor Differentiation:Barbecue-centric dining concepts adopt pellet systems to distinguish menus in competitive markets, creating incremental demand beyond traditional gas installations.
- Food Truck Mobility Requirements:Portable griddle systems capture catering and mobile foodservice operators seeking NSF-certified equipment that withstands transit vibration and variable power access.
Market Restraints
- 304-Grade Stainless Steel Input Volatility:Nickel and chromium price swings compress fabricator margins and complicate long-term contract pricing with hospitality chains.
- Canadian Manufacturing Concentration:Crown Verity and select competitors anchor production north of the border, exposing the supply base to cross-border tariff friction and currency fluctuation.
- Charcoal Combustion Substitution Pressure:EPA particulate matter thresholds and municipal fire marshal ordinances render solid-fuel equipment economically unviable in urban jurisdictions with air quality management districts.
Strategic Opportunities
- Rooftop Hotel Amenity Integration:Built-in gas line configurations engineered for municipal fire code compliance capture poolside and rooftop dining installations in resort and urban hospitality properties.
- Electric Infrastructure Readiness:Energy transition timelines in California and New York create white space for electric grill portfolios as grid capacity and commercial kitchen wiring standards evolve.
- IoT Temperature Monitoring Convergence:Connected thermostatic controls paired with kitchen management systems enable predictive maintenance contracts and differentiate premium equipment tiers.
Industry Challenges
- NSF Certification Timeline Compression:Food equipment qualification cycles tighten as NSF International revises testing protocols, extending product development schedules and straining R&D budgets.
- Municipal Ordinance Fragmentation:Local fire marshal ordinances and outdoor dining permit requirements vary by city, forcing manufacturers to maintain multiple specification variants for single metropolitan areas.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Outdoor Commercial Grills Market |
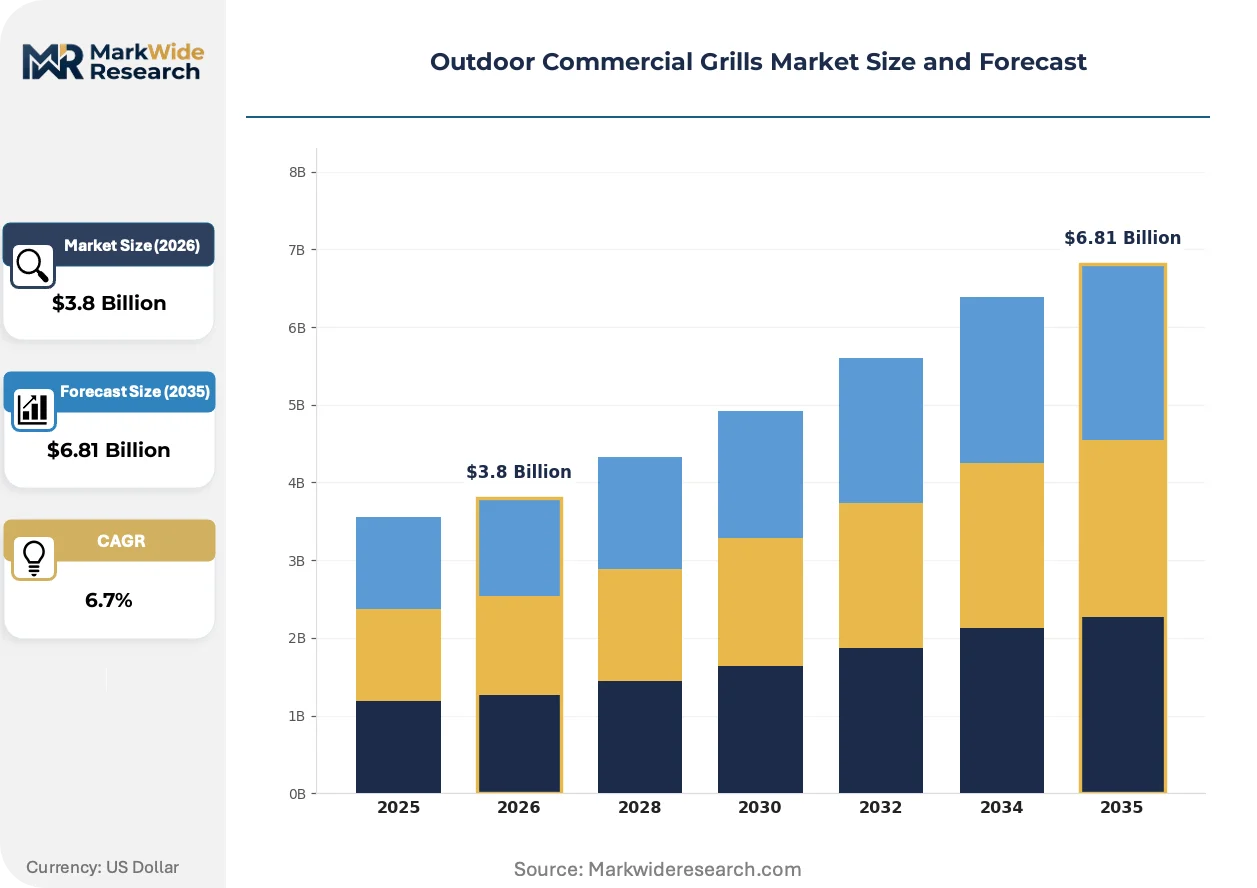
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Grills, Charcoal Grills, Wood Pellet Grills, Electric Grills End User: Restaurants, Food Trucks, Catering Services, Hotels Installation Type: Permanent Installation, Portable Units, Built-in Models, Freestanding Grills Size: Small, Medium, Large, Extra Large |
| Companies Covered | Crown Verity, Blackstone, R&V Works, Holstein Manufacturing, Meadow Creek, Southern Pride, Louisiana Grills, Old Country BBQ Pits, Magikitch’n, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Outdoor Commercial Grills Market Evolving Landscape
Connected kitchen infrastructure and thermostatic precision are redefining equipment specifications, while regulatory pressure on combustion emissions reshapes fuel-type portfolios across commercial foodservice channels.
Infrared burner technology is fragmenting the high-heat segment by delivering instantaneous ignition and zone-specific temperature modulation without the thermal lag of traditional convection systems. Fast-casual chains with high-throughput lunch rushes adopt these configurations to compress ticket times and reduce energy waste during idle periods. The technology is fragmenting competitive positioning by enabling smaller footprints and lower ventilation requirements that challenge conventional gas line infrastructure assumptions.
EPA volatile organic compound emission guidelines for charcoal combustion are tightening enforcement in urban air quality management districts, particularly in California's South Coast and San Joaquin Valley regions. Manufacturers respond by accelerating gas and electric alternative development while phasing out solid-fuel SKUs from catalogs distributed to metropolitan accounts. Hotels and resorts in these districts face permit denials for charcoal installations, redirecting capital expenditure toward compliant equipment categories.
After-sales service unbundling is compressing traditional distribution relationships as hospitality procurement teams separate equipment acquisition from installation and maintenance contracts. Third-party foodservice equipment servicers capture recurring revenue streams previously retained by manufacturer-authorized dealers, particularly in Texas and Florida where independent operator density supports specialized technician networks. This pattern concentrates in multi-unit casual dining chains with centralized procurement functions and standardized equipment specifications across regional footprints.
Outdoor Commercial Grills Market Segmentation
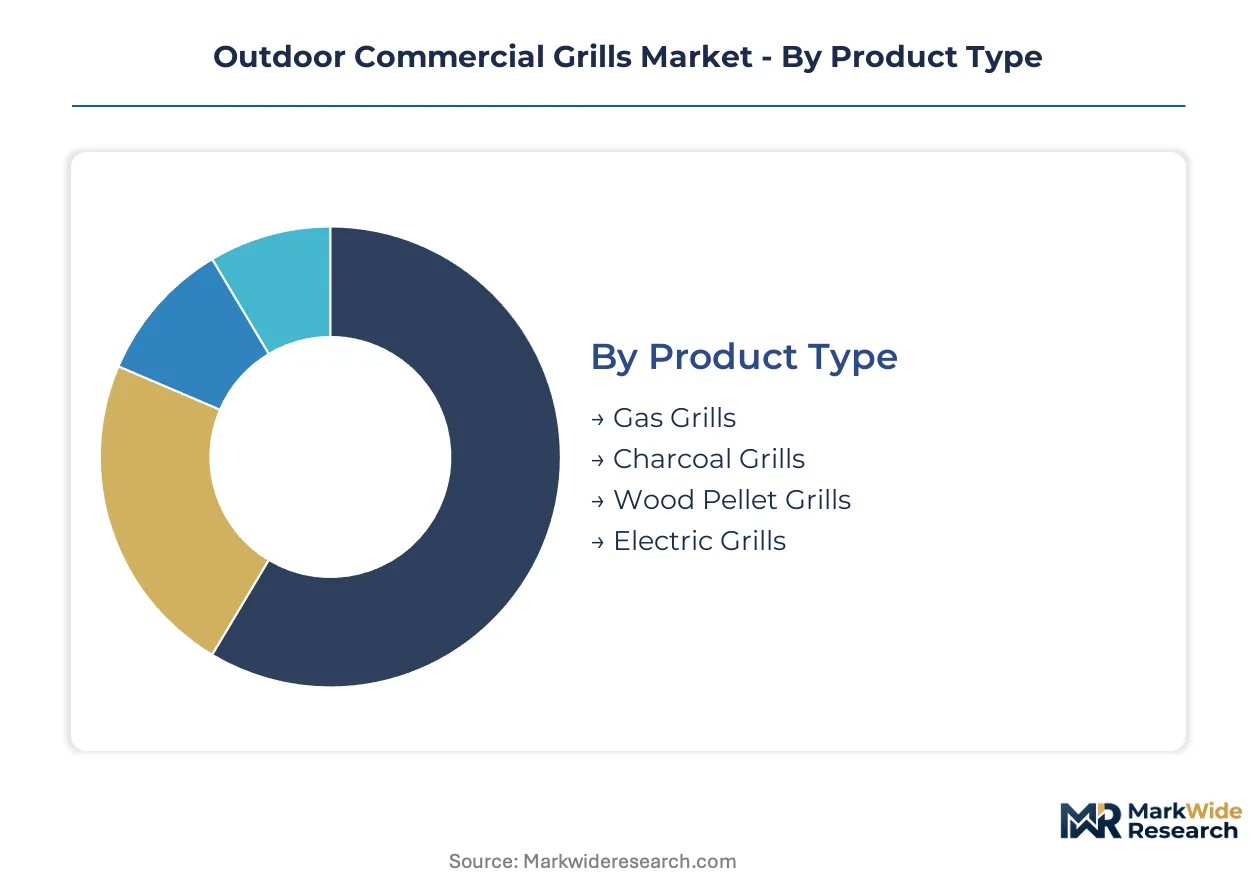
Outdoor commercial grill procurement patterns diverge sharply across fuel types, mobility requirements, and thermal capacity specifications. Each segmentation dimension carries distinct regulatory exposure, margin profiles, and replacement cycle dynamics that shape manufacturer portfolio priorities.
Product Type:
Domestic production concentrates on gas and electric configurations engineered for NSF/ANSI Standard 4 compliance, while wood pellet systems draw specialized fabrication from Canadian and Midwestern suppliers serving export-oriented barbecue concepts.
- Gas Grills:Thermostatically controlled 304-grade stainless steel systems with instantaneous ignition and precise temperature modulation. Texas, California, and Florida hospitality operators prioritize these units for year-round patio dining throughput exceeding 500°F surface temperatures. EPA volatile organic compound thresholds accelerate displacement of solid-fuel alternatives in urban air quality districts.
- Wood Pellet Grills:Automated auger-fed combustion systems generating controlled smoke-flavor profiles through hardwood pellet combustion. Barbecue-centric dining concepts in competitive Southern and Midwestern markets adopt these configurations for menu differentiation. Supply chains concentrate in Wisconsin and Minnesota fabrication clusters.
- Charcoal Grills:Solid-fuel equipment facing permit denials in California South Coast and San Joaquin Valley air quality management districts.
- Electric Grills:Zero-emission alternatives gaining traction in California and New York as commercial kitchen wiring standards evolve.
Gas grills command the established base. The steepest expansion runs through wood pellet configurations.
End User:
Volume concentration sits with multi-unit restaurant chains specifying standardized equipment across regional footprints, while mobility requirements fragment procurement toward specialized portable fabricators.
- Restaurants:Quick-service and casual dining chains drive replacement cycles through centralized procurement functions. These operators demand NSF-certified equipment with predictive maintenance compatibility and integration with kitchen management systems.
- Hotels:Resort and urban hospitality properties specify built-in gas line configurations for poolside and rooftop amenity integration. Municipal fire code compliance engineering differentiates supplier relationships in Florida and Arizona destination markets.
- Food Trucks:Mobile operators prioritizing transit durability and variable power access.
- Catering Services:Event-focused procurement emphasizing rapid deployment and breakdown logistics.
Restaurants anchor volume procurement. Hotels are expanding most quickly through amenity-driven capital expenditure.
Installation Type:
Permanent infrastructure commitments dominate hotel and resort capital planning, while food truck and catering mobility requirements sustain portable fabrication specialists.
- Permanent Installation:Fixed gas line configurations requiring municipal fire marshal approval and professional ventilation engineering. These installations dominate resort and urban hospitality properties where outdoor dining revenue justifies infrastructure investment.
- Built-in Models:Custom-fabricated enclosures integrating with poolside and rooftop architectural designs. California and Florida design-build contractors specify these for cohesive amenity aesthetics.
- Portable Units:Transit-optimized systems capturing food truck and mobile catering demand.
- Freestanding Grills:Modular configurations for flexible patio layouts and seasonal repositioning.
Permanent installation commands the established base. Built-in models are climbing the fastest through hospitality amenity integration.
Size:
Cost tier differentiation separates entry-level small-format units from premium extra-large configurations, with medium and large capacities capturing mainstream foodservice throughput requirements.
- Large:High-throughput configurations serving 500+ covers daily in quick-service lunch rushes. Infrared burner technology adoption concentrates in this tier for zone-specific temperature modulation without thermal lag.
- Medium:Versatile capacity range dominating independent restaurant and casual dining procurement. These units balance footprint constraints with protein preparation volume for 200-400 daily covers.
- Small:Compact formats for limited patio footprints and specialty protein stations.
- Extra Large:Custom-fabricated systems for resort banquet operations and stadium concessions.
Medium formats command the established base. Large configurations are gaining share fastest through infrared technology adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA volatile organic compound thresholds and municipal fire marshal ordinances are redrawing procurement geography across outdoor commercial foodservice equipment. Fabricators align production footprints with regulatory enforcement intensity and patio dining revenue concentration.
United States
Texas, California, and Florida hospitality operators drive replacement cycles through year-round outdoor revenue operations. EPA particulate matter thresholds in California's South Coast and San Joaquin Valley air quality management districts accelerate displacement of solid-fuel equipment. Los Angeles and San Diego design-build contractors specify built-in gas line configurations for rooftop hotel amenity integration.
Canada
Crown Verity anchors North American NSF-certified output from its domestic manufacturing base, serving cross-border hospitality channels. Canadian currency fluctuation and tariff exposure complicate long-term contract pricing with United States chains. Ontario fabrication clusters concentrate on thermostatically controlled 304-grade stainless steel systems for export-oriented barbecue concepts.
Germany
REACH chemical compliance and CE marking requirements shape product qualification cycles for commercial cooking equipment entering European hospitality markets. Bavarian and North Rhine-Westphalia industrial clusters engineer precision thermostatic controls for fast-casual chains. Berlin and Munich hotel developers specify permanent-installation gas lines for rooftop dining amenities.
Australia
New South Wales and Victoria hospitality operators adopt wood pellet configurations for smoke-flavor menu differentiation in competitive Sydney and Melbourne dining markets. The country's national environmental regulator enforces emission thresholds on solid-fuel commercial cooking equipment. Queensland resort properties drive demand for built-in poolside grill installations.
Japan
METI energy efficiency standards and JIS certification requirements compress product development timelines for commercial kitchen equipment. Tokyo and Osaka fast-casual chains prioritize infrared burner technology for high-throughput lunch operations. Kanto region fabrication specialists supply thermostatically controlled systems for compact urban patio footprints.
Outdoor Commercial Grills Market Competitive Landscape
Player mix skews toward mid-cap fabrication specialists with captive NSF certification capabilities and cross-border manufacturing footprints. Market structure concentrates around three strategic tiers: Canadian-based full-line suppliers, United States portable equipment specialists, and regional permanent-installation engineering firms. Competitive moves center on certification timeline acceleration and municipal fire code compliance engineering.
Within the Canadian manufacturing tier, Crown Verity exemplifies the cross-border NSF-certified supplier archetype. Blackstone occupies a position among United States-based portable equipment fabricators serving mobile foodservice operators. Magikitch'n represents the permanent-installation engineering specialist archetype with municipal fire code compliance capabilities.
| Leading Market Players |
|---|
| Crown Verity |
| Blackstone |
| R&V Works |
| Holstein Manufacturing |
| Meadow Creek |
| Southern Pride |
| Louisiana Grills |
| Old Country BBQ Pits |
| Magikitch'n |
| Others |
Value Network & Pricing Analysis
Gas-to-electric fuel substitution in California and New York municipal jurisdictions simultaneously redraws supplier geography toward domestic electrical-component fabricators and compresses pricing premiums previously commanded by Canadian gas-line specialists. This shift fragments procurement patterns across coastal urban markets while concentrating volume pricing power with NSF-certified electric grill producers.
Pricing Analysis
Certification level creates the primary spread across the competitive set, with NSF/ANSI Standard 4 qualification separating premium-tier 304-grade stainless steel systems from uncertified economy alternatives. Three-tier pricing structure across premium, standard, and economy levels tracks thermal capacity and IoT integration depth. Cost compression in the mid-tier segment intensifies as nickel and chromium input volatility squeezes fabricator margins. Independent restaurant operators exhibit the highest price sensitivity due to limited capital expenditure flexibility, while multi-unit chains absorb premium pricing for predictive maintenance compatibility.
Supply Chain Analysis
Port congestion across Vancouver and Los Angeles trade lanes complicates inbound logistics for Canadian-manufactured Crown Verity units serving Texas and Florida hospitality operators. Geographic supply concentration centers on Ontario fabrication clusters, Wisconsin wood pellet system producers, and California electric grill assemblers. Raw material dependencies rest on 304-grade stainless steel sheet, nickel-chromium alloys, and precision thermostatic control modules. Single-source vulnerability concentrates in Canadian currency exposure and cross-border tariff friction. Distribution runs through manufacturer-authorized dealers, third-party foodservice equipment servicers, and direct procurement channels for centralized hospitality chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where NSF certification timelines and municipal fire code compliance engineering create structural switching costs that defend incumbent positions against price-based competition.
For Market Incumbents: Consolidate certification capabilities through accelerated NSF/ANSI Standard 4 testing protocol investment, compressing product development cycles that strain smaller fabricators. Anchor production capacity in Ontario or domestic electrical-component hubs to mitigate cross-border tariff exposure from Canadian manufacturing concentration. Vertical integration into 304-grade stainless steel sheet procurement hedges nickel and chromium price volatility threatening mid-tier margins. For New Entrants and Emerging Players: After-sales service unbundling presents a service-layer gap where incumbent manufacturers cede recurring revenue to third-party technicians. Target electric grill portfolios for California and New York energy transition timelines as grid capacity expands commercial kitchen wiring standards. Penetrate through IoT temperature monitoring convergence paired with kitchen management system integration, bypassing capital-intensive fabrication infrastructure. For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-cap Canadian fabrication specialists holding captive NSF certification capabilities but lacking electric portfolio diversification. Long-term viability favors suppliers with cross-fuel flexibility across gas, pellet, and electric configurations. Monitor EPA volatile organic compound enforcement intensity in California air quality districts as the inflection signal for charcoal substitution acceleration and electric infrastructure readiness timing.| Strategic Initiative | Industry Significance |
|---|---|
| NSF Certification Acceleration | Compressed qualification cycles force retooling investments that smaller fabricators cannot absorb. |
| Electric Portfolio Development | California and New York energy transition timelines create first-mover positioning in zero-emission equipment. |
| IoT Control Integration | Predictive maintenance contracts differentiate premium tiers from commodity gas grill alternatives. |
| Cross-Border Manufacturing Diversification | Tariff exposure from Canadian concentration necessitates domestic assembly footprint expansion. |
| After-Sales Service Captivity | Third-party technician networks capture recurring revenue streams previously retained by dealers. |
Research Methodology
Initial hypotheses were tested against primary input from foodservice equipment procurement directors, NSF certification testing engineers, hospitality chain maintenance directors, and municipal fire marshal inspection officers and refined through secondary validation. Primary fieldwork combined structured interviews with equipment specification committees at multi-unit restaurant operators and aftermarket service technicians in Texas and Florida. Secondary sources encompassed EPA emission threshold documentation, NSF International protocol revisions, customs trade data for 304-grade stainless steel imports, and hospitality capital expenditure disclosures. Bottom-up demand aggregation across end-user segments was triangulated against top-down market sizing from fabrication capacity estimates.
Variance decomposition across the projection horizon isolates volume drivers by fuel type, installation configuration, and thermal capacity tier. The analytical framework models segmentation dimensions including product type, end-user category, installation permanence, and geographic regulatory cluster. CAGRs were derived from replacement cycle analysis in year-round patio dining markets and penetration assumptions for wood pellet and electric alternatives. Industry-specific forecast inputs incorporate nickel price volatility indices and municipal outdoor dining ordinance adoption rates.
Underlying assumptions cover sustained EPA enforcement intensity in California air quality districts and stable cross-border trade conditions for Canadian-manufactured equipment, with deviation risk concentrated in tariff policy shifts and accelerated electric grid infrastructure timelines. Forecasts reflect these documented conditions without contingency for regulatory reversal or commodity price collapse. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Switzerland Kitchen Appliances Product Market
Kitchen Appliances
Europe Household Refrigerator Market
Kitchen Appliances
China Kitchen Appliances Market
Kitchen Appliances
Household Bread Machine Market
Kitchen Appliances
Residential Induction Cooktops Market
Kitchen Appliances
Built-In Kitchen Appliances Market
Kitchen Appliances
Household Coffee Machine Market
Kitchen Appliances
China Mixer Grinder Market
Kitchen Appliances
Kitchen Chimney Market
Kitchen Appliances
North America Electric Kettle Market
Kitchen Appliances
US Cookware Market
Kitchen Appliances
Brazil Kitchen Appliances Market
Kitchen Appliances
Smart Kitchen System Market
Kitchen Appliances
Kitchen Appliances Market
Kitchen Appliances
Sandwich Maker Market
Kitchen Appliances
Malaysia Smart Kitchen Appliances Market