
 Low-Temperature Sterilization Market | 2026-2036
Low-Temperature Sterilization Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Temperature Sterilization Market Outlook
The gap between premium vaporized hydrogen peroxide systems and commodity ethylene oxide chambers is expanding as instrument manufacturers specify gentler sterilization protocols for polymer-coated and electronic-enabled devices. STERIS Corporation dominates the North American installed base through its integrated equipment and consumables model. Getinge AB leverages its surgical workflow integration to sustain premium pricing across European and Asian hospital networks. Tuttnauer Ltd. competes aggressively on capital cost, anchoring its position in mid-tier clinics and regional medical centers.
Low-temperature sterilization encompasses processes that eliminate microbial life on heat-sensitive medical devices at temperatures typically below 60 degrees Celsius, using reactive gases or vaporized chemicals that penetrate lumens and complex geometries without thermal degradation. The primary purpose is to reprocess advanced surgical instruments, endoscopes, and implantable devices that would distort or fail under steam autoclave conditions. Hydrogen peroxide and vaporized hydrogen peroxide segments are capturing the fastest growth as instrument complexity rises and cycle-time pressures intensify in high-throughput surgical departments. The ethylene oxide segment retains substantial volume but faces structural headwinds from occupational exposure regulations and abatement compliance costs that compress margins for commodity operators.
The FDA enforces stringent reprocessing validation requirements under its device guidance, while EPA regulations on ethylene oxide emissions are reshaping facility siting and abatement investment decisions across the United States. The EU Medical Device Regulation (MDR) and REACH frameworks impose additional conformity and chemical safety burdens on systems deployed in European healthcare settings. Stakeholders must monitor regulatory divergence between jurisdictions as sterilization modality choices become increasingly locked into long-term capital commitments and instrument compatibility portfolios.
Market Dynamics
Surgical instrument manufacturers are embedding polymer coatings and electronic sensors that degrade above 60 degrees Celsius, forcing sterilization departments to abandon steam autoclaves and validate hydrogen peroxide-based alternatives. This materials evolution is restructuring capital allocation across hospital networks and ambulatory surgical centers.
Growth Catalysts
- EPA Ethylene Oxide Emission Limits:The EPA's tightened ambient air standards for EtO are accelerating facility closures and replacement investments in vaporized hydrogen peroxide systems across United States healthcare infrastructure.
- Endoscope Reprocessing Volumes:Rising minimally invasive surgical procedures are expanding installed base requirements for low-temperature sterilizers capable of processing flexible endoscope lumens without thermal damage.
- Polymer-Coated Instrument Adoption:Instrument manufacturers specifying hydrogen peroxide-compatible coatings for robotic surgery tools are creating locked-in demand for validated low-temperature protocols.
Market Restraints
- Platinum Catalyst Cost Volatility:Hydrogen peroxide sterilizers depend on platinum-group catalysts for gas decomposition, exposing operators to precious metal price swings that compress service contract margins.
- EtO Abatement Capital Burden:Remaining ethylene oxide operators face structural cost disadvantages as catalytic oxidation and wet scrubber systems add seven-figure compliance investments per facility.
- Lumen Penetration Limitations:Narrow-diameter flexible endoscopes below 1mm internal channel diameter present technical sterilization assurance challenges that hydrogen peroxide systems have not fully resolved.
Strategic Opportunities
- India Hospital Modernization:The country's PLI scheme for medical devices and expanding private hospital networks create whitespace for low-temperature sterilizer deployment as surgical volume concentrates in tier-1 cities.
- EU MDR Validation Services:The Medical Device Regulation's reprocessing documentation requirements are opening adjacent revenue streams for sterilization-as-a-service providers offering validated protocol packages.
- RFID-Enabled Load Traceability:Converging sterilizer hardware with radio-frequency identification and hospital information systems is enabling outcome-based service pricing and predictive maintenance contracts.
Industry Challenges
- Sterilization Science Talent Scarcity:Hospital departments struggle to recruit microbiologists and biomedical engineers capable of validating novel low-temperature cycles for complex instrument geometries.
- Legacy EtO Infrastructure Stranding:Facilities with recently upgraded ethylene oxide abatement systems face sunk-cost dilemmas when evaluating hydrogen peroxide conversion timelines.
- Instrument Compatibility Certification Delays:Original equipment manufacturer validation studies for new polymer-electronic hybrid devices extend sterilizer qualification timelines by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Temperature Sterilization Market |
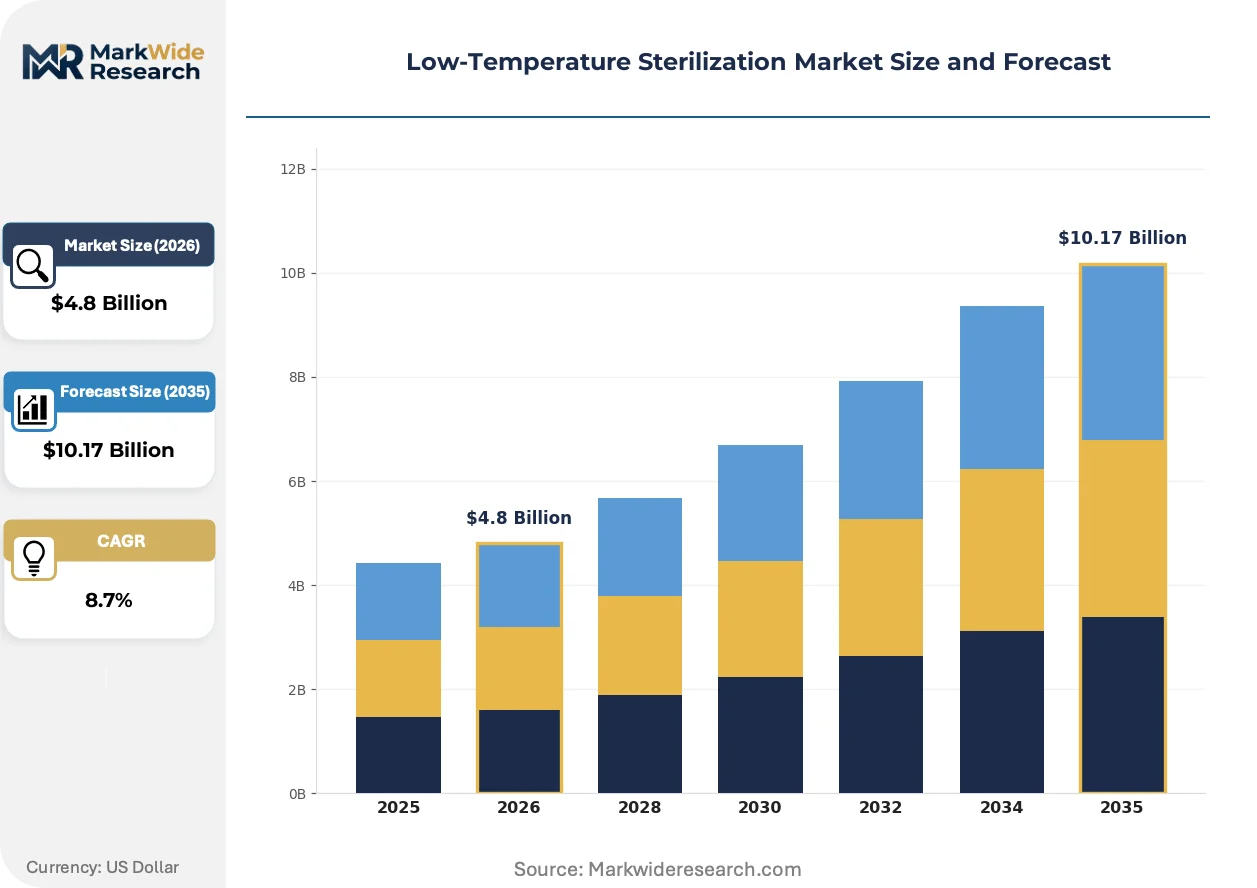
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethylene Oxide, Hydrogen Peroxide, Formaldehyde, Vaporized Hydrogen Peroxide End User: Hospitals, Clinics, Laboratories, Dental Offices Application: Medical Devices, Surgical Instruments, Laboratory Equipment, Pharmaceutical Products Delivery Mode: On-Site, Off-Site, Mobile, Automated |
| Companies Covered | 3M Company, Solventum Corporation, STERIS Corporation, Steelco S.p.A., Tuttnauer Ltd., Getinge AB, Cantel Medical, Shinva Medical Instrument Co., Ltd., Advanced Sterilization Products (Fortive), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Temperature Sterilization Market Strategic Shifts
Low-temperature sterilization is converging with digital workflow integration and materials science advances that compress cycle times while expanding instrument compatibility. These developments are redrawing competitive boundaries between equipment vendors and service providers.
Next-generation vaporized hydrogen peroxide systems are unifying sterilization chambers with automated load tracking and real-time biological indicator monitoring. Large hospital networks in Germany and the United States are deploying these integrated platforms to eliminate manual documentation steps. The technology is unifying hardware, consumables, and compliance data into single-vendor contracts that lock out commodity competitors.
REACH authorization requirements for ethylene oxide are forcing European operators toward closed-loop abatement systems or modality substitution. The industrial consequence is accelerated depreciation of open-ventilation EtO chambers and premium pricing for hydrogen peroxide capacity. Central and Eastern European hospital networks are responding fastest due to older installed bases and limited legacy abatement investments.
Buying committees are consolidating sterilization procurement under centralized supply chain functions rather than decentralized clinical engineering departments. United States health systems with 10-plus hospitals are displacing site-by-site capital purchases with enterprise-wide equipment leases bundled with preventive maintenance. This shift is most visible in California and Texas, where large networks are standardizing on single-platform vaporized hydrogen peroxide fleets to simplify training and spare parts inventory.
Low-Temperature Sterilization Market Segmentation
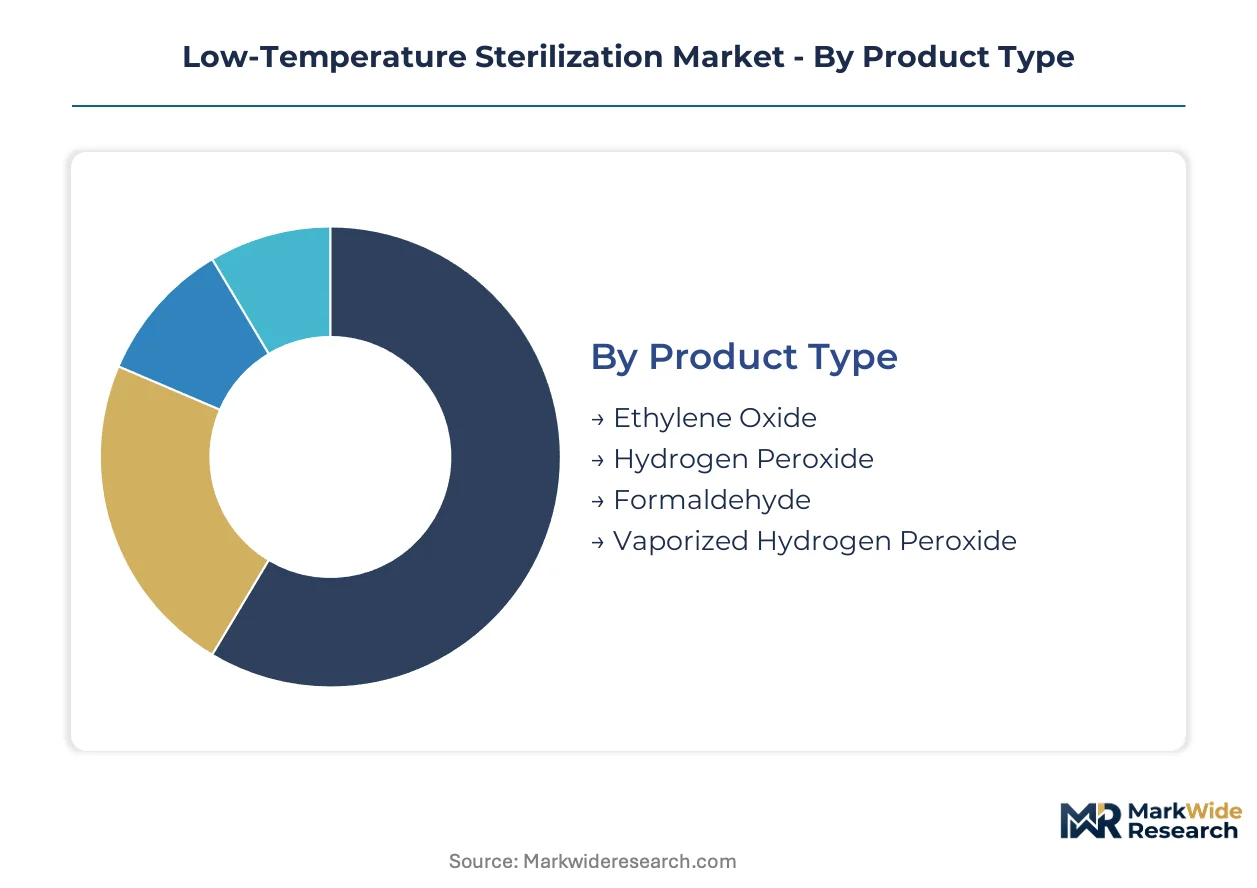
Low-temperature sterilization purchasing splits across modality chemistry, facility scale, instrument type, and service architecture. These divisions determine capital intensity, regulatory exposure, and vendor selection criteria for healthcare procurement teams.
Product Type:
Technology specifications define penetration depth, cycle duration, and compatibility with polymer-electronic instrument hybrids.
- Vaporized Hydrogen Peroxide:Converts liquid hydrogen peroxide into vapor phase for lumen penetration at 45-50 degrees Celsius. United States hospital networks are standardizing on this modality as EPA ethylene oxide enforcement tightens and robotic surgery instruments proliferate.
- Hydrogen Peroxide:Plasma-phase systems using radio frequency energy to ionize hydrogen peroxide gas. European surgical centers favor these units for shorter aeration requirements and REACH compliance advantages over ethylene oxide.
- Ethylene Oxide:Alkylating gas with established penetration for long-lumen endoscopes, now requiring catalytic abatement investments that strain mid-tier facility budgets.
- Formaldehyde:Low-temperature steam formaldehyde systems retain niche presence in Central European laboratory sterilization where instrument compatibility databases are mature.
Mature deployment sits with ethylene oxide. Newer deployment is concentrated in vaporized hydrogen peroxide.
End User:
Facility scale determines throughput requirements, capital availability, and regulatory sophistication in sterilization protocol validation.
- Hospitals:Multi-department surgical networks processing 50-plus loads daily require validated hydrogen peroxide fleets with RFID traceability integration.
- Clinics:Ambulatory surgical centers in Texas and Florida are displacing ethylene oxide with compact vaporized hydrogen peroxide units to avoid abatement capital.
- Laboratories:Research facilities with cell culture contamination sensitivity specify formaldehyde-compatible protocols for biological safety cabinet sterilization cycles.
- Dental Offices:Implantology practices with lower throughput favor tabletop hydrogen peroxide systems for handpiece and surgical instrument reprocessing.
Capital concentration clusters in hospitals. Volume expansion is accelerating fastest in clinics.
Application:
Instrument material composition and lumen geometry dictate sterilization modality selection and cycle parameter validation.
- Surgical Instruments:Robotic surgery toolsets with polymer coatings and electronic articulation require hydrogen peroxide protocols below 60 degrees Celsius to prevent sensor drift.
- Medical Devices:Implantable cardiovascular and orthopedic devices demand validated sterility assurance levels with biological indicator documentation for FDA submission.
- Laboratory Equipment:Cell culture incubators and biosafety cabinets specify formaldehyde or hydrogen peroxide cycles compatible with HEPA filter integrity.
- Pharmaceutical Products:Aseptic processing equipment and packaging components use vaporized hydrogen peroxide for terminal sterilization of heat-sensitive biologics.
Complexity premiums attach to surgical instruments. Standardized protocols dominate laboratory equipment.
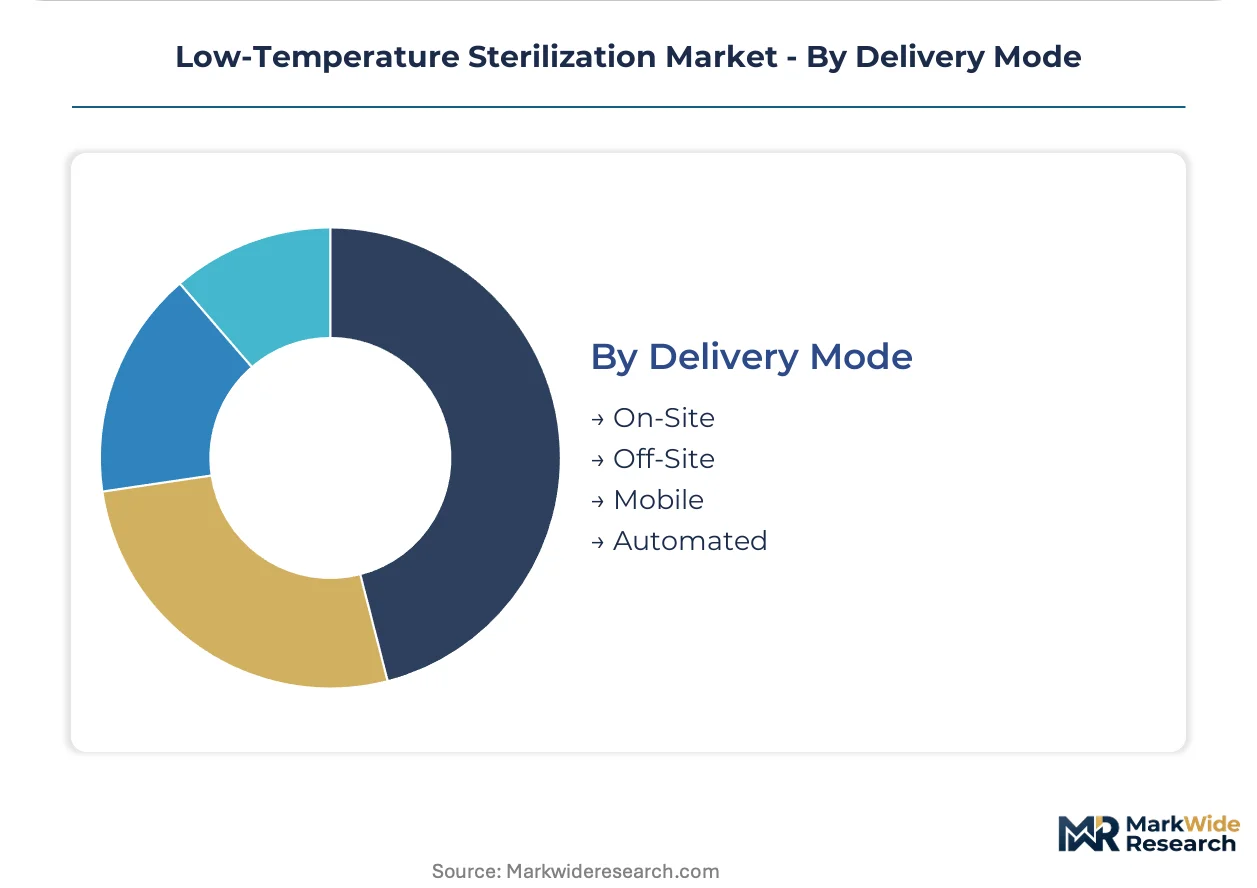
Delivery Mode:
Service architecture choices reflect capital constraints, throughput variability, and compliance delegation preferences.
- On-Site:Hospital-owned sterilization departments with dedicated staff and preventive maintenance contracts retain control over cycle validation and instrument turnaround.
- Off-Site:Third-party reprocessing centers in Germany and the United States consolidate ethylene oxide capacity for regional hospital networks facing individual facility abatement costs.
- Mobile:Trailer-mounted vaporized hydrogen peroxide units serve temporary surgical facilities and disaster response deployments with rapid setup protocols.
- Automated:Robotic loading systems with hospital information system integration are penetrating large United States health systems seeking labor cost reduction and traceability compliance.
Ownership models favor on-site installation. Outsourcing is expanding most quickly in off-site consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cleveland anchors North American low-temperature sterilization deployment through its dense cluster of hospital systems and medical device reprocessing centers. Surgical volume concentration in this Midwest corridor drives capital allocation toward vaporized hydrogen peroxide systems. The city's health network consolidation creates procurement scale that smaller metros cannot replicate.
United States
Ambulatory surgical centers in Texas and Florida are displacing aging ethylene oxide infrastructure with compact hydrogen peroxide units to avoid seven-figure abatement investments. The EPA's tightened ambient air standards for ethylene oxide emissions are accelerating facility closures across Sun Belt states. Hospital networks in California are standardizing on single-platform vaporized hydrogen peroxide fleets to simplify training and spare parts inventory across 10-plus hospital systems.
Germany
Large hospital networks in Bavaria and North Rhine-Westphalia deploy integrated sterilization platforms with automated load tracking and real-time biological indicator monitoring. The EU Medical Device Regulation's reprocessing documentation requirements are opening adjacent revenue streams for sterilization-as-a-service providers. Central and Eastern European hospital networks source validated protocol packages from German sterilization consultancies to meet MDR conformity burdens.
India
Private hospital networks in Mumbai and Delhi are expanding low-temperature capacity as surgical volume concentrates in tier-1 cities. The country's Production Linked Incentive scheme for medical devices creates whitespace for sterilizer deployment in newly constructed super-specialty facilities. Regional medical centers in Gujarat and Karnataka face equipment financing constraints that favor Tuttnauer's capital-cost positioning over premium integrated systems.
Japan
Metropolitan Tokyo hospitals specify hydrogen peroxide protocols for robotic surgery instruments with polymer coatings and electronic articulation. The Pharmaceuticals and Medical Devices Agency enforces stringent reprocessing validation requirements that extend sterilizer qualification timelines. Osaka-based surgical centers favor plasma-phase systems for shorter aeration requirements in high-throughput departments.
China
Shinva Medical Instrument anchors domestic supply through its installed base in provincial hospital networks across the Yangtze River Delta. The National Medical Products Administration is harmonizing reprocessing standards with international ISO frameworks for export-oriented device manufacturers. Shenzhen's private hospital construction boom is absorbing tabletop hydrogen peroxide systems for ophthalmology and dental implantology practices.
Low-Temperature Sterilization Market Competitive Environment
Premium-margin players sit above commodity-margin players across service integration depth and instrument compatibility certification breadth. The market structures around three tiers: integrated equipment-consumables-service providers, standalone capital equipment vendors, and regional maintenance contractors. Strategic archetypes include the full-stack hospital partner, the cost-optimized mid-tier supplier, and the regulatory compliance specialist. Dominant competitive moves center on enterprise-wide fleet standardization contracts and adjacent validation service bundling.
Within the integrated-system tier, STERIS Corporation and Getinge AB occupy positions defined by surgical workflow integration and premium pricing sustainment across hospital networks. Tuttnauer Ltd. exemplifies the capital-cost-optimized archetype, anchoring mid-tier clinic and regional medical center penetration. Solventum Corporation and 3M Company represent the consumables and compatibility certification vector, with 3M's historical presence in healthcare supply chains reinforcing its sterilization assurance positioning. These three groupings—integrated workflow, cost-optimized equipment, and consumables-science—capture the competitive geometry without exhaustive player enumeration.
| Leading Market Players |
|---|
| 3M Company |
| Solventum Corporation |
| STERIS Corporation |
| Steelco S.p.A. |
| Tuttnauer Ltd. |
| Getinge AB |
| Cantel Medical |
| Shinva Medical Instrument Co., Ltd. |
| Advanced Sterilization Products (Fortive) |
| Others |
Value Chain & Pricing Dynamics
Backward integration into platinum-group catalyst supply anchors pricing power for vaporized hydrogen peroxide sterilizer manufacturers, while outsourced consumables production compresses margins for mid-tier equipment vendors competing on capital cost alone. This structural split between captive catalyst sourcing and third-party chemical procurement determines which players can sustain service-contract profitability when precious metal volatility spikes.
Pricing Analysis
Uptime-guarantee contracts anchor value-based pricing for integrated sterilization platforms, with three-tier pricing structure across premium, standard, and economy levels separating STERIS and Getinge from Tuttnauer and regional competitors. Price differentiation hinges on FDA validation depth and RFID traceability bundling. Cost compression in economy-tier tabletop units intensifies because Chinese manufacturers are flooding dental and ophthalmology segments. Ambulatory surgical centers exhibit highest price sensitivity; large hospital networks with GPO contracts show lowest.
Supply Chain Analysis
Single-source vulnerability sits with South African and Russian platinum-group metal suppliers, exposing hydrogen peroxide sterilizer catalyst production to geopolitical disruption. Manufacturing concentrates in the United States, Germany, and China, with consumables sourcing drawing from Mexican chemical processors and Indian sterilization packaging producers. Tariff exposure on platinum catalysts threatens service contract margins. Distribution runs through hospital GPOs and specialized medical device distributors rather than direct sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EPA ethylene oxide emission limits and FDA reprocessing validation requirements erect barrier-to-entry moats that protect incumbent integrated-system providers from commodity competition.
For Market Incumbents: Lock in enterprise-wide fleet standardization contracts with 10-plus hospital systems before REACH authorization deadlines force European modality switches. Consolidate position by acquiring sterilization-as-a-service providers in Germany and California, where EU MDR documentation burdens and California air quality enforcement accelerate outsourcing demand. Threat of stranded EtO infrastructure in mid-tier facilities creates acquisition targets at distressed valuations. For New Entrants and Emerging Players: Enter via India's PLI scheme for medical devices, where private hospital construction in Mumbai and Delhi outpaces sterilization capacity deployment. White-space concentrates in tier-2 city regional medical centers facing Tuttnauer financing gaps but requiring validated hydrogen peroxide protocols for polymer-coated instruments. Go-to-market angle: consumables-light service contracts that transfer validation liability from hospital biomedical engineers. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by surgical workflow integrators seeking sterilization data streams for predictive analytics platforms. Long-term viability favors players with FDA master file submissions and EU MDR technical documentation libraries already compiled. Signal to watch: EPA enforcement action against remaining EtO facilities in Texas and Florida, which would accelerate replacement capex timelines and compress valuation multiples for unprepared targets.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Unlocks hospital procurement eligibility for novel hydrogen peroxide cycle parameters. |
| EU MDR Technical Documentation | Enables sterilization-as-a-service revenue in German and Central European networks. |
| Hospital System Partnership | Locks out competitors through enterprise-wide vaporized hydrogen peroxide fleet standardization. |
| Platinum Catalyst Supply Agreement | Hedges service contract margins against South African supply disruption. |
| RFID Traceability Integration | Captures predictive maintenance pricing premium from California health systems. |
Study Parameters
FDA 510(k) databases, EPA enforcement action records, and EU MDR notified body technical documentation formed the secondary backbone, cross-referenced with primary interviews involving hospital sterilization department managers, biomedical validation engineers, GPO contracts directors, and sterilizer field service technicians. Bottom-up and top-down triangulation reconciled installed base counts from manufacturer service records against hospital procurement database expenditure patterns.
Bottom-up modeling anchored forecasts, with top-down cross-checks against healthcare capital expenditure surveys and surgical volume projections. Segmentation dimensions spanned sterilization modality chemistry, facility scale tier, instrument application type, and service delivery architecture. CAGRs derived from instrument replacement cycle analysis and regulatory-driven modality substitution curves, with platinum price volatility and EPA enforcement intensity as scenario variables across the analysis window.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden EPA EtO facility shutdown orders or platinum supply disruption. Forecasts reflect documented assumptions on instrument polymer coating adoption rates and REACH authorization timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
Alcohol Based Disinfectants Market
Disinfectants and Preservatives
Bleach Gel Market
Disinfectants and Preservatives
Sterilants Market
Disinfectants and Preservatives
North America Hydrogen Peroxide Market
Disinfectants and Preservatives
Clean Label Preservatives Market
Disinfectants and Preservatives
Continuously Sterilized Product Market
Disinfectants and Preservatives
Disinfectants Market
Disinfectants and Preservatives
Deltamethrin Market
Disinfectants and Preservatives
North America Disinfectants and Cleaning Agents Market
Disinfectants and Preservatives
Sulfuryl Fluoride Market
Disinfectants and Preservatives
Antimicrobial Chemicals Market
Disinfectants and Preservatives
Preservatives Market
Disinfectants and Preservatives
Hydrogen Peroxide Market
Disinfectants and Preservatives
Europe Disinfectant Wipes Market
Disinfectants and Preservatives
Bactericides Market
Disinfectants and Preservatives
Disinfectant and Cleaning Agents Market