
 UVC Disinfection Products Market | 2026-2036
UVC Disinfection Products Market Size, Share, and Industry Trends Forecast 2026-2036
UVC Disinfection Products Market Outlook
Aftermarket service revenue for lamp replacement and calibration is tilting toward OEM-controlled programs and away from third-party maintenance. Trojan Technologies leverages its installed base of municipal water systems to sustain recurring filter and lamp revenue. Danaher Corporation anchors its position through vertical integration into mercury vapor lamp manufacturing. Atlantic Ultraviolet Corporation competes on specialized laboratory sterilization units where technical specification compliance dominates procurement decisions.
UVC disinfection products are ultraviolet-C emitting devices operating at wavelengths between 200 and 280 nanometers, typically employing low-pressure mercury vapor lamps or solid-state LEDs to denature microbial DNA and render pathogens non-viable. Fixed installations command the largest revenue pool in commercial and infrastructure settings where continuous air and water treatment justifies capital expenditure. Portable units represent the fastest-expanding category as educational institutions and hospitality operators seek flexible deployment without permanent building modifications. LEDs are displacing mercury vapor in applications where RoHS compliance and instant on-off cycling provide operational advantages.
The EPA regulates pesticidal device claims for UVC surface disinfectants in the United States, while the EU F-Gas Regulation constrains mercury-based lamp production across European member states. FDA enforcement of medical device sterilization standards shapes product validation requirements for healthcare-facing manufacturers. Stakeholders must monitor regulatory divergence between jurisdictions as mercury phase-out timelines and LED performance standards reshape competitive positioning and sourcing strategies.
Market Dynamics
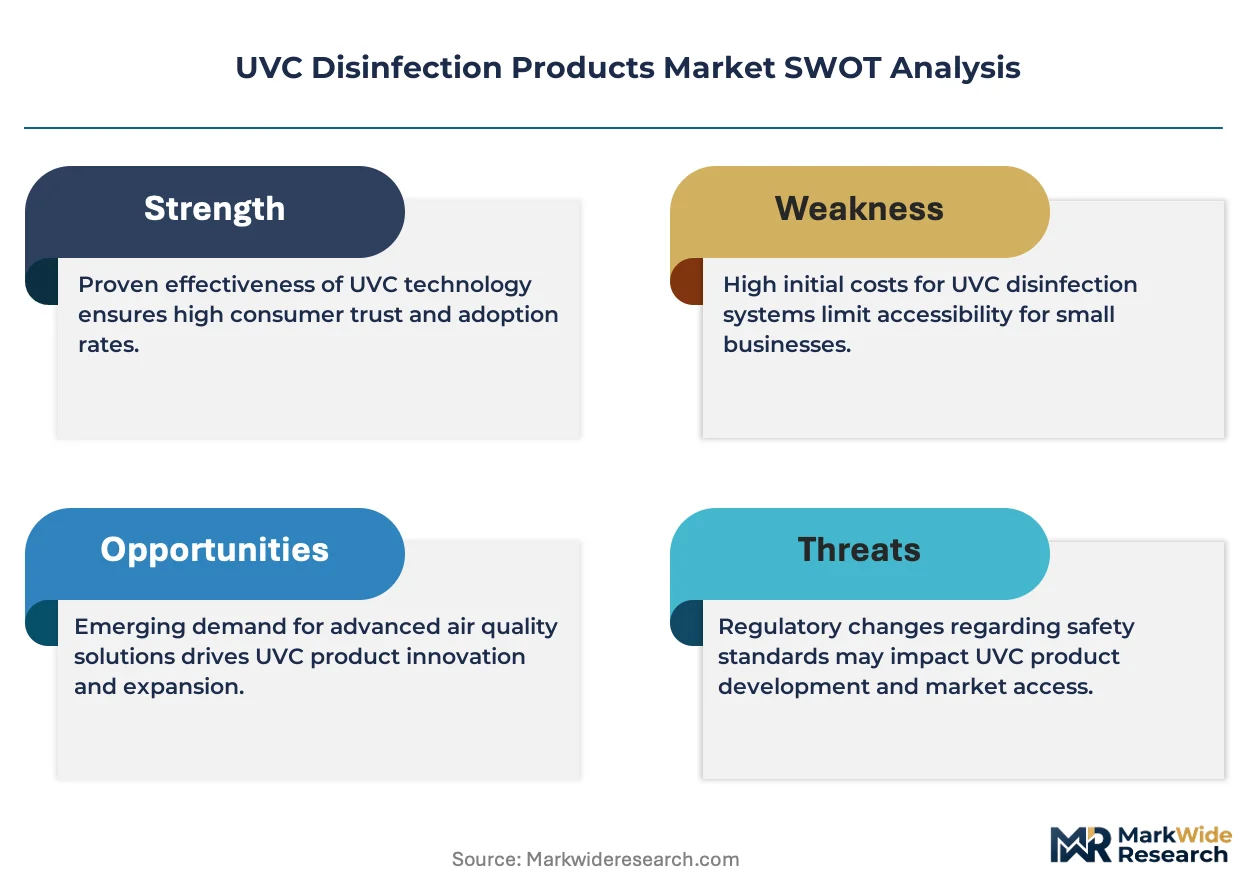
The UVC Disinfection Products Market pivots on mercury lamp phase-out mandates colliding with LED performance maturation, forcing manufacturers to recalibrate supply chains and certification roadmaps simultaneously.
Growth Catalysts
- EU F-Gas Regulation:Mercury vapor lamp production constraints accelerate LED substitution in German pharmaceutical cleanrooms and Dutch water treatment facilities.
- Hospital-acquired infection protocols:US healthcare networks expand fixed UVC installations in operating theaters to meet Joint Commission accreditation standards.
- Far-UVC wavelength research:Columbia University and academic medical centers validate 222-nanometer efficacy for occupied-space disinfection, opening new deployment scenarios.
Market Restraints
- Mercury supply concentration:Primary mercury refining concentrates in Kyrgyzstan and China, exposing lamp manufacturers to geopolitical supply interruptions.
- LED output limitations:Current solid-state UVC diodes deliver 3-5% wall-plug efficiency versus 35-40% for optimized mercury vapor, constraining high-throughput water applications.
- EPA pesticidal device registration:Surface disinfection claims require 18-24 month validation cycles, delaying product commercialization for US market entry.
Strategic Opportunities
- Indian healthcare infrastructure:Government hospital modernization under Ayushman Bharat creates first-time demand for affordable portable units in tier-2 and tier-3 cities.
- Food processing integration:Conveyor-integrated UVC systems for produce wash lines address FDA Food Safety Modernization Act preventive controls requirements.
- HVAC retrofit channels:Coil-irradiation and in-duct systems penetrate commercial real estate through MEP contractor networks rather than traditional disinfection distributors.
Industry Challenges
- Photometric calibration expertise:Qualified technicians for irradiance mapping and dosimetry validation remain scarce relative to installed base expansion.
- Legacy system interoperability:Building management system integration requires protocol translation between proprietary UVC controllers and BACnet or Modbus networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UVC Disinfection Products Market |
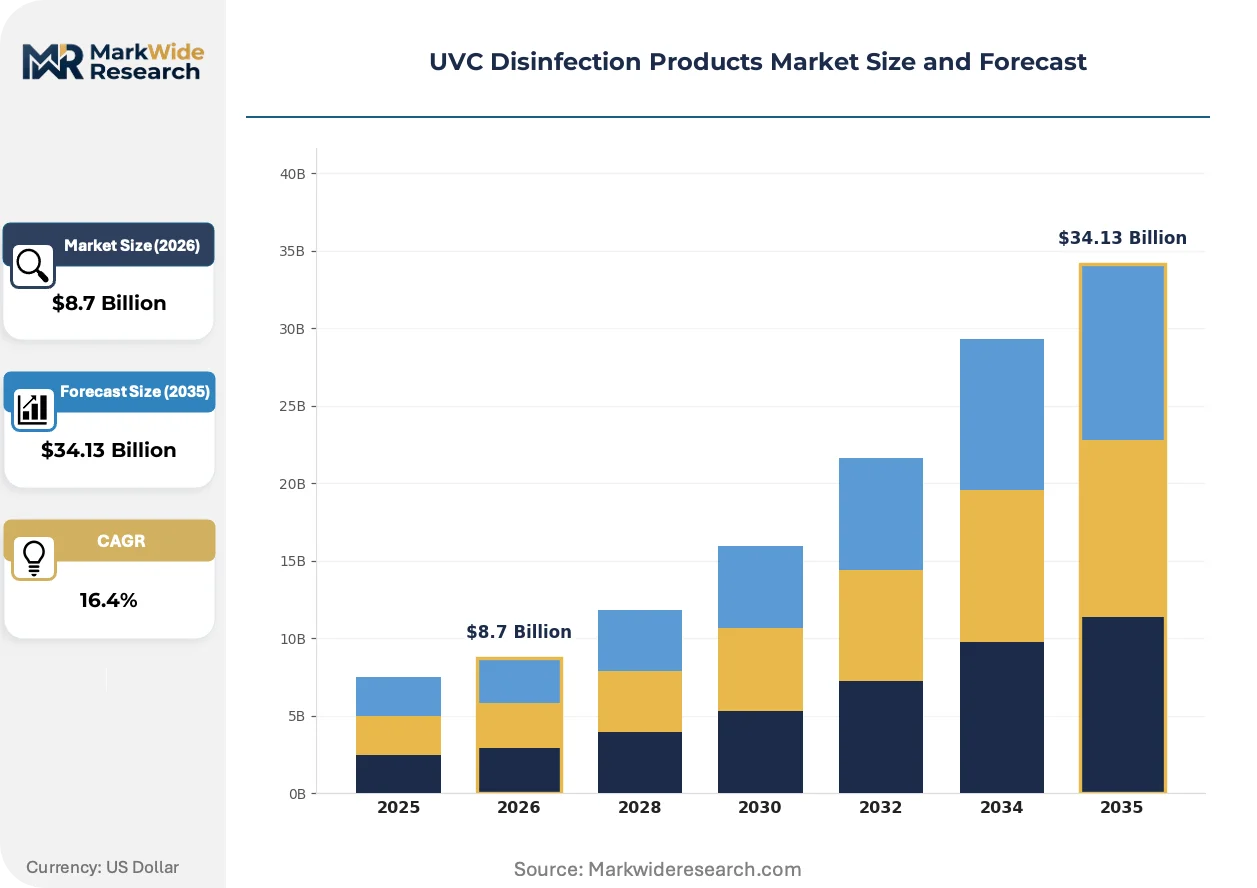
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Devices, Fixed Installations, Portable Units, Air Purifiers End User: Healthcare Facilities, Educational Institutions, Hospitality Sector, Residential Users Application: Surface Disinfection, Water Treatment, Air Sanitization, Laboratory Sterilization Technology: Mercury Vapor, Low-Pressure UV, Medium-Pressure UV, LEDs |
| Companies Covered | Xylem Inc., Halma Group, Trojan Technologies, Danaher Corporation, Evoqua Water Technologies LLC, Atlantic Ultraviolet Corporation, Koninklijke Philips N.V., Industrie De Nora S.p.A., Hoenle AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UVC Disinfection Products Market Strategic Shifts
Mercury-dependent architectures face obsolescence pressure while solid-state alternatives command premium positioning, reshaping R&D allocation and manufacturing footprints across the supply base.
Mercury vapor lamp technology dominates high-output water and air treatment applications through decades of reliability data and established ballast ecosystems. Municipal utilities and pharmaceutical manufacturers continue specifying medium-pressure systems for validated processes. LED UVC is migrating from niche portable applications into fixed infrastructure as irradiance output per dollar improves and RoHS compliance deadlines approach.
The EU F-Gas Regulation constrains mercury-containing lamp production across member states with accelerating phase-out timelines. This forces European OEMs to redesign product portfolios around solid-state sources or source mercury lamps from non-EU suppliers. Healthcare and laboratory segments in Germany, France, and the Netherlands face compressed procurement timelines as existing mercury-based inventory depletes.
Service contract structures are unbundling from equipment sales as buyers demand performance-guaranteed outcomes rather than capital asset ownership. Third-party facility management firms and infection control consultants are capturing specification influence previously held by equipment distributors. This shift concentrates in US hospital systems and UK NHS trusts where operational expenditure budgets displace capital approval cycles.
UVC Disinfection Products Market Segmentation
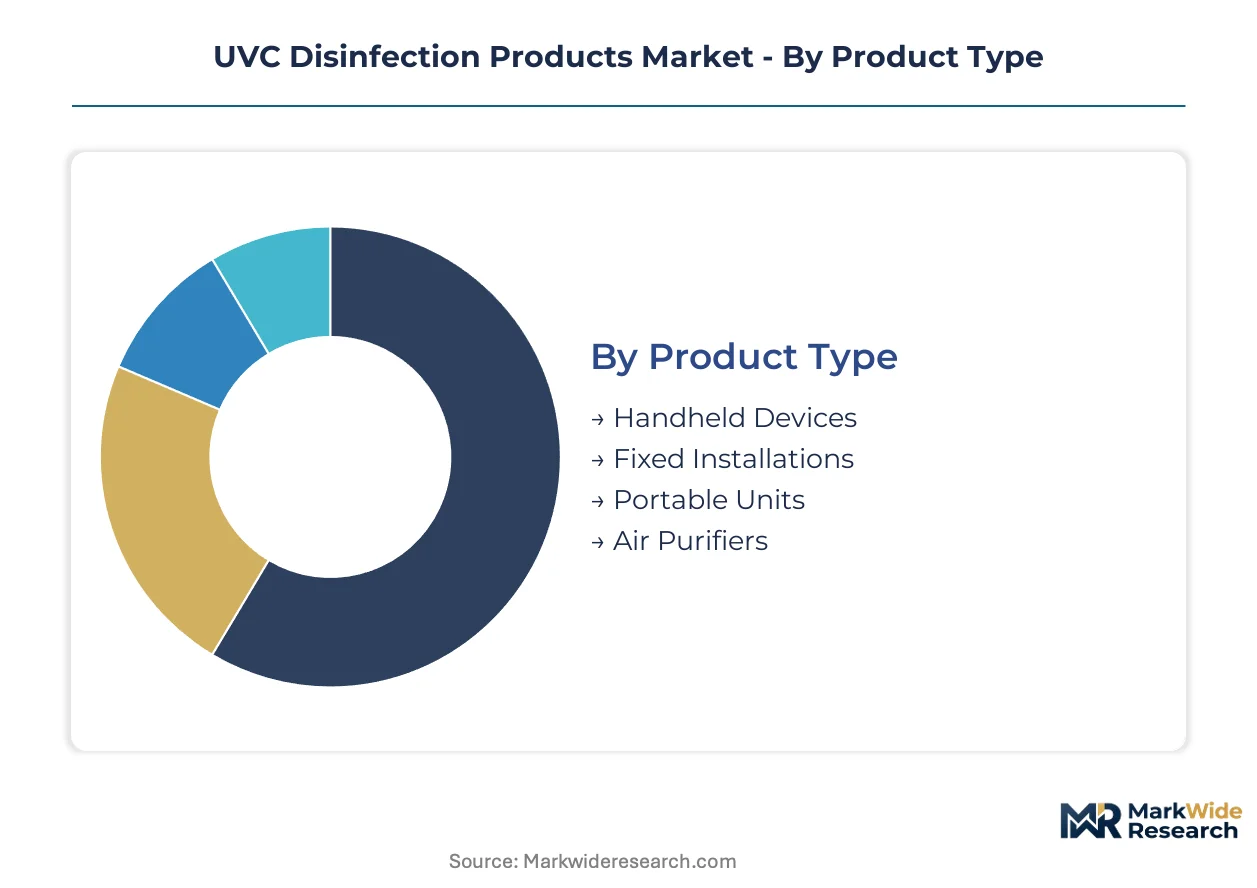
Segmentation in the UVC disinfection market reveals divergent replacement cycles and capital intensity across product architectures. Procurement patterns split between infrastructure-heavy fixed systems with decade-long depreciation schedules and portable units subject to faster obsolescence from LED performance gains.
Product Type:
Replacement cycles stretch from 3-5 years for portable electronics to 10-15 years for fixed infrastructure, creating distinct aftermarket revenue profiles and customer lock-in dynamics.
- Fixed Installations:Permanently mounted systems integrated into HVAC ductwork, water treatment infrastructure, or ceiling arrays for continuous air sanitization. US hospital networks concentrate procurement here as Joint Commission accreditation drives capital allocation toward validated whole-room disinfection in operating theaters and isolation rooms.
- Portable Units:Mobile devices on casters or carts enabling repositioning across wards, classrooms, or hotel floors without electrical retrofit. Educational institutions and hospitality operators in Germany and the Netherlands favor this flexibility where building ownership or lease structures resist permanent modifications.
- Handheld Devices:Wand-style or pistol-grip units for targeted surface treatment of medical equipment, workstations, or food preparation areas.
- Air Purifiers:Standalone consumer and commercial units with integrated UVC chambers for room-scale air circulation.
Fixed Installations dominate installed base. Portable Units is where expansion concentrates.
End User:
Customer archetypes span from regulated healthcare procurement with mandatory FDA validation to price-sensitive residential buyers influenced by retail channel positioning.
- Healthcare Facilities:Hospitals, outpatient clinics, and long-term care centers subject to infection control protocols and medical device sterilization standards. US healthcare networks anchor demand for fixed UVC systems as Medicare reimbursement ties to hospital-acquired infection rates tighten.
- Hospitality Sector:Hotels, restaurants, and event venues seeking visible hygiene differentiation for guest confidence. German hotel chains deploy medium-pressure UV systems for water treatment in spa and pool facilities where Legionella prevention carries liability exposure.
- Educational Institutions:K-12 schools and universities balancing budget constraints with occupancy density concerns.
- Residential Users:Individual consumers purchasing through retail channels for home air purification or surface disinfection.
Healthcare Facilities dominate installed base. Hospitality Sector is where expansion concentrates.
Application:
Technical specifications diverge sharply between water treatment requiring high-dose mercury vapor systems and surface disinfection where lower-output LEDs suffice.
- Water Treatment:High-throughput systems for municipal utilities, pharmaceutical manufacturing, and food processing requiring validated microbial inactivation. Dutch water treatment facilities specify medium-pressure UV for drinking water disinfection under EU Drinking Water Directive compliance.
- Air Sanitization:In-duct, upper-room, and whole-room systems for continuous or episodic airborne pathogen reduction. US commercial real estate operators retrofit HVAC systems with coil-irradiation UVC as energy efficiency and indoor air quality converge in building upgrade decisions.
- Surface Disinfection:Direct irradiation of medical equipment, workstations, and high-touch environmental surfaces.
- Laboratory Sterilization:Validated processes for research facilities and pharmaceutical cleanrooms requiring documented dosimetry.
Water Treatment dominates installed base. Air Sanitization is where expansion concentrates.
Technology:
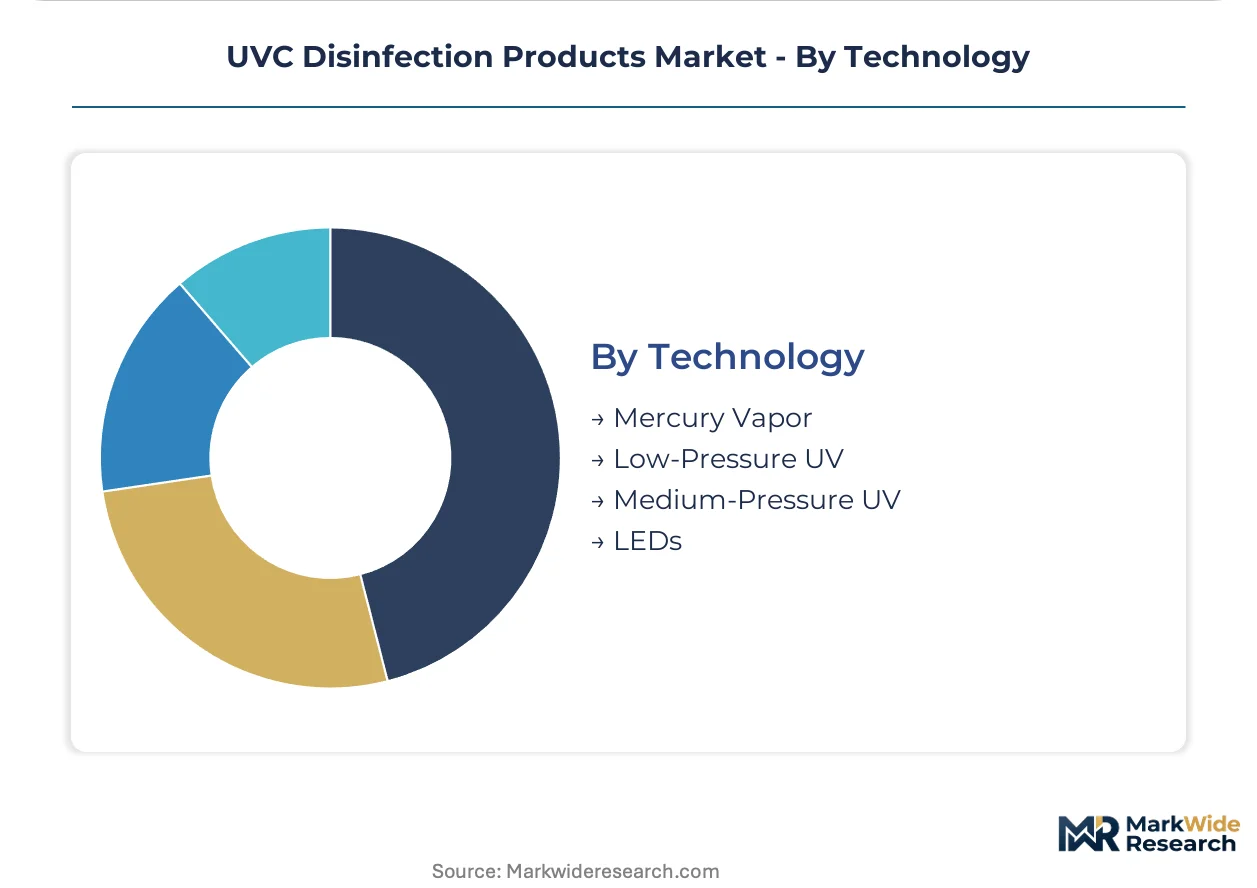
Mercury vapor architectures face regulatory phase-out pressure while LED performance maturation determines substitution economics across power classes.
- Mercury Vapor:Traditional low-pressure and medium-pressure lamp systems delivering high irradiance output with established reliability data. Pharmaceutical manufacturers in Germany continue specifying these for validated water treatment processes where regulatory submission history reduces approval risk.
- LEDs:Solid-state UVC emitters offering instant on-off cycling, RoHS compliance, and mercury elimination. Portable unit manufacturers favor LEDs as EU F-Gas Regulation deadlines approach and supply chain liability from mercury handling intensifies.
- Low-Pressure UV:Mercury-based monochromatic emitters at 254 nanometers for standard disinfection applications.
- Medium-Pressure UV:Polychromatic mercury systems with broader wavelength output for advanced oxidation and chlorine-resistant pathogens.
Mercury Vapor dominates installed base. LEDs is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. German pharmaceutical buyers absorb premium pricing for validated mercury systems, while Indian hospital procurement under Ayushman Bharat prioritizes affordable portable units. US healthcare networks fall between these poles, trading capital intensity for Joint Commission compliance.
United States
Hospital-acquired infection protocols and Medicare reimbursement penalties drive fixed UVC installations in operating theaters. FDA enforcement of medical device sterilization standards elevates certification costs for manufacturers seeking healthcare market entry. The Boston-Cambridge corridor concentrates far-UVC research at Columbia University and affiliated medical centers validating 222-nanometer occupied-space applications.
Germany
Hospital networks and pharmaceutical manufacturers deploy medium-pressure UV systems for water treatment and air sanitization in cleanroom environments. The EU F-Gas Regulation constrains mercury-based lamp production, compressing procurement timelines as existing inventory depletes. The Rhine-Ruhr industrial cluster anchors demand for validated processes where regulatory submission history reduces pharmaceutical approval risk.
Netherlands
Drinking water utilities specify medium-pressure UV disinfection under EU Drinking Water Directive compliance obligations. Dutch facilities prioritize mercury vapor reliability for high-throughput municipal applications despite LED substitution pressure elsewhere. The Randstad metropolitan region concentrates water technology engineering expertise and system integration capabilities.
India
Government hospital modernization under Ayushman Bharat creates first-time demand for affordable portable units in tier-2 and tier-3 cities. BIS certification requirements and CDSCO medical device regulations shape import substitution strategies for domestic manufacturers. The Maharashtra-Gujarat pharmaceutical corridor generates parallel demand for laboratory sterilization equipment as contract manufacturing expands.
China
Domestic LED UVC manufacturing scales rapidly as mercury lamp exports face RoHS compliance barriers in European markets. NMPA medical device registration and GB standards compliance determine market access for healthcare-facing products. The Yangtze River Delta concentrates solid-state emitter fabrication and downstream system assembly for both domestic consumption and export.
UVC Disinfection Products Market Competitive Environment
Water technology conglomerates and specialized disinfection equipment fabricators split the market into distinct capability tiers. The vendor base concentrates around municipal infrastructure incumbents with decades of reliability data and emerging solid-state specialists chasing LED substitution economics. Two strategic archetypes dominate: integrated water treatment platforms leveraging installed base service contracts, and component-focused specialists competing on technical specification compliance. Competitive moves center on backward integration into lamp manufacturing and geographic expansion through MEP contractor channels rather than traditional distribution.
Among water technology conglomerates, Xylem Inc. and Danaher Corporation exemplify the integrated-platform archetype through captive supply chain control and recurring aftermarket revenue structures. Trojan Technologies anchors the municipal infrastructure tier with sustained filter and lamp replacement programs. Halma Group and Atlantic Ultraviolet Corporation occupy positions within specialized laboratory and industrial sterilization segments where technical compliance dominates procurement decisions. Evoqua Water Technologies LLC, Industrie De Nora S.p.A., and Hoenle AG represent regional specialists with concentrated European manufacturing footprints.
| Leading Market Players |
|---|
| Xylem Inc. |
| Halma Group |
| Trojan Technologies |
| Danaher Corporation |
| Evoqua Water Technologies LLC |
| Atlantic Ultraviolet Corporation |
| Koninklijke Philips N.V. |
| Industrie De Nora S.p.A. |
| Hoenle AG |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Rotterdam maritime corridor absorbs freight volatility that compresses margins on mercury vapor lamp imports while amplifying price premiums for RoHS-compliant LED systems. German pharmaceutical buyers absorb elevated landed costs for validated medium-pressure UV equipment, whereas Indian hospital procurement under Ayushman Bharat constrains budgets to domestically assembled portable units. This freight-cost asymmetry reinforces tiered pricing across certification-grade boundaries.
Pricing Analysis
Aftermarket service contracts for lamp replacement and calibration sustain lifetime value beyond initial equipment sales. Pricing stratifies across FDA-validated healthcare systems, CE-marked industrial installations, and uncertified consumer devices. Cost compression in portable LED segments intensifies as Chinese solid-state manufacturing scales. Educational institutions exhibit highest price sensitivity; pharmaceutical cleanrooms show lowest.
Supply Chain Analysis
Mercury feedstock refining concentrates in Kyrgyzstan and China, exposing lamp manufacturers to geopolitical interruption. UVC system production draws from quartz glass fabrication in Germany, electronic ballast assembly in China, and LED chip fabrication in the Yangtze River Delta. Single-source vulnerability concentrates in mercury supply. Distribution runs through MEP contractor networks for fixed infrastructure and medical device distributors for healthcare applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UVC disinfection market tracks cyclical recovery patterns tied to hospital capital expenditure cycles. Medicare reimbursement penalties for hospital-acquired infections compress procurement timelines during accreditation renewal periods.
For Market Incumbents: Insulate recurring revenue streams by captive supply of replacement lamps and proprietary calibration protocols. Trojan Technologies demonstrates this through municipal service contracts that lock utilities into decade-long maintenance programs. Backward integration into mercury vapor lamp manufacturing defends margin position against LED substitution pressure from Chinese competitors. For New Entrants and Emerging Players: Pursue white-space opportunity in tier-2 and tier-3 Indian cities where Ayushman Bharat infrastructure investment outpaces established supplier presence. Food processing integration for FDA Food Safety Modernization Act compliance offers penetrable entry point with shorter validation cycles than healthcare. Channel partnership with regional MEP contractors bypasses entrenched medical device distribution. For Investors and Strategic Acquirers: Carve-out targets emerge from water technology conglomerates divesting non-core disinfection units as LED transition accelerates. Five-to-ten-year viability hinges on solid-state patent portfolios and RoHS compliance certification. Signal to watch: EU F-Gas Regulation enforcement actions accelerating mercury lamp inventory depletion.| Strategic Initiative | Industry Significance |
|---|---|
| LED Manufacturing Scale-Up | Chinese solid-state fabrication capacity expansion undercuts mercury vapor cost structures for portable applications. |
| Hospital System Partnership | Joint Commission accreditation requirements lock US healthcare networks into validated service contract structures. |
| Regulatory Certification Investment | FDA medical device validation and EPA pesticidal device registration create defensible competitive moats. |
| Backward Integration into Lamp Production | Danaher Corporation's captive mercury vapor supply secures margin control amid raw material concentration. |
| HVAC Retrofit Channel Development | MEP contractor relationships penetrate commercial real estate through energy efficiency upgrade budgets. |
Study Parameters
Desk research of FDA 510(k) filings, EPA pesticidal device registrations, and EU ECHA substance restriction databases preceded structured interviews with hospital infection control officers, pharmaceutical manufacturing engineers, water utility procurement managers, and MEP contracting executives. Primary fieldwork across the United States, Germany, Netherlands, India, and China validated secondary estimates. Bottom-up unit economics and top-down sectoral allocation triangulated market sizing.
Assumptions held fixed include EU F-Gas Regulation phase-out timelines, FDA enforcement intensity for medical device sterilization, and LED wall-plug efficiency improvement curves. Variables included hospital capital expenditure cyclicality, mercury supply disruption scenarios, and far-UVC 222-nanometer regulatory approval pathways. Segmentation modeling spanned product architecture, end-user vertical, application type, and technology platform. CAGRs derived from installed base replacement cycles and first-time adoption penetration curves.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese LED manufacturers or accelerated EU mercury bans would shift outcomes. Cross-checking against hospital procurement database benchmarks and water utility capital improvement plans is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
Global Fusidic Acid Market
Disinfectants and Preservatives
Salon Disinfectants Market
Disinfectants and Preservatives
Sodium Dichloroisocyanurate Market
Disinfectants and Preservatives
Disinfectant & Antimicrobial Chemicals Market
Disinfectants and Preservatives
Clinical Grade Disinfectant Market
Disinfectants and Preservatives
Global Fumigation Products Market
Disinfectants and Preservatives
Europe Hydrogen Peroxide Market
Disinfectants and Preservatives
Chlorine Disinfectant Market
Disinfectants and Preservatives
Surface Disinfectants Market
Disinfectants and Preservatives
Chlorine Dioxide Market
Disinfectants and Preservatives
Pyrethroids Market
Disinfectants and Preservatives
Bactericides Market
Disinfectants and Preservatives
UK Hypochlorous Acid Market
Disinfectants and Preservatives
Antimicrobial Chemicals Market
Disinfectants and Preservatives
Air Treatment Products Market
Disinfectants and Preservatives
Microbial Control Chemical Market