
 Europe Wood Decorative Wall Panel Market | 2026-2036
Europe Wood Decorative Wall Panel Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Wood Decorative Wall Panel Market Insights
Poland's expanding particleboard and MDF substrate capacity is reconfiguring supply dynamics for downstream decorative panel producers across Central Europe. Egger Group leverages integrated resin and substrate operations to sustain margin control from raw fiber through finished veneer. Kronospan anchors its competitive position via high-volume engineered wood output serving retail and contractor channels. Swiss Krono Group differentiates through specialized surface-texturing lines that occupy the premium residential segment.
Europe wood decorative wall panels are interior surfacing elements manufactured from solid timber, reconstituted wood fibers, or thin veneer laminates, typically ranging from 8 to 25 millimeters in thickness and engineered for aesthetic cladding, acoustic dampening, or thermal insulation in built environments. Their primary commercial purpose is to deliver architecturally specified finishes while substituting for solid wood to reduce material cost and dimensional variability. Engineered wood and laminated panels lead volume due to cost efficiency and batch consistency, while veneered panels command concentrated margin pools in hospitality and luxury residential applications where natural grain authenticity drives specification. Natural wood retains niche dominance in heritage restoration and certified sustainable builds where FSC chain-of-custody documentation is mandatory.
The EU Green Deal and Construction Products Regulation shape demand by mandating environmental product declarations and limiting formaldehyde emissions in interior wood products. ECHA REACH restrictions on hazardous preservatives and flame retardants further filter which treatments and coatings gain market access across member states. EMAS and national building codes in France and Germany add layer-specific compliance burdens for acoustic and fire-rated installations. Stakeholders must monitor evolving carbon-accounting rules and bio-based content thresholds to determine which substrate technologies and finishing chemistries retain eligibility in public procurement frameworks.
Market Dynamics
The EU Green Deal's embodied-carbon thresholds are forcing substrate substitution decisions across Central European panel finishing operations, compressing margins for conventional MDF-dependent producers while advantaging cross-laminated timber-integrated supply chains.
Growth Catalysts
- Boutique Hospitality Specification:Acoustic-grade timber cladding is displacing synthetic alternatives in Scandinavian and Alpine corridor hotel renovations, driven by biophilic design mandates and guest experience premiums.
- EU Construction Products Regulation:Mandatory environmental product declarations for interior finishes are filtering non-compliant imports and consolidating demand toward domestic fabricators with verified chain-of-custody documentation.
- Cross-Laminated Timber Cluster Proximity:German and Polish CLT fabrication hubs supply adjacent panel finishing operations with reduced transport emissions, qualifying finished goods for public procurement frameworks with carbon-accounting requirements.
Market Restraints
- Resin Cost Volatility:Urea-formaldehyde and MDI pricing fluctuations in petrochemical feedstock markets compress margins for particleboard-dependent producers without captive chemical operations.
- Substrate Concentration Risk:Poland's expanding particleboard capacity creates single-geography dependency for Central European downstream panel producers, exposing supply chains to localized energy price shocks or labor disruptions.
- Formaldehyde Emission Limits:ECHA REACH restrictions on interior wood product chemistry disqualify legacy adhesive formulations, forcing capital-intensive retooling for smaller finishing operations.
Strategic Opportunities
- Eastern European Underpenetration:Romania and Bulgaria's hospitality construction pipelines lack established decorative panel supply relationships, creating first-mover positioning for acoustic-certified product lines.
- Digital Specification Platforms:Architect and interior designer procurement is migrating to BIM-integrated material libraries, enabling direct-to-specifier bypass of traditional distributor markups.
- Bio-Based Coating Convergence:Waterborne polyurethane and plant-derived oil finishes are hybridizing with conventional lacquer systems, opening premium positioning for chemistries meeting EMAS and French national building code bio-content thresholds.
Industry Challenges
- Fire-Rated Certification Timelines:Extended testing protocols for CE-marked acoustic and fire-rated installations delay product launches, compressing revenue recognition windows for project-tied orders.
- Surface-Texturing Capex Intensity:Specialized embossing and synchronized pore lines require seven-figure equipment investments, fragmenting competitive capability between volume and premium positioning.
- FSC Chain-of-Custody Integration:Multi-tier supplier audits for certified sustainable builds create administrative burden and documentation gaps that disqualify otherwise qualified bids in heritage restoration segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Wood Decorative Wall Panel Market |
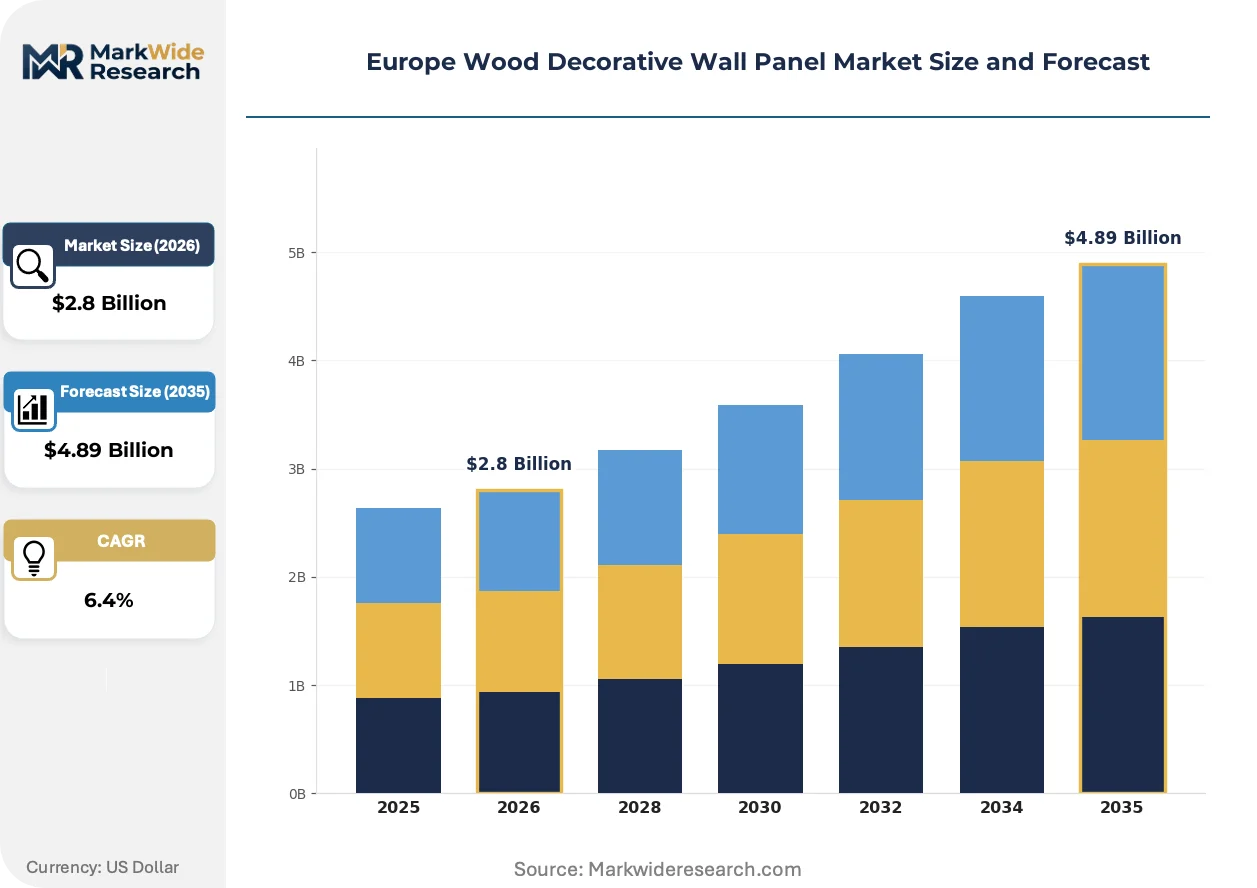
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Wood, Engineered Wood, Laminated Panels, Veneered Panels Application: Residential Interiors, Commercial Spaces, Retail Outlets, Hospitality Sector Installation Type: Wall-mounted, Ceiling-mounted, Modular, Custom Fit Distribution Channel: Online Retail, Offline Retail, Specialty Stores, Direct Sales |
| Companies Covered | Egger Group, Kronospan, Swiss Krono Group, Finsa, Sonae Arauco, Decospan, Danzer, Arauco, Pfleiderer Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Wood Decorative Wall Panel Market Trends and Innovations
Surface engineering and specification digitization are compressing traditional channel structures while regulatory chemistry restrictions reconfigure viable finishing operations across the continent.
Digital printing technology for wood-grain replication is hybridizing with thin-veneer substrates, enabling batch-size flexibility that solid-sawn lumber cannot match. Boutique hotel chains and luxury residential developers are specifying these hybrid surfaces for feature walls where natural grain variation is architecturally required but supply consistency is operationally critical. The technology is compressing lead times from specification to installation while expanding design-option breadth that conventional veneering operations cannot economically support.
Revised EU Construction Products Regulation documentation requirements are mandating digital environmental product declaration databases for all interior finishes placed on the single market. Manufacturers must now maintain third-party-verified lifecycle assessments accessible through centralized EU portals, filtering out smaller competitors lacking compliance infrastructure. German and French public procurement frameworks are the first to enforce automated EPD verification, with other member states adopting interoperable systems through 2027.
Architect and contractor material selection is migrating from physical sample libraries to virtual reality visualization platforms with embedded specification data. Hospitality and commercial office verticals are the earliest adopters, compressing the traditional distributor showroom role to logistics and credit functions. Scandinavian markets demonstrate the most advanced platform penetration, with specification decisions increasingly finalized before supplier contact occurs.
Europe Wood Decorative Wall Panel Market Segmentation
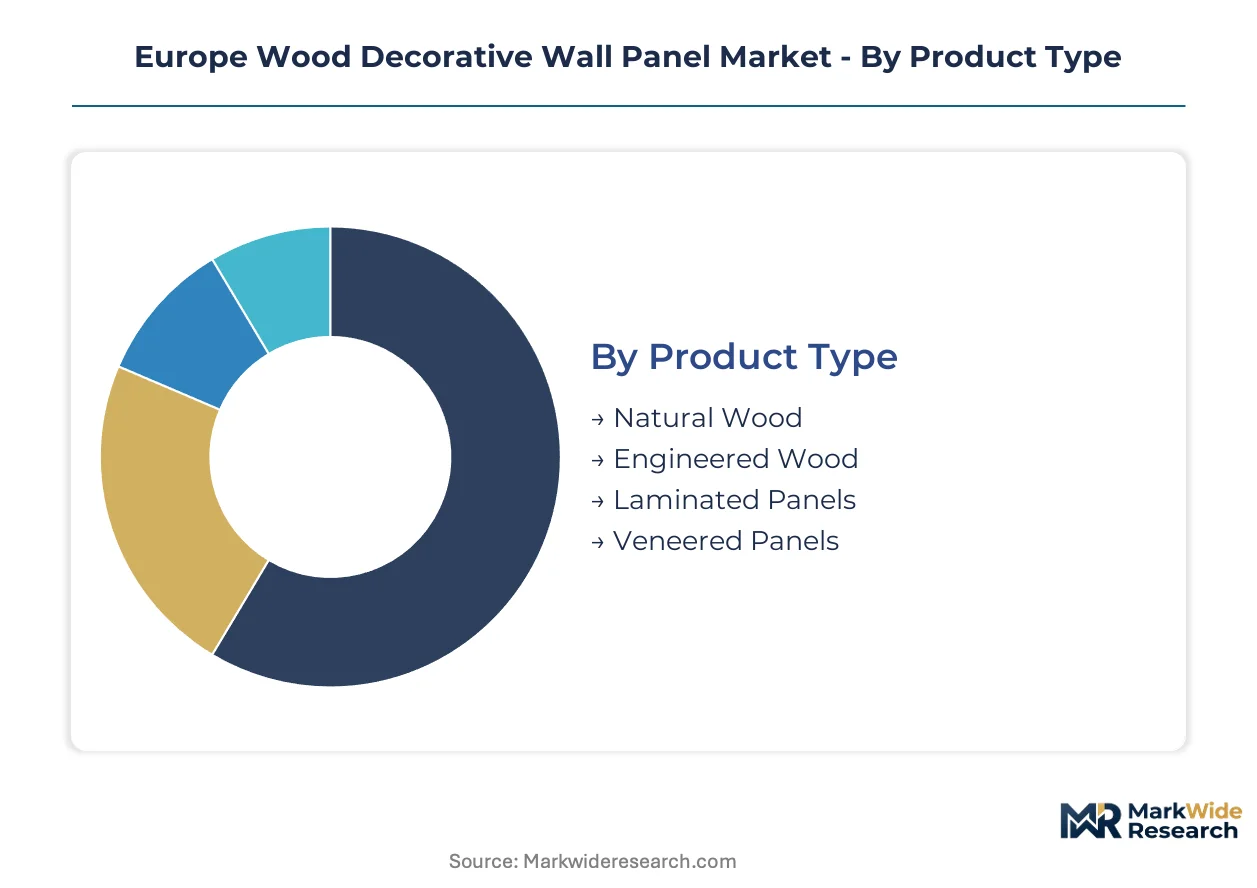
Architects and contractors specify wood decorative wall panels through multiple intersecting criteria that determine acoustic performance, fire rating, and aesthetic compliance. Segmentation clarity enables fabricators to align substrate engineering with precise end-use requirements across hospitality, retail, and residential verticals.
Product Type:
After-sales service intensity varies sharply across product types, with natural wood demanding specialized restoration expertise and engineered formats requiring technical support for modular replacement systems.
- Natural Wood:Solid timber panels deliver authentic grain variation and dimensional stability prized in heritage restoration and FSC-certified sustainable builds. Scandinavian boutique hotels specify these for acoustic-grade feature walls where biophilic design mandates override cost considerations.
- Engineered Wood:Reconstituted fiber substrates with laminated construction achieve batch consistency and moisture resistance impossible with solid-sawn lumber. German cross-laminated timber clusters supply adjacent finishing operations, reducing transport emissions for carbon-accounting-compliant public procurement.
- Laminated Panels:Multi-layer bonded construction with decorative surface films dominates volume production for retail and contractor channels across Central Europe.
- Veneered Panels:Thin natural wood laminates over engineered cores concentrate margin pools in luxury residential applications where grain authenticity drives specification.
By volume, Engineered Wood leads. By growth pace, Veneered Panels is expanding most quickly.
Application:
Cost tier stratification separates specification behavior, with hospitality and luxury residential commanding premium acoustic and fire-rated systems while retail and standard residential absorb economy-grade engineered formats.
- Residential Interiors:Homeowners and developers prioritize moisture-resistant engineered substrates for kitchens and bathrooms, while living spaces specify veneered or natural wood for feature walls. Polish fabrication clusters serve adjacent finishing operations with reduced lead times for Central European housing developments.
- Commercial Spaces:Office fit-outs mandate CE-marked acoustic installations with documented environmental product declarations under EU Construction Products Regulation. Extended certification timelines compress revenue recognition windows for project-tied orders.
- Retail Outlets:Brand environment designers favor digital-print hybrid surfaces enabling batch flexibility for seasonal refresh cycles.
- Hospitality Sector:Alpine corridor and Scandinavian boutique hotels accelerate timber cladding specification driven by guest experience premiums and biophilic design mandates.
By installed value, Hospitality Sector leads. By expansion trajectory, Commercial Spaces are gaining share fastest.
Installation Type:
Volume concentration favors standardized mounting systems, though custom fabrication retains margin premiums in architecturally complex heritage restorations.
- Wall-mounted:Vertical cladding applications dominate specification across residential and commercial verticals, with concealed fixing systems enabling seamless aesthetic surfaces required by French and German national building codes.
- Ceiling-mounted:Suspended acoustic baffle systems serve open-plan office and hospitality atrium applications where reverberation control is architecturally specified.
- Modular:Interlocking panel systems reduce on-site labor and enable future reconfiguration, attracting facility managers in commercial lease environments.
- Custom Fit:Bespoke dimensioning and surface texturing command seven-figure equipment investments, fragmenting capability between volume and premium positioning.
By specification frequency, Wall-mounted leads. By margin expansion, Custom Fit is climbing the fastest.
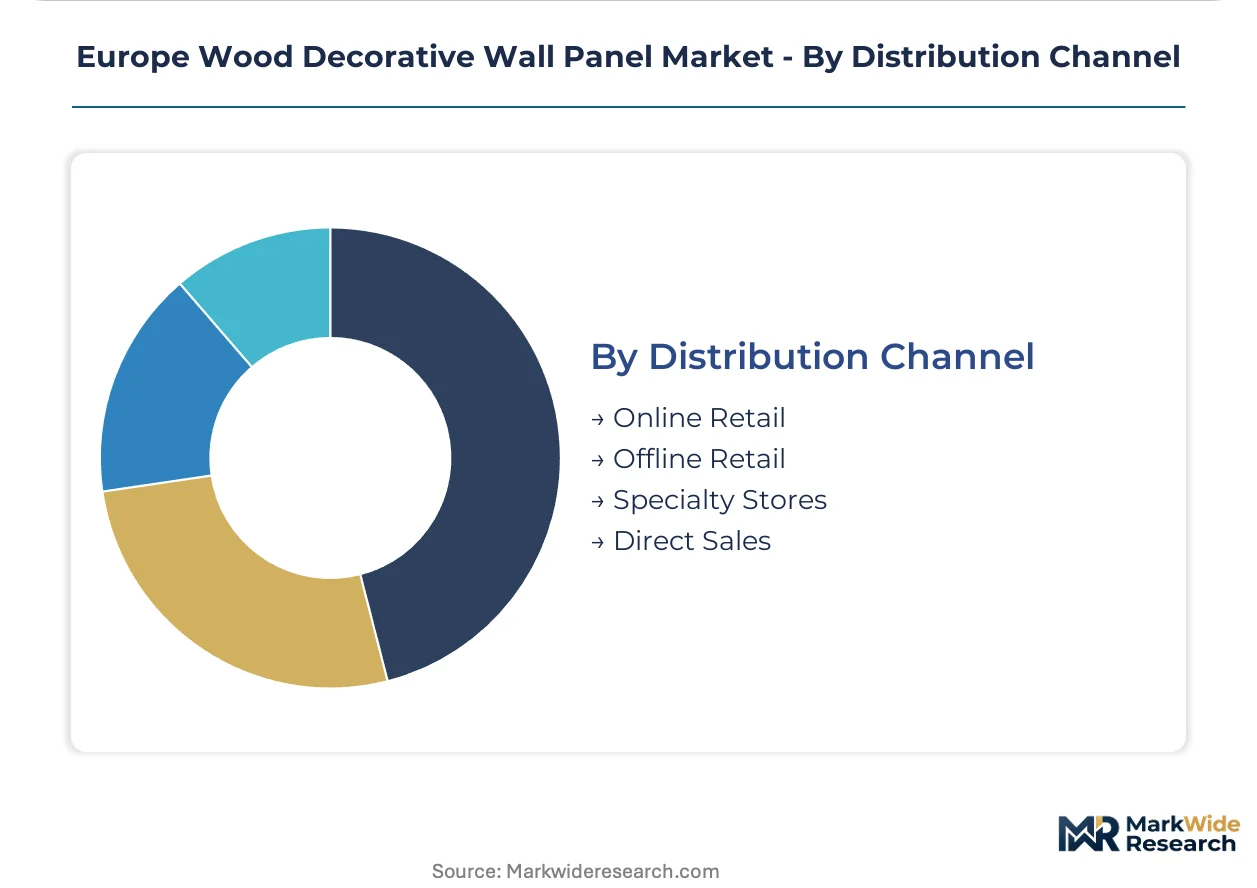
Distribution Channel:
Customer type bifurcation drives channel selection, with architects and contractors migrating to direct and digital procurement while homeowners remain tethered to physical showrooms for tactile material validation.
- Online Retail:Digital specification platforms with BIM-integrated material libraries enable direct-to-architect bypass of traditional distributor markups, with Scandinavian markets demonstrating most advanced penetration.
- Offline Retail:Builder merchant and big-box channels serve renovation contractors and self-build homeowners with standardized engineered wood inventory.
- Specialty Stores:Curated showrooms with sample libraries and fire-rated certification documentation target heritage restoration and luxury residential segments.
- Direct Sales:Fabricator-to-developer relationships dominate hospitality and commercial office verticals where project scale justifies dedicated account management.
By transaction volume, Offline Retail leads. By channel shift velocity, Online Retail is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-laminated timber fabrication clusters in Germany and Poland supply adjacent panel finishing operations, compressing transport emissions and qualifying finished goods for carbon-accounting procurement frameworks. Scandinavian boutique hotels and Alpine corridor hospitality projects concentrate specification demand for acoustic-grade timber cladding. EU Green Deal embodied-carbon thresholds filter non-compliant imports toward domestic fabricators with verified chain-of-custody documentation.
Germany
Baden-Württemberg and Bavaria host engineered wood fabrication hubs serving carbon-accounting-compliant public procurement. ECHA REACH formaldehyde emission limits force adhesive formulation upgrades across particleboard-dependent operations. CLT clusters in southern Germany supply adjacent veneer finishing lines with reduced logistics emissions for hospitality sector projects.
Poland
Expanding particleboard and MDF substrate capacity reconfigures supply dynamics for Central European downstream producers. EU Construction Products Regulation environmental product declaration mandates filter smaller competitors lacking compliance infrastructure. Manufacturing concentration near Poznań and Wrocław exposes supply chains to localized energy price volatility.
France
Île-de-France and Auvergne-Rhône-Alpes drive specification for fire-rated acoustic installations in commercial office fit-outs. National building codes layer compliance burdens for CE-marked interior finishes beyond baseline EU requirements. Paris-based architect studios migrate procurement to BIM-integrated material libraries, compressing traditional distributor showroom roles.
Sweden
Stockholm and Gothenburg boutique hotels accelerate timber cladding specification driven by biophilic design mandates and guest experience premiums. EMAS environmental management standards add certification requirements for heritage restoration segments. Swedish markets demonstrate the most advanced penetration of virtual reality visualization platforms for specification decisions.
Italy
Lombardy and Veneto concentrate luxury residential demand for veneered panels where natural grain authenticity drives specification. Extended fire-rated certification timelines for CE-marked installations delay product launches for project-tied orders. Northern Italian fabricators specialize in surface-texturing equipment for premium positioning against volume competitors.
Europe Wood Decorative Wall Panel Market Competitive Landscape
Integrated substrate-to-finish operators and specialized surface-texturing specialists split the market between margin control and premium positioning. Three strategic archetypes dominate: captive chemical and fiber operations sustaining cost discipline, high-volume engineered wood producers serving retail channels, and specialized finishing lines occupying architect-specified segments. Competitive moves concentrate on backward integration into resin production and synchronized pore line equipment investments that fragment capability between scale and premium tiers.
Among Central European integrated operators, Egger Group exemplifies captive chemical and substrate operations sustaining margin control from raw fiber through finished veneer. Kronospan anchors high-volume engineered wood output serving retail and contractor channels across the region. Swiss Krono Group occupies specialized surface-texturing positioning for premium residential segments where grain replication technology commands specification premiums. These three fabricators represent divergent strategic paths within a market filtering toward compliance-heavy, carbon-accounting-driven procurement frameworks.
| Leading Market Players |
|---|
| Egger Group |
| Kronospan |
| Swiss Krono Group |
| Finsa |
| Sonae Arauco |
| Decospan |
| Danzer |
| Arauco |
| Pfleiderer Group |
| Others |
Pricing and Supply Chain Analysis
Rhine-Alpine Corridor freight costs compress margin pools for Central European panel finishers while amplifying price differentiation between carbon-accounting-compliant domestic supply and import-dependent competitors serving cost-sensitive retail channels.
Pricing Analysis
EU Construction Products Regulation dictates the pricing tier structure across the Europe wood decorative wall panel market. Three-tier pricing structure across premium, standard, and economy levels separates FSC-certified acoustic-grade systems for hospitality from engineered wood retail formats and commodity particleboard imports. Price differentiation rests on certification grade and geographic delivery cost, with Polish substrate proximity enabling margin retention against Baltic import pressure. Cost compression in economy tiers intensifies because resin feedstock volatility transmits directly to particleboard-dependent producers without captive chemical operations. Retail contractors exhibit highest price sensitivity, while boutique hotel developers absorb premiums for biophilic-specified natural grain finishes.
Supply Chain Analysis
Egger Group and Kronospan concentrate captive substrate-to-finish capacity across Baden-Württemberg, Bavaria, and Greater Poland voivodeships. Geographic supply concentrates in Germany, Poland, and Austria where cross-laminated timber clusters feed adjacent veneer finishing lines. Raw material dependencies center on urea-formaldehyde resins, thin-veneer laminates, and decorative surface films imported from Nordic sawmills. Single-source vulnerability runs through Poznań-Wrocław particleboard concentration exposed to localized energy price shocks. Distribution runs through builder merchant networks for retail volume and direct sales teams for hospitality and commercial project specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
BIM-integrated material libraries are reconfiguring specification economics toward platform-mediated discovery, compressing traditional distributor markups while rewarding early adopters with embedded environmental product declaration data.
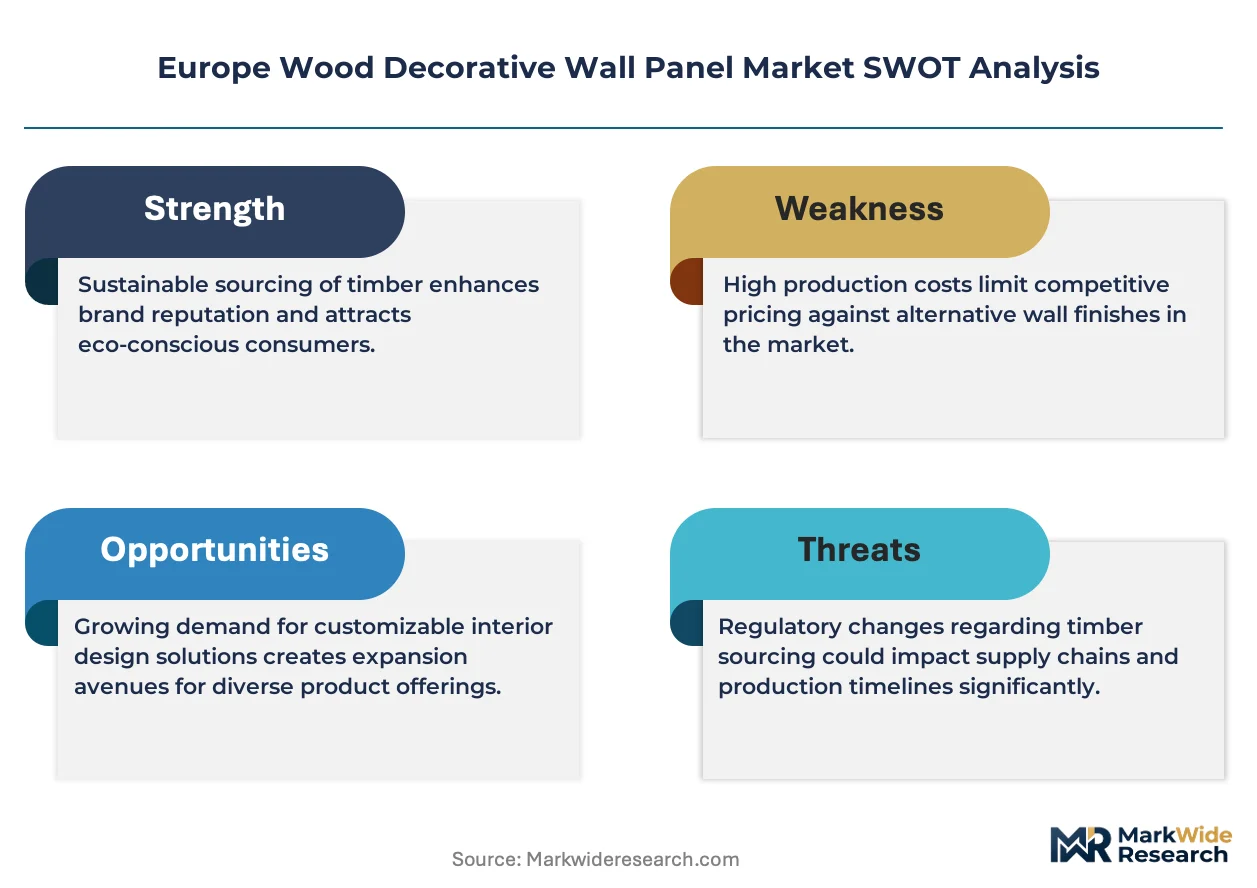
For Market Incumbents: Build certification moats around synchronized pore line investments and FSC chain-of-custody documentation. Incumbents should deepen upstream control over resin formulation to offset petrochemical feedstock volatility threatening particleboard margins. Acoustic-grade fire-rated certification infrastructure defends against low-cost Baltic imports lacking CE-marked testing protocols. For New Entrants and Emerging Players: Mid-market commercial buildings in Romania and Bulgaria represent the most penetrable entry point for acoustic-certified product lines lacking established supply relationships. New entrants should target facility manager procurement through modular interlocking systems reducing on-site labor and enabling future reconfiguration. Digital specification platform presence enables direct-to-architect bypass before incumbent distributor contracts renew. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified building materials conglomerates with underinvested decorative panel divisions lacking EPD compliance infrastructure. Long-term viability favors specialized surface-texturing specialists with seven-figure embossing equipment and verified bio-based coating formulations meeting EMAS thresholds. Watch for inflection signals in public procurement framework adoption rates for automated environmental product declaration verification.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive urea-formaldehyde supply insulates margin control from petrochemical feedstock volatility. |
| Digital Specification Platform Integration | BIM-embedded material libraries enable direct-to-architect procurement bypassing distributor markups. |
| Acoustic Fire-Rated Certification Investment | CE-marked testing protocols filter non-compliant imports from hospitality specification pools. |
| Eastern European Distribution Buildout | First-mover positioning in Romania and Bulgaria captures underpenetrated commercial construction pipelines. |
| Bio-Based Coating Formulation Development | Plant-derived oil finishes meeting French national building code thresholds unlock premium residential positioning. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EU Construction Products Regulation filings, ECHA REACH substance restrictions, and cross-laminated timber cluster production data. Primary interviews engaged plant managers at particleboard and MDF substrate facilities, procurement leads at boutique hotel developers, specification directors at Paris and Stockholm architect studios, and distribution channel partners across Central European builder merchant networks. Secondary validation drew from customs trade databases, national building code registries in France and Germany, and environmental product declaration portals. Bottom-up volume modeling triangulates against top-down sector expenditure analysis.
Forecast inputs span substrate technology evolution, regulatory chemistry restriction timelines, and hospitality construction pipeline tracking across the analysis window. Segmentation dimensions include product type, application vertical, installation system, and distribution channel, with additional modeling of carbon-accounting compliance tiers affecting public procurement eligibility. CAGRs derive from trend extrapolation of specification migration patterns and cluster-based supply capacity expansion. Industry-specific inputs incorporate CLT fabrication hub proximity effects and EMAS certification adoption curves.
Practitioners should monitor ECHA REACH formaldehyde emission limit revisions, Baltic import volume fluctuations, and BIM platform penetration rates for early signals of competitive repositioning. Forecasts reflect assumptions regarding regulatory enforcement consistency and petrochemical feedstock price stabilization. Quarterly review of environmental product declaration database entries and public procurement framework carbon-accounting adoption is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Global Furniture Market
Furniture
UK Sustainable Home Furniture Market
Furniture
Global Smart Furniture Market
Furniture
Global Free Standing Electrical Height-Adjustable Tables Market
Furniture
Global Home Furniture Market
Furniture
Portering Chair Market
Furniture
Piano Stools Market
Furniture
High End Furnitures Market
Furniture
Wooden Furniture Market
Furniture
Europe High-End Furniture Market
Furniture
Massive Wood Slabs Market
Furniture
Europe Sustainable Home Furniture Market
Furniture
United States Upholstered Furniture Market
Furniture
GCC Luxury Furniture Market
Furniture
Furniture and Home Furnishing Store Market
Furniture
Pool Tables Market