
 Software Defined Storage Market | 2026-2036
Software Defined Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Software Defined Storage Market Intelligence
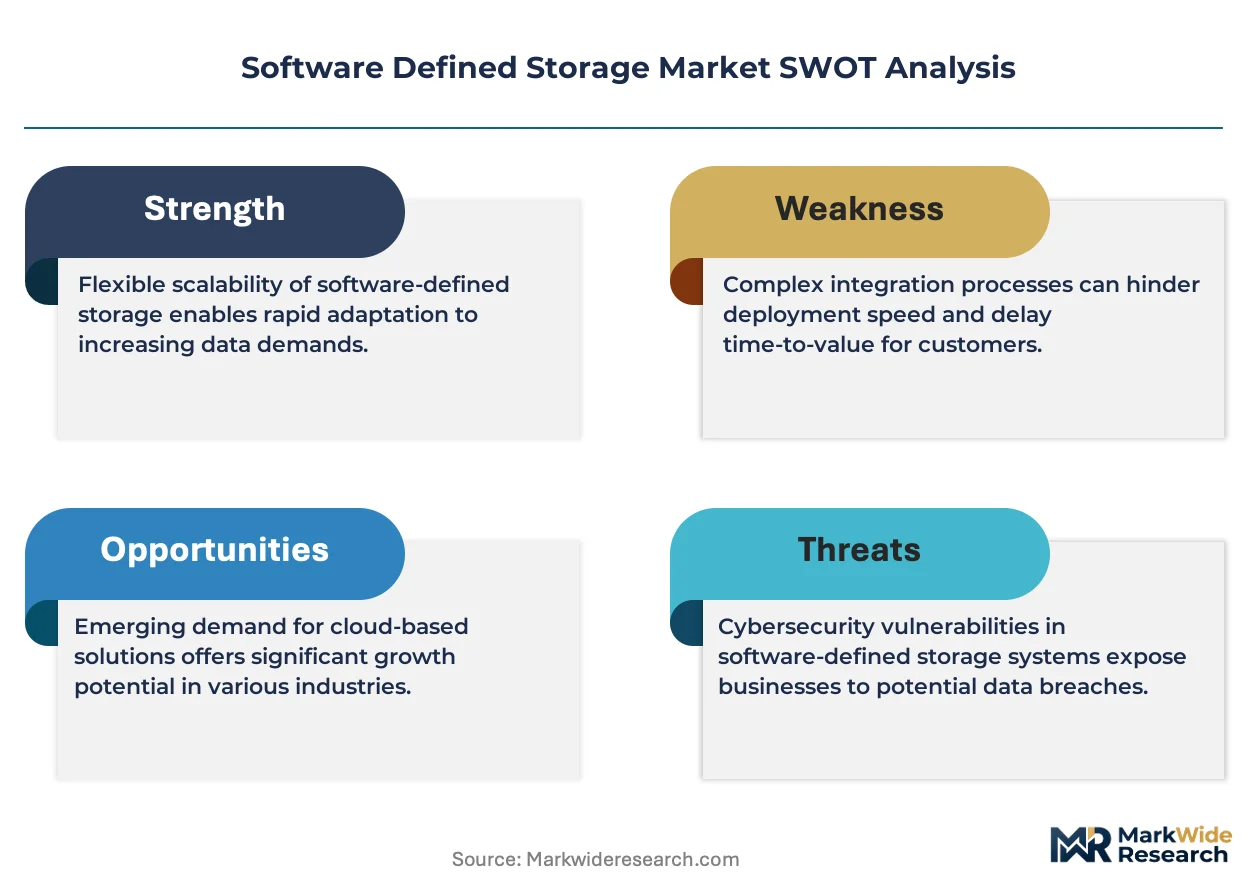
Enterprise IT departments are collapsing traditional storage procurement cycles as cloud-native buyers gain share over legacy infrastructure teams. Dell EMC leverages its server-to-storage integration to anchor large-scale virtualization deployments across Fortune 500 accounts. NetApp competes through unified data management layers that bridge on-premises and cloud-native environments. IBM differentiates via enterprise-grade object storage platforms targeting regulated industries with stringent retention requirements.
Software defined storage decouples storage software from proprietary hardware, enabling policy-driven provisioning across commodity servers via APIs and virtualization layers. The architecture pools disk, flash, and cloud resources into a single control plane, primarily serving enterprises seeking elastic capacity without vendor lock-in. Object storage solutions within this architecture capture expanding margin pools as unstructured data volumes from AI training and media archives multiply. Hybrid cloud deployment models sustain the fastest trajectory, driven by enterprises maintaining sensitive workloads on-premises while bursting analytics to public cloud infrastructure. Edge computing configurations remain nascent but attract specialized investment from telecom operators deploying distributed content delivery nodes.
FCC guidelines on communications infrastructure resilience shape storage redundancy requirements for US telecom operators, while GDPR and EU AI Act data sovereignty provisions compel European enterprises toward region-hybrid architectures. ISO 27001 and SOC 2 compliance frameworks increasingly function as procurement gatekeepers, with non-certified vendors excluded from financial services and government RFP processes. Stakeholders must weigh the pace of cloud repatriation against persistent latency requirements for AI inference workloads at the edge.
Market Dynamics
Cloud-native deployment models are collapsing traditional storage procurement cycles as enterprises abandon three-year hardware refresh schedules for API-driven, consumption-based provisioning. This structural shift redistributes margin pools from hardware vendors to software layer specialists while compressing buyer decision timelines from quarters to weeks.
Growth Catalysts
- SEC data retention mandates:Financial services firms in the United States face expanded record-keeping requirements for electronic communications and transaction logs, forcing infrastructure upgrades toward software-defined architectures that automate compliance-tier storage policies.
- Hyperscale data center buildouts:United States cloud operators are deploying software-defined storage at massive scale to support AI training workloads, creating pull-through demand for compatible enterprise-grade platforms.
- NVMe-over-Fabrics:This protocol eliminates storage network bottlenecks, enabling software-defined controllers to pool high-performance flash across distributed nodes without proprietary SAN hardware.
Market Restraints
- Specialized engineering talent scarcity:Software-defined storage deployment requires rare expertise in distributed systems, Kubernetes storage orchestration, and cloud-native data services, constraining enterprise rollout velocity.
- Flash memory price volatility:NAND contract pricing fluctuates with smartphone and PC demand cycles, compressing hardware margin predictability for vendors building all-flash software-defined arrays.
- Legacy SAN sunk costs:Enterprises with recent investments in Fibre Channel infrastructure face write-off penalties that delay software-defined storage migration timelines.
Strategic Opportunities
- Edge AI inference clusters:Telecom operators deploying 5G MEC nodes require lightweight software-defined storage for localized model serving, creating a greenfield segment outside hyperscale dominance.
- EU AI Act data sovereignty provisions:European enterprises must maintain training data within regional boundaries, accelerating demand for hybrid software-defined platforms that federate on-premises and EU-cloud resources.
- Container-native storage abstraction:Convergence of Kubernetes persistent volume management with object storage APIs enables unified data planes spanning edge, core, and cloud without vendor-specific plugins.
Industry Challenges
- Multi-cloud data mobility:Enterprises struggle to maintain consistent storage policies and data portability across AWS S3, Azure Blob, and Google Cloud Storage APIs without vendor lock-in.
- ISO 27001 certification timelines:Software-defined storage vendors targeting financial services and government sectors face 12-18 month audit cycles that delay revenue recognition from qualified pipeline.
- Retrofit complexity with mainframe environments:Regulated industries dependent on IBM z/OS storage architectures encounter integration friction when overlaying software-defined layers onto decades-old data hierarchies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Software Defined Storage Market |
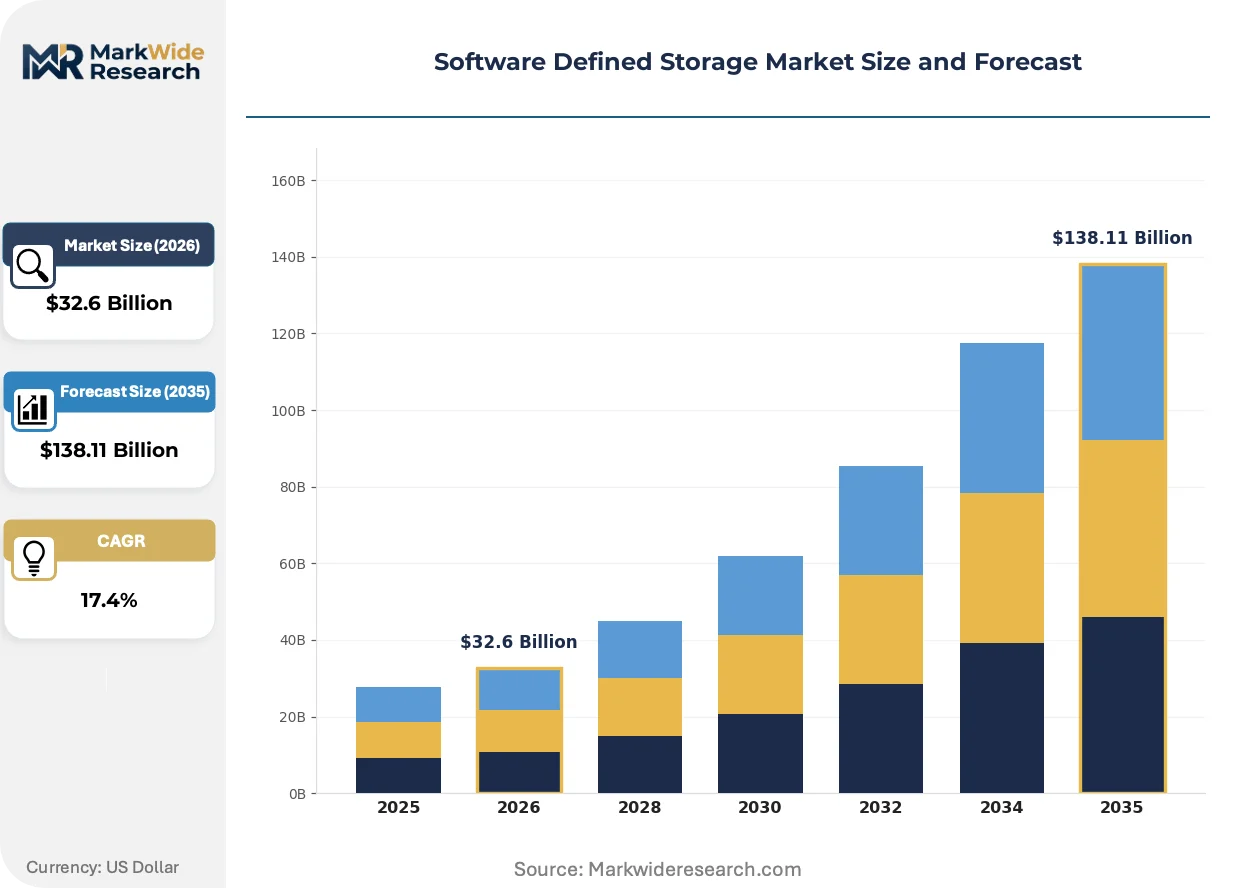
| Market Size in 2026 | $32.6 Billion |
| Market Size in 2035 | $138.11 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premises, Cloud-Native, Hybrid Cloud, Multi-Cloud, Edge Computing Solution Type: Block Storage, File Storage, Object Storage, Hyperconverged Infrastructure, Backup & Recovery Use Case: Virtualization, Big Data Analytics, Disaster Recovery, Content Delivery, DevOps Automation End User Industry: Telecom Operators, Media & Entertainment, Government Agencies, Education Sector, Manufacturing Firms |
| Companies Covered | DataCore, Quantum, NetApp, MinIO, Veeam Software, Dell EMC, DDN, Cloudian, IBM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Software Defined Storage Market Strategic Shifts & Innovations
Computational storage and AI-optimized data placement are rewriting performance economics for unstructured data workloads. These shifts compress the boundary between storage hardware intelligence and software control planes.
Computational storage drives with embedded processing cores is supplanting traditional host-based data reduction in AI training environments. Hyperscale operators are deploying these devices at rack scale to execute compression and encryption without CPU overhead. This architecture is supplanting conventional all-flash arrays for vector database and model checkpoint workloads.
GDPR Article 17 right-to-erasure enforcement is compelling storage vendors to implement automated data lifecycle policies with cryptographic deletion guarantees. European data protection authorities are auditing software-defined platforms for compliance with erasure certification requirements. Financial services firms in Germany and France are prioritizing vendors with built-in data mapping and lineage tools.
Consumption-based financing models are displacing capital purchase agreements for enterprise storage procurement. Infrastructure teams now benchmark vendors on $/TB-month operational metrics rather than three-year TCO calculations. This behavioral shift is most pronounced among North American healthcare systems navigating constrained capital budgets under CMS reimbursement pressure.
Software Defined Storage Market Segmentation
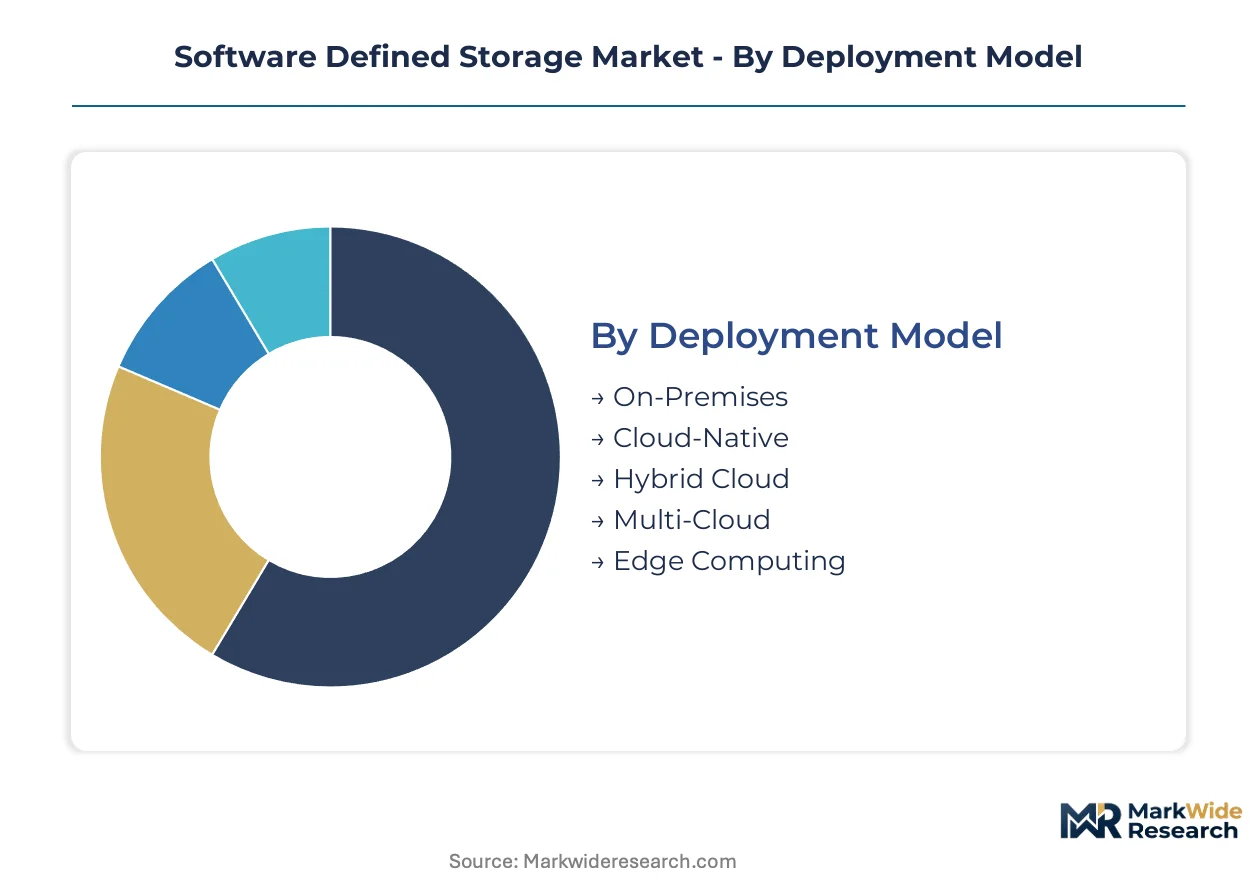
Software-defined storage architectures fragment across deployment topologies and workload characteristics, with margin distribution shifting toward cloud-native orchestration layers and object storage engines. Procurement patterns diverge sharply between latency-sensitive virtualization stacks and throughput-optimized analytics pipelines, requiring vendors to maintain parallel engineering investments.
Deployment Model:
Margin pools concentrate in hybrid cloud configurations that bridge on-premises sovereignty with public cloud elasticity, while edge computing deployments capture premium pricing for distributed latency optimization.
- On-Premises:Traditional enterprise data centers deploy software-defined controllers atop commodity server hardware to replace Fibre Channel SAN arrays. Financial services firms in the United States favor this model for SEC-mandated transaction log retention requiring air-gapped physical control.
- Cloud-Native:Containerized storage orchestration via Kubernetes persistent volumes enables API-driven provisioning without hardware procurement cycles. North American healthcare systems under CMS reimbursement pressure are collapsing three-year refresh schedules into consumption-based month-to-month contracts.
- Hybrid Cloud:Unified control planes federate on-premises flash arrays with AWS S3 or Azure Blob tiers through policy-driven data placement. GDPR Article 17 erasure mandates compel European enterprises toward this architecture for regional data sovereignty compliance.
- Multi-Cloud:Abstraction layers normalize storage APIs across competing hyperscale providers to prevent vendor lock-in. Enterprises struggle with consistent policy enforcement across AWS, Azure, and Google Cloud storage services.
- Edge Computing:Lightweight software-defined nodes deployed at 5G MEC locations support localized AI inference with sub-10ms latency requirements. Telecom operators building distributed content delivery networks represent the primary demand concentration.
On-Premises holds installed capacity. Cloud-Native is rotating up the share rankings.
Solution Type:
Application throughput requirements dictate solution selection, with unstructured data workloads driving object storage expansion and transactional systems preserving block storage dominance.
- Block Storage:NVMe-over-Fabrics protocols enable software-defined pooling of high-performance flash across distributed nodes without proprietary SAN hardware. Virtualization workloads in United States enterprise data centers sustain demand for low-latency volume services.
- File Storage:POSIX-compliant distributed filesystems serve legacy enterprise applications through NFS or SMB protocols. Media production studios in Los Angeles and New York maintain dependency on high-throughput file services for 4K/8K video editing workflows.
- Object Storage:Flat namespace architectures with erasure coding optimize cost-per-gigabyte for petabyte-scale unstructured repositories. AI training data lakes and long-term compliance archives multiply demand from hyperscale operators and regulated industries.
- Hyperconverged Infrastructure:Collapsed compute-storage networking stacks simplify procurement for mid-market enterprises with limited specialized engineering staff. Manufacturing firms with distributed plant operations favor this model for rapid remote site deployment.
- Backup & Recovery:Immutable object storage backends with ransomware-resistant air-gapping replace tape libraries for enterprise resilience strategies. ISO 27001-certified vendors capture financial services and government procurement opportunities.
Block Storage retains transactional dominance. Object Storage is climbing the fastest on AI workload expansion.
Use Case:
Workload characteristics segment procurement authority between infrastructure teams and line-of-business data science units with divergent performance priorities.
- Virtualization:VMware and Hyper-V environments demand consistent low-latency IOPS for virtual machine density optimization. United States Fortune 500 data centers represent the core installed base with entrenched refresh cycles.
- Big Data Analytics:Distributed query engines like Spark and Presto require high-throughput object storage for columnar dataset access. Cloud-native deployment models are displacing on-premises Hadoop clusters for elasticity advantages.
- Disaster Recovery:Synchronous replication across availability zones with automated failover orchestration replaces secondary data center construction. SEC-mandated business continuity requirements accelerate financial services procurement.
- Content Delivery:Geo-distributed object storage with CDN integration optimizes media streaming latency for subscriber retention. Telecom operators deploying 5G infrastructure drive edge-adjacent storage node deployment.
- DevOps Automation:Infrastructure-as-code templates for storage provisioning accelerate CI/CD pipeline velocity without ticket-based IT intervention. Technology sector enterprises with containerized microservices architectures lead adoption.
Virtualization holds installed capacity. Big Data Analytics is rotating up the share rankings.
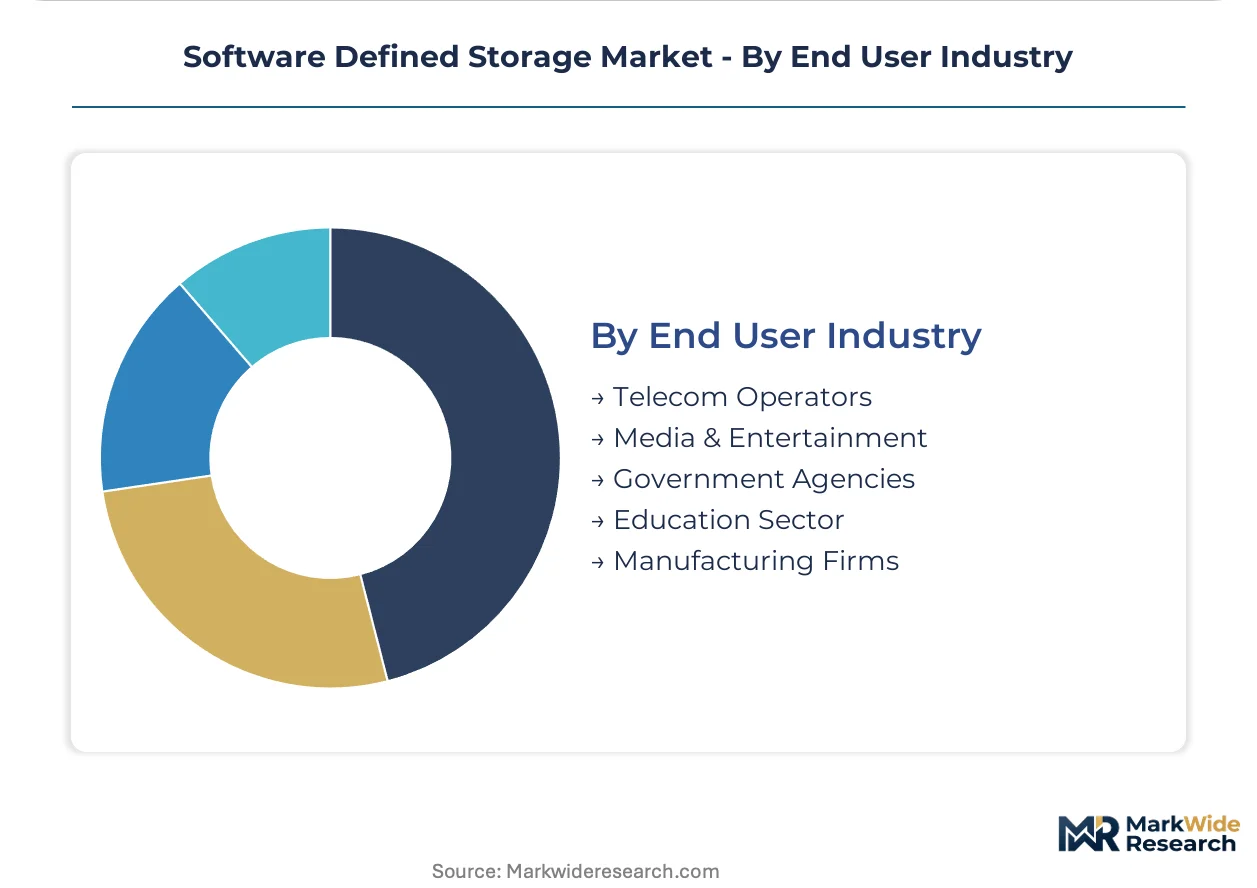
End User Industry:
Regulatory compliance intensity and data sovereignty requirements fragment procurement patterns across verticals with divergent risk tolerances.
- Telecom Operators:FCC resilience guidelines mandate storage redundancy for critical communications infrastructure. 5G MEC buildouts and distributed content delivery nodes create greenfield demand for edge-optimized software-defined platforms.
- Media & Entertainment:Exponential growth in 4K/8K production and streaming archives drives petabyte-scale object storage procurement. Los Angeles and New York production clusters concentrate demand for high-throughput file and object services.
- Government Agencies:FedRAMP and StateRAMP authorization requirements gate software-defined storage procurement for federal and state-level cloud deployments. Multi-year contract vehicles favor established vendors with compliance infrastructure.
- Education Sector:Constrained capital budgets under public funding pressures accelerate shift toward consumption-based operational expenditure models. Research universities with HPC workloads represent exceptions requiring on-premises performance.
- Manufacturing Firms:Industrial IoT sensor data lakes and predictive maintenance analytics drive edge storage deployment at plant floor locations. Legacy operational technology integration creates retrofit complexity for brownfield facilities.
Telecom Operators hold installed capacity. Media & Entertainment is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hyperscale operators export software-defined storage architectures to European enterprises navigating GDPR compliance, creating a transatlantic technology corridor that shapes procurement patterns across both markets.
United States
Hyperscale data center buildouts in Northern Virginia and Dallas-Fort Worth drive massive software-defined storage deployment for AI training workloads. SEC data retention mandates force financial services firms toward automated compliance-tier storage policies. San Francisco Bay Area cloud-native vendors supply API-driven provisioning platforms to enterprises abandoning three-year hardware refresh cycles.
Germany
Industrial IoT sensor data lakes at automotive plants in Bavaria and Baden-Württemberg demand edge-optimized software-defined nodes for predictive maintenance analytics. GDPR Article 17 right-to-erasure enforcement compels vendors to implement cryptographic deletion guarantees with automated lifecycle policies. Frankfurt's financial services cluster prioritizes ISO 27001-certified platforms for qualified procurement pipeline access.
China
Domestic cloud operators deploy software-defined storage at massive scale to support AI training and smart city data aggregation. MIIT data localization requirements mandate sovereign control over critical information infrastructure, favoring indigenous platform development. Yangtze River Delta technology corridors concentrate engineering talent for distributed systems and Kubernetes storage orchestration.
Japan
Financial institutions in Tokyo and Osaka modernize mainframe-attached storage hierarchies with software-defined overlays for hybrid cloud burst capacity. METI industrial digitization programs subsidize edge computing deployment at manufacturing sites for real-time quality control. Kansai region automotive suppliers adopt lightweight software-defined nodes for localized supply chain analytics.
United Kingdom
London-based hedge funds and trading venues adopt software-defined architectures for sub-millisecond analytics on market data streams. FCA operational resilience requirements mandate storage redundancy for critical trading infrastructure with automated failover orchestration. Cambridge-Oxford research corridor demands high-throughput object storage for genomics and AI training datasets.
Software Defined Storage Market Key Industry Players
Listed leaders compete with private specialists across capital structure and R&D velocity, creating a tiered market where scale advantages clash with targeted innovation. Public companies leverage balance sheet capacity for platform consolidation while venture-backed challengers capture cloud-native segments through API-first architectures. Three archetypes dominate: hyperscale-integrated incumbents, open-source-native disruptors, and compliance-focused specialists serving regulated verticals. Competitive moves center on strategic partnerships with Kubernetes orchestration vendors and portfolio diversification into edge-optimized configurations.
Among hyperscale-integrated incumbents, Dell EMC and NetApp exemplify the server-to-storage convergence archetype, while IBM occupies a position within the compliance-focused tier for regulated industries. Within the open-source-native segment, MinIO represents the cloud-native object storage disruptor challenging proprietary platforms through S3-compatible APIs. These three anchors illustrate the competitive tension between hardware-anchored scale and software-layer agility reshaping procurement authority across enterprise IT departments.
| Leading Market Players |
|---|
| DataCore |
| Quantum |
| NetApp |
| MinIO |
| Veeam Software |
| Dell EMC |
| DDN |
| Cloudian |
| IBM |
| Others |
Cost & Logistics Intelligence
ISO 27001 certification gates both vendor qualification and price stratification across financial services procurement pipelines, compressing margins for uncertified suppliers while enabling certified specialists to command service premiums. This dual-gate mechanism concentrates buyer power among qualified vendors and fragments price discovery across compliance tiers.
Pricing Analysis
Next-generation NVMe-over-Fabrics deployments command substantial premiums over legacy Fibre Channel SAN replacements, while prior-generation SATA-based software-defined controllers face accelerating price erosion. Consumption-based SaaS-tiered pricing dominates enterprise procurement, with differentiation driven by ISO 27001 certification tier and geographic delivery cost for edge node deployment. Cost compression in mid-market hyperconverged configurations is intensifying because hyperscale cloud operators are exporting internal cost benchmarks downward. Healthcare systems under CMS reimbursement pressure exhibit highest price sensitivity, while United States financial services firms facing SEC mandates show lowest sensitivity due to compliance-driven urgency.
Supply Chain Analysis
Taiwan and South Korea anchor NAND flash fabrication and controller silicon supply, while China concentrates commodity server motherboard and chassis manufacturing. Component sourcing draws from Taiwanese foundries for advanced storage processors, Korean fabs for high-density NAND, and Chinese integrators for white-label server hardware. Single-source vulnerability in advanced NAND nodes creates exposure to smartphone demand cycle volatility. Distribution runs through hyperscale cloud operators for direct enterprise sales, regional systems integrators for mid-market deployment, and telecom equipment vendors for edge computing configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise adoption velocity hinges on distributed systems engineering scarcity, with Kubernetes storage orchestration expertise commanding premium compensation and constraining rollout timelines for complex hybrid deployments.
For Market Incumbents: Consolidate through targeted acquisition of Kubernetes-native storage orchestration specialists to close capability gaps against cloud-native challengers. Anchor defensive positioning by deepening backward integration into NVMe controller silicon supply, insulating margin structures from NAND price volatility while accelerating certification timelines for FedRAMP and StateRAMP compliance. For New Entrants and Emerging Players: Kubernetes persistent volume management for regulated European enterprises represents a service-layer gap where incumbents under-serve GDPR Article 17 erasure automation requirements. Target German automotive and French financial services clusters with ISO 27001 pre-certified platforms. Lead go-to-market through channel partnerships with regional systems integrators possessing existing compliance-audited customer relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with venture-backed object storage specialists possessing S3-compatible APIs but lacking enterprise compliance infrastructure. Long-term viability centers on 5-10 year cloud repatriation dynamics and edge AI inference workload proliferation. Monitor hyperscale capex disclosure trends as the inflection signal for enterprise procurement cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified control planes bridging VMware environments with AWS S3 tiers accelerate hybrid cloud adoption. |
| Acquisition of Specialist Firm | Kubernetes-native storage orchestration targets address capability scarcity constraining enterprise deployment velocity. |
| Strategic Partnership | Alliances with telecom equipment vendors unlock 5G MEC edge computing procurement channels. |
| Geographic Expansion | Frankfurt and London data center presence satisfies GDPR data sovereignty mandates for EU financial services. |
| Product Launch | Computational storage drives with embedded processing cores capture AI training workload demand from hyperscale operators. |
Research Approach
A spread of perspectives from storage architects at Fortune 500 enterprises, Kubernetes platform engineers at cloud-native vendors, procurement officers at North American healthcare systems, and regulatory compliance leads at financial services firms converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through SEC 10-K filings, hyperscaler capex disclosures, and FedRAMP authorization databases. Bottom-up deployment model sizing triangulated against top-down market aggregation across the analysis window.
Deployment model, solution type, use case, and end-user industry dimensions structured the analytical framework, with additional segmentation by regional regulatory cluster capturing GDPR, SEC, and MIIT compliance variations. CAGRs derived from trend extrapolation of historical procurement patterns adjusted for technology substitution effects. Forecast inputs incorporated NVMe adoption curves and Kubernetes persistent volume attach rates across enterprise virtualization environments.
Underlying assumptions cover sustained hyperscale data center investment, stable NAND supply elasticity, and regulatory enforcement continuity, with deviation risk concentrated in flash memory price volatility and specialized engineering talent availability. Recalibration cycles align with material shifts in hyperscaler capex guidance and data sovereignty regulatory enforcement actions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Global in-Memory Database Market
Storage Solutions
Asia Pacific Automated Storage and Retrieval System Market
Storage Solutions
Netherlands Data Center Storage Market
Storage Solutions
Denmark Data Center Storage Market
Storage Solutions
Cloud Native Storage Market
Storage Solutions
Network File System Market
Storage Solutions
Automated Storage and Retrieval Systems in Laboratories Market
Storage Solutions
Global Ethernet Storage Fabric Market
Storage Solutions
Storage and Backup Software Market
Storage Solutions
Storage in Big Data Market
Storage Solutions
Global Server Storage Area Network Market
Storage Solutions
Network Attached Storage (NAS) Market
Storage Solutions
Philippines Data Center Storage Market
Storage Solutions
Global Personal Cloud Storage Market
Storage Solutions
Global Data Erasure Solutions Market
Storage Solutions
Cloud Block Storage Market