
 Global Mobile Data Protection Market | 2026-2036
Global Mobile Data Protection Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mobile Data Protection Market Foresight
Hardware-based security modules are recalibrating cost structures across the mobile data protection stack as silicon-level encryption displaces pure software implementations. Microsoft Corporation leverages its cloud-native endpoint security portfolio to anchor enterprise subscription revenue across hybrid work environments. Broadcom Inc. sustains dominant positions in secure access chips through backward integration into semiconductor design. Check Point Software Technologies Ltd. specializes in mobile threat defense for regulated industries, competing on policy granularity rather than price.
Mobile data protection encompasses the technologies, protocols, and administrative controls that secure information residing on or transiting through portable endpoints such as smartphones, tablets, and IoT peripherals, typically employing AES-256 encryption, certificate-based authentication, and containerized application isolation to prevent unauthorized exfiltration. The primary commercial purpose is to enforce confidentiality, integrity, and availability of corporate and personal data against loss, theft, or interception on devices operating outside traditional network perimeters. Encryption software and mobile device management together command the largest installed base, though cloud-based deployment modes are capturing the fastest expansion as organizations retire on-premises policy servers. Endpoint security solutions for BFSI institutions concentrate margin pools because compliance mandates require audit-ready logging and real-time threat response capabilities that command premium pricing.
The U.S. Food and Drug Administration and the Federal Communications Commission shape device-level security requirements for connected medical and communication equipment, while the European Union's GDPR and AI Act impose breach-notification timelines and algorithmic transparency obligations that directly influence mobile data protection procurement criteria. India's Telecom Regulatory Authority and Bureau of Indian Standards are tightening mobile security certification pathways for government and banking applications. Stakeholders must monitor how fragmented national encryption standards reshape cross-border product certification costs and determine whether to pursue localized compliance or modular platform architectures.
Market Dynamics
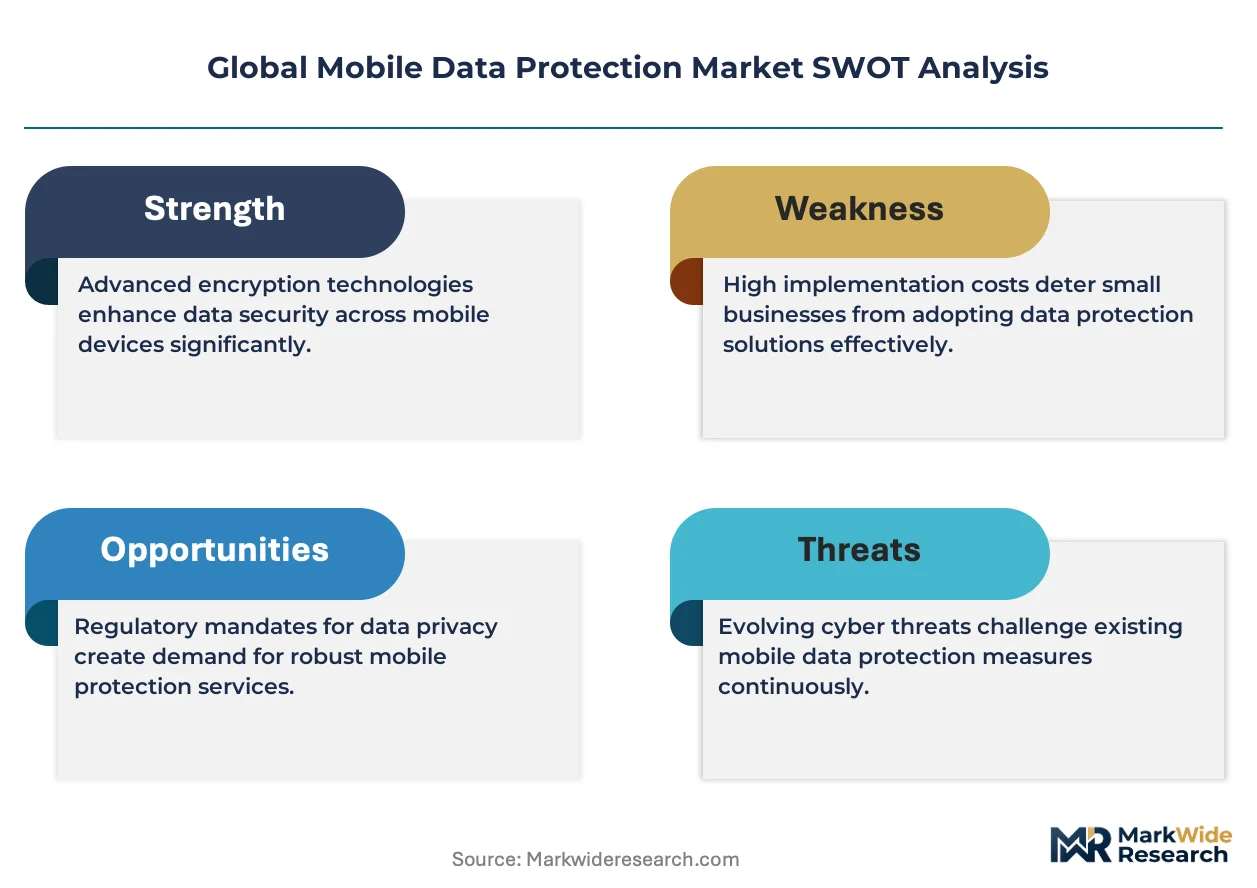
Zero-trust architecture mandates are compressing deployment cycles for mobile data protection as federal and commercial buyers reject perimeter-based security models. Hardware-rooted encryption is displacing software-only implementations across enterprise procurement specifications.
Growth Catalysts
- GDPR Article 32 Enforcement:EU data controllers now require encryption-by-default for mobile endpoints processing personal data, expanding addressable demand for certified protection suites.
- BFSI Mobile Banking Expansion:Financial institutions in India and Germany are deploying endpoint detection and response tools to satisfy real-time transaction security requirements.
- Post-Quantum Cryptography Migration:NIST-standardized algorithms are accelerating silicon refresh cycles as device manufacturers integrate quantum-resistant key exchange protocols.
Market Restraints
- Silicon Supply Concentration:Secure element fabrication depends on concentrated foundry capacity in Taiwan and South Korea, creating single-source vulnerability for hardware encryption modules.
- Cross-Border Certification Fragmentation:India's BIS and the EU's Common Criteria impose divergent evaluation standards, inflating compliance costs for multi-territory product launches.
- Substitution by Biometric-Only Authentication:Fingerprint and facial recognition systems are capturing low-risk use cases that previously required full-disk encryption, compressing entry-level pricing.
Strategic Opportunities
- India Government Sector:TRAI-mandated security certifications for mobile banking and e-governance applications are creating localized procurement windows for compliant vendors.
- Medical IoT Convergence:FDA cybersecurity guidance for connected diagnostic devices is forcing integration between mobile data protection and clinical workflow platforms.
- Subscription-Based Licensing:Per-device annual contracts are replacing perpetual licenses in enterprise segments, improving vendor revenue predictability and customer lifetime value.
Industry Challenges
- Embedded Cryptography Talent Scarcity:Firmware-level security engineering requires specialized skills in side-channel attack mitigation that outpace university pipeline output.
- Legacy MDM Integration Complexity:Enterprises maintaining on-premises mobile device management infrastructure face painful migration paths to cloud-native protection architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mobile Data Protection Market |
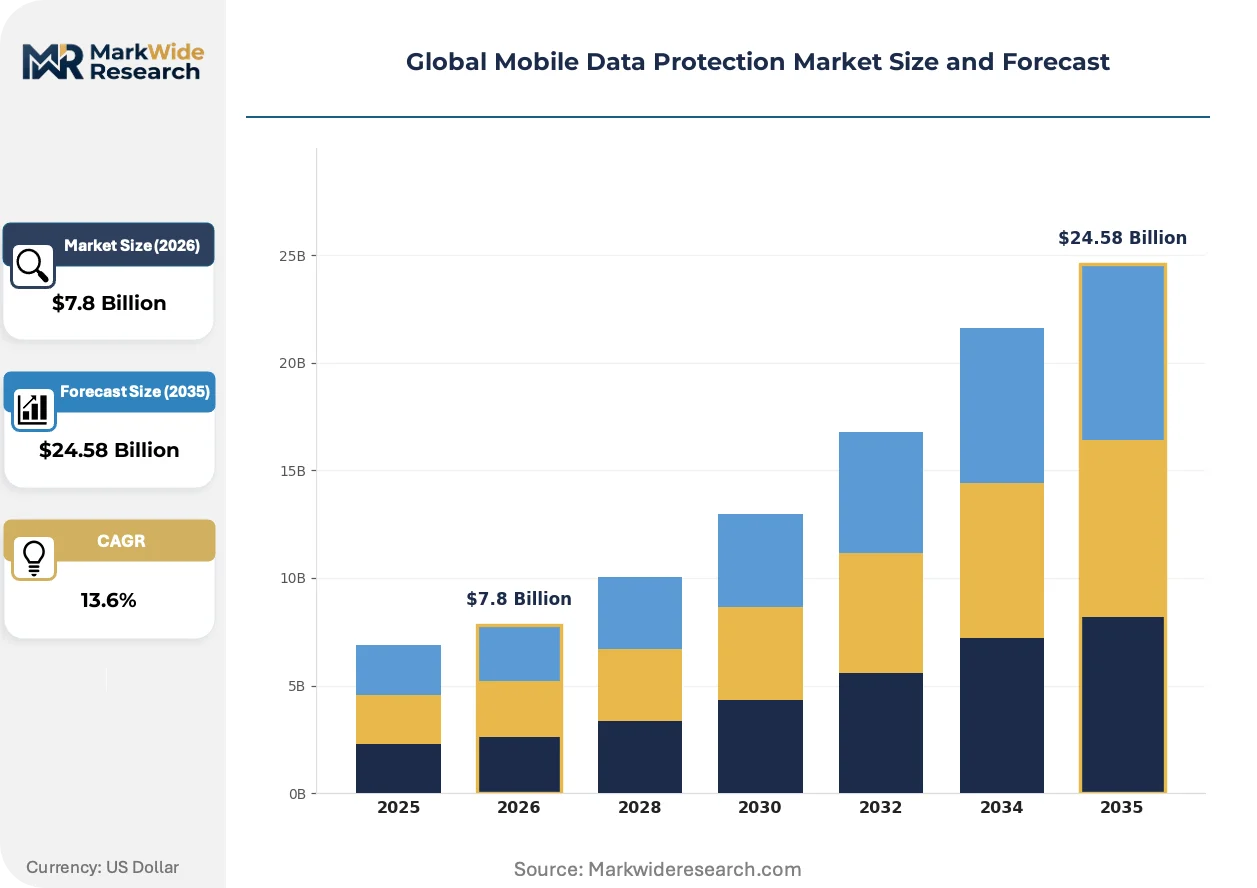
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $24.58 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Encryption Software, Endpoint Security, Data Loss Prevention, Mobile Device Management, Identity & Access Management, Secure Email Deployment Mode: Cloud-Based, On-Premises, Hybrid, Managed Services, Containerized, Virtual Appliances End User Industry: BFSI Institutions, Government Agencies, Telecommunication Firms, Media & Entertainment Companies, Education Providers, Transportation Services Device Type: Smartphones, Tablets, Laptops, Wearable Devices, IoT Devices, Rugged Devices |
| Companies Covered | Microsoft Corporation, Broadcom Inc., Dell Technologies Inc., Hewlett Packard Enterprise Company, Trend Micro Incorporated, Cisco Systems Inc., Check Point Software Technologies Ltd., McAfee LLC, IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mobile Data Protection Market Shifts & Advancements
Artificial intelligence is embedding threat detection directly into endpoint silicon, shifting competitive advantage from signature-based software to predictive hardware-software co-design. This convergence is compressing response latencies while raising barriers for pure-play software vendors.
Confidential computing extensions in ARM and x86 processor architectures are automating memory encryption without operating system involvement. Cloud service providers are adopting these instructions for multi-tenant mobile backend infrastructure. The technology is automating the isolation of sensitive workloads from hypervisor compromise, eliminating a major attack surface in virtualized environments.
The EU AI Act's risk classification system is mandating algorithmic transparency for automated decision-making on mobile platforms. Device manufacturers must now document training data provenance and model performance metrics for high-risk applications. Healthcare and financial services deployments in Germany and France are restructuring procurement specifications to require audit-ready AI governance documentation.
Enterprise buyers are consolidating mobile security spending under platform vendors rather than assembling point solutions. Chief information security officers now prefer integrated endpoint protection platforms that unify device management, threat detection, and data loss prevention. This preference consolidation is most pronounced in United States federal contracting, where FedRAMP-authorized platforms capture disproportionate award volumes.
Global Mobile Data Protection Market Segmentation
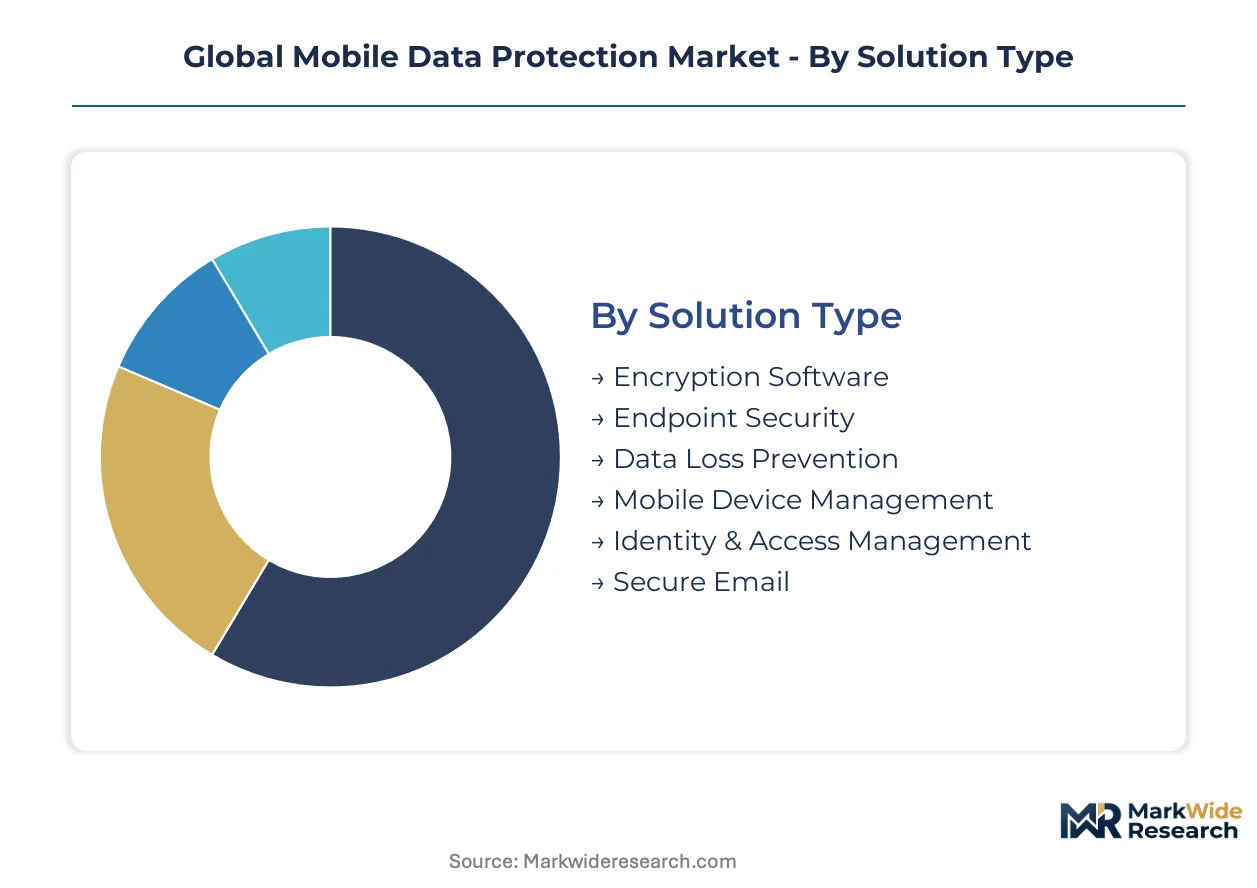
Mobile data protection vendors configure their portfolios around distinct buyer priorities: risk tolerance, infrastructure legacy, compliance exposure, and endpoint diversity. Segmentation reveals where procurement budgets concentrate and which technology combinations command premium positioning.
Solution Type:
Buyer sophistication separates enterprises seeking point-product depth from those demanding integrated platforms.
- Encryption Software:AES-256 implementations dominate enterprise specifications, with full-disk and file-level variants addressing different data-at-rest exposures. BFSI institutions in Germany and India drive procurement volume as mobile banking transaction volumes expand and regulators mandate cryptographic controls for customer financial data.
- Endpoint Security:Real-time threat detection and response capabilities anchor enterprise security stacks, integrating antivirus, behavioral analytics, and automated remediation. United States federal agencies prioritize FedRAMP-authorized endpoint protection platforms as zero-trust mandates compress deployment timelines and consolidate vendor relationships.
- Data Loss Prevention:Content inspection and policy enforcement for data-in-motion on mobile channels.
- Mobile Device Management:Policy orchestration and remote wipe capabilities for corporate-owned and BYOD fleets.
- Identity & Access Management:Certificate-based authentication and conditional access for mobile application gateways.
- Secure Email:Encrypted messaging and attachment protection for regulated communications.
Volume sits with Endpoint Security; growth tilts toward Encryption Software.
Deployment Mode:
Infrastructure maturity and data sovereignty requirements fragment procurement patterns across buyer types.
- Cloud-Based:SaaS delivery eliminates on-premises policy server maintenance and accelerates multi-tenant scaling. Organizations retiring legacy MDM infrastructure favor cloud-native architectures for reduced operational overhead and faster feature cadence.
- On-Premises:Air-gapped deployments satisfy classified environments and strict data residency mandates. Government agencies in India and defense contractors in the United States retain on-premises control to satisfy national security certification pathways and limit third-party data exposure.
- Hybrid:Split architectures balancing cloud management with local policy enforcement.
- Managed Services:Outsourced security operations for mid-market buyers lacking internal SOC capabilities.
- Containerized:Microservices-based protection modules for DevOps-integrated mobile application pipelines.
- Virtual Appliances:Software-defined security functions deployed on private infrastructure.
Cloud-Based deployments capture the steepest expansion trajectory; On-Premises retains the largest installed base among regulated industries.
End User Industry:
Compliance intensity and mobile transaction scale determine solution complexity and pricing tolerance.
- BFSI Institutions:Real-time transaction security, audit-ready logging, and regulatory reporting dominate procurement criteria. Indian banks deploying endpoint detection and response tools under TRAI-mandated certifications and German financial institutions satisfying BaFin requirements drive premium solution adoption.
- Government Agencies:Classified data handling and supply chain security impose hardware-rooted encryption requirements. United States federal buyers specify FIPS 140-2 validated modules while Indian government e-governance applications require BIS-certified security implementations.
- Telecommunication Firms:Subscriber identity protection and network edge security for carrier-managed devices.
- Media & Entertainment Companies:Digital rights management and content leak prevention for pre-release materials.
- Education Providers:Student data privacy and BYOD policy enforcement for K-12 and university environments.
- Transportation Services:Fleet device management and logistics data protection for mobile workforce coordination.
BFSI Institutions concentrate margin pools; Government Agencies provide the most stable multi-year contract structures.
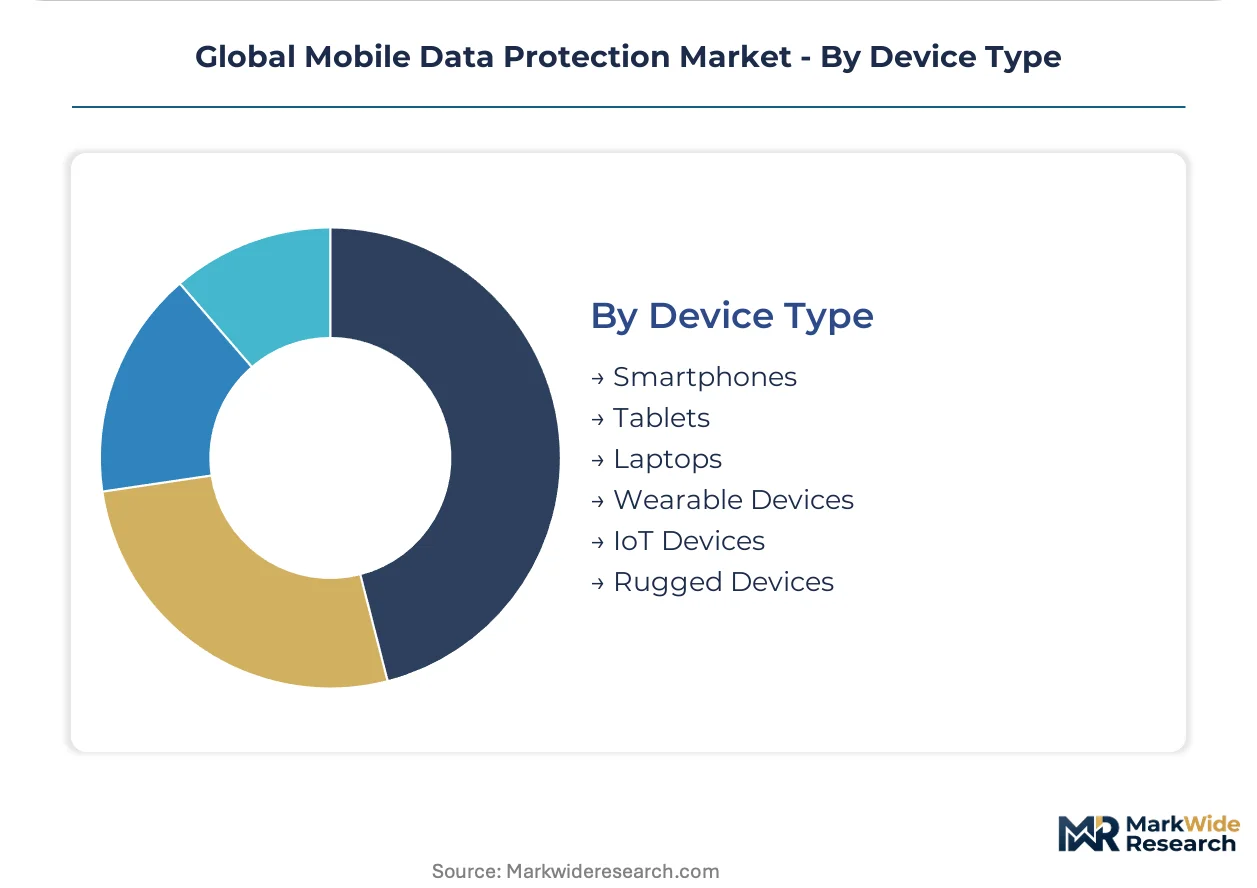
Device Type:
Form factor diversity stretches protection architectures across divergent hardware capabilities and threat models.
- Smartphones:Consumer-grade and enterprise-managed handsets constitute the primary attack surface for mobile data exfiltration. Financial services deployments in the United States and Germany prioritize containerized application isolation to separate corporate and personal data on employee-owned devices.
- IoT Devices:Resource-constrained endpoints with limited cryptographic acceleration require lightweight protection protocols. FDA cybersecurity guidance for connected medical devices in the United States forces integration between mobile data protection and clinical workflow platforms, expanding addressable scope beyond traditional IT endpoints.
- Tablets:Field service and clinical documentation platforms with larger attack surfaces than phones.
- Laptops:Full-compute endpoints bridging mobile and desktop protection requirements.
- Wearable Devices:Health and enterprise access credentials with minimal user interface for security interactions.
- Rugged Devices:Industrial and military-specified hardware operating in extreme environmental conditions.
Smartphones generate the highest unit volumes; IoT Devices are gaining share fastest as medical and industrial connectivity expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement budgets for mobile data protection concentrate in the United States, Germany, and India as federal agencies and financial institutions accelerate zero-trust deployments. Regulatory fragmentation across these jurisdictions is reshaping vendor certification strategies and localization requirements.
United States
Federal zero-trust mandates and FedRAMP authorization requirements drive enterprise endpoint security procurement. The FDA and FCC impose device-level security standards for connected medical and communication equipment. Security vendors cluster in Northern Virginia and Silicon Valley to capture federal contracting flows and cloud-native platform integration opportunities.
Germany
BaFin compliance requirements and the EU AI Act's risk classification system compel financial institutions to harden mobile governance frameworks. GDPR Article 32 enforcement mandates encryption-by-default for personal data processing on endpoints. Frankfurt and Munich host concentrated banking technology procurement, with vendors restructuring AI documentation for audit-ready healthcare and financial deployments.
India
TRAI-mandated security certifications for mobile banking and e-governance applications create localized procurement windows. The Bureau of Indian Standards tightens certification pathways for government and banking security implementations. Bengaluru and Mumbai anchor financial services technology adoption, with public sector banks deploying endpoint detection tools under regulatory pressure.
United Kingdom
Post-Brexit data protection alignment and financial services regulatory scrutiny sustain demand for audit-ready mobile security. The Information Commissioner's Office enforces breach-notification timelines that influence procurement criteria. London's fintech concentration drives containerized application isolation adoption for BYOD fleet management.
South Korea
Secure element fabrication capacity and semiconductor design leadership position the country as critical infrastructure for hardware-rooted encryption. MFDS and national cybersecurity frameworks shape medical device and government mobile security specifications. Seoul anchors Samsung and SK hynix supply chain coordination for silicon-level encryption module production.
Global Mobile Data Protection Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with platform vendors capturing consolidated enterprise accounts while point-product specialists defend niche compliance verticals. The vendor base organizes around three strategic archetypes: cloud-native platform providers with subscription revenue models, semiconductor-integrated security module fabricators, and policy-granular specialists for regulated industries. Dominant competitive moves include backward integration into silicon design and strategic partnerships to bridge legacy MDM migration paths.
Within the platform-provider tier, Microsoft Corporation and Dell Technologies Inc. exemplify cloud-native endpoint security consolidation, while Broadcom Inc. occupies a position representing semiconductor-integrated secure access chip production. Check Point Software Technologies Ltd. anchors the policy-specialist archetype for regulated industry defense. These entities collectively illustrate how competitive positioning stratifies across integrated platform breadth, hardware-software co-design depth, and vertical compliance granularity.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Broadcom Inc. |
| Dell Technologies Inc. |
| Hewlett Packard Enterprise Company |
| Trend Micro Incorporated |
| Cisco Systems Inc. |
| Check Point Software Technologies Ltd. |
| McAfee LLC |
| IBM Corporation |
| Others |
Supply & Pricing Matrix
Firmware security engineering talent concentration in Israel and Northern Virginia widens pricing-tier spreads between premium hardware-integrated suites and commodity software implementations. Labor-cost differentials for embedded cryptography specialists directly compress margins at the economy tier while FedRAMP-authorized vendors command sustained premiums.
Pricing Analysis
Volume concentrates in endpoint security subscriptions while margin pools sit with hardware-rooted encryption modules certified to FIPS 140-2 and Common Criteria. Price differentiation separates FedRAMP-authorized platform vendors from uncertified software-only competitors, with certification grade and volume scale as primary tiering mechanisms. Pricing pressure stems from biometric-only authentication capturing low-risk use cases that previously required full-disk encryption. Mid-market buyers exhibit highest price sensitivity; United States federal agencies demonstrate lowest sensitivity due to zero-trust mandate compliance deadlines.
Supply Chain Analysis
Secure element fabrication rests on concentrated foundry capacity in Taiwan and South Korea, with TSMC and Samsung Foundry anchoring silicon-level encryption module production. Raw material dependencies include high-purity silicon wafers, specialized photoresists, and rare-earth elements for magnetic components. Single-source vulnerability for advanced-node secure element production creates structural risk as geopolitical friction threatens cross-border equipment shipments. Distribution runs through direct enterprise sales for federal and BFSI accounts, with cloud service providers and systems integrators handling mid-market volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware-rooted encryption is displacing software-only implementations across procurement specifications, compressing timelines for vendors lacking silicon-integrated security portfolios.
For Market Incumbents: Anticipate margin compression from cloud-native platform vendors consolidating enterprise accounts under unified endpoint protection suites. Defend position by accelerating backward integration into semiconductor design through strategic foundry partnerships or captive secure element production. Prioritize FedRAMP authorization maintenance as United States federal contracting concentrates award volumes among authorized platforms.
For New Entrants and Emerging Players: Begin with TRAI-mandated certification pathways for Indian government and banking applications, where localized compliance requirements create procurement windows against global platform vendors. Target medical IoT convergence opportunities under FDA cybersecurity guidance, where clinical workflow integration demands specialized expertise that incumbent endpoint security vendors lack. Pursue managed security service provider partnerships to bypass direct enterprise sales infrastructure requirements.
For Investors and Strategic Acquirers: The window for entry favors semiconductor-integrated security module specialists with captive foundry relationships and existing Common Criteria certifications. Long-term viability hinges on post-quantum cryptography migration readiness as NIST-standardized algorithms accelerate silicon refresh cycles. Watch for quantum-resistant key exchange protocol integration announcements as inflection indicators for competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified endpoint protection consolidates device management, threat detection, and data loss prevention under single vendor relationships. |
| Backward Integration | In-house secure element design reduces foundry dependency and captures margin pools from hardware-encrypted endpoint sales. |
| Regulatory Certification Investment | FedRAMP and Common Criteria authorizations unlock United States federal and German BFSI procurement channels. |
| Strategic Partnership | Clinical workflow platform alliances expand addressable scope into FDA-regulated medical IoT device security. |
| Geographic Expansion | Localized TRAI and BIS certification pursuit captures Indian government sector mobile banking and e-governance deployments. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this mobile data protection market assessment. Primary interviews with chief information security officers, federal procurement officers, semiconductor supply chain managers, and clinical workflow platform engineers combined with secondary validation from FDA 510(k) submissions, FedRAMP authorization repositories, and Bureau of Indian Standards certification databases. Bottom-up endpoint shipment modeling and top-down enterprise security spending analysis provided triangulation across data sources.
Granularity-level modeling addressed solution type, deployment mode, end-user industry, device type, and geographic regulatory cluster across the analysis window. CAGRs derived from segment-specific adoption curves incorporating zero-trust mandate implementation timelines, post-quantum cryptography migration schedules, and BFSI mobile banking expansion trajectories. Forecast inputs included semiconductor foundry capacity allocation disclosures, federal IT budget appropriations, and TRAI regulatory enforcement intensity indicators.
Foundry capacity constraints, regulatory certification timeline delays, and biometric authentication substitution rates are the dominant revision risks for mobile data protection market projections. Forecasts reflect assumptions regarding sustained geopolitical friction in advanced semiconductor manufacturing access and stable enforcement intensity for GDPR Article 32 and EU AI Act obligations. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
E-Mail Security Market
Cybersecurity
Singapore Cybersecurity Market
Cybersecurity
Botnet Detection Market
Cybersecurity
Deception Technology Market
Cybersecurity
Global SSH Terminal Market
Cybersecurity
Global Information Security Consulting Market
Cybersecurity
Global Network Security Firewall Market
Cybersecurity
North America Extended Detection and Response Market
Cybersecurity
Global Digital Forensic Laboratory As a Service Market
Cybersecurity
Container-based Firewall Market
Cybersecurity
Taiwan Cybersecurity Market
Cybersecurity
Netherlands Cybersecurity Market
Cybersecurity
Global Online Fraud Detection and Prevention Market
Cybersecurity
Big Data Security Market
Cybersecurity
Africa Cybersecurity Market
Cybersecurity
Saas-Based IT Security Market