
 Barefoot Shoes Market | 2026-2036
Barefoot Shoes Market Size, Share, and Industry Trends Forecast 2026-2036
Barefoot Shoes Market Outlook
Chinese synthetic rubber suppliers are pivoting toward thinner, more flexible sole compounds that meet zero-drop specifications. Vivobarefoot leverages direct-to-consumer channels to control pricing and education touchpoints. Xero Shoes anchors its position through made-to-measure sizing platforms that reduce return rates. Merrell competes by bridging traditional outdoor credibility with barefoot biomechanics.
Barefoot shoes are footwear engineered with zero heel-to-toe drop, minimal stack height, and flexible soles that permit natural foot splay and proprioceptive feedback during locomotion. Construction typically employs 3-8mm rubber outsoles, breathable mesh uppers, and anatomically shaped toe boxes to replicate unshod biomechanics while protecting against terrain hazards. Minimalist footwear commands the largest revenue pool due to cross-category versatility, while trail runners capture the fastest growth as technical specifications migrate from niche ultrarunning into mainstream hiking. Natural rubber compounds concentrate margin pools because supply chain transparency commands premium positioning among sustainability-focused buyers.
REACH compliance in Europe restricts phthalates and heavy metals in sole compounds, forcing reformulation investments that smaller manufacturers struggle to absorb. The US Consumer Product Safety Commission monitors choking hazards in children's barefoot shoes, creating divergent testing protocols across Atlantic markets. ASTM International develops performance benchmarks for flexibility and abrasion that increasingly influence retail buyer specifications. Stakeholders must track how biomechanical research publications shift consumer preference from aesthetic minimalism toward clinically validated gait improvement claims.
Market Dynamics
REACH compliance costs are compressing supplier margins across European distribution channels while simultaneously accelerating consolidation among compound manufacturers unable to absorb reformulation investments.
Growth Catalysts
- Zero-drop biomechanics:Physiotherapy networks in Germany validate gait improvement claims, converting clinical endorsement into consumer pull through practitioner-patient channels.
- REACH chemical safety mandates:ECHA restrictions on phthalates and heavy metals create competitive moats for compliant manufacturers while disqualifying import-heavy competitors.
- Trail running technical migration:Ultrarunning specifications for flexibility and ground feel migrate into mainstream hiking footwear, expanding addressable buyer pools beyond specialist athletes.
Market Restraints
- Natural rubber supply concentration:Southeast Asian latex sourcing exposes margin pools to climate volatility and harvest disruptions.
- Stack height technical ceiling:Minimalist construction limits cushioning innovation, constraining appeal among consumers requiring orthotic accommodation or joint protection.
- Divergent Atlantic testing protocols:US Consumer Product Safety Commission choking hazard standards for children's footwear fragment compliance costs across export-oriented manufacturers.
Strategic Opportunities
- Made-to-measure sizing platforms:Digital foot-scanning integration reduces return rates while capturing proprietary biometric data for product development.
- Direct-to-consumer education infrastructure:Owned channels bypass retail margin extraction while controlling biomechanical messaging to natural movement communities.
- ASTM International performance benchmarks:Emerging flexibility and abrasion standards create certification-based differentiation opportunities ahead of retail buyer mandate adoption.
Industry Challenges
- Podiatric research translation gap:Converting peer-reviewed gait studies into marketing-compliant claims requires specialized regulatory affairs talent scarce among mid-cap footwear brands.
- Compound R&D capex intensity:Thin, flexible sole development demands iterative prototyping cycles that strain working capital for synthetic rubber formulators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Barefoot Shoes Market |
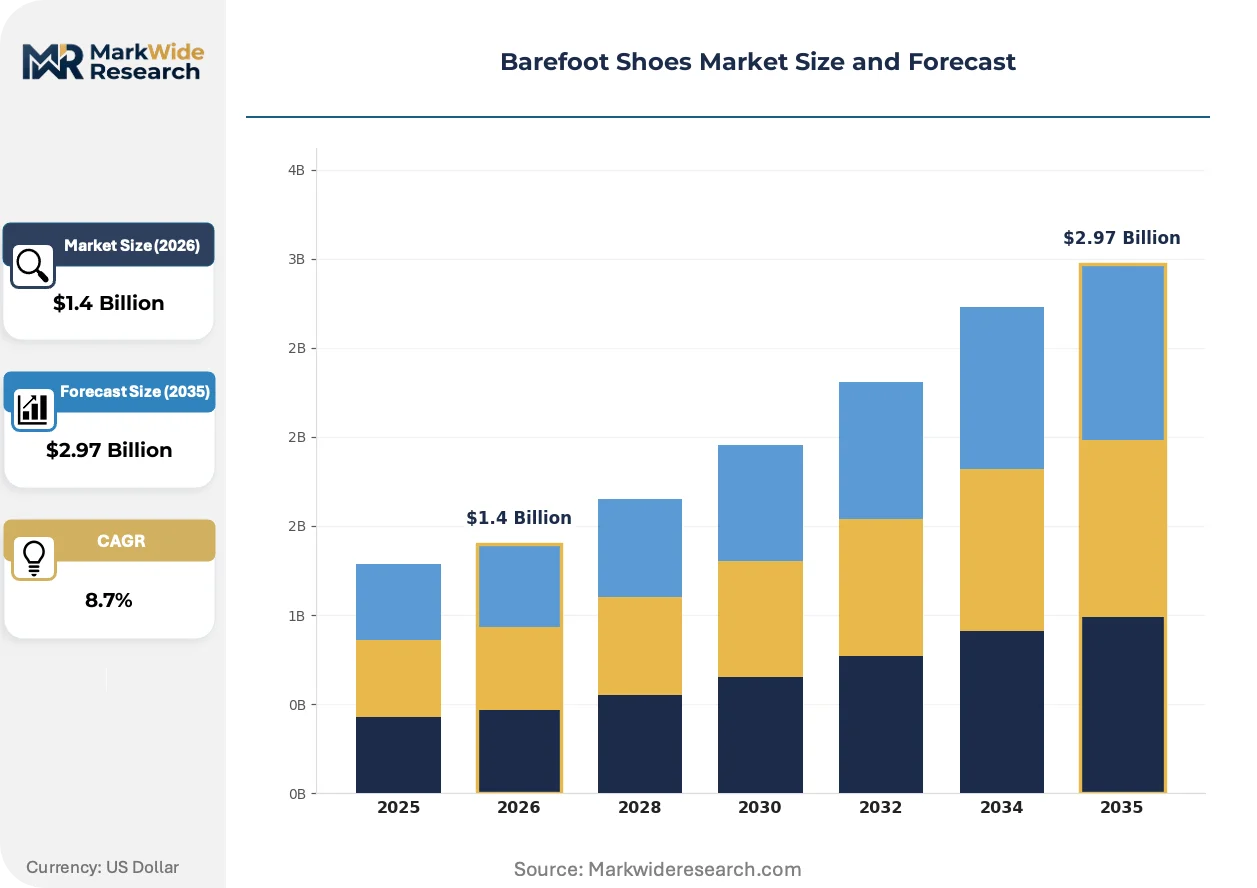
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Minimalist Footwear, Trail Runners, Casual Sneakers, Sports Shoes Material: Mesh, Leather, Synthetic, Natural Rubber Age Group: Adult, Child, Teen, Senior Application: Running, Walking, Sports, Everyday Use |
| Companies Covered | Vivobarefoot, Xero Shoes, Vibram, Merrell, Lems Shoes, Altra Running, Feelgrounds, New Balance, Be Lenka, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Barefoot Shoes Market Strategic Shifts
Biomechanical validation is displacing aesthetic minimalism as the primary purchase driver, while supply chain transparency requirements and channel restructuring reshape competitive positioning.
Laser-etched footbed topography is electrifying proprioceptive feedback engineering. Podiatric researchers at Munich Technical University validate enhanced neural mapping through calibrated surface texture patterns. Trail runners and outdoor enthusiasts adopt these configurations fastest, compressing the innovation-to-mainstream cycle from specialist ultrarunning into general hiking categories.
ECHA's 2023 REACH amendment restricting polycyclic aromatic hydrocarbons in rubber compounds forces sole manufacturers toward bio-based alternatives. Reformulation timelines extend 18-24 months for established suppliers. German and Austrian brands with captive compound development respond fastest, while import-dependent distributors face inventory discontinuity risks.
Subscription-based replacement cycles are unbundling traditional retail purchasing. Outdoor enthusiasts in Bavaria and Baden-Württemberg pilot automated resole programs tied to mileage tracking. Direct channels capture recurring revenue while reducing customer acquisition costs, though specialty retailers in these regions resist margin erosion through exclusive colorway negotiations.
Barefoot Shoes Market Segmentation
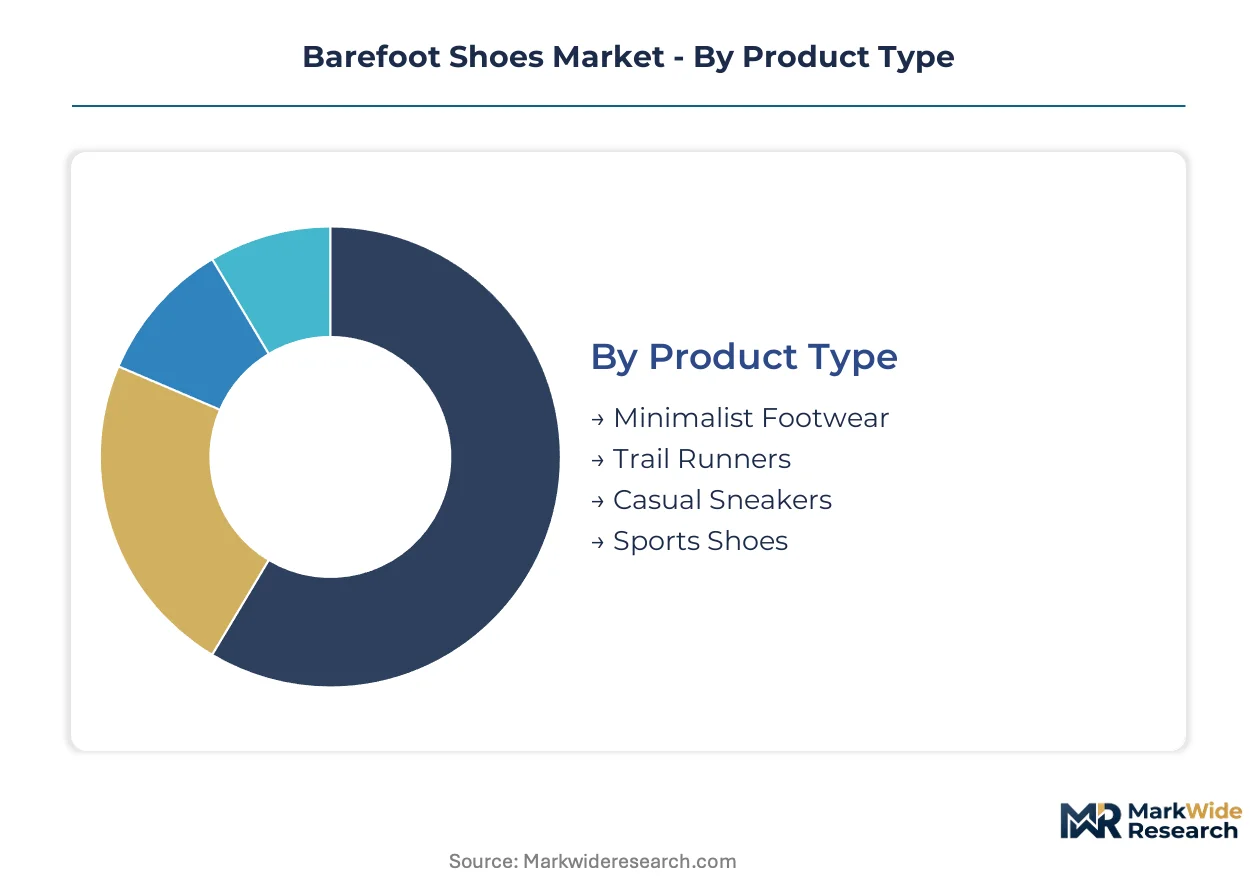
Barefoot shoes segment across biomechanical function, material composition, and user lifecycle stage. Each dimension shapes manufacturing complexity, margin structure, and channel strategy differently.
Product Type:
Buyer selection hinges on terrain specificity versus versatility trade-offs.
- Minimalist Footwear:Zero-drop construction with 3-8mm stack height and anatomical toe boxes serves cross-category use. Adult urban commuters in Germany drive volume through physiotherapy referrals validating natural gait mechanics.
- Trail Runners:Technical specifications for ground feel and proprioceptive feedback migrate from ultrarunning into mainstream hiking. Bavarian outdoor clubs accelerate adoption through community-based trial programs.
- Casual Sneakers:Aesthetic-forward designs with reduced biomechanical rigor capture fashion-adjacent buyers seeking minimalism without performance claims.
- Sports Shoes:Court-specific outsole patterns address lateral stability needs in gym and cross-training environments.
Minimalist footwear leads on scale; trail runners lead on momentum.
Material:
Supply chain transparency requirements and REACH compliance reshape procurement priorities across compound categories.
- Natural Rubber:Southeast Asian latex sourcing with harvest traceability commands premium positioning among sustainability-focused buyers in Austria and Germany. ECHA polycyclic aromatic hydrocarbon restrictions favor bio-based alternatives with 18-24 month reformulation timelines.
- Mesh:Breathable synthetic weaves dominate upper construction for running applications. Chinese suppliers pivot toward thinner, more flexible compounds meeting zero-drop specifications.
- Leather:Full-grain and nubuck variants serve casual and heritage-positioned lines requiring durability over ground feel.
- Synthetic:PU and TPU compounds offer cost-efficient alternatives for entry-tier positioning, though phthalate restrictions constrain formulation flexibility.
Natural rubber dominates margin capture; mesh dominates unit volume.
Age Group:
Biomechanical development stage and regulatory exposure determine product architecture and compliance burden.
- Adult:Largest addressable pool with established physiotherapy referral channels converting clinical validation into purchase intent.
- Child:US Consumer Product Safety Commission choking hazard standards fragment testing protocols. German pediatric podiatry networks emphasize natural foot development.
- Teen:Athletic program adoption and peer influence drive trial, with school running clubs in Baden-Württemberg serving as conversion nodes.
- Senior:Joint protection needs and balance improvement claims attract buyers, though stack height limitations constrain orthotic accommodation.
Adult segments anchor revenue; child segments face steepest regulatory complexity.
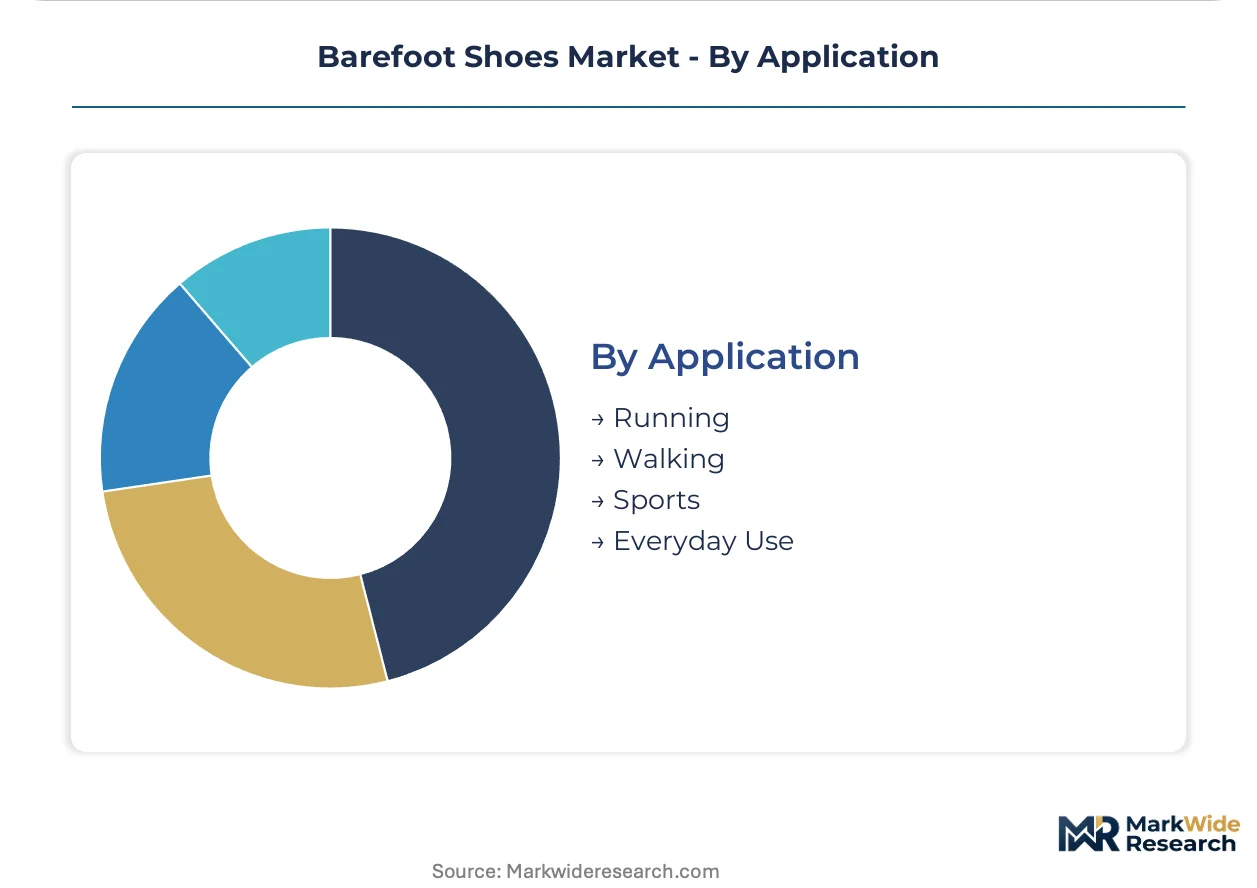
Application:
Activity intensity and surface variety dictate sole compound selection and durability specifications.
- Running:Forefoot strike optimization and cadence feedback requirements drive technical specification density. Munich Technical University research on laser-etched footbed topography validates neural mapping benefits.
- Walking:Moderate mileage and urban surface predictability allow simplified construction with broader size range accommodation.
- Sports:Multi-directional movement patterns demand reinforced lateral stability absent in pure running designs.
- Everyday Use:Versatility prioritization accepts biomechanical compromise for aesthetic and workplace appropriateness.
Running commands specification leadership; everyday use commands distribution breadth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH compliance costs in Europe are driving production migration toward jurisdictions with lower chemical safety enforcement burdens. Southeast Asian compound manufacturers absorb reformulation investments more readily than European counterparts. This regulatory-arbitrage dynamic reshapes supply chain geography across the forecast window.
Germany
Natural movement communities in Bavaria and Baden-Württemberg validate gait improvement claims through physiotherapy networks. ECHA polycyclic aromatic hydrocarbon restrictions force sole manufacturers toward bio-based alternatives with 18-24 month timelines. Munich Technical University researchers pioneer laser-etched footbed topography for enhanced proprioceptive feedback.
United States
Trail running adoption accelerates through ultrarunning community influence migrating into mainstream hiking. Consumer Product Safety Commission choking hazard standards for children's footwear fragment testing protocols. Colorado and California outdoor retail clusters anchor specialty distribution for technical barefoot specifications.
China
Synthetic rubber suppliers pivot toward thinner, more flexible compounds meeting zero-drop specifications. GB standards on footwear materials create parallel compliance tracks distinct from REACH. Guangdong and Zhejiang manufacturing belts concentrate domestic production capacity for export-oriented brands.
Austria
Pediatric podiatry networks emphasize natural foot development for child segments. EU Green Deal procurement criteria favor supply chain transparency in natural rubber sourcing. Vienna serves as a conversion node for subscription-based replacement cycle pilots tied to mileage tracking.
United Kingdom
Direct-to-consumer education infrastructure bypasses retail margin extraction while controlling biomechanical messaging. UKCA marking requirements post-Brexit diverge from CE conformity assessment procedures. London and Southeast England clusters host digital foot-scanning platform development for made-to-measure sizing.
Barefoot Shoes Market Competitive Environment
German and Austrian producers anchor the premium tier through captive compound development and REACH compliance integration. Chinese suppliers hold the volume tier through flexible sole manufacturing scale. The market structures around three archetypes: biomechanical research validators, direct-to-consumer educators, and made-to-measure sizing specialists. Capacity expansion and strategic partnerships dominate competitive moves as brands secure compound supply and distribution access.
Within the direct-to-consumer educator archetype, Vivobarefoot exemplifies owned-channel pricing control and natural movement community engagement. Xero Shoes occupies a position emphasizing made-to-measure sizing platforms that reduce return rates. Merrell represents the bridge archetype, connecting traditional outdoor credibility with barefoot biomechanics validation. These three companies collectively illustrate the strategic segmentation between pure-play minimalists and hybrid outdoor crossover positioning.
| Leading Market Players |
|---|
| Vivobarefoot |
| Xero Shoes |
| Vibram |
| Merrell |
| Lems Shoes |
| Altra Running |
| Feelgrounds |
| New Balance |
| Be Lenka |
| Others |
Value Chain & Pricing Dynamics
ECHA's REACH polycyclic aromatic hydrocarbon restrictions gate qualified supply for premium-tier barefoot shoe manufacturers while simultaneously compressing margin pools for non-compliant competitors. German and Austrian brands with captive compound development capture pricing power through bio-based sole certification, whereas import-dependent distributors face inventory discontinuity risks that force discounting to maintain shelf presence.
Pricing Analysis
Distributor margin extraction in European specialty retail runs 35-45 percent, compressing to 15-20 percent for direct-to-consumer channels that control biomechanical education touchpoints. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified natural rubber compounds from phthalate-restricted synthetics and entry-tier PU alternatives. Pricing pressure stems from Chinese synthetic rubber suppliers pivoting toward zero-drop specifications at scale. Trail runners and outdoor enthusiasts exhibit lowest price sensitivity due to technical specification loyalty, while casual sneaker buyers drive volume through promotional elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Southeast Asian latex harvesting concentrated in Thailand, Indonesia, and Vietnam, where climate volatility and harvest disruptions expose margin pools to commodity price spikes. Natural rubber, breathable mesh weaves, and laser-etched footbed compounds constitute critical input dependencies. Regulatory restriction through ECHA reformulation timelines creates 18-24 month supply gaps for non-captive manufacturers. Distribution runs through direct-to-consumer platforms, specialty outdoor retailers in Bavaria and Colorado, and physiotherapy network referrals in German urban centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where REACH compliance costs in Europe exceed reformulation investments absorbed by Southeast Asian compound manufacturers, creating margin capture opportunities for brands with dual-sourcing flexibility.
For Market Incumbents: Lock in captive compound development capacity in Germany and Austria to defend against ECHA regulatory escalation while securing bio-based alternative pipelines ahead of 18-24 month reformulation windows. Deepen physiotherapy network channel control in Bavaria and Baden-Württemberg to convert clinical endorsement into recurring subscription revenue through mileage-tracking resole programs. For New Entrants and Emerging Players: Begin with made-to-measure sizing platforms targeting senior and child segments where orthotic accommodation gaps and natural foot development claims create white-space opportunity. Austrian pediatric podiatry networks and German school running clubs in Baden-Württemberg represent the most penetrable conversion nodes. Pursue digital foot-scanning integration as primary go-to-market angle to reduce return rates and capture proprietary biometric data. For Investors and Strategic Acquirers: Roll-up economics work for biomechanical research validators because podiatric research translation gaps create scarcity value for regulatory affairs talent capable of converting gait studies into marketing-compliant claims. Long-term viability hinges on certification-based differentiation ahead of ASTM International performance benchmark adoption. Watch laser-etched footbed topography adoption rates in trail running categories as inflection indicator for innovation-to-mainstream cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Education Infrastructure | Vivobarefoot's owned-channel pricing control bypasses retail margin extraction while validating gait improvement claims. |
| Made-to-Measure Sizing Platform | Xero Shoes reduces return rates through digital foot-scanning integration capturing proprietary biometric data for product development. |
| Biomechanical Research Validation | Munich Technical University laser-etched footbed studies convert peer-reviewed gait research into marketing-compliant neural mapping claims. |
| Subscription-Based Replacement Cycles | Bavaria and Baden-Württemberg outdoor enthusiasts pilot automated resole programs tied to mileage tracking reducing customer acquisition costs. |
| REACH Compliance Integration | German and Austrian brands with captive compound development respond fastest to ECHA polycyclic aromatic hydrocarbon restrictions creating competitive moats. |
Study Parameters
Multiple input streams — primary interviews with barefoot shoe brand executives, compound manufacturing R&D directors, and physiotherapy network practitioners; secondary validation through ECHA regulatory filings, ASTM International standard development records, and customs trade data — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured procurement priorities across German specialty retailers, Austrian pediatric podiatry clinics, and Colorado outdoor retail clusters. Secondary sources included REACH compliance databases, Munich Technical University biomechanical research publications, and Nielsen retail audit data tracking category penetration in Bavaria and Baden-Württemberg.
Data-stream reconciliation across product type, material composition, age group, and application segmentation dimensions anchored volume and value modeling throughout the forecast period. CAGRs were derived from trend extrapolation calibrated against historical adoption curves in adjacent minimalist footwear categories. Industry-specific forecast inputs incorporated ECHA reformulation timeline assumptions, laser-etched footbed topography adoption rates, and physiotherapy referral channel expansion trajectories in German-speaking markets.
Several conditions sit outside the modeled scope, including unforeseen regulatory acceleration beyond REACH amendments, breakthrough cushioning technologies that resolve stack height limitations for senior segments, and macroeconomic shocks disrupting Southeast Asian latex harvesting. Forecasts reflect documented assumptions regarding biomechanical validation displacement of aesthetic minimalism and subscription model adoption rates among outdoor enthusiasts. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Mountain Bike Footwear and Socks Market
Footwear
Ankle Boots Market
Footwear
High Heels Footwear Market
Footwear
Global Espadrille Flats Market
Footwear
OEM Shoe Manufacturer Service Market
Footwear
Middle East and Africa E-Commerce Footwear Market
Footwear
Shoe Rental Service Market
Footwear
Chunky Sneaker Market
Footwear
South America Athletic Footwear Market
Footwear
Middle East and Africa Athletic Footwear Market
Footwear
Riding Boots Market
Footwear
Sneaker Identification Service Market
Footwear
Leather Sneakers Market
Footwear
Global Men Leather Shoes Market
Footwear
Premium Shoes Market
Footwear
Snow Boots for Women Market