
 Ankle Boots Market | 2026-2036
Ankle Boots Market Size, Share, and Industry Trends Forecast 2026-2036
Ankle Boots Market Outlook
Modular sole-and-upper bundling is pivoting how consumers configure ankle boots across seasons, letting buyers swap weather-rated outsoles without replacing full pairs. Dr. Martens leverages its heritage manufacturing base to sustain premium positioning in durable leather constructions. Timberland anchors its competitive stance through upstream control over waterproof membrane technology. Thursday Boot Co. differentiates via direct-to-consumer channel control that bypasses wholesale markups.
Ankle boots are close-fitting footwear extending to the ankle bone, typically constructed with leather or synthetic uppers, reinforced heel counters, and rubber or leather outsoles designed for ground traction and weather protection; they serve commercial purposes across fashion retail, occupational safety, and outdoor recreation segments. Chelsea boots lead volume within the product type dimension due to elastic-sided convenience and workplace versatility, while Western styles occupy higher margin pools in specialty retail. Leather commands the material hierarchy for durability perception, though synthetic alternatives are gaining fastest among budget-tier buyers seeking animal-free options.
The European Chemicals Agency enforces REACH restrictions on chromium VI in leather tanning, compelling suppliers to certify finishing processes or lose EU market access. The US Consumer Product Safety Commission monitors phthalate content in synthetic uppers, shaping formulation choices for brands selling into American retail. California's Proposition 65 requires explicit labeling of chemicals known to reproductive harm, adding compliance costs that filter through pricing structures. Stakeholders must monitor emerging state-level chemical disclosure expansions beyond California to anticipate fragmented compliance burdens.
Market Dynamics
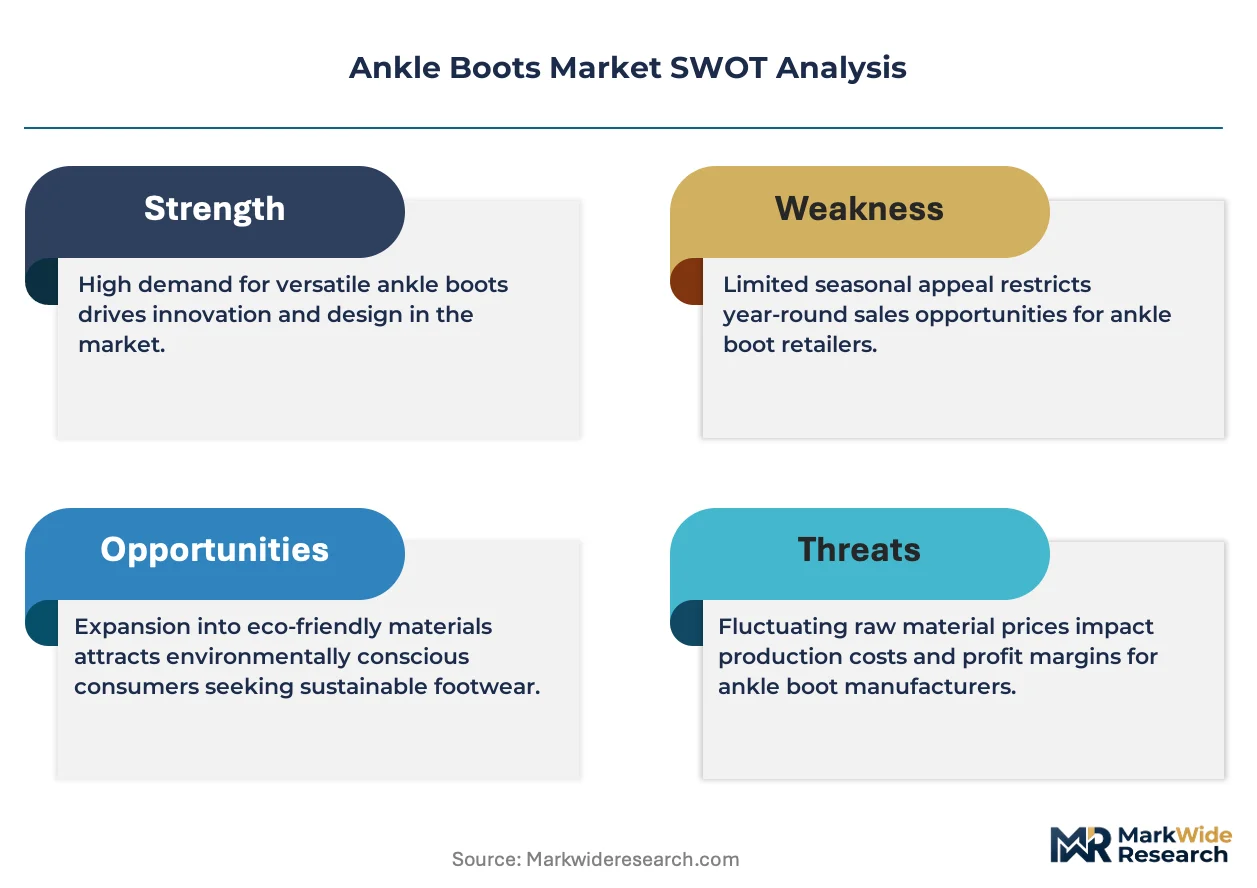
REACH compliance and California Proposition 65 disclosure mandates are compressing material sourcing flexibility across the ankle boots supply chain, forcing tanneries and synthetic suppliers to certify chemical profiles or exit major Western retail channels.
Growth Catalysts
- Urban fashion retail densification:Women's footwear specialists are expanding floor space for ankle boots in Tier-1 Chinese cities, pulling volume through localized design studios.
- REACH chromium VI restrictions:European tanneries investing in vegetable-tanning alternatives capture preferential placement with EU-based brands seeking compliant leather inputs.
- Waterproof membrane integration:Bonded construction techniques are penetrating occupational safety segments where all-weather performance commands specification priority.
Market Restraints
- Leather input cost volatility:Argentine and Brazilian hide supply fluctuations transmit directly to finished goods pricing, compressing margin buffers for mid-tier assemblers.
- Proposition 65 labeling friction:California's chemical disclosure requirements add documentation overhead that filters through to retail price points, deterring smaller exporters.
- Synthetic upper substitution ceiling:Durability perception gaps limit animal-free alternatives to budget-tier positioning despite formulation advances.
Strategic Opportunities
- Direct-to-consumer channel bypass:Vertical control over digital storefronts eliminates wholesale markups and captures first-party demand data for sizing algorithms.
- Modular sole-and-upper systems:Interchangeable weather-rated components extend product lifecycle and justify premium positioning through repairability credentials.
- Domestic Chinese premium leather:Local tanneries upgrading to full-grain constructions are displacing Italian imports in domestic brand supply chains.
Industry Challenges
- Certification timeline compression:ECHA's accelerated substance evaluation schedules force reformulation cycles that outpace traditional seasonal product development.
- Specialized pattern-making talent scarcity:Last-design expertise for Chelsea and Western silhouettes concentrates in legacy manufacturing clusters, constraining geographic diversification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ankle Boots Market |
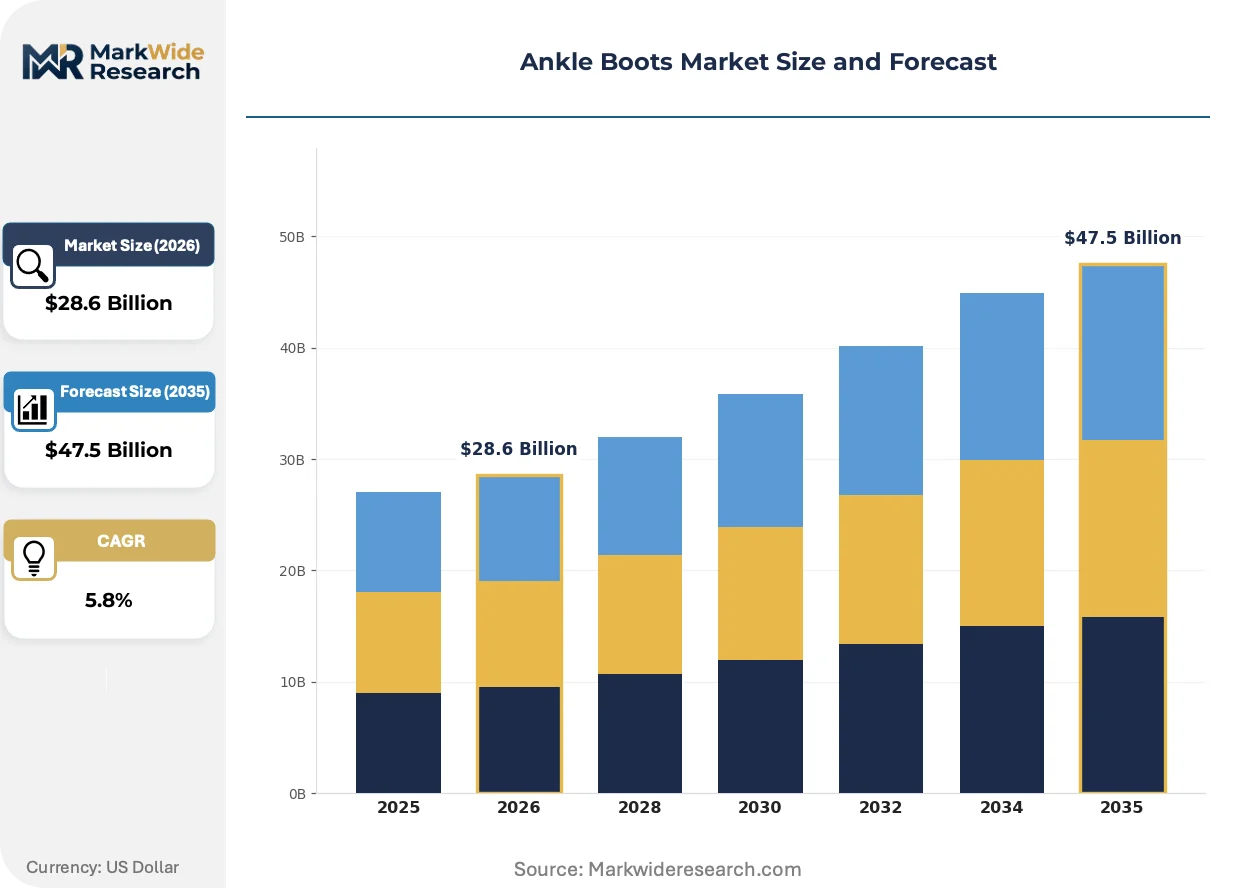
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chelsea, Chukka, Western, Dress Material: Leather, Suede, Synthetic, Canvas End User: Women, Men, Unisex, Kids Price Tier: Luxury, Mid-Range, Budget, Discount |
| Companies Covered | Dr. Martens, Steve Madden, Clarks, Timberland, Sam Edelman, Frye Company, Cole Haan, Aldo Group Inc., Thursday Boot Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ankle Boots Market Strategic Shifts
Material science advances and channel restructuring are converging to reshape how ankle boots are specified, manufactured, and sold across fashion and functional segments.
Water-based polyurethane coatings are expanding into premium synthetic uppers, delivering abrasion resistance comparable to split leather without tanning chemical exposure. Fast-fashion retailers in Germany and the Netherlands are adopting these formulations at scale for autumn-winter lines. The technology is expanding into territory previously reserved for leather-construction specialists, compressing the performance gap between animal and synthetic inputs.
REACH authorization requirements for chromium VI compounds are forcing tanneries to document alternative finishing chemistries or surrender EU market access. The European Chemicals Agency's 2024 substance evaluation wave targeted leather processing aids specifically. Italian and Spanish tanneries serving luxury footwear brands are responding with accelerated vegetable-tanning investments and third-party OEKO-TEX certification.
Repairability mandates in France and forthcoming EU-wide durability labeling are shifting buyer specifications toward resoleable constructions and disclosed component lifespans. Commercial buyers in Scandinavian public procurement are now weighting total cost-of-ownership metrics over upfront unit pricing. This specification shift favors modular boot architectures with replaceable outsoles and documented component sourcing.
Ankle Boots Market Segmentation
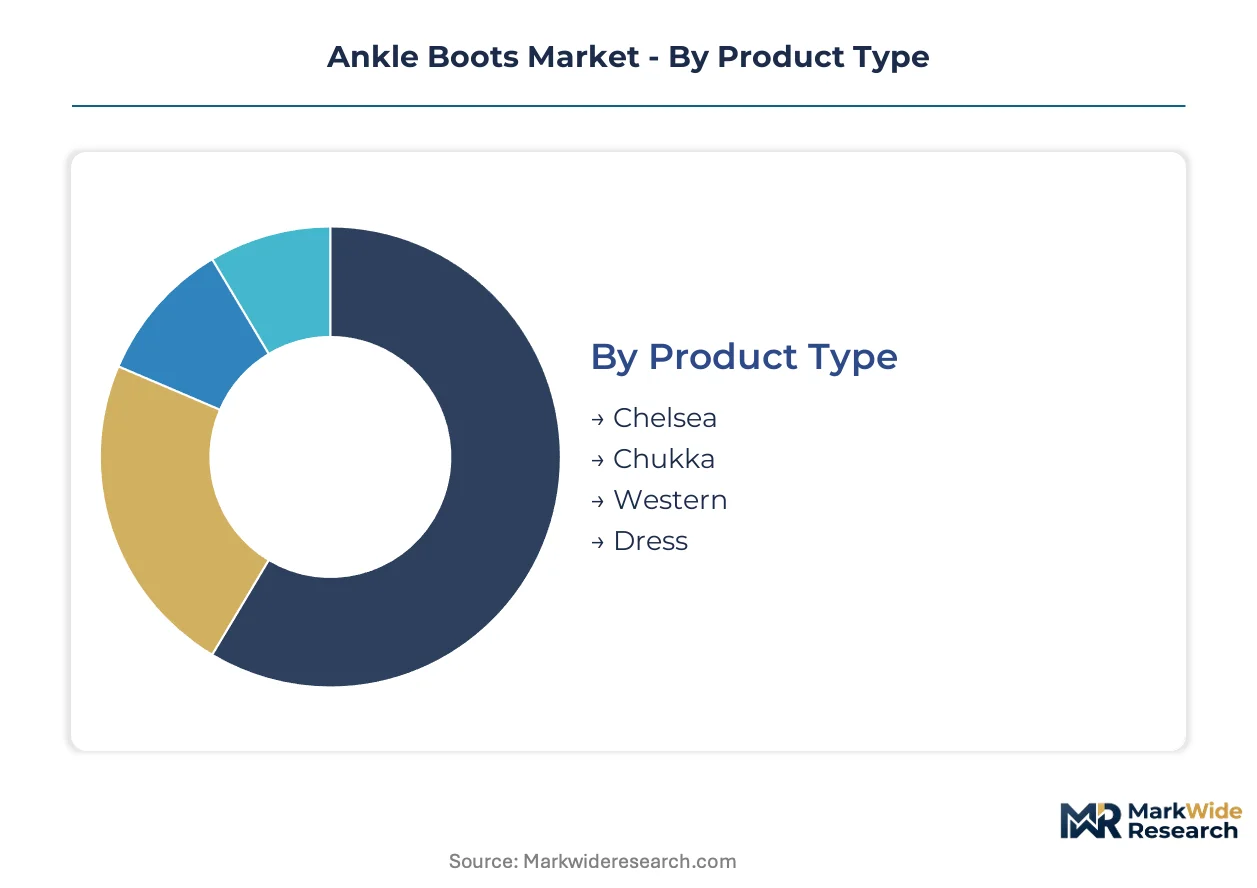
Ankle boots segment across four functional dimensions that shape procurement patterns and margin structures. Buyers prioritize different attributes depending on end-use context, from workplace durability specifications to fashion-forward styling requirements. Understanding these segment boundaries clarifies where premium positioning commands pricing power versus where cost efficiency dominates purchasing decisions.
Product Type:
Workplace versatility and styling flexibility drive product type selection across commercial and consumer channels.
- Chelsea:Elastic-sided construction with pull-tab entry enables rapid donning in occupational settings. Demand concentrates in urban professional segments across London, Milan, and New York where office-casual dress codes blur formal boundaries; ECHA REACH compliance on elastic compounds shapes supplier qualification.
- Western:Stacked heels and decorative stitching serve specialty retail with higher margin capture. Growth accelerates in Texas, Nashville, and Calgary where heritage aesthetics command premium positioning; durability perception limits synthetic substitution despite formulation advances.
- Chukka:Two-eyelet desert boot origins translate to casual versatility with minimal hardware.
- Dress:Sleek lasts and polished finishes target formal occasions with narrower fit tolerances.
Chelsea leads on scale; Western leads on momentum.
Material:
Input costs and regulatory compliance burden determine material selection hierarchies across price tiers.
- Leather:Full-grain and top-grain constructions deliver abrasion resistance and patina development valued in premium positioning. Italian and Spanish tanneries supplying luxury brands accelerate vegetable-tanning investments to satisfy ECHA substance evaluation timelines; hide supply volatility from Argentine and Brazilian sources transmits directly to finished goods pricing.
- Synthetic:Water-based polyurethane coatings achieve abrasion resistance comparable to split leather without chromium VI exposure. Fast-fashion retailers in Germany and the Netherlands adopt these formulations at scale; California Proposition 65 disclosure requirements add documentation overhead that filters through pricing structures.
- Suede:Napped finishes from reverse-side splits offer texture differentiation with lower structural durability.
- Canvas:Woven cotton uppers serve seasonal and budget positioning with minimal weather protection.
Leather dominates revenue concentration; synthetic climbs the fastest on volume expansion.
End User:
Fit specification and styling preference vary sharply across demographic boundaries, requiring dedicated last libraries and marketing channels.
- Women:Fashion-forward silhouettes with heel height variation and decorative hardware drive purchase frequency. Tier-1 Chinese cities—Beijing, Shanghai, Shenzhen—anchor volume expansion as domestic brands localize design studios; modular sole-and-upper systems extend product lifecycle through repairability credentials.
- Men:Durability prioritization and conservative styling reduce replacement frequency while elevating per-purchase spend.
- Unisex:Shared last designs compress inventory complexity for direct-to-consumer specialists.
- Kids:Growth-stage fit tolerance and rapid size turnover constrain premium positioning opportunities.
Women's segment captures highest absolute spend; unisex gains share fastest through channel simplification.
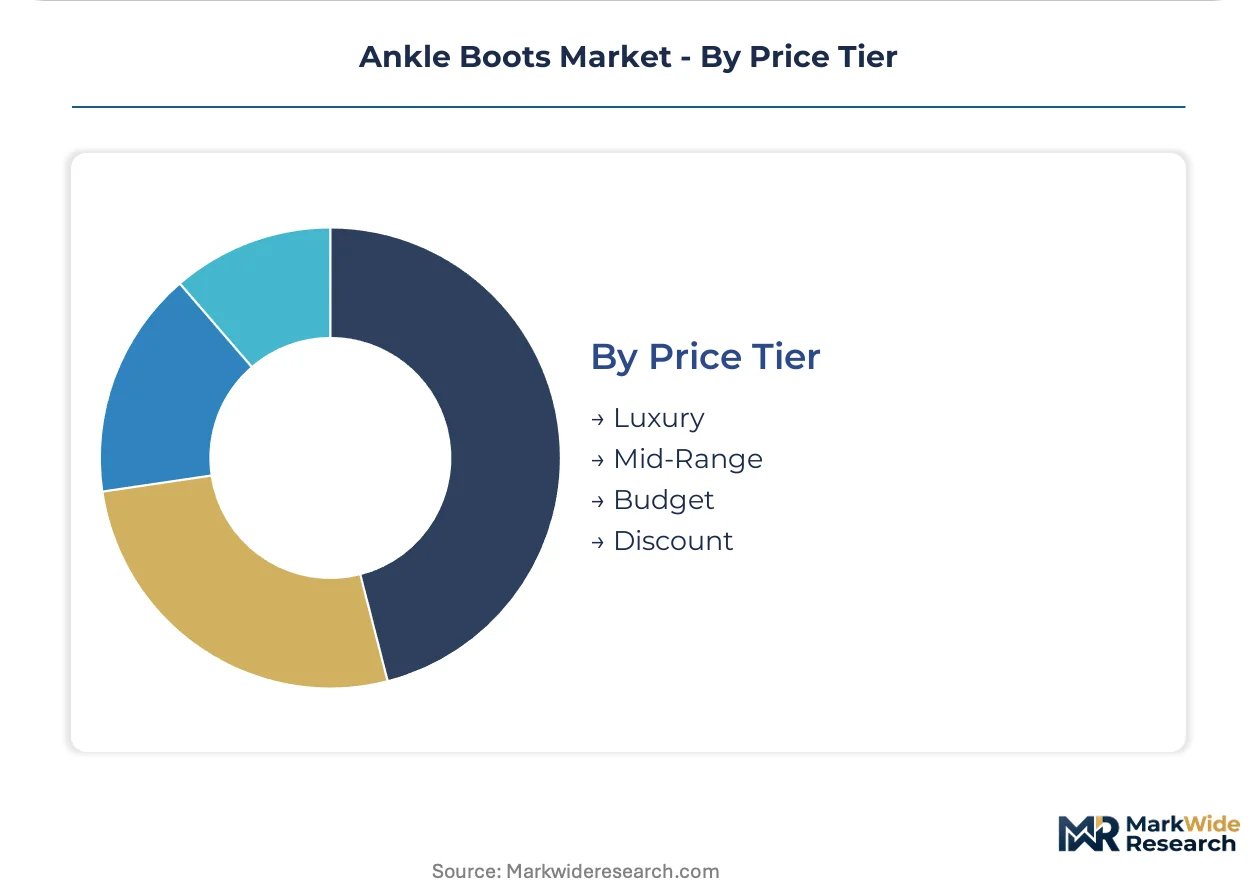
Price Tier:
Certification grade and construction complexity stratify pricing architecture across retail channels.
- Luxury:Hand-finished details, full-grain leather, and resoleable construction justify three-figure price points. Italian manufacturing clusters in Tuscany and Marche supply heritage brands with OEKO-TEX certified inputs; repairability mandates in France and forthcoming EU-wide durability labeling reinforce specification priority.
- Mid-Range:Machine-welted construction with corrected-grain leather balances quality perception against accessibility.
- Budget:Cemented construction and synthetic uppers serve price-sensitive volume with compressed margin buffers.
- Discount:Closeout inventory and off-season liquidation clear excess stock without brand equity dilution.
Luxury commands margin concentration; mid-range shows steepest expansion trajectory through channel upgrade.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ankle boot manufacturing originated in British cobbling traditions of the nineteenth century, with Northamptonshire's leatherworking clusters establishing the technical foundations for durable welted construction. Italian tanneries in Tuscany and Marche subsequently scaled luxury finishing techniques, while Chinese production bases in Guangdong and Zhejiang later absorbed volume manufacturing for global export markets.
United States
Domestic demand concentrates in metropolitan fashion corridors of New York and Los Angeles, where heritage workwear aesthetics command premium positioning. California's Proposition 65 chemical disclosure requirements shape formulation choices for brands distributing through American retail channels. Thursday Boot Co. and Frye Company anchor competitive positioning through direct-to-consumer channel control and heritage manufacturing narratives respectively.
China
Tier-1 cities—Beijing, Shanghai, Shenzhen—drive volume expansion as domestic brands localize design studios for women's fashion-forward silhouettes. The country's national quality regulator enforces GB standards on footwear safety that parallel REACH substance restrictions. Guangdong province's leatherworking clusters are upgrading to full-grain constructions that displace Italian imports in domestic brand supply chains.
United Kingdom
London and Manchester anchor professional demand for Chelsea boot versatility where office-casual dress codes blur formal boundaries. ECHA REACH restrictions on chromium VI in leather tanning compel British-based brands to certify finishing processes with EU-compliant tanneries. Northamptonshire's heritage manufacturing base sustains premium positioning through resoleable construction expertise.
Italy
Tuscany and Marche supply luxury footwear brands with OEKO-TEX certified vegetable-tanned inputs responding to accelerated ECHA substance evaluation timelines. Italian tanneries capture preferential placement with EU-based brands seeking compliant leather alternatives to chromium VI finishes. Milan's fashion retail channels concentrate demand for hand-finished details and narrow fit tolerances.
Germany
Fast-fashion retailers in Berlin and Hamburg adopt water-based polyurethane coatings at scale for autumn-winter synthetic upper lines. ECHA's 2024 substance evaluation wave targeted leather processing aids specifically, forcing documentation of alternative finishing chemistries. Bavaria's industrial safety distributors specify waterproof membrane integration for occupational segments where all-weather performance commands priority.
Ankle Boots Market Competitive Environment
The competitive structure tilts toward heritage specialists with manufacturing lineage rather than pure retail brands. Market concentration remains moderate, with tiered positioning separating luxury resoleable constructions from fast-fashion volume plays. Three archetypes dominate: British heritage manufacturers leveraging Northamptonshire production bases, Italian luxury houses commanding tannery relationships, and direct-to-consumer specialists bypassing wholesale markups. Dominant competitive moves include backward integration into tannery sourcing and modular sole-system development extending product lifecycle.
Among heritage British manufacturers, Dr. Martens and Clarks occupy positions exemplifying durable construction archetypes, while Timberland anchors waterproof technology specialization. Thursday Boot Co. represents the direct-to-consumer channel control model that captures first-party demand data. These three named entities illustrate how manufacturing lineage, technical differentiation, and distribution architecture stratify competitive positioning across price tiers.
| Leading Market Players |
|---|
| Dr. Martens |
| Steve Madden |
| Clarks |
| Timberland |
| Sam Edelman |
| Frye Company |
| Cole Haan |
| Aldo Group Inc. |
| Thursday Boot Co. |
| Others |
Value Chain & Pricing Dynamics
Repairability mandates in France and forthcoming EU-wide durability labeling are forcing buyers to weight total cost-of-ownership metrics over upfront unit pricing, compelling suppliers to document component lifespans and resoleable constructions while compressing margin buffers for cemented alternatives.
Pricing Analysis
Three-tier pricing structure across luxury, mid-range, and budget levels dominates the ankle boots market, with certification grade and construction complexity serving as primary differentiation drivers. Luxury hand-finished constructions with OEKO-TEX certified vegetable-tanned leather command substantial premiums, while budget cemented synthetics face intensifying cost compression from REACH compliance documentation overhead. Fast-fashion retailers exhibit highest price sensitivity, whereas heritage brand loyalists demonstrate lowest elasticity.
Supply Chain Analysis
Direct-to-consumer channels and wholesale distribution networks handle downstream demand, with upstream manufacturing anchored in Italy, Spain, and China's Guangdong province. Full-grain leather hides from Argentina and Brazil, synthetic polyurethane formulations, and waterproof membrane technologies constitute critical input dependencies. Single-source vulnerability concentrates in Italian tannery clusters serving luxury brands, with tariff exposure on Brazilian hides transmitting directly to finished goods pricing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ankle boots market functions as a stable compounder, with women's fashion footwear adoption across urban retail channels providing steady volume expansion irrespective of cyclical pressures.
For Market Incumbents: Lock in tannery relationships with EU-compliant vegetable-tanning capacity to defend against REACH authorization timelines that outpace seasonal product development. Deepen backward integration into full-grain leather sourcing from Guangdong's upgrading clusters to offset Argentine hide volatility and capture domestic Chinese demand growth. For New Entrants and Emerging Players: Enter via modular sole-and-upper systems targeting Scandinavian public procurement channels where repairability credentials command specification priority. White-space concentrates in direct-to-consumer Western styles for Texas and Nashville heritage aesthetic segments, with go-to-market leverage through digital-native storytelling bypassing wholesale markups. For Investors and Strategic Acquirers: Asymmetric upside sits with direct-to-consumer specialists controlling first-party demand data for sizing algorithms and inventory optimization. Long-term viability favors acquisition targets with captive tannery access and documented OEKO-TEX certification, with inflection signal monitoring on ECHA's accelerated substance evaluation schedules forcing industry-wide reformulation cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tannery Sourcing | Captures OEKO-TEX certified vegetable-tanned inputs ahead of REACH chromium VI restrictions. |
| Modular Sole-System Development | Extends product lifecycle through replaceable weather-rated components satisfying French repairability mandates. |
| Direct-to-Consumer Channel Launch | Eliminates wholesale markups while capturing first-party demand data for algorithmic sizing. |
| Domestic Chinese Premium Leather Investment | Displaces Italian imports in domestic brand supply chains as Guangdong clusters upgrade. |
| Water-Based Polyurethane Coating Adoption | Delivers abrasion resistance without chromium VI exposure for German and Dutch fast-fashion lines. |
Study Parameters
Direct dialogue with brand sourcing directors, tannery technical managers, footwear retail category buyers, and regulatory compliance officers grounded the qualitative foundation, cross-referenced with customs trade records, ECHA substance evaluation databases, SEC footwear sector filings, and Circana retail audit data. Bottom-up manufacturer interviews and top-down channel revenue estimates underwent iterative triangulation to reconcile volume and value figures.
Bottom-up modeling aggregated manufacturer shipment data by product type, material grade, end-user demographic, and price tier across the projection horizon, while top-down analysis validated totals against regional consumption patterns. CAGRs derived from segment-level growth trajectories incorporated leather input cost indices, REACH compliance timeline assumptions, and urban retail floor space expansion rates in Tier-1 Chinese cities.
Inputs from tannery certification databases and retail point-of-sale systems were available through the study window; gaps in proprietary brand margin structures introduce uncertainty bands around mid-range segment forecasts. Periodic stress-testing of base assumptions is recommended against ECHA substance evaluation acceleration and Argentine hide supply volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Middle East and Africa E-Commerce Footwear Market
Footwear
Breathable Mesh Running Shoes Market
Footwear
PVC Footwear Market
Footwear
Driving Footwear Market
Footwear
Desert Boots Market
Footwear
Dance Shoes Market
Footwear
Europe Barefoot Shoes Market
Footwear
Leather Sneakers Market
Footwear
UK Lifestyle Sneakers Market
Footwear
US Slip Resistant Shoes Market
Footwear
PU Sole (Footwear Polyurethane) Market
Footwear
Global Espadrille Flats Market
Footwear
Trail Running Shoes Market
Footwear
North America Footwear Market
Footwear
Sustainable Footwear Market
Footwear
Barefoot Shoes Market