
 Casual Shoes Market | 2026-2036
Casual Shoes Market Size, Share, and Industry Trends Forecast 2026-2036
Casual Shoes Market Analysis
A capital-intensity divergence between automated manufacturing investments and artisanal craft capabilities is reorganizing competitive hierarchies in casual footwear. Nike leverages vertical integration in synthetic upper production to control cost structures across volume tiers. Adidas anchors its position through R&D intensity in bio-based midsole formulations. New Balance sustains geographic dominance in North American domestic manufacturing.
Casual shoes are everyday non-athletic footwear constructed from leather, canvas, synthetic textiles, or rubber compounds, designed for comfort and versatility across social and semi-formal settings. Manufacturing processes span cemented construction for price-accessible tiers and stitch-down or Goodyear welting for durability-focused segments. The sneakers category leads volume globally while commanding narrowing margin pools amid saturation. Premium leather loafers occupy concentrated margin pools where small-batch Italian and Portuguese workshops maintain pricing power. Synthetic slip-ons represent the fastest-growing material-format intersection, driven by vegan leather formulations and injection-molded unit economics.
REACH restrictions on chromium VI in leather tanning reshape European supply chains, while the US Consumer Product Safety Commission enforces phthalate limits in children's casual footwear. China's GB standards for footwear safety and the EU's pending Digital Product Passport requirements will compound compliance burdens for multi-region suppliers. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and certification gaps.
Market Dynamics
REACH chemical safety standards in Europe and state-level consumer protection laws in the United States are tightening material disclosure requirements, forcing manufacturers to reconfigure supply chains and accelerate alternative material validation programs.
Growth Catalysts
- Urban professional wardrobe hybridization:Young adult urban professionals are expanding purchases of versatile casual footwear that transitions between office and social settings, compressing the traditional formal-casual footwear boundary.
- GB standards compliance infrastructure:China's GB standards for footwear safety have matured domestic testing capabilities, enabling faster local certification for brands entering tier-one cities.
- Bio-based midsole R&D pipelines:Laboratory-scale breakthroughs in plant-derived foam formulations are migrating to pilot production, reducing petroleum dependency in comfort-critical components.
Market Restraints
- Chromium VI tanning phase-out costs:REACH restrictions on chromium VI in leather tanning are forcing European tanneries to absorb capital-intensive process conversions or exit the supply base.
- Phthalate compliance fragmentation:The US Consumer Product Safety Commission enforces phthalate limits in children's casual footwear that diverge from EU thresholds, creating dual-certification burdens for multi-region suppliers.
- Synthetic upper supply concentration:Automated manufacturing investments in synthetic textile production have consolidated around a narrow supplier base in East Asia, amplifying disruption risk.
Strategic Opportunities
- Digital Product Passport readiness:The EU's pending Digital Product Passport requirements will reward early movers who build material traceability infrastructure, creating certification gaps for laggards.
- Vegan leather formulation scale-up:Injection-molded unit economics for plant-derived polymers are approaching cost parity with conventional synthetics in the slip-on category.
- Artisanal craft capability scarcity:Small-batch Italian and Portuguese workshops maintain pricing power in premium leather loafers, presenting acquisition targets for brands seeking margin pool access.
Industry Challenges
- Dual carbon goals alignment:China's MEE enforcement of dual carbon goals is accelerating energy audits for footwear manufacturers, compressing timelines for facility retrofits.
- Cross-jurisdiction certification gaps:Stranded inventory risk mounts as regulatory divergence between REACH, GB standards, and US state-level disclosure laws outpaces harmonization efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Casual Shoes Market |
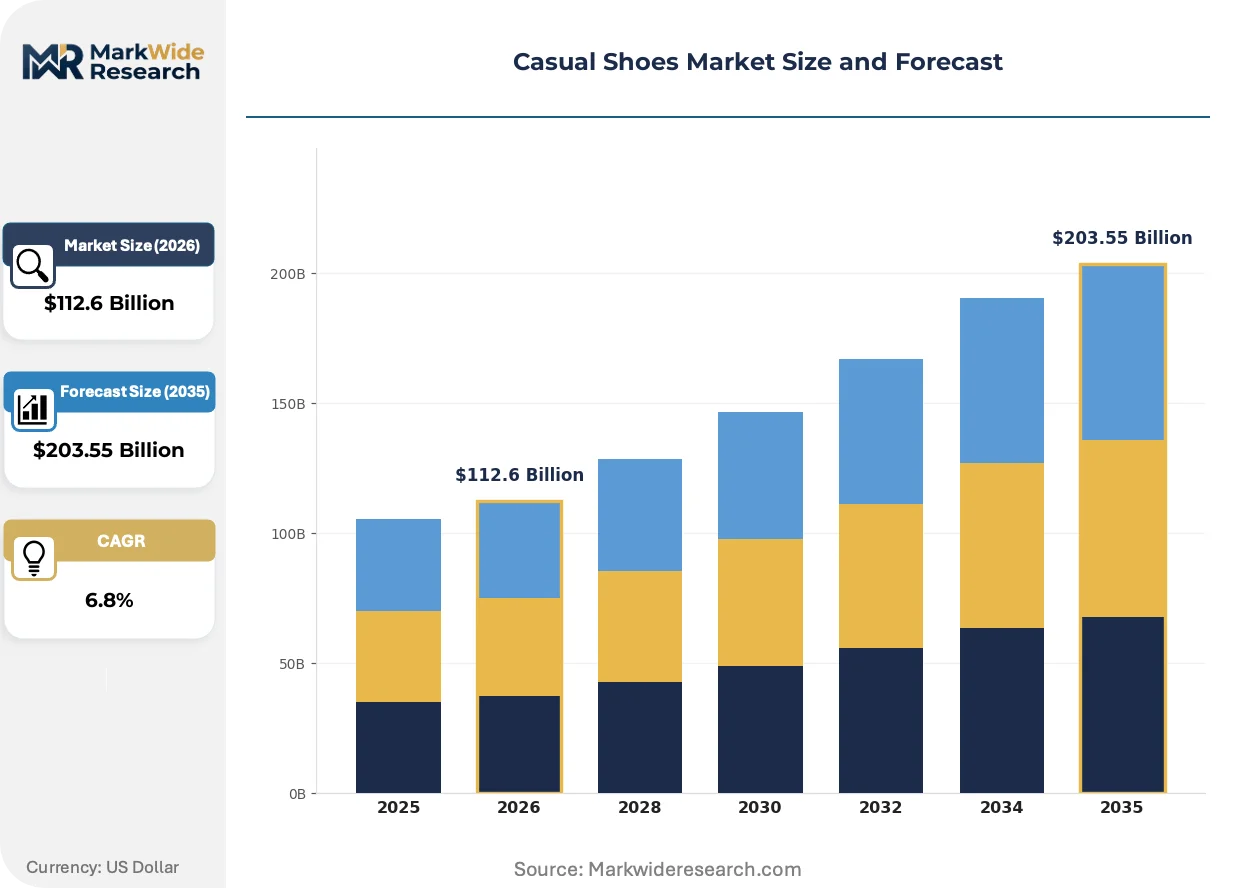
| Market Size in 2026 | $112.6 Billion |
| Market Size in 2035 | $203.55 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Sneakers, Loafers, Sandals, Slip-Ons Material: Leather, Canvas, Synthetic, Rubber End User: Men, Women, Kids, Unisex Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | New Balance, Flux Footwear, Nike, Duke & Dexter, Greats, Adidas, Monrow Shoes, Blackstock & Weber, Skechers USA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Casual Shoes Market Emerging Trajectories
Material science breakthroughs and regulatory disclosure mandates are converging to reshape how casual footwear is designed, sourced, and brought to market across price tiers.
Plant-derived polyurethane foam is decomposing the petroleum-dependent midsole supply chain by delivering equivalent energy return with lower density variance. Performance-oriented brands are adopting these formulations for lifestyle silhouettes previously reserved for petroleum foams. The technology is decomposing cost structures in the $80-$150 retail tier where material differentiation drives purchase decisions.
ECHA's expansion of REACH candidate list substances is accelerating substitution research across European supply chains. Tanneries and textile finishers must now document SVHC content above 0.1% w/w, pushing compliance costs toward smaller suppliers. Children's casual footwear faces the steepest testing burden as phthalate, bisphenol, and flame retardant screening intensifies ahead of 2025 enforcement windows.
Direct-to-consumer channel maturation is compressing wholesale dependency for mid-tier brands. Urban professionals in Shanghai, Berlin, and New York are purchasing through brand-owned digital storefronts that offer customization tools and transparent material sourcing data. This shift is most visible in the sneaker category where margin pressure from wholesale discounting has eroded profitability for volume-dependent players.
Casual Shoes Market Segmentation
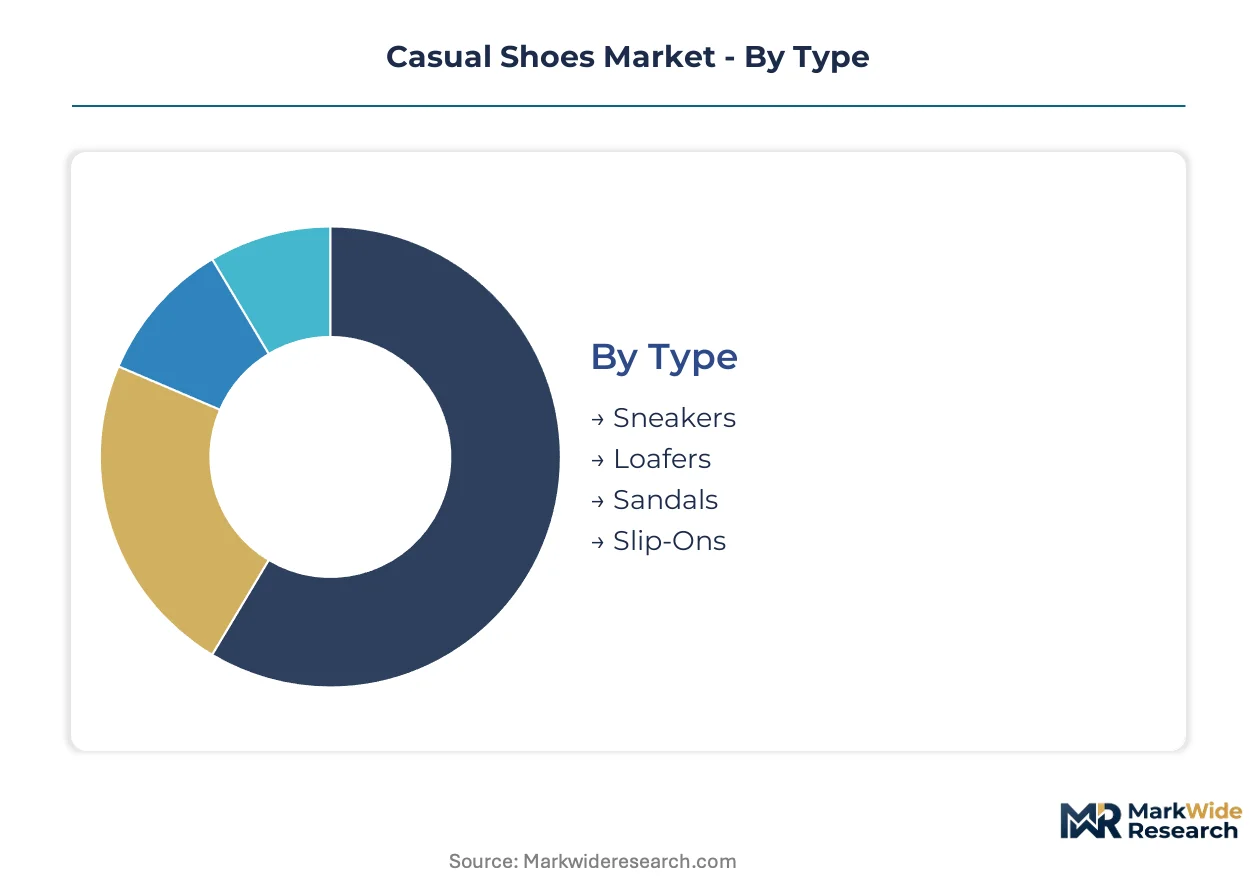
Casual footwear segmentation reveals how material chemistry, construction methods, and end-use requirements fragment demand across compliance regimes. Each dimension carries distinct regulatory exposure and margin architecture.
Type:
REACH substance restrictions and GB safety standards apply differentially based on construction complexity and intended use environment.
- Sneakers:Cemented or vulcanized rubber outsoles with mesh, knit, or synthetic uppers dominate volume. Demand concentrates in Chinese tier-one cities where young professionals prioritize office-to-gym versatility; phthalate screening intensifies for children's variants under US Consumer Product Safety Commission enforcement.
- Loafers:Slip-on leather construction spans cemented, Blake-stitched, and Goodyear-welted methods. Italian and Portuguese workshops command pricing power in hand-finished tiers; ECHA's chromium VI limits force tannery requalification for European supply.
- Sandals:Open-heel designs using rubber compounds or plant-based polymers. India's BIS certification and Brazil's ANVISA requirements shape import eligibility.
- Slip-Ons:Injection-molded unit economics enable rapid vegan leather formulation scale-up. Fastest adoption trajectory among plant-derived polymer categories.
Established volume favors sneakers; emerging adoption favors slip-ons.
Material:
Cost tier and certification burden diverge sharply across feedstock origins and processing chemistry.
- Leather:Chrome-tanned, vegetable-tanned, and synthetic-tanned variants. REACH chromium VI phase-out costs burden European tanneries; Italian suppliers absorb capital-intensive process conversions while maintaining premium positioning.
- Synthetic:Polyurethane, polyester, and recycled PET textiles. Automated manufacturing concentrates in East Asian supplier bases; dual carbon goals enforcement by China's MEE accelerates facility energy audits.
- Canvas:Cotton or hemp woven uppers with rubber foxing. Portugal and Vietnam maintain craft-scale production for heritage brands.
- Rubber:Natural latex or petroleum-derived compounds for outsoles and unitary construction. Malaysia and Thailand supply natural rubber feedstock; synthetic variants face petroleum dependency scrutiny.
Synthetic materials scale fastest; leather retains margin concentration.
End User:
Demographic targeting determines testing protocols, sizing complexity, and channel strategy.
- Men:Sizing standardization enables automated production; business casual hybridization drives loafer and minimalist sneaker demand in Shanghai, Berlin, and New York.
- Women:Expanded size runs and seasonal color rotation increase SKU complexity. Direct-to-consumer customization tools capture urban professional spend.
- Kids:Phthalate, bisphenol, and flame retardant screening intensifies under US Consumer Product Safety Commission and EU REACH children's product enforcement.
- Unisex:Simplified size matrices reduce inventory risk; gender-neutral positioning aligns with sustainability-transparent marketing in European markets.
Men's segment anchors volume scale; unisex positioning gains share fastest.
Price Tier:
Margin architecture separates by material provenance, labor intensity, and certification depth.
- Budget:Cemented construction with synthetic uppers and injection-molded outsoles. Volume concentrates in mass retail and marketplace channels; margin compression from wholesale dependency erodes profitability.
- Mid-Range:Mixed material construction with limited traceability claims. Bio-based midsole R&D pipelines migrate to this tier first as plant-derived foam costs approach petroleum parity.
- Premium:Full-grain leather or advanced synthetic textiles with documented supply chains. EU Digital Product Passport readiness rewards early movers with certification gaps for competitors.
- Luxury:Hand-finished construction from named tanneries and workshops. Small-batch Italian and Portuguese producers maintain scarcity pricing; acquisition targets for brands seeking margin pool access.
Budget tier captures volume velocity; luxury tier captures margin concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across major demand centers. German and Italian buyers absorb premium leather craftsmanship costs with minimal volume contraction, while Indian and Southeast Asian markets compress margins on synthetic entry-level tiers.
United States
Urban professionals in New York and Los Angeles drive demand for office-to-gym hybrid silhouettes. The US Consumer Product Safety Commission enforces phthalate limits in children's casual footwear, intensifying testing burdens for multi-category suppliers. Portland, Oregon anchors domestic manufacturing clusters where heritage brands maintain stitch-down production capabilities.
China
Young adult consumers in Shanghai and Beijing prioritize versatile casual footwear for social-to-professional transitions. The Ministry of Ecology and Environment enforces dual carbon goals through facility energy audits, compressing retrofit timelines for manufacturers. The Pearl River Delta concentrates synthetic upper production where automated textile investments have consolidated supplier bases.
Germany
REACH candidate list expansions by ECHA accelerate substitution research across chemical supply chains. Berlin and Munich consumers demonstrate strong price tolerance for documented sustainable materials. Bavarian tanneries absorb capital-intensive chromium VI phase-out costs while maintaining premium positioning in European supply networks.
Italy
Hand-finished leather loafer demand concentrates among affluent buyers in Milan and Florence. ECHA documentation requirements for SVHC content above 0.1% w/w push compliance costs toward smaller finishers. The Marche region hosts small-batch workshops where artisanal scarcity sustains pricing power in luxury tiers.
India
BIS certification requirements shape import eligibility for rubber and canvas constructions entering Mumbai and Delhi markets. Price-sensitive volume concentrates in mass retail channels where cemented synthetic constructions dominate. Tamil Nadu and Uttar Pradesh host domestic manufacturing clusters serving budget-tier distribution networks.
Casual Shoes Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in casual footwear manufacturing. Nike and Adidas control upstream synthetic material production and bio-based formulation pipelines respectively, while regional artisans occupy narrow premium niches. Three archetypes dominate: vertically integrated volume players, R&D-intensive material innovators, and craft-scale heritage specialists. Competitive moves concentrate on supply chain control and certification infrastructure rather than price warfare.
Among US-based heritage manufacturers, New Balance anchors domestic production capabilities that bypass Asian supply concentration. Nike exemplifies the integrated volume archetype through captive synthetic upper production. Adidas occupies the material innovation tier with pilot-scale bio-based midsole deployment. These three companies represent the structural divergence between automated scale and craft capability that defines competitive positioning.
| Leading Market Players |
|---|
| New Balance |
| Flux Footwear |
| Nike |
| Duke & Dexter |
| Greats |
| Adidas |
| Monrow Shoes |
| Blackstock & Weber |
| Skechers USA |
| Others |
Supply Flow & Price Mechanics
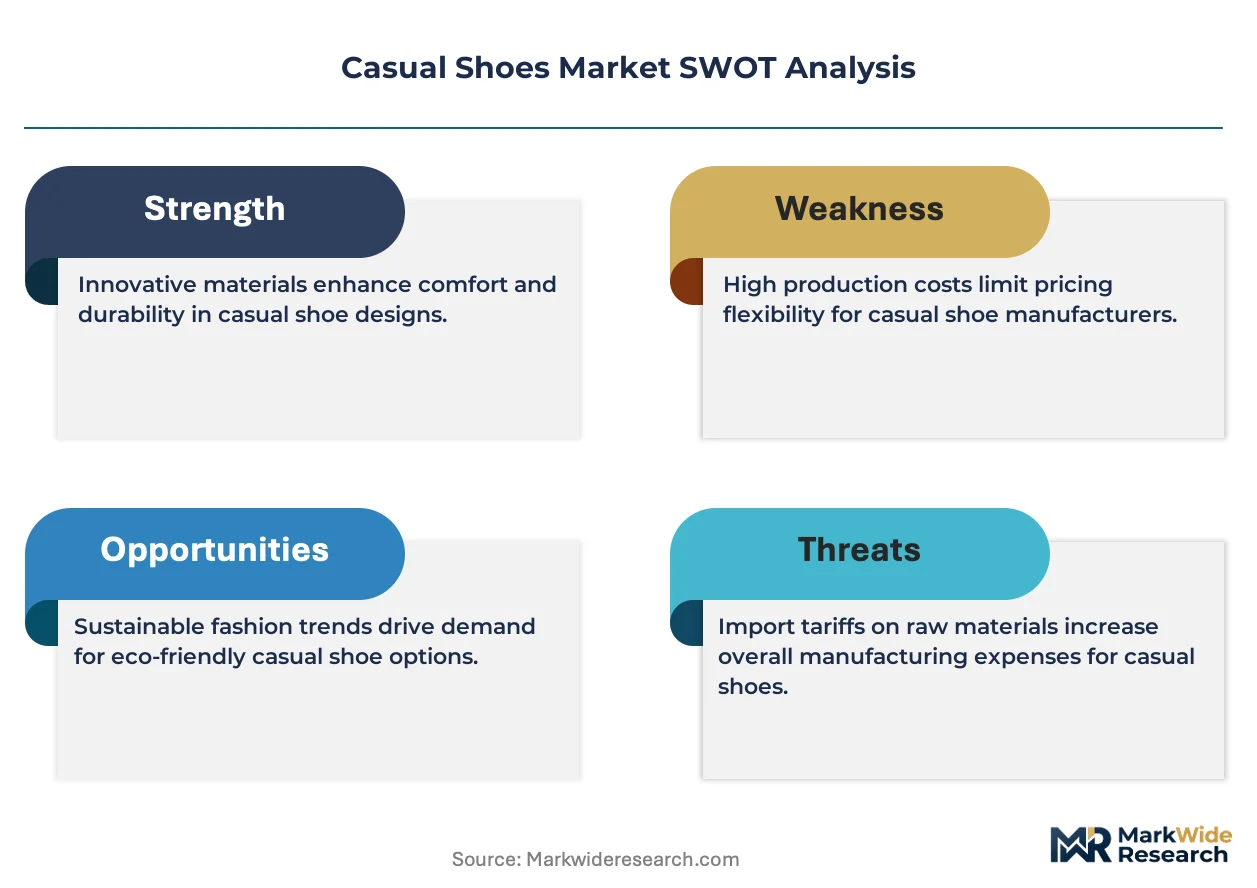
ECHA's REACH candidate list expansion gates both supplier qualification and price differentiation simultaneously, forcing tanneries and textile finishers to absorb documentation costs that separate certified from uncertified tiers while compressing margins on volume-dependent synthetic constructions.
Pricing Analysis
After-sales service revenue from resoling, refurbishment, and extended care programs drives lifetime value in leather constructions. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification depth and construction method. Cost compression in the budget tier intensifies because wholesale dependency erodes profitability. Mass retail buyers exhibit highest price sensitivity; luxury workshop customers demonstrate minimal elasticity.
Supply Chain Analysis
China, Vietnam, and Portugal anchor global casual footwear manufacturing across distinct capability tiers. China concentrates synthetic upper production and automated textile investments. Vietnam scales cemented construction for mid-range export volumes. Portugal sustains craft-scale heritage production for premium leather segments. Raw material flows draw from Malaysian natural rubber plantations, Italian tanneries navigating chromium VI phase-outs, and East Asian petroleum-derived polymer suppliers. Single-source vulnerability concentrates in synthetic textile feedstocks where automated production consolidated around narrow supplier bases. Distribution runs through brand-owned direct-to-consumer storefronts, wholesale retail partnerships, and marketplace platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery pattern as post-pandemic wardrobe replenishment cycles normalize and urban professional return-to-office policies stabilize hybrid footwear demand.
For Market Incumbents: Shield market position by accelerating bio-based midsole R&D pipelines before plant-derived foam costs reach parity, and deepen backward integration into captive synthetic upper production to offset East Asian supplier concentration risk. Prioritize Digital Product Passport infrastructure investment to create certification gaps for competitors lagging on material traceability. For New Entrants and Emerging Players: Customization and transparent material sourcing data represent service-layer gaps where established volume players under-serve urban professionals in Shanghai, Berlin, and New York. Target the unisex segment with simplified size matrices and sustainability-transparent marketing. Deploy direct-to-consumer digital storefronts with configuration tools as the primary go-to-market angle. For Investors and Strategic Acquirers: The EU's pending Digital Product Passport requirements reshape the acquisition landscape by rewarding early movers with material traceability infrastructure. Five-to-ten-year viability favors brands with demonstrated compliance capability across REACH, GB standards, and US state-level disclosure laws. Target acquisition archetype: small-batch Italian and Portuguese workshops with artisanal scarcity pricing power. Monitor ECHA enforcement windows as the signal indicating regulatory inflection timing.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Based Midsole Scale-Up | Plant-derived polyurethane foam pilot production reduces petroleum dependency in comfort-critical components. |
| Digital Product Passport Infrastructure | Material traceability systems reward early movers ahead of EU documentation mandates. |
| Artisanal Workshop Acquisition | Small-batch Italian and Portuguese producers maintain scarcity pricing in premium leather tiers. |
| Direct-to-Consumer Channel Expansion | Brand-owned digital storefronts with customization tools capture urban professional spend in tier-one cities. |
| Chromium VI Tanning Process Conversion | European tanneries absorb capital-intensive REACH compliance to maintain supply network positioning. |
Methodological Framework
A spread of perspectives from brand managers, category buyers at multi-brand retailers, supply planners, and channel sales heads converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against customs records, SEC 10-K filings, and retail audit data from Nielsen and Circana. Bottom-up volume modeling and top-down value triangulation cross-checked segment-level outputs.
Segmentation dimensions modeled include material chemistry, construction method, end-use requirements, price tier, and regional regulatory cluster across the analysis window. CAGRs derived from historical trajectory analysis and forward-looking input cost assumptions. Industry-specific forecast inputs incorporated dual carbon goals enforcement timelines and REACH candidate list expansion schedules.
Underlying assumptions cover normalized wardrobe replenishment cycles and stable urban professional employment patterns, with deviation risk concentrated in regulatory enforcement timing and synthetic feedstock price volatility. Recalibration cycles align with material shifts in ECHA substance restrictions and China's MEE energy audit implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Cyber-Shoes Market
Footwear
Sports Shoes Market
Footwear
Dance Shoes Market
Footwear
Europe Barefoot Shoes Market
Footwear
Sports Footwear Market
Footwear
Sandals Market
Footwear
Europe Athletic Footwear Market
Footwear
Global Footwear Market
Footwear
Custom Shoes Market
Footwear
Equestrian Footwear Market
Footwear
Europe Footwear Market
Footwear
Middle East and Africa E-Commerce Footwear Market
Footwear
Shoe Insoles Market
Footwear
Sneaker Identification Service Market
Footwear
White Sneakers Market
Footwear
Self-Lacing Shoes Market