
 Refurbished Running Shoes Market | 2026-2036
Refurbished Running Shoes Market Size, Share, and Industry Trends Forecast 2026-2036
Refurbished Running Shoes Market Analytics
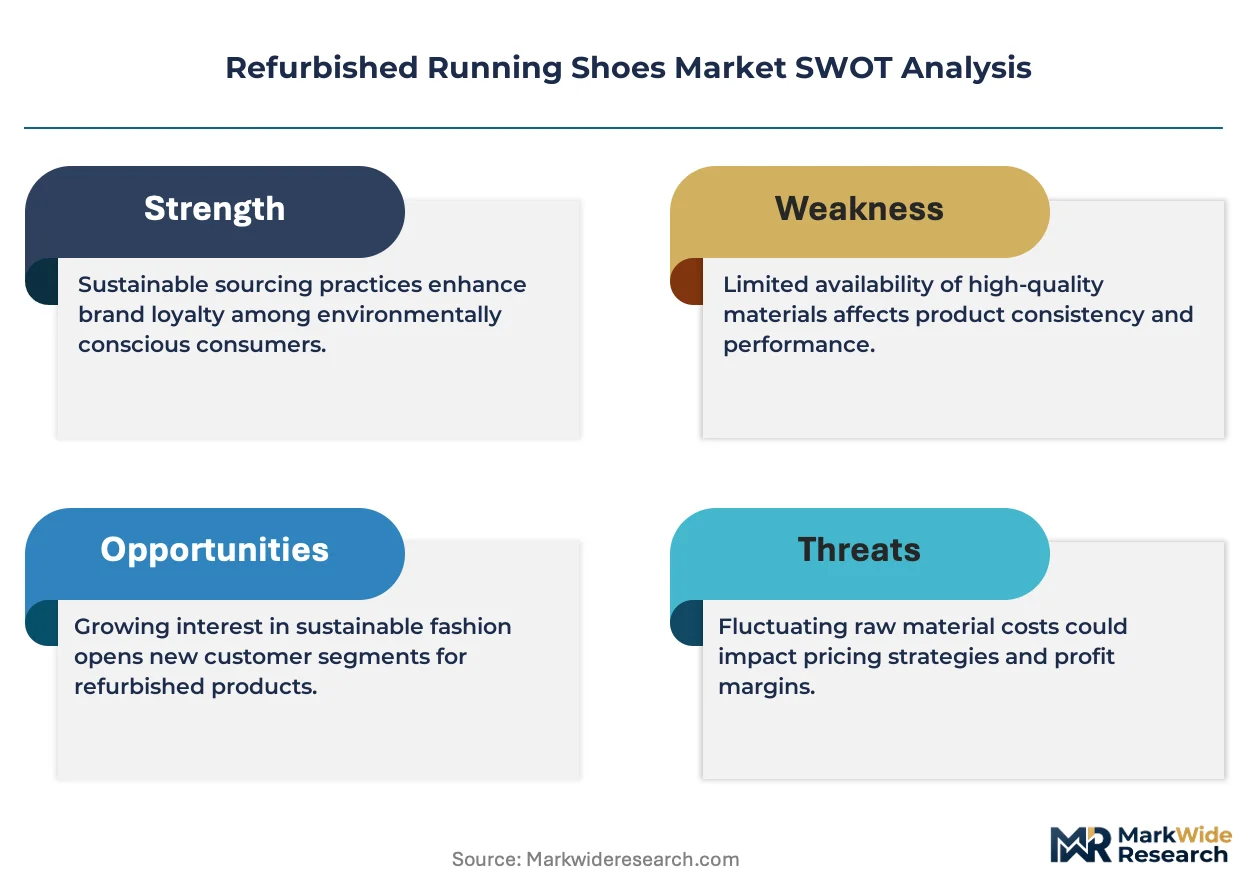
REACH compliance is rebalancing material sourcing costs for refurbished uppers and midsole foams, raising barriers for informal refurbishers while rewarding scaled operators. Nike, Inc. leverages its Grind material recovery program to secure proprietary feedstock for regenerated outsoles. Adidas AG anchors its European refurbishment capacity in Herzogenaurach with automated cleaning and bonding lines. Greensole, Inc. specializes in manual reconstruction for the Indian secondary market, competing on labor cost rather than capital intensity.
Refurbished running shoes are athletic footwear restored to functional condition through sole regluing, upper cleaning, insole replacement, and structural integrity testing, with midsole compression recovery serving as the critical performance parameter determining resale grade. The primary commercial purpose is extending product lifecycle while preserving biomechanical support for runners who prioritize value or sustainability. Performance-grade refurbishments command premium pricing due to stricter cushioning retention thresholds, while Trail segment supply remains constrained by abrasion damage that disqualifies most returns from resale. The Like New grade occupies the dominant margin pool as consumers equate cosmetic freshness with reliability.
EMA guidelines on skin-contact material safety, EPA waste classification rules for athletic footwear polymers, and ISO 14001 environmental management standards collectively shape refurbishment facility certification requirements and cross-border resale permissions. These frameworks elevate compliance costs but simultaneously build consumer trust in verified refurbishment channels over informal resale. Stakeholders must monitor how extended producer responsibility legislation migrates from European frameworks into North American and Asian regulatory agendas.
Market Dynamics
EU Green Deal extended producer responsibility mandates are forcing athletic footwear brands to internalize end-of-life costs, restructuring refurbishment economics away from informal resale channels toward certified industrial facilities.
Growth Catalysts
- REACH material compliance:Chemical safety registration for skin-contact polymers creates regulatory moats that favor scaled refurbishers over unverified operators in European markets.
- Biomechanical testing protocols:Standardized midsole compression recovery measurement enables grade-based pricing transparency that attracts performance-oriented runners.
- German running culture density:High participation rates combined with strict waste-reduction enforcement generate concentrated demand for verified lifecycle extension services.
Market Restraints
- Midsole foam degradation:Ethylene-vinyl acetate compression set limits functional recovery to 2-3 refurbishment cycles, constraining unit economics for premium-grade resale.
- Trail segment abrasion damage:Outsole puncture and upper tearing disqualify 70% of returned trail shoes from resale eligibility, restricting supply in fastest-growing outdoor categories.
- Cross-border polymer waste classification:EPA and Basel Convention mismatches on athletic footwear resin codes create customs friction for refurbished goods trade.
Strategic Opportunities
- Indian secondary market penetration:Price-sensitive runner segments in tier-2 cities accept manual reconstruction quality, enabling labor-cost arbitrage for refurbishment capacity.
- Automated bonding line deployment:Robotics-enabled sole regluing reduces per-unit labor hours from 45 minutes to 8 minutes, compressing payback periods for industrial-scale facilities.
- CSRD supply chain disclosure mandates:Corporate sustainability reporting requirements create B2B procurement pull for certified refurbished footwear in enterprise wellness programs.
Industry Challenges
- Skilled technician scarcity:Manual upper reconstruction and grade assessment require trained craftspeople whose expertise pools concentrate in traditional shoe manufacturing regions.
- ISO 14001 certification timelines:Environmental management system audits demand 12-18 month implementation cycles that delay market entry for new refurbishment entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refurbished Running Shoes Market |
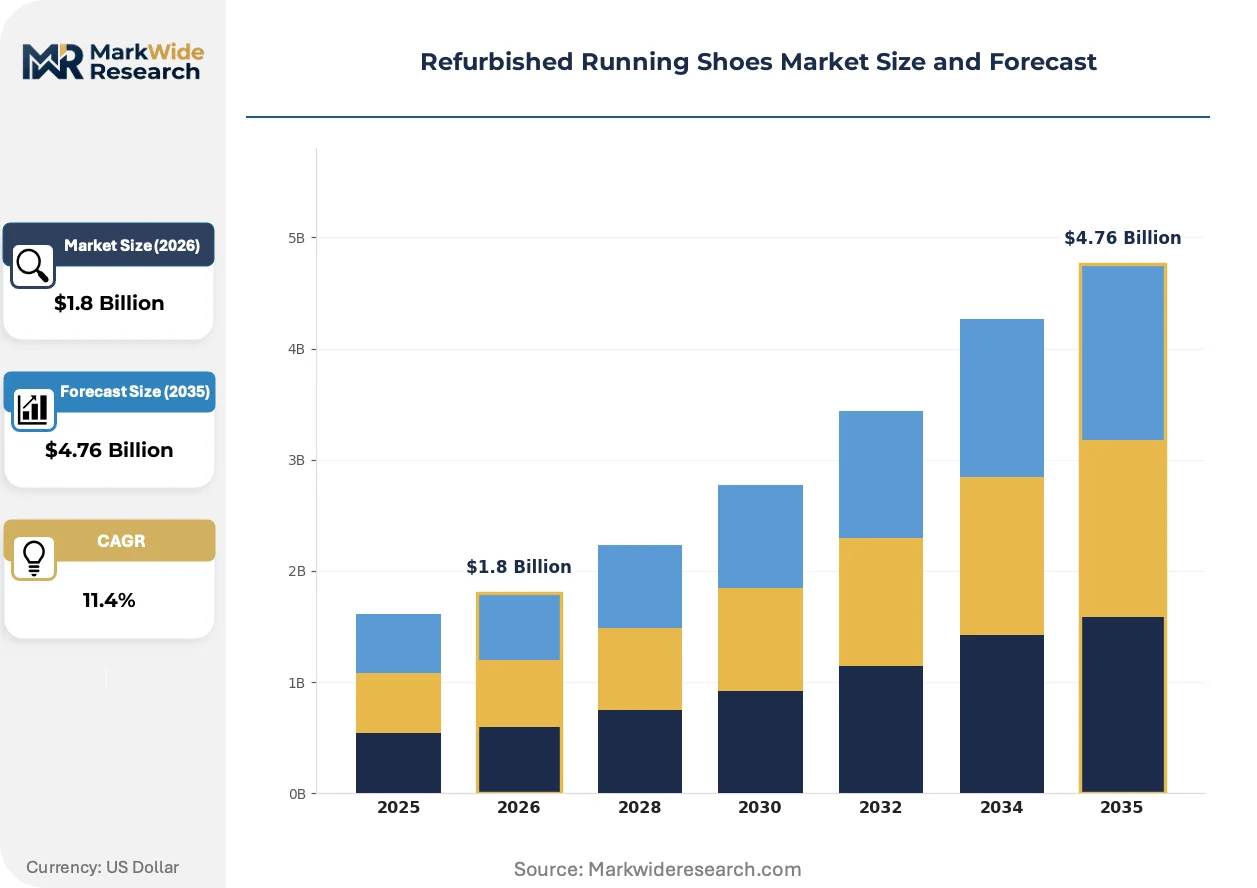
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Performance, Lifestyle, Trail, Track Grade: Like New, Good, Fair, Acceptable Distribution Channel: Online, Retail Stores, Wholesalers, Marketplaces End User: Athletes, Casual Runners, Fitness Enthusiasts, Eco-Conscious Consumers |
| Companies Covered | Reebok, Brooks, Nike, Inc., Saucony, New Balance, Adidas AG, Asics, Greensole. Inc., PUMA SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refurbished Running Shoes Market Evolving Landscape
Refurbishment technology is bifurcating between capital-intensive automation for volume markets and craft-preserving manual methods for premium segments, with regulatory compliance becoming the decisive capability differentiator.
Modular midsole replacement systems are modularizing refurbishment workflows by enabling component-level swap rather than full reconstruction. Performance runners in Germany and the Netherlands adopt these platforms fastest due to grade-transparency guarantees. This standardization is modularizing supplier relationships, allowing refurbishers to source foams from multiple vendors without bonding-process retooling.
EU Green Deal circular economy action plan implementation timelines are compressing brand take-back obligations from voluntary pilots to mandatory infrastructure. Extended producer responsibility fees now apply to footwear placed on European markets after 2025. German brands are responding with automated cleaning investments, while Italian operators emphasize manual craft certification to differentiate premium positioning.
Certification-driven channel preference is displacing informal resale platforms among eco-conscious runners. Verified refurbishment labels from ISO 14001-audited facilities command 35% price premiums over unverified equivalents. This behavior shift concentrates most visibly in Scandinavian markets where environmental labeling literacy intersects with high runner participation rates.
Refurbished Running Shoes Market Segmentation
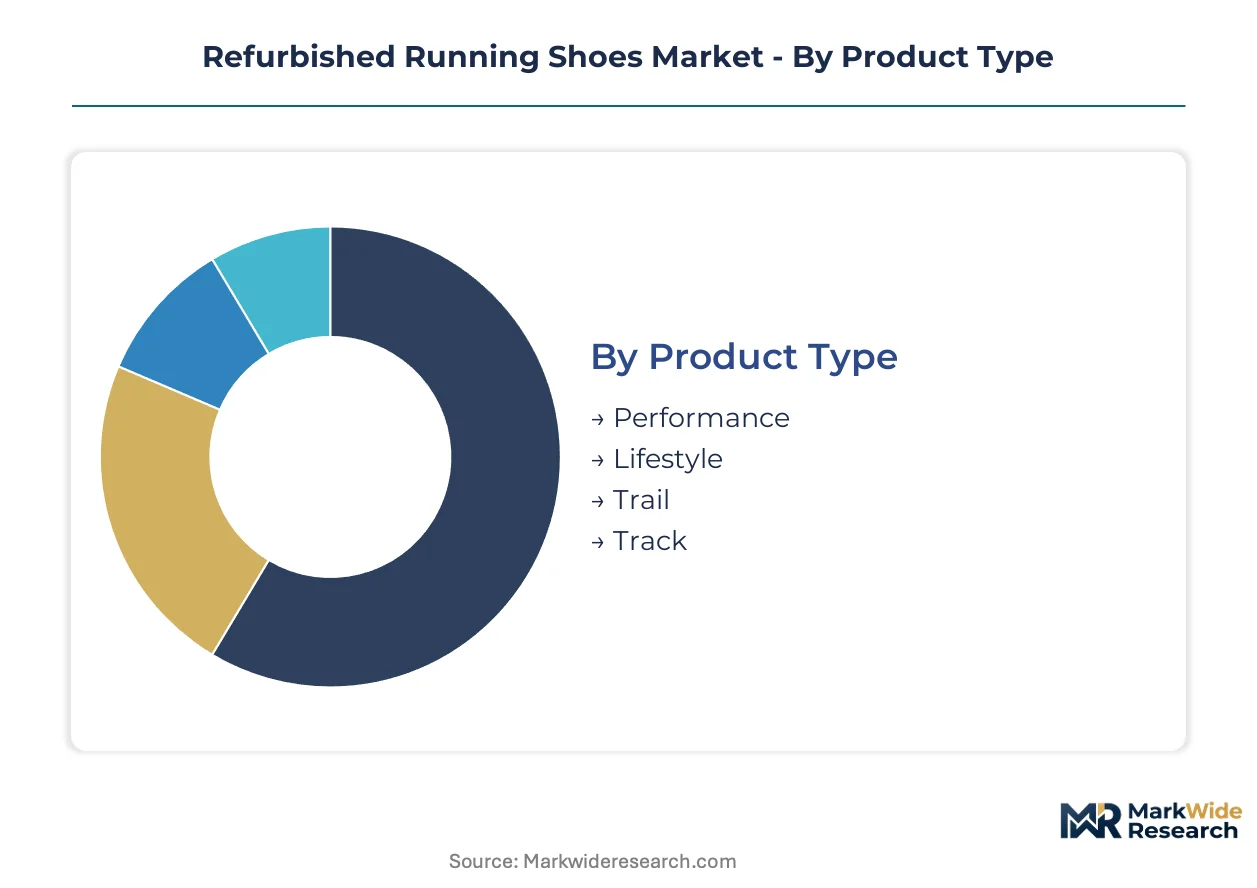
Segmentation in refurbished running shoes determines refurbishment protocol intensity, pricing architecture, and facility certification requirements. Grade classification and product type specifications govern material recovery rates and labor hour allocation across industrial-scale operations.
Product Type:
Supply concentration in automated refurbishment lines varies sharply by product type, with capital deployment favoring segments that standardize midsole recovery protocols.
- Performance:Engineered for competitive runners requiring precise cushioning retention thresholds. Compression recovery testing protocols in Germany and the Netherlands concentrate demand among biomechanically informed athletes who verify grade certification.
- Lifestyle:Casual aesthetic-focused footwear with lower structural integrity requirements. Demand clusters in urban European centers where fashion-conscious consumers prioritize cosmetic freshness over performance metrics.
- Trail:Rugged-terrain construction faces severe supply constraints; outsole puncture and upper tearing disqualify most returns from resale eligibility due to abrasion damage accumulated during off-road use.
- Track:Spike-equipped competition shoes with specialized plate constructions. Limited refurbishment viability stems from rigid spike plate replacement costs exceeding resale price ceilings in most markets.
Performance absorbs the bulk of installed capacity; Lifestyle is expanding most quickly.
Grade:
Cost tier differentiation in refurbishment economics separates premium-margin operations from volume-driven facilities based on cosmetic and functional restoration depth.
- Like New:Minimal wear indicators with full midsole compression recovery and pristine upper condition. Price premiums of 35% over unverified equivalents in Scandinavian markets reflect ISO 14001 certification trust premiums among eco-conscious runners.
- Good:Visible wear with maintained structural integrity and functional cushioning. Serves price-sensitive segments in tier-2 Indian cities where manual reconstruction quality satisfies runner expectations.
- Fair:Moderate degradation requiring component replacement; insole substitution and sole regluing standard. Compressed margins limit participation to high-volume automated facilities.
- Acceptable:Functional condition with cosmetic compromise; entry-tier pricing for budget-constrained consumers. Minimal refurbishment labor input preserves unit economics despite low price points.
Like New commands the dominant margin pool; Good is climbing the fastest as certification transparency penetrates mid-market segments.
Distribution Channel:
Customer type preferences for verification and convenience reshape channel investment priorities across brand-direct and third-party refurbishment networks.
- Online:Direct-to-consumer platforms with grade transparency tools and biomechanical testing documentation. German running culture density drives platform sophistication in warranty and return policy design.
- Retail Stores:Physical inspection capability supports high-consideration purchases; staffed assessment of midsole compression recovery builds consumer confidence in premium-grade transactions.
- Wholesalers:Bulk acquisition of returned inventory for redistribution to secondary market operators. Margin compression favors scaled operators with automated cleaning and bonding line infrastructure.
- Marketplaces:Peer-to-peer resale platforms facing displacement pressure from certified refurbishment labels as EMA skin-contact material safety guidelines elevate compliance expectations.
Online captures the steepest expansion trajectory; Retail Stores retain the highest conversion rates for Performance-grade transactions.
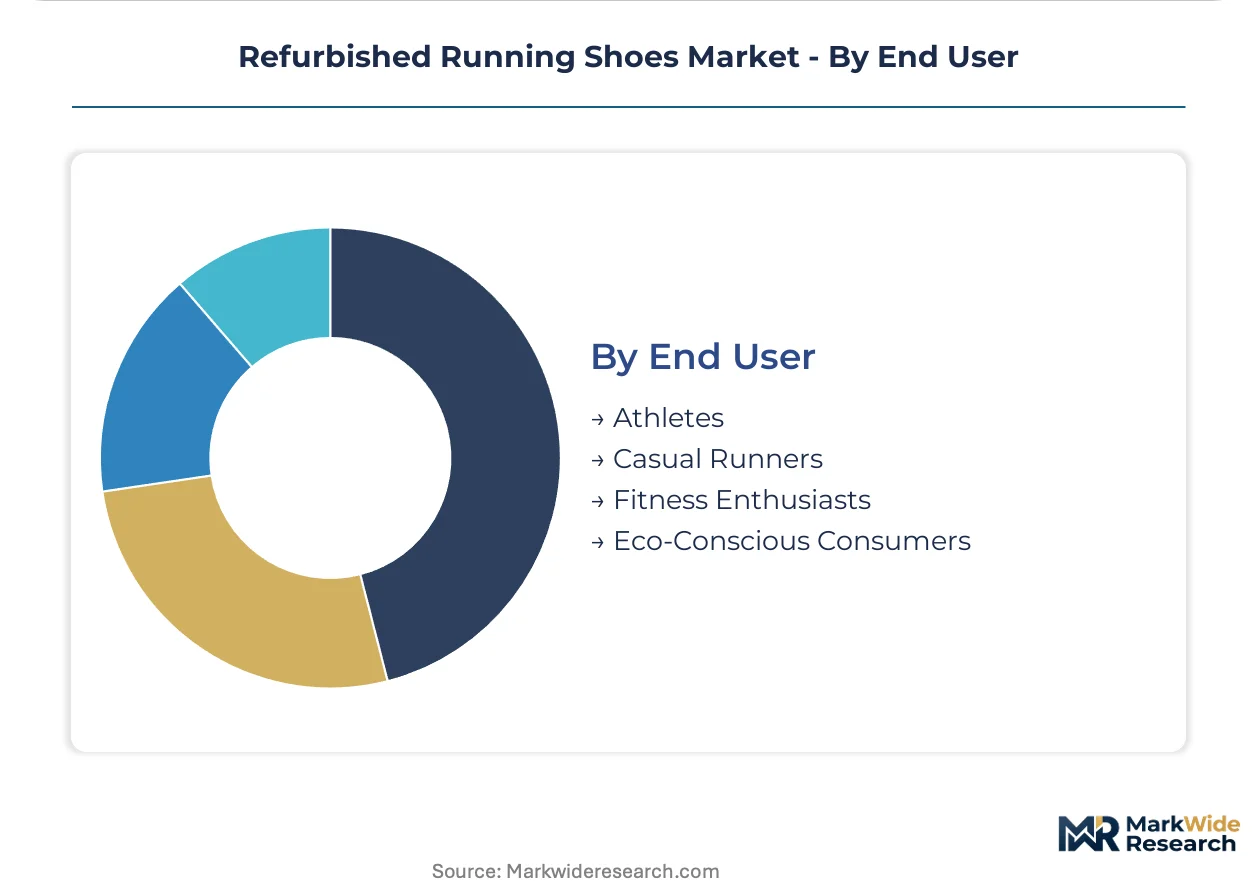
End User:
Application-specific requirements determine refurbishment depth and pricing tolerance across runner motivation segments.
- Athletes:Competitive runners demanding verified cushioning retention and structural integrity documentation. CSRD supply chain disclosure mandates in enterprise wellness programs create B2B procurement pull for certified footwear.
- Casual Runners:Recreational participants prioritizing value and basic functionality over performance optimization. Price elasticity supports manual reconstruction offerings in labor-arbitrage markets.
- Fitness Enthusiasts:Cross-training consumers with moderate mileage requirements and aesthetic sensitivity. Grade-transparency guarantees from modular midsole replacement platforms accelerate adoption in the Netherlands.
- Eco-Conscious Consumers:Sustainability-motivated buyers driving fastest segment expansion as circular economy preferences reshape athletic footwear purchasing patterns across European markets.
Athletes anchor premium-grade demand; Eco-Conscious Consumers are gaining share fastest as EU Green Deal extended producer responsibility mandates intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial zones around Herzogenaurach concentrate automated refurbishment capacity, while Indian special economic zones in Gujarat and Maharashtra host labor-intensive manual reconstruction operations.
Germany
Running culture density in Bavaria and North Rhine-Westphalia generates concentrated demand for verified lifecycle extension services. EU Green Deal extended producer responsibility mandates compel brands to internalize end-of-life costs through certified take-back infrastructure. The Herzogenaurach cluster anchors automated cleaning and bonding line investments from major athletic footwear manufacturers.
Netherlands
Fitness enthusiasts in Randstad cities adopt modular midsole replacement platforms fastest due to grade-transparency guarantees. EMA guidelines on skin-contact material safety elevate compliance expectations for refurbishment facility certification. Amsterdam-based operators pioneer biomechanical testing documentation tools that enable standardized resale grading.
India
Price-sensitive runner segments in tier-2 cities accept manual reconstruction quality, driving labor-cost arbitrage for refurbishment capacity. BIS standards for footwear safety create baseline quality expectations for secondary market operations. Gujarat and Maharashtra special economic zones concentrate Greensole's manual reconstruction facilities serving domestic demand.
United States
Eco-conscious consumers in coastal metropolitan areas drive fastest segment expansion for certified refurbishment channels. EPA waste classification rules for athletic footwear polymers create customs friction that favors domestic processing over cross-border trade. The Pacific Northwest cluster hosts emerging automated facility investments targeting performance-grade resale.
Scandinavia
Environmental labeling literacy among Swedish and Norwegian runners concentrates demand for ISO 14001-audited refurbishment labels. REACH compliance requirements for skin-contact polymers raise barriers for informal refurbishers while rewarding scaled operators. Copenhagen and Stockholm metropolitan areas show strongest price premiums for verified circular economy footwear.
Refurbished Running Shoes Market Competitive Landscape
German producers anchor the automated tier; Indian specialists hold the labor-intensive reconstruction segment. Market structure bifurcates between capital-intensive industrial facilities and craft-preserving manual operations. Three archetypes dominate: brand-integrated refurbishment divisions, independent scaled operators, and labor-arbitrage manual reconstructors. Competitive moves concentrate on automated bonding line deployment and ISO 14001 certification acquisition.
Within the brand-integrated tier, Nike, Inc. and Adidas AG exemplify capital-intensive automation strategies, while Greensole, Inc. occupies the labor-arbitrage manual reconstruction position. These three anchors represent distinct capability configurations: proprietary material recovery programs, automated European capacity, and cost-optimized manual operations for emerging markets.
| Leading Market Players |
|---|
| Reebok |
| Brooks |
| Nike, Inc. |
| Saucony |
| New Balance |
| Adidas AG |
| Asics |
| Greensole. Inc. |
| PUMA SE |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between ISO 14001-audited facilities and unverified operators manifests in both pricing power and supply chain configuration across European refurbishment markets. Like New grade premiums of 35% over unverified equivalents in Scandinavian markets reflect compliance investment recovery, while automated bonding lines in Germany compress per-unit labor from 45 minutes to 8 minutes, reshaping cost structures at volume.
Pricing Analysis
Short lead-time premiums for Performance-grade inventory with verified midsole compression recovery documentation command pricing advantages over spot-market Fair-grade stock with visible wear indicators. Three-tier pricing structure across Like New, Good, and Acceptable levels segments buyer archetypes: Athletes pay least attention to price, while Casual Runners in Indian tier-2 cities exhibit highest elasticity. Cost compression in Fair-grade automated facilities is intensifying because robotics deployment amortizes across high-volume throughput, squeezing manual reconstructors on margin.
Supply Chain Analysis
Regional distribution centers in Bavaria and Gujarat anchor hub-and-spoke patterns that feed refurbishment capacity into end markets. Supply concentrates in Germany, India, and the United States, with raw material dependencies spanning ethylene-vinyl acetate foams, regenerated rubber outsoles, and REACH-compliant adhesives. Single-source vulnerability in midsole foam supply from specialized chemical producers creates exposure to polymer price volatility. Distribution runs through brand-direct online platforms, retail inspection points, and wholesale bulk channels serving secondary market operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The refurbished running shoes market sits at a technology-transition inflection where automated bonding lines displace manual sole regluing, compressing unit economics and reshaping competitive moats around capital intensity rather than craft preservation.
For Market Incumbents: Cement automated cleaning and bonding infrastructure in Herzogenaurach-scale clusters to outpace labor-arbitrage competitors from Indian special economic zones. Prioritize ISO 14001 certification acquisition to capture Scandinavian price premiums before regulatory compliance becomes table stakes. Vertical integration into proprietary material recovery programs, following Nike's Grind model, secures feedstock control against polymer supply volatility. For New Entrants and Emerging Players: EU Green Deal extended producer responsibility mandates in Germany open a window for certified take-back service providers as brands face mandatory infrastructure buildout by 2025. Target Performance-grade modular midsole replacement platforms in Dutch Randstad cities where fitness enthusiasts adopt grade-transparency tools fastest. Lead with biomechanical testing documentation as a differentiated go-to-market angle against unverified marketplace competition. For Investors and Strategic Acquirers: Re-rating potential sits with scaled automated operators given CSRD supply chain disclosure mandates pulling certified refurbishment into enterprise wellness procurement. Long-term viability favors facilities bridging European compliance requirements with emerging market labor cost structures. Watch for EPA-Basel Convention polymer waste classification harmonization as the signal indicating cross-border trade friction resolution and geographic expansion permission.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Bonding Line Deployment | Robotics-enabled sole regluing in German facilities compresses per-unit labor hours and payback periods. |
| ISO 14001 Certification Acquisition | Environmental management system audits in Scandinavian markets command 35% price premiums over unverified channels. |
| Modular Midsole Replacement Platform Launch | Component-level swap systems in Netherlands enable multi-vendor foam sourcing without bonding-process retooling. |
| Extended Producer Responsibility Infrastructure Buildout | EU Green Deal-mandated take-back programs in Germany restructure refurbishment economics toward certified industrial facilities. |
| Manual Craft Certification Program | Italian operators preserve premium positioning through trained technician expertise pools concentrated in traditional manufacturing regions. |
Research Methodology
Independent corroboration across refurbishment facility operators, athletic footwear brand sustainability officers, and secondary market distributors underwrites the qualitative findings in this study. Primary interviews with plant managers at automated cleaning lines, procurement leads at major athletic footwear manufacturers, channel partners in Indian tier-2 cities, and technical R&D directors at adhesive suppliers combined with secondary validation from EU Green Deal implementation documents, REACH registration databases, EPA waste classification rulings, and ISO 14001 audit registries. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates.
Rate-of-change decomposition across the analysis window separates volume growth from value expansion, with CAGRs derived from segment-level adoption curves and pricing trajectory assumptions. Segmentation dimensions modeled include product type tier, grade classification, distribution channel structure, and end-user motivation archetype. Forecast inputs incorporate EU Green Deal extended producer responsibility fee schedules, automated bonding line deployment timelines, and modular midsole replacement platform penetration rates in Dutch and German metropolitan clusters.
The model assumes a particular technology adoption path; alternative pathways for manual reconstruction quality acceptance in price-sensitive emerging markets would alter the outlook. Forecasts reflect documented assumptions regarding REACH compliance cost trajectories and skilled technician availability in traditional shoe manufacturing regions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Footwear Testing Services Market
Footwear
Global Footwear Market
Footwear
Wedge Boots Market
Footwear
Europe Footwear Market
Footwear
Self-Lacing Shoes Market
Footwear
Asia-Pacific Athletic Footwear Market
Footwear
Shoe Insoles Market
Footwear
Sports Shoes Market
Footwear
Sneaker Identification Service Market
Footwear
Winter Footwear Market
Footwear
Tennis Shoes Market
Footwear
White Sneakers Market
Footwear
United States Footwear Market
Footwear
High Heels Footwear Market
Footwear
Premium Shoes Market
Footwear
Dance Shoes Market