
 Cyber-Shoes Market | 2026-2036
Cyber-Shoes Market Size, Share, and Industry Trends Forecast 2026-2036
Cyber-Shoes Market Outlook
Subscription-based firmware updates and software-defined gait analytics is broadening the recurring-revenue model beyond one-time hardware sales. Cybershoes leverages its native VR integration stack to anchor early-adopter loyalty among PC-gaming households. Nike sustains R&D intensity in motion-sensor miniaturization for its connected footwear pipeline. Adidas AG competes through specialty retail channel control in European urban centers.
Cyber-shoes integrate pressure-sensitive insoles, IMU arrays, and low-latency wireless transceivers to translate physical locomotion into virtual movement, serving immersive entertainment and quantified fitness use cases. Manufacturing prioritizes injection-molded TPU chassis with embedded flex circuits to survive repetitive bending cycles. Gaming Shoes command the dominant revenue share due to direct pairing with VR headset ecosystems, while Biometric Feedback technology captures the fastest expansion as athletes demand real-time cadence and impact-force data. Fitness Footwear occupies a maturing niche where margin pools have compressed amid generic sensor commoditization.
FCC Part 15 rules govern wireless emission thresholds for U.S.-market cyber-shoes, while EU REACH restricts hazardous substances in embedded batteries and circuit substrates. South Korea's MFDS and radio-equipment frameworks enforce local certification for biometric data collection wearables. Stakeholders must monitor evolving electromagnetic compatibility standards and battery-transport regulations as product complexity escalates.
Market Dynamics
Wireless latency compression and FCC Part 15 compliance costs are redrawing competitive boundaries between integrated-stack vendors and modular hardware suppliers. The tension between immersive fidelity demands and battery thermal constraints shapes product architecture decisions.
Growth Catalysts
- Esports Infrastructure Investment:South Korea's government-backed gaming complexes and Germany's dedicated VR arenas are installing locomotion hardware as standard equipment. Tournament broadcasters demand spectator-friendly physical movement.
- REACH-Driven Material Substitution:EU restrictions on hazardous substances in embedded electronics are accelerating bio-based TPU formulation adoption. Manufacturers reformulating flex circuits gain preferential retail placement in European urban centers.
- IMU Array Miniaturization:MEMS foundries in Taiwan and South Korea now fabricate six-axis inertial units at wearable-grade power budgets. Fitness application developers access previously military-tier motion fidelity.
Market Restraints
- Lithium-Polymer Supply Concentration:Thin-film battery cell production clusters in Guangdong province. Any regional power rationing or export licensing delays cascade through assembly schedules.
- Radio Spectrum Fragmentation:Cyber-shoes must certify separately for FCC Part 15, EU RED, and South Korea's KC mark. Each jurisdiction imposes distinct emission testing protocols.
- VR Headset Ecosystem Lock-In:Proprietary wireless pairing stacks from Meta and Sony limit cross-platform locomotion hardware. Third-party peripheral vendors face API access negotiations.
Strategic Opportunities
- Clinical Rehabilitation:German and US physical therapy chains are piloting gait-capture cyber-shoes for stroke recovery. Regulatory pathways through FDA 510(k) and BfArM create first-mover certification moats.
- Military Training Simulation:US Army and Bundeswehr procurement offices are soliciting locomotion systems for squad-level virtual exercises. Impact-hardened chassis specifications diverge from consumer gaming designs.
- 5G Edge-Compute Pairing:South Korean carriers are subsidizing low-latency wearables that offload processing to MEC nodes. Cloud-rendered VR reduces onboard compute weight and extends battery duration.
Industry Challenges
- Embedded Firmware Talent Scarcity:Real-time sensor fusion engineering requires rare combinations of DSP optimization and wireless stack expertise. Salaries for qualified firmware architects in San Francisco and Seoul have escalated beyond hardware startup burn rates.
- Multi-Jurisdiction Certification Timelines:Simultaneous FCC, REACH, and MFDS submissions demand dedicated regulatory affairs staff. Six-to-nine month approval windows delay revenue recognition for new product generations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cyber-Shoes Market |
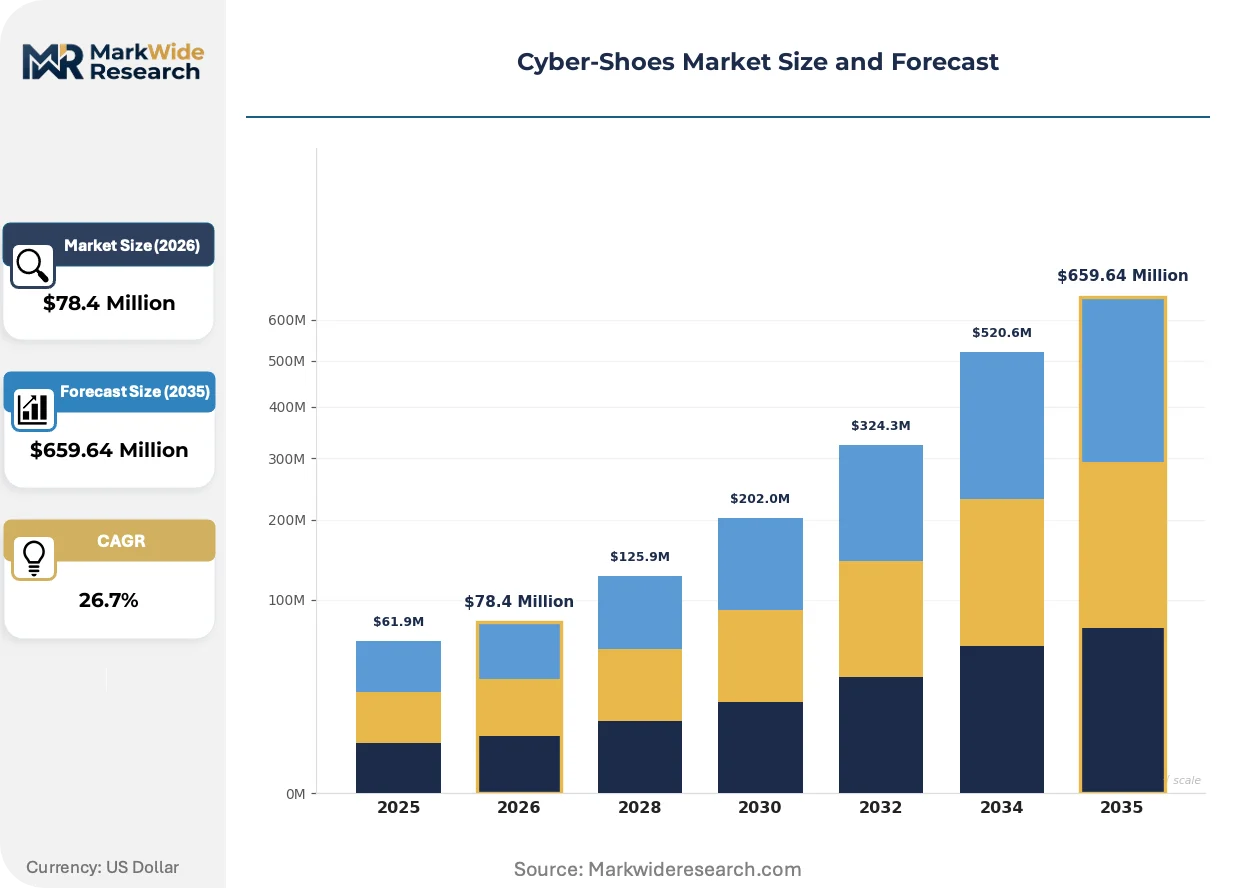
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $659.64 Million |
| CAGR (2026 – 2036) | 26.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Sneakers, Gaming Shoes, Fitness Footwear, Enhanced Performance Shoes Technology: Motion Sensors, Virtual Reality, Augmented Reality, Biometric Feedback End User: Gamers, Fitness Enthusiasts, Athletes, Casual Users Distribution Channel: Online Retail, Specialty Stores, Brand Outlets, Supermarkets |
| Companies Covered | Cybershoes, Nike, Adidas AG, Under Armour, Puma SE, ASICS Corporation, New Balance Athletics, Skechers U.S.A., Digitsole, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cyber-Shoes Market Strategic Shifts
Software-defined sensing architectures are displacing fixed-function hardware designs across the cyber-shoes value chain. Vendors now compete on algorithmic gait interpretation rather than raw component specifications.
Fiber-optic strain sensors are integrating into TPU midsole laminates to capture plantar pressure distribution at kilohertz sampling rates. Professional cycling teams and Olympic track programs are early adopters, purchasing units at tenfold consumer price points. This sensor modality is integrating with machine-learning gait classification to enable injury-prediction services that command recurring subscription revenue.
FCC Part 15 Subpart C is tightening emission masks for 2.4 GHz wearable devices, forcing antenna redesigns and shielding investments. The industrial consequence falls heaviest on budget-tier manufacturers lacking RF engineering benches. Gaming-focused brands with existing wireless headset expertise are absorbing compliance costs faster than pure-play footwear entrants.
Enterprise procurement of locomotion hardware is unbundling from VR headset bundles. US-based corporate training departments now issue separate RFPs for physical movement systems, prioritizing OSHA-aligned safety documentation over consumer aesthetic ratings. This purchasing pattern is most visible in Texas and North Carolina manufacturing hubs where Fortune 500 companies operate dedicated immersive training facilities.
Cyber-Shoes Market Segmentation
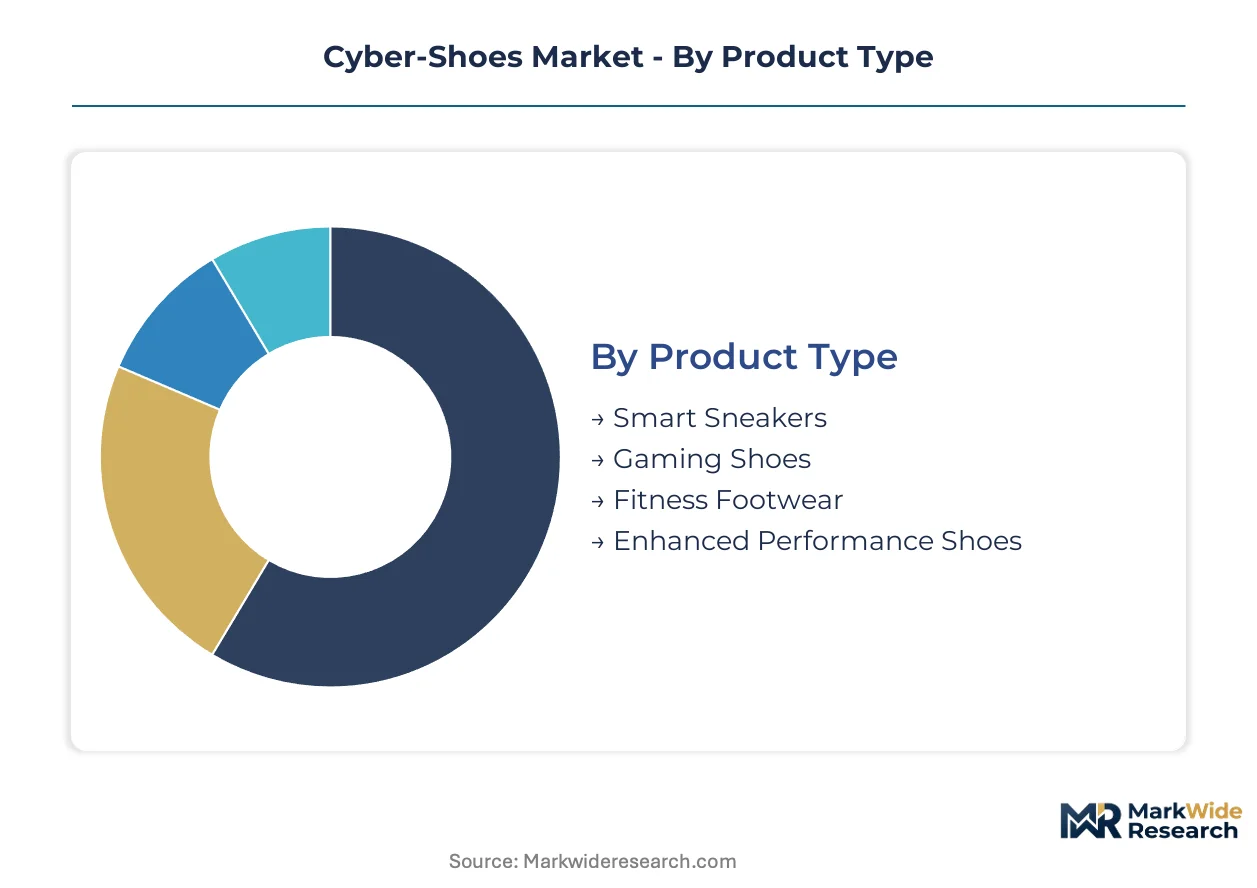
Cyber-shoes manufacturers must align R&D spend and certification timelines against distinct technical requirements across product architectures. Segment-specific capital intensity determines which players can compete across multiple categories versus specializing in single verticals.
Product Type:
Injection-molded TPU chassis with embedded flex circuits demand the heaviest upfront tooling investment, particularly for products targeting repetitive bending cycles in high-frequency use environments.
- Gaming Shoes:Low-latency wireless transceivers pair directly with VR headset ecosystems from Meta and Sony. Demand concentrates in South Korea's government-backed gaming complexes and Germany's dedicated VR arenas where tournament broadcasters require spectator-friendly physical movement.
- Smart Sneakers:Pressure-sensitive insoles and IMU arrays enable quantified fitness tracking through smartphone companion apps. United States urban centers show strongest adoption where fitness-tech ecosystems overlap with consumer electronics retail density.
- Fitness Footwear:Generic sensor commoditization has compressed margin pools in this maturing niche.
- Enhanced Performance Shoes:Fiber-optic strain sensors integrated into TPU midsole laminates serve professional cycling teams and Olympic track programs at premium price points.
Most installed capacity flows through Gaming Shoes. Expansion is steepest in Enhanced Performance Shoes.
Technology:
Algorithmic differentiation now outweighs raw component specifications as vendors compete on software-defined sensing architectures rather than fixed-function hardware designs.
- Biometric Feedback:Machine-learning gait classification enables injury-prediction services commanding recurring subscription revenue. Athletes in German and US physical therapy chains drive pilot programs for stroke recovery applications requiring FDA 510(k) and BfArM certification pathways.
- Motion Sensors:MEMS foundries in Taiwan and South Korea fabricate six-axis inertial units at wearable-grade power budgets. Fitness application developers access previously military-tier motion fidelity through these components.
- Virtual Reality:Proprietary wireless pairing stacks limit cross-platform compatibility.
- Augmented Reality:Overlay applications remain secondary to full immersion use cases.
Biometric Feedback captures the steepest expansion trajectory. Motion Sensors anchor current installed base.
End User:
Procurement authority and technical sophistication vary dramatically across user profiles, from individual consumers to institutional buyers with dedicated immersive training facilities.
- Athletes:Real-time cadence and impact-force data demands drive kilohertz sampling rates and fiber-optic strain sensor integration. Olympic programs and professional cycling teams purchase units at tenfold consumer price points.
- Gamers:PC-gaming households anchor early-adopter loyalty through native VR integration stacks. FCC Part 15 Subpart C emission compliance costs fall heaviest on budget-tier manufacturers lacking RF engineering benches.
- Fitness Enthusiasts:Subscription-based firmware updates broaden recurring-revenue models.
- Casual Users:Price sensitivity limits adoption to promotional retail cycles.
Athletes generate highest per-unit revenue. Gamers provide volume concentration.
Distribution Channel:
Channel control determines margin capture and customer education effectiveness, with specialty retail commanding premium positioning for technically complex products.
- Specialty Stores:Adidas AG competes through channel control in European urban centers where staff expertise explains bio-based TPU formulations and REACH-compliant material substitution. German physical therapy chains source clinical rehabilitation units through this channel.
- Online Retail:Direct-to-consumer models support subscription-based gait analytics and software-defined firmware updates. Cybershoes leverages native VR integration stack marketing to anchor PC-gaming household loyalty.
- Brand Outlets:Nike sustains R&D intensity messaging through controlled retail environments.
- Supermarkets:Generic fitness footwear with commoditized sensors occupies shelf space at compressed margins.
Specialty Stores dominate premium product flows. Online Retail expands most quickly for subscription-enabled offerings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's government-backed gaming complexes install locomotion hardware as standard equipment, while Germany's dedicated VR arenas attract tournament broadcasters demanding spectator-friendly physical movement. Both countries exemplify how esports infrastructure investment concentrates cyber-shoes demand in markets where fitness-tech ecosystems overlap with immersive entertainment.
United States
PC-gaming households in Texas and North Carolina anchor early-adopter loyalty through native VR integration stacks. FCC Part 15 rules govern wireless emission thresholds for U.S.-market cyber-shoes, creating compliance cost barriers for budget-tier manufacturers. Corporate training departments in Fortune 500 manufacturing hubs now issue separate RFPs for physical movement systems prioritizing OSHA-aligned safety documentation.
Germany
Physical therapy chains across Bavaria and North Rhine-Westphalia pilot gait-capture cyber-shoes for stroke recovery applications. BfArM certification pathways create first-mover regulatory moats for clinical rehabilitation vendors. EU REACH restrictions on hazardous substances in embedded electronics accelerate bio-based TPU formulation adoption among manufacturers seeking preferential retail placement in European urban centers.
South Korea
Government-backed gaming complexes in Seoul and Busan-Ulsan install locomotion hardware as standard tournament equipment. MFDS and radio-equipment frameworks enforce local certification for biometric data collection wearables. MEMS foundries in the Seoul Capital Area fabricate six-axis inertial units at wearable-grade power budgets, supplying fitness application developers with previously military-tier motion fidelity.
Japan
Professional cycling teams and Olympic track programs in Kanto and Kansai regions purchase fiber-optic strain sensor units at tenfold consumer price points. METI standards guide wearable electronics safety protocols for high-performance athletic applications. Machine-learning gait classification services command recurring subscription revenue from injury-prediction offerings targeting elite sports institutions.
China
Thin-film battery cell production clusters in Guangdong province supply lithium-polymer cells for cyber-shoes assembly schedules. MIIT radio-equipment regulations and GB standards govern wireless wearable transmission thresholds. Yangtze River Delta manufacturing hubs prioritize injection-molded TPU chassis with embedded flex circuits designed to survive repetitive bending cycles in high-frequency use environments.
Cyber-Shoes Market Competitive Environment
Top-tier vendors anchor integrated-stack positions, while modular hardware suppliers compete on component specialization and cost efficiency. The market structure reflects a bifurcation between gaming-focused brands with existing wireless headset expertise and pure-play footwear entrants lacking RF engineering benches. Three strategic archetypes dominate: native VR integration specialists, traditional athletic footwear incumbents with connected product pipelines, and clinical rehabilitation technology providers. Competitive moves center on M&A activity targeting MEMS foundry partnerships and geographic expansion into government-subsidized 5G edge-compute ecosystems.
Within the native VR integration tier, Cybershoes exemplifies early-mover positioning through direct pairing with PC-gaming household ecosystems. Among traditional athletic footwear incumbents, Nike and Adidas AG occupy contrasting strategic positions—Nike sustains R&D intensity messaging through controlled retail environments, while Adidas AG competes through specialty retail channel control in European urban centers. These three companies represent the dominant competitive archetypes without exhaustive market coverage.
| Leading Market Players |
|---|
| Cybershoes |
| Nike |
| Adidas AG |
| Under Armour |
| Puma SE |
| ASICS Corporation |
| New Balance Athletics |
| Skechers U.S.A. |
| Digitsole |
| Others |
Value Chain & Pricing Dynamics
Fiber-optic strain sensor integration into TPU midsole laminates is compressing production costs for premium-tier cyber-shoes while concentrating manufacturing expertise in Yangtze River Delta hubs. This dual shift simultaneously lowers entry thresholds for performance-tier products and tightens supplier leverage over brands lacking in-house MEMS fabrication partnerships.
Pricing Analysis
Capacity additions in Guangdong province are reshaping price floors for lithium-polymer battery cells that power wireless transceiver modules. Three-tier pricing structure across premium, standard, and economy levels separates FDA 510(k)-certified clinical rehabilitation units from FCC Part 15-compliant gaming peripherals and generic fitness trackers. Cost compression in the economy tier stems from MEMS commoditization out of Taiwan foundries. Casual users exhibit highest price sensitivity, while Olympic programs and professional cycling teams demonstrate inelastic demand for kilohertz-sampling fiber-optic configurations.
Supply Chain Analysis
Dual-sourcing requirements from German and US physical therapy chains are forcing manufacturers to qualify secondary MEMS foundries beyond their primary Taiwan and South Korea suppliers. Raw material dependencies center on thin-film lithium-polymer cells, injection-molded TPU compounds, and six-axis inertial measurement units. Single-source vulnerability concentrates in Guangdong battery cell production where regional power rationing cascades through assembly schedules. Distribution runs through specialty retail channels in European urban centers and direct-to-consumer online platforms for subscription-enabled firmware updates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
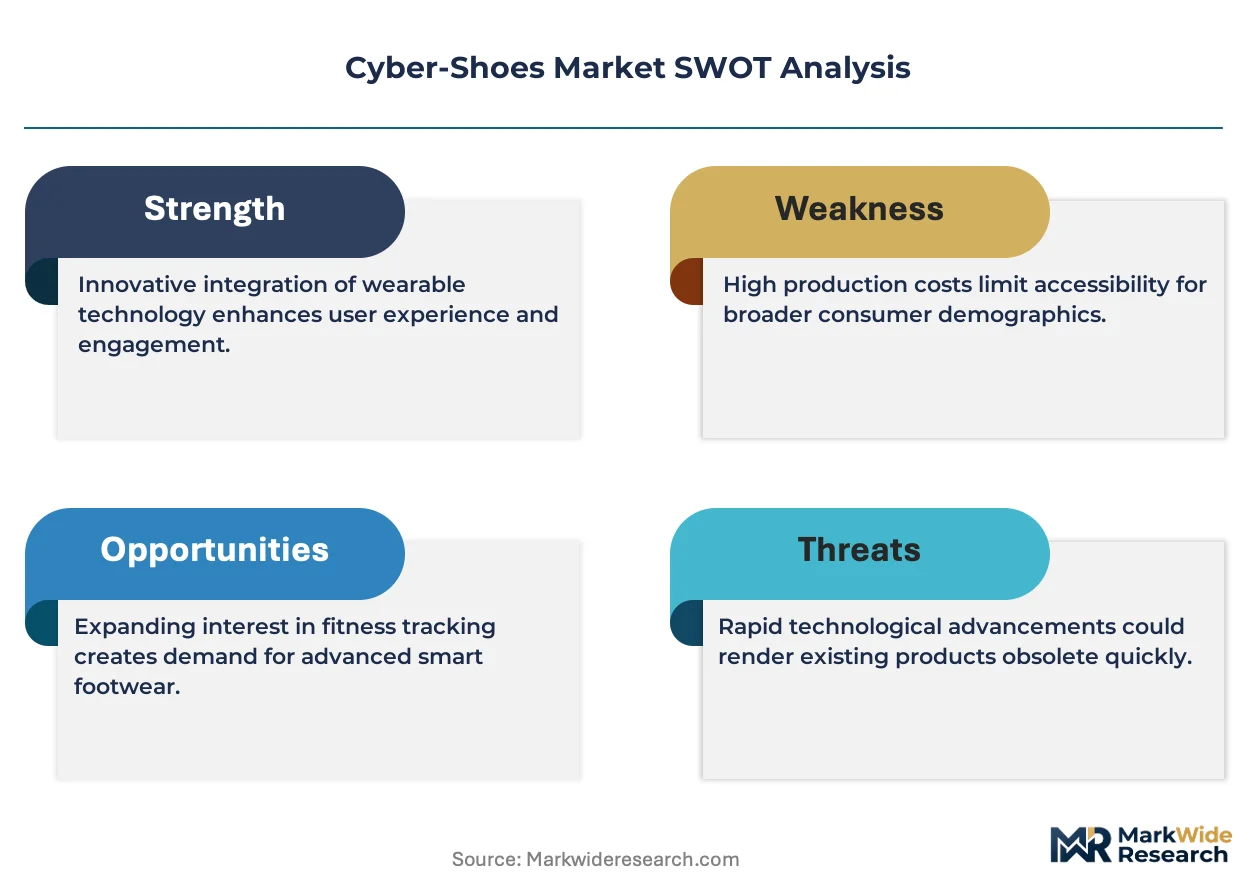
The cyber-shoes market functions as a stable compounder anchored by recurring-revenue firmware subscriptions and replacement-cycle hardware demand from institutional esports infrastructure.
For Market Incumbents: Cement integrated-stack positions by acquiring MEMS foundry partnerships in Seoul Capital Area and locking exclusive API access with Meta's VR headset ecosystem. Channel control in German specialty retail provides defensive moats against pure-play footwear entrants lacking RF engineering benches. Prioritize BfArM certification investments for clinical rehabilitation verticals where regulatory barriers protect margin pools. For New Entrants and Emerging Players: Enter via 5G edge-compute pairing opportunities in South Korea where carriers subsidize low-latency wearables offloading processing to MEC nodes. White-space targets include corporate training departments in Texas and North Carolina manufacturing hubs issuing separate RFPs for OSHA-aligned locomotion systems. Direct-to-consumer subscription models bypass incumbent retail gatekeepers. For Investors and Strategic Acquirers: Roll-up economics work for clinical rehabilitation technology providers because FDA 510(k) and BfArM certification timelines create six-to-nine month approval windows that deter rapid competitive entry. Long-term viability hinges on algorithmic gait interpretation capabilities rather than raw component specifications. Watch for inflection when enterprise procurement fully unbundles locomotion hardware from VR headset bundles.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Foundry Partnership | Taiwan and South Korea fabrication access secures six-axis inertial units at wearable-grade power budgets. |
| Regulatory Certification Pathway | FDA 510(k) and BfArM approvals create first-mover moats in German and US physical therapy chains. |
| 5G Edge-Compute Integration | South Korean carrier subsidies reduce onboard compute weight and extend battery duration for cloud-rendered VR. |
| Software-Defined Sensing Architecture | Algorithmic gait interpretation displaces fixed-function hardware designs across the value chain. |
| Specialty Retail Channel Control | Adidas AG leverages European urban center positioning to explain REACH-compliant bio-based TPU formulations. |
Study Parameters
Coverage spans the United States, Germany, South Korea, Japan, and China, with primary inputs from each market cluster. The research combines structured interviews with VR hardware product managers, MEMS foundry engineering directors, esports tournament operators, physical therapy procurement leads, and FCC regulatory affairs consultants. Secondary validation draws from FCC Part 15 filings, ECHA REACH substance restriction updates, MFDS biometric device registrations, and SEC 10-K disclosures from athletic footwear incumbents. Bottom-up unit economics triangulate against top-down market sizing across gaming, fitness, and clinical rehabilitation end-use segments.
Rate-of-change decomposition separates volume expansion from price trajectory and mix-shift effects across the projection horizon. The analytical framework models cyber-shoes demand by product architecture, sensing technology tier, end-user sophistication, and regional certification cluster. CAGRs derive from segment-level adoption curves weighted by esports infrastructure investment timelines and 5G edge-compute deployment schedules. Forecast inputs include MEMS foundry capacity expansion announcements and REACH-driven material substitution timelines.
Inputs from regulatory filing databases and foundry capacity announcements were available through the study window; gaps in real-time lithium-polymer cell inventory levels introduce uncertainty bands around near-term assembly schedules. Forecasts reflect assumptions on wireless latency compression rates and VR headset ecosystem openness. Deviation in FCC Part 15 Subpart C enforcement stringency or Guangdong power grid stability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Casual Shoes Market
Footwear
Women's Luxury Footwear Market
Footwear
Refurbished Running Shoes Market
Footwear
Protective Footwear Market
Footwear
North America Footwear Market
Footwear
Indian Footwear Market
Footwear
Snow Boots for Women Market
Footwear
Formal Shoes Market
Footwear
Sneaker Identification Service Market
Footwear
High Heels Footwear Market
Footwear
Sports Footwear Market
Footwear
Duck Boots Market
Footwear
Europe Footwear Market
Footwear
Second Hand Designer Shoes Market
Footwear
Shoe Insoles Market
Footwear
Water Shoes Market