
 High Performance Epoxy Market | 2026-2036
High Performance Epoxy Market Size, Share, and Industry Trends Forecast 2026-2036
High Performance Epoxy Market Intelligence
The historical volume-price tradeoff between bulk industrial users and specialized aerospace clients is collapsing as performance requirements intensify across all sectors. Huntsman Corporation leverages its deep formulation expertise in advanced composites for aviation and defense applications. Dow Inc. competes on manufacturing scale and broad-portfolio offerings for the automotive and construction segments. Hexion specializes in thermoset resins, serving diverse industrial end-uses with a focus on material durability and chemical resistance.
High performance epoxies are thermosetting polymers characterized by superior mechanical properties, chemical resistance, and thermal stability, typically derived from the reaction of an epoxide resin with a polyamine hardener. Their primary industrial purpose is to create strong, durable bonds and protective coatings for components exposed to harsh operating environments. Within applications, the aerospace segment commands the highest value due to stringent certification needs, while automotive use is expanding. Liquid and paste product types dominate volume, but film-based epoxies offer precision application for high-value electronics.
Market access and formulation are governed by a complex web of chemical safety regulations, including the EPA's Toxic Substances Control Act in the United States and the ECHA's REACH framework in Europe. In China, compliance with GB standards and MEE environmental protection laws is mandatory for both domestic production and imports. Navigating these divergent regional compliance pathways while innovating in bio-based and recyclable formulations represents the central strategic challenge for suppliers.
Market Dynamics
The central dynamic shaping the high performance epoxy market is the regulatory-driven shift toward sustainable chemistry. Mandates from Europe's ECHA and China's MEE are compelling a fundamental reformulation away from traditional petrochemical feedstocks toward bio-based and recyclable alternatives.
Growth Catalysts
- Lightweighting in Automotive:Demand from electric vehicle manufacturers for lightweight structural adhesives and battery pack encapsulation is a primary catalyst, reducing vehicle mass and extending range.
- Aerospace Sector Expansion:The recovery and expansion of commercial aviation drives consumption of high-strength composites for airframes and interiors, where epoxies are essential for bonding and structural integrity.
- Wind Energy Subsidies:Government incentives for renewable energy, such as the US Inflation Reduction Act (IRA), stimulate demand for epoxies in manufacturing large-scale wind turbine blades.
Market Restraints
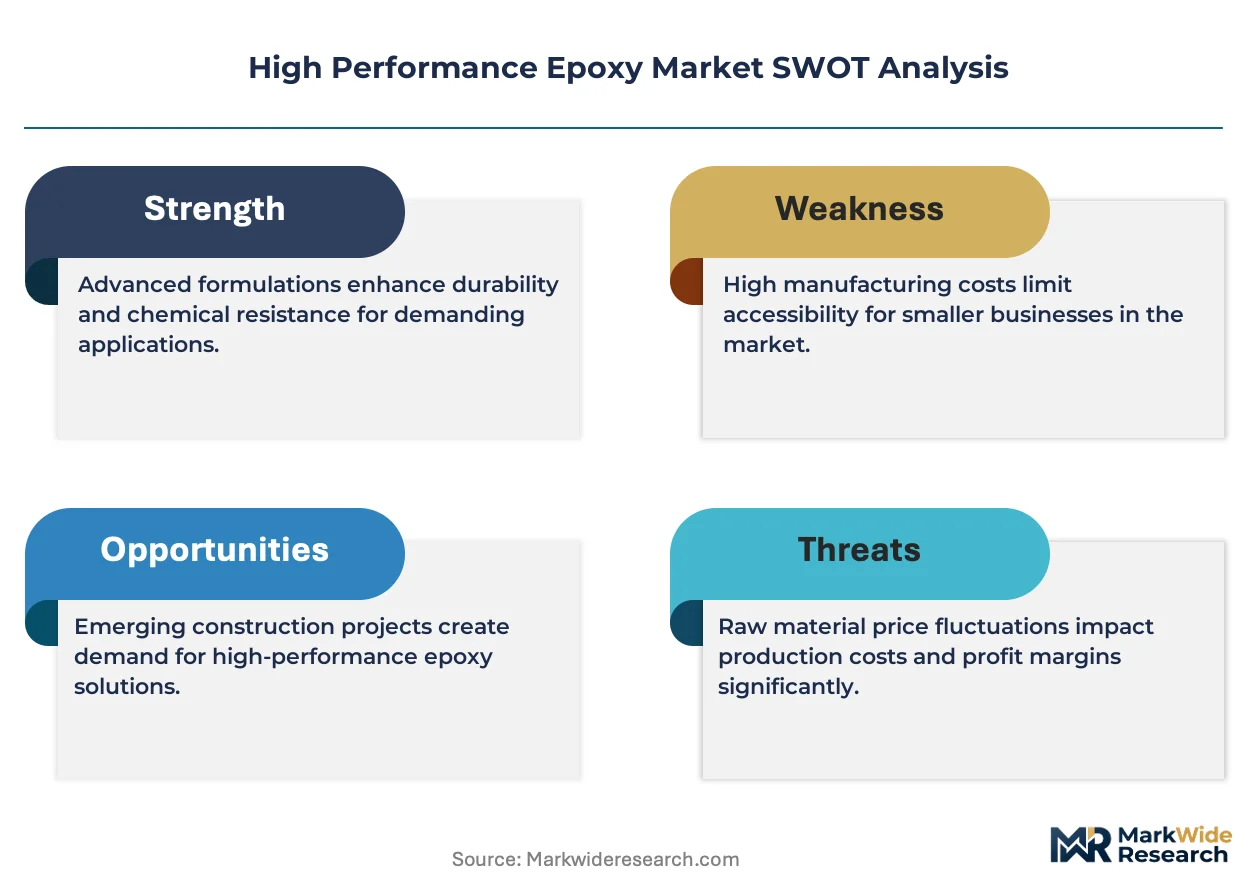
- Feedstock Price Volatility:The market remains exposed to price fluctuations in key petrochemical precursors like bisphenol-A (BPA), impacting formulation costs and final product pricing.
- Curing Time Limitations:Long cure times for some high-performance systems create production bottlenecks in high-volume manufacturing environments like automotive assembly lines, limiting throughput.
- Thermoplastic Composite Competition:Advanced thermoplastics offer recyclability and faster processing cycles, presenting a substitution threat for certain structural components in aerospace and automotive applications.
Strategic Opportunities
- 3D Printing and Additive Manufacturing:Formulating epoxies as photopolymer resins for vat polymerization and binder jetting processes opens new opportunities in rapid prototyping and custom part production.
- Bio-Based Formulations:Developing epoxies from renewable sources like lignin or plant oils allows suppliers to meet corporate sustainability goals and comply with frameworks like the EU Green Deal.
- Indian Electronics Manufacturing:The expansion of electronics assembly in India, supported by the Production Linked Incentive (PLI) scheme, creates demand for specialized epoxies for encapsulation and underfill applications.
Industry Challenges
- Divergent Regulatory Navigation:Managing distinct compliance requirements for chemical registration, such as the EPA's TSCA in the United States and China's GB standards, increases administrative overhead and time-to-market.
- Formulation Expertise Scarcity:A shortage of polymer chemists and application engineers skilled in developing and qualifying new epoxy systems for advanced sectors like aerospace is an operational bottleneck.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Performance Epoxy Market |
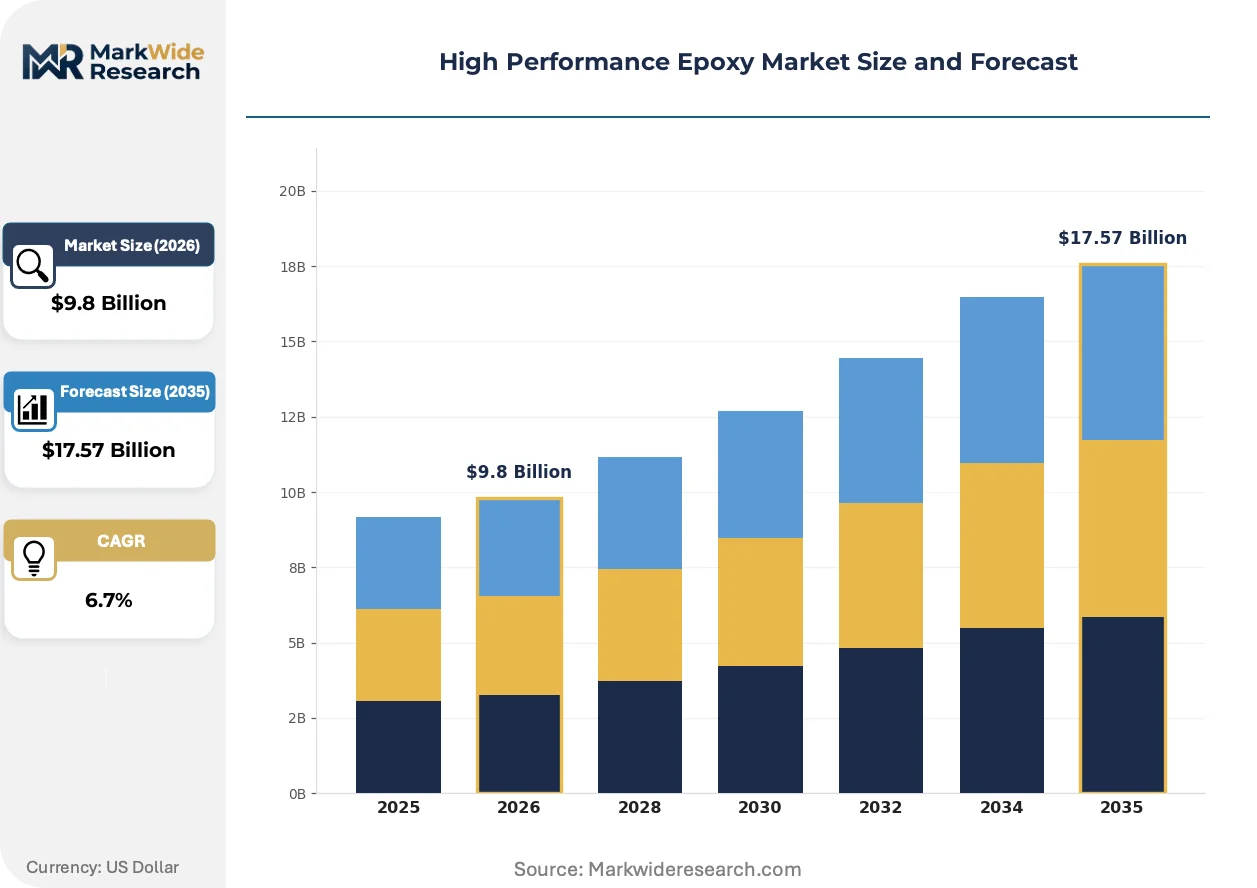
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.57 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
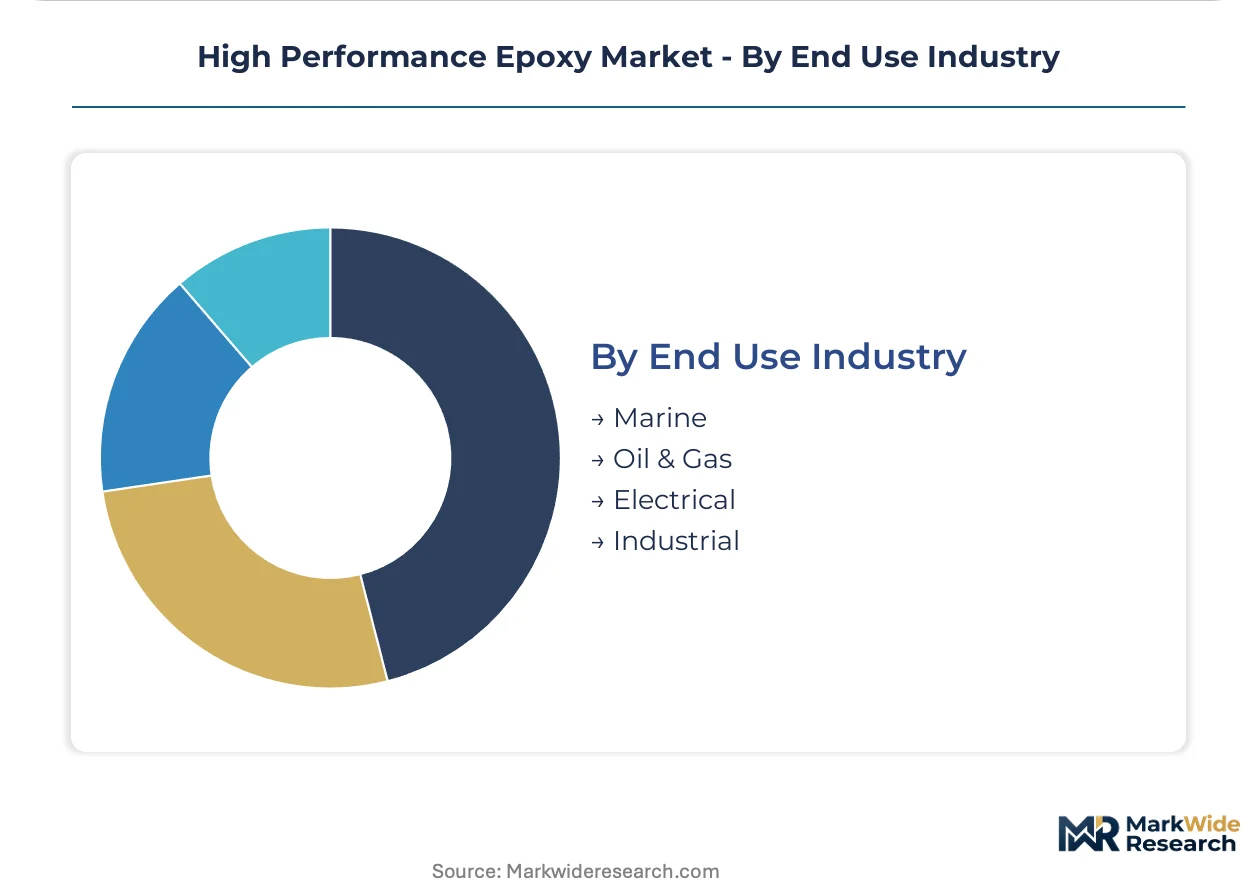
| Segmentation | Application: Aerospace, Automotive, Construction, Electronics Product Type: Liquid, Paste, Solid, Film Technology: 2-Part, 1-Part, Nanotechnology, Bio-based End Use Industry: Marine, Oil & Gas, Electrical, Industrial |
| Companies Covered | Huntsman Corporation, Olin Corporation, 3M, Dow Inc., Hexion, Kukdo Chemical Co., Ltd., Sinopec Corporation, Westlake Epoxy, DIC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Performance Epoxy Market Strategic Shifts & Innovations
Material innovation is converging with process automation to redefine performance and application boundaries. This shift, which is reshaping the competitive landscape, prioritizes not just the inherent properties of the epoxy, but also its compatibility with high-throughput, precision manufacturing environments.
Film-based epoxies are pre-impregnated, solid-state adhesives offering precise thickness control and uniform bond lines for high-value components. The advanced electronics sector is rapidly adopting these films for die-attach and substrate bonding applications. The technology's precision is miniaturizing component layouts in consumer electronics and automotive control units by eliminating the variability of liquid dispensers.
The European Chemicals Agency's (ECHA) REACH framework continues to restrict or require authorization for substances of very high concern (SVHCs), including certain epoxy precursors. This regulation compels ongoing reformulation efforts across the entire supply chain to replace targeted chemicals with safer alternatives. Formulators serving the European automotive and construction markets are most affected, accelerating the switch to lower-VOC and SVHC-free systems.
A shift towards total-cost-of-ownership (TCO) evaluation is altering purchasing decisions for industrial end-users. Buyers are increasingly selecting epoxies based on process efficiency, such as faster cure speeds or reduced waste, rather than on per-unit material cost alone. This trend is most visible in the wind energy and automotive sectors, where production cycle time is a critical manufacturing metric.
High Performance Epoxy Market Segmentation
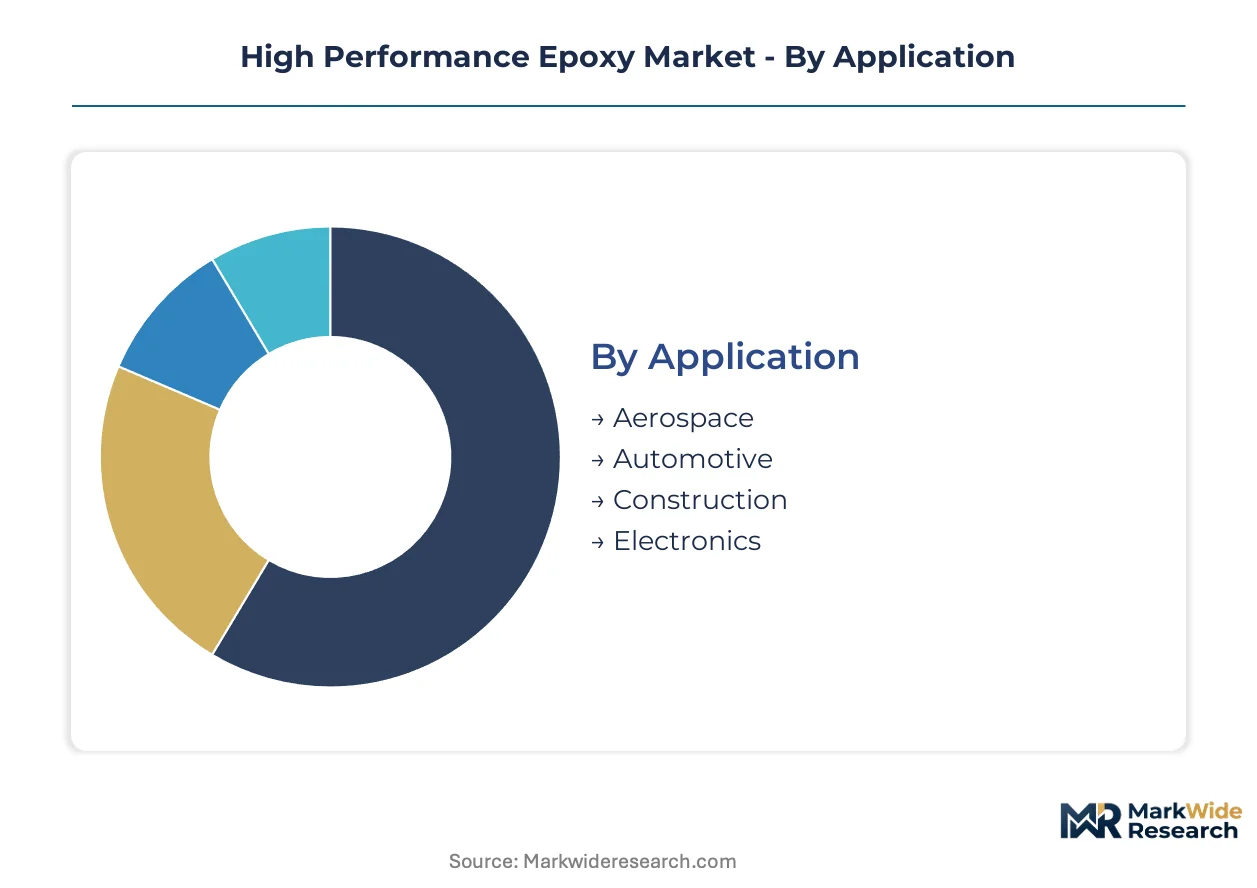
The high performance epoxy market is segmented to reveal nuanced demand patterns and supply chain configurations. Understanding these distinct segments allows suppliers to tailor product formulations and market entry strategies effectively. This granular view highlights where specialized expertise delivers the most value.
Application:
High performance epoxies reach end-users through diverse application channels, each demanding specific formulation and delivery considerations.
- Aerospace:This segment utilizes epoxies for lightweight structural components, advanced composites, and interior applications, requiring materials with exceptional strength-to-weight ratios and stringent certification. Demand concentrates in commercial aviation and defense sectors for airframe and engine parts.
- Automotive:Epoxies serve as structural adhesives, sealants, and encapsulation materials for battery packs, crucial for reducing vehicle mass and enhancing durability in modern vehicles. Electric vehicle manufacturers drive significant consumption for efficient assembly and extended range.
- Construction:Epoxies provide protective coatings, flooring systems, and structural bonding for infrastructure projects, offering durability and chemical resistance in demanding environments.
- Electronics:This segment employs epoxies for encapsulation, die-attach, and substrate bonding, ensuring electrical insulation and mechanical protection for sensitive components.
By volume, automotive applications account for significant consumption. By growth pace, electronics and aerospace applications are expanding rapidly.
Product Type:
Product type segmentation highlights the diverse physical forms epoxies take to meet specific application requirements and processing needs.
- Liquid:These epoxies offer low viscosity and excellent flow characteristics, making them suitable for impregnation, casting, and potting applications. Demand is particularly strong in the wind energy sector for manufacturing large turbine blades and in composite fabrication.
- Film:Film-based epoxies are pre-impregnated, solid-state adhesives offering precise thickness control and uniform bond lines for critical assemblies. The advanced electronics sector rapidly adopts these films for die-attach and substrate bonding in miniaturized components.
- Paste:Paste epoxies are thixotropic formulations designed for gap-filling, sealing, and bonding irregular surfaces, commonly used in general industrial assembly.
- Solid:Solid epoxies are utilized in powder coatings, molding compounds, and prepregs, providing robust electrical insulation and protective layers for various components.
Each product type offers distinct advantages in terms of application method and processing efficiency for industrial users.
Technology:
Technology advancements drive performance characteristics and sustainability profiles across various epoxy formulations.
- 2-Part:These systems involve an epoxide resin reacting with a polyamine hardener, delivering superior mechanical properties, chemical resistance, and thermal stability upon curing. They are essential for high-stress structural bonding in aerospace and demanding construction applications.
- Bio-based:Bio-based epoxies are formulated from renewable sources such as lignin or plant oils, offering reduced environmental impact and aligning with corporate sustainability goals. These alternatives gain traction in European markets driven by the EU Green Deal.
- 1-Part:One-part epoxies are heat-cured, single-component systems that simplify manufacturing processes by eliminating the need for on-site mixing.
- Nanotechnology:This technology incorporates nanoparticles into epoxy formulations to enhance mechanical strength, thermal stability, and electrical conductivity for specialized applications.
Innovation in epoxy technology is increasingly influenced by regulatory pressures and the push for sustainable chemistry.
End Use Industry:
End-use industry segmentation reflects the specific operational environments and durability requirements that high performance epoxies must withstand.
- Oil & Gas:Epoxies provide critical corrosion resistance, high-temperature stability, and structural integrity for pipelines, offshore platforms, and processing equipment. They protect infrastructure exposed to harsh operating conditions.
- Electrical:This industry relies on epoxies for insulation, encapsulation of sensitive components, and thermal management in power generation, distribution, and electronics manufacturing. Epoxies ensure reliable operation of grid infrastructure.
- Marine:Epoxies are used in marine applications for waterproofing, anti-corrosion coatings, and structural repairs on ship hulls, decks, and offshore structures, enduring saltwater exposure.
- Industrial:This broad category includes general manufacturing, machinery assembly, and protective coatings for factory floors and equipment, demanding durability and chemical resistance.
Each industry prioritizes specific performance attributes, such as chemical resistance or thermal stability, for long-term operational integrity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global network of advanced manufacturing hubs, connected by extensive logistics infrastructure, underwrites demand for high performance epoxies. These materials are critical for structural integrity and protective coatings across diverse industrial applications. Regional market dynamics reflect localized industrial specialization and distinct regulatory pressures.
China
China's robust industrial base drives significant consumption of high performance epoxies for advanced electronics and automotive manufacturing. The country's MEE environmental protection laws and GB standards compel local producers and importers to comply with strict chemical regulations. Major industrial clusters in the Yangtze River Delta continue to expand their capacity for high-tech component production.
United States
The United States market benefits from strong demand in aerospace, electric vehicle manufacturing, and wind energy projects. Regulations from the EPA's Toxic Substances Control Act (TSCA) and incentives like the US Inflation Reduction Act (IRA) shape material development. Aerospace manufacturing in Seattle and electric vehicle production in Michigan represent significant consumption hubs.
Germany
Germany's advanced manufacturing sector, particularly in automotive lightweighting and specialized construction, fuels demand for high performance epoxies. Compliance with the ECHA's REACH framework and the EU Green Deal influences the shift towards sustainable and bio-based formulations. Industrial regions like Bavaria and North Rhine-Westphalia lead in the adoption of these advanced materials.
India
India's expanding electronics assembly industry and infrastructure development create new opportunities for high performance epoxies. The Production Linked Incentive (PLI) scheme supports domestic manufacturing, increasing the need for specialized encapsulation and bonding materials. Karnataka's electronics manufacturing hub and Gujarat's industrial zones are key growth centers for epoxy consumption.
High Performance Epoxy Market Key Industry Players
Concentration sits with established chemical conglomerates offering broad portfolios, alongside specialized manufacturers focusing on high-value applications. The market exhibits a tiered structure, with large-scale producers competing on volume and niche players excelling in custom formulations. Companies pursue portfolio diversification and strategic partnerships to expand their application reach.
Specialists in advanced composites, such as Huntsman Corporation, anchor the high-value aerospace segment with deep formulation expertise. Dow Inc. represents the archetype of large-scale chemical producers, leveraging extensive manufacturing capabilities across diverse industrial sectors. Hexion, a thermoset resin specialist, exemplifies players focused on material durability and chemical resistance for industrial end-uses.
| Leading Market Players |
|---|
| Huntsman Corporation |
| Olin Corporation |
| 3M |
| Dow Inc. |
| Hexion |
| Kukdo Chemical Co., Ltd. |
| Sinopec Corporation |
| Westlake Epoxy |
| DIC Corporation |
| Others |
Cost & Logistics Intelligence
Extended lead times for specialized epoxy precursors, particularly those tied to petrochemical feedstocks, directly influence final product pricing and supply chain resilience. This dependency creates pricing power for suppliers with integrated raw material access.
Pricing Analysis
Volume-based tiering structures differentiate pricing for high performance epoxies, with bulk industrial users accessing lower per-unit costs compared to specialized aerospace clients. Certification level and formulation complexity drive significant price differentiation, particularly for aerospace-grade materials. Pricing softness reflects intense competition from thermoplastic alternatives in high-volume automotive applications. Automotive manufacturers and general industrial users exhibit higher price sensitivity, while aerospace and electronics sectors prioritize performance and certification over cost.
Supply Chain Analysis
Inventory observations show a lean approach for standard epoxy grades, but longer holding periods for custom, high-performance formulations due to complex raw material sourcing. Geographic supply concentration centers heavily in China for basic epoxy resins and hardeners, alongside specialized production in Germany and the United States for advanced formulations. Raw material dependencies include bisphenol-A (BPA) and various polyamine hardeners. Commodity price volatility in petrochemical precursors represents a significant structural risk. Distribution runs through a network of specialized chemical distributors and direct sales channels to large industrial end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The high performance epoxy market is experiencing a buyer-power shift, driven by increasing consolidation among large automotive OEMs and electronics manufacturers demanding integrated solutions.
For Market Incumbents: Secure long-term supply agreements for bio-based feedstocks to mitigate regulatory risks and insulate against petrochemical price volatility. Deepen vertical integration into specialized hardener production to counter emerging thermoplastic composite competition. Invest in R&D for faster-curing systems to address production bottlenecks in automotive assembly lines. Pursue strategic partnerships with additive manufacturing equipment providers to expand application reach.
For New Entrants and Emerging Players: Service-layer gaps exist in localized technical support and rapid prototyping for specialized applications. Target the Indian electronics manufacturing segment with tailored encapsulation and underfill solutions, leveraging the PLI scheme. Focus on developing bio-based or lower-VOC formulations to gain market entry in Europe, aligning with the EU Green Deal. A direct-to-customer technical sales approach can penetrate niche markets requiring high-touch application engineering.
For Investors and Strategic Acquirers: Carve-out targets emerge from large chemical conglomerates seeking to divest non-core thermoset resin businesses. These assets often possess valuable formulation expertise and established customer relationships in high-value segments. Focus on companies specializing in advanced composite epoxies or those with proprietary bio-based technologies. The increasing stringency of global chemical regulations, particularly REACH, is a signal to watch for accelerated M&A activity in sustainable chemistry.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop faster-curing epoxy systems | Accelerates production cycles in automotive and wind energy manufacturing, improving throughput. |
| Invest in bio-based feedstock R&D | Aligns with global sustainability mandates and reduces reliance on volatile petrochemicals. |
| Expand additive manufacturing formulations | Opens new markets in rapid prototyping and custom component production for aerospace. |
| Strengthen localized technical support | Addresses specific application challenges for electronics manufacturers in emerging regions like India. |
| Form strategic partnerships with OEMs | Secures long-term demand and co-develops next-generation materials for lightweighting initiatives. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews with industry stakeholders and rigorous secondary data validation. Primary research involved discussions with polymer chemists, procurement leads at aerospace and automotive OEMs, and regulatory affairs specialists. Secondary sources included trade association reports, government environmental agency publications like ECHA and EPA, and corporate financial filings. This blend facilitated a robust bottom-up and top-down triangulation of market data.
The forecasting approach established clear boundaries for market projections across the analysis window, modeling key segmentation dimensions. These included application, product type, technology, and end-use industry, alongside regional manufacturing hubs. Compound annual growth rates were derived by integrating historical performance trends with projected shifts in regulatory frameworks and technological advancements. Key industry-specific forecast inputs included electric vehicle production forecasts and commercial aircraft delivery schedules.
Underlying assumptions cover anticipated regulatory stability and continued technological investment in sustainable chemistry, with deviation risk concentrated in unforeseen geopolitical events impacting raw material supply. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Performance Chemicals
High Performance Plastics Market
Performance Chemicals
Global Oilfield Production Chemicals Market
Performance Chemicals
Chemical Feed Systems Market
Performance Chemicals
Global High Performance Polymers Market
Performance Chemicals
Global High Performance Polyamides Market
Performance Chemicals
Global Reflective Materials Market
Performance Chemicals
Asia-Pacific Hydrogen Peroxide Market
Performance Chemicals
Mecoprop Market