
 Global Reflective Materials Market | 2026-2036
Global Reflective Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Global Reflective Materials Market Foresight
Buyer concentration across state-level transportation departments is realigning procurement volumes toward fewer, larger contracts with multi-year performance guarantees. 3M Company leverages its captive resin and microreplication capabilities to sustain pricing power in North American highway retroreflectivity programs. Avery Dennison Corporation anchors European demand through ORAFOL Europe GmbH's specialized distribution network for traffic signage films. Nippon Carbide Industries Co., Inc. dominates Asian supply chains with in-house glass bead production and regional technical service centers.
Reflective materials are engineered optical structures—typically microprismatic arrays, glass bead embedded layers, or metallized substrates—that return incident light toward its source within narrow divergence angles, measured in candelas per lux per square meter (cd/lx/m²). These materials function primarily to enhance nighttime visibility of vehicles, road surfaces, protective garments, and commercial signage under low-illumination conditions. Microprismatic films command premium positioning due to superior long-distance retroreflectivity and durability against abrasion and UV degradation. Glass beads occupy high-volume, cost-sensitive road marking applications where initial material cost outweighs service-life considerations. Reflective yarns are gaining traction in personal protective equipment as EN ISO 20471 certification requirements tighten across European industrial workplaces.
Federal Highway Administration (FHWA) minimum retroreflectivity standards for traffic signs, European Committee for Standardization (CEN) EN 12899 requirements for road marking materials, and China's GB/T 18833 national standard for retroreflective sheeting collectively dictate product compliance thresholds and testing protocols. Manufacturers must maintain dual-certification laboratories to access both North American and European procurement channels without redundant qualification cycles. Stakeholders should monitor evolving photometric performance thresholds and biobased content mandates as regulatory agencies integrate circular-economy criteria into infrastructure material specifications.
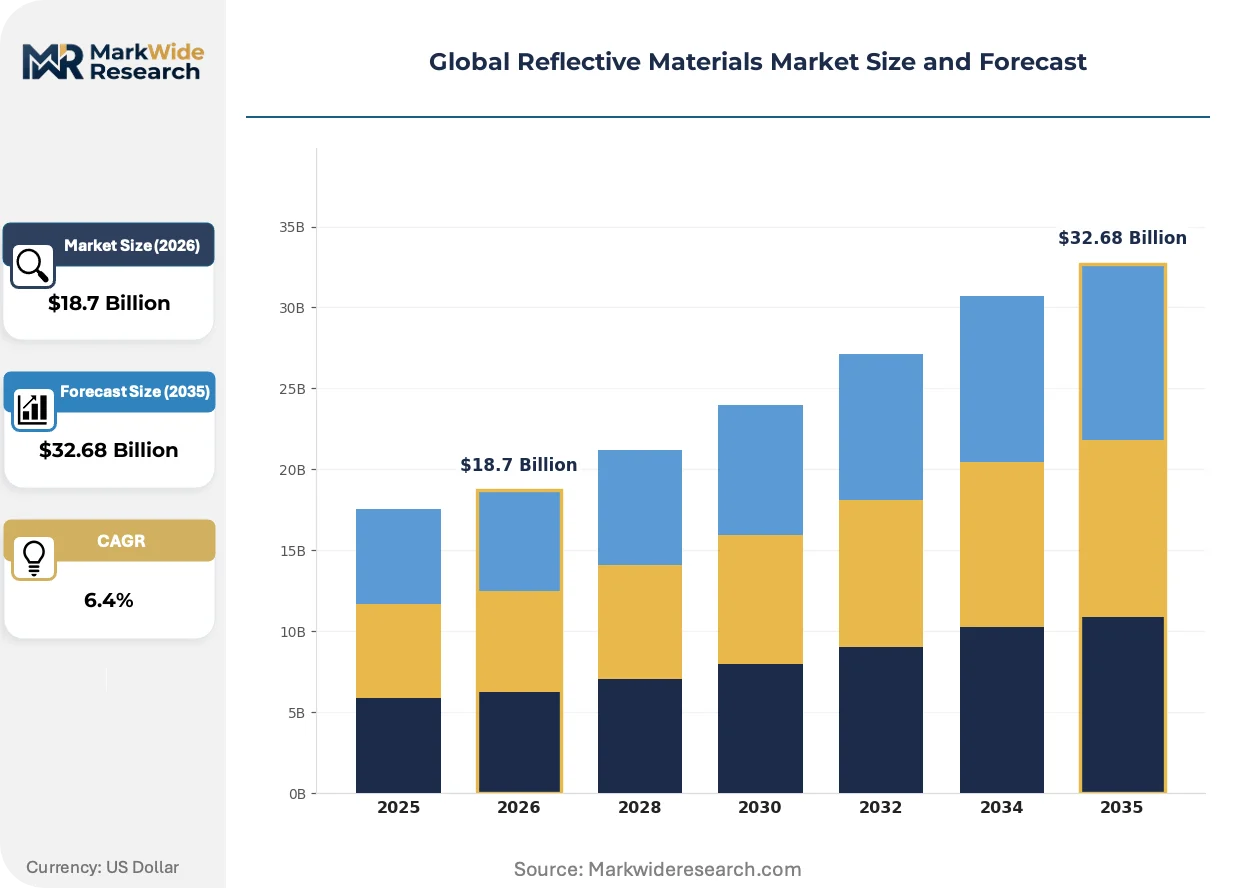
Market Dynamics
Highway agencies in China, the United States, and Germany are consolidating procurement into multi-year performance contracts, compressing supplier margins while demanding extended durability guarantees against UV degradation and abrasion.
Growth Catalysts
- FMVSS 108 mandates:The NHTSA regulation requires retroreflective tape on commercial trailers, sustaining replacement demand across North American trucking fleets.
- Glass bead road marking:Municipal contractors in India and Brazil favor this cost-effective formulation for high-volume highway striping programs.
- China's highway expansion:Provincial transportation bureaus are retrofitting urban signage and tunnel markings with microprismatic films under GB/T 18833 compliance.
Market Restraints
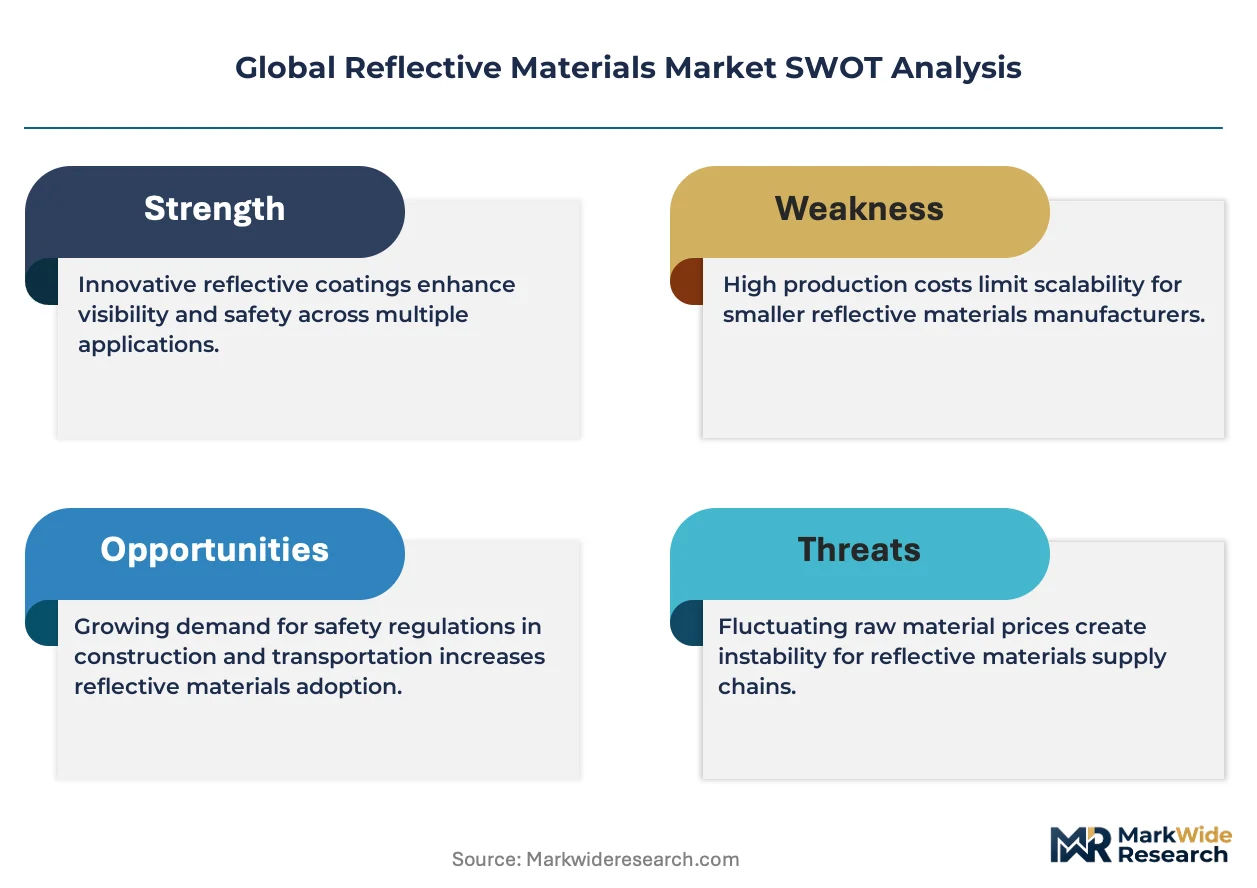
- Petroleum-derived resin volatility:Acrylic and polycarbonate feedstock costs fluctuate with crude oil pricing, squeezing film manufacturer margins.
- Asian glass bead concentration:Over 70 percent of spherical silica supply originates from Chinese and Indian producers, creating single-source vulnerability.
- Microprismatic patent thickets:3M's intellectual property portfolio around cube-corner geometry limits new entrants in premium highway signage.
Strategic Opportunities
- Indonesia's underpenetrated infrastructure:Trans-Java toll road expansion lacks standardized retroreflective specifications, opening first-mover positioning.
- Wearable PPE convergence:EN ISO 20471 certification for industrial garments is pulling reflective yarn into European manufacturing and logistics sectors.
- Biobased content mandates:EU Green Deal circular-economy criteria are pressuring infrastructure material specifications toward recycled-content films.
Industry Challenges
- Dual-certification laboratory capex:Manufacturers must maintain separate photometric testing facilities for FHWA and CEN protocols to avoid redundant qualification cycles.
- Microreplication technician scarcity:Precision optical engineering talent concentrates in Japan and Germany, constraining capacity expansion elsewhere.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Reflective Materials Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microprismatic Films, Glass Beads, Fluorescent Sheeting, Glass Bubbles, Reflective Yarns Application: Traffic Safety, Personal Protective Equipment, Road Marking, Signage, Outdoor Advertising End User Industry: Construction, Public Transportation, Marine Services, Emergency Services, Event Management Distribution Channel: Direct Sales, Online Retailers, Distributors, Industrial Suppliers, Specialty Stores |
| Companies Covered | 3M Company, Avery Dennison Corporation, ORAFOL Europe GmbH, Nippon Carbide Industries Co., Inc., Coats Group plc, Changzhou Hua R Sheng Reflective Material Co., Ltd., Asian Paints PPG, ALANOD GmbH & Co. KG, Reflomax, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Reflective Materials Market Shifts & Advancements
Photometric performance thresholds are tightening across jurisdictions while material science advances enable thinner, more flexible retroreflective constructions. These shifts are compressing traditional supply hierarchies.
Microprismatic retroreflective film is overtaking glass bead formulations in European highway signage procurement. German and French transportation authorities specify cube-corner technology for long-distance visibility on autobahn and autoroute networks. This displacement is forcing glass bead producers to retreat into cost-sensitive emerging markets where initial material cost dominates lifetime value calculations.
REACH substance restrictions are reshaping adhesive and coating chemistries in reflective sheeting production. ECHA's candidate list scrutiny of persistent organic pollutants is compelling reformulation of pressure-sensitive adhesives used in vehicle conspicuity tape. European film converters are accelerating qualification of solvent-free laminating processes to maintain CE marking access.
State-level transportation departments are bundling signage, pavement marking, and intelligent transportation system contracts into single-vendor agreements. This consolidation favors suppliers with captive resin production and in-house microreplication capabilities. The phenomenon is most pronounced in Texas, California, and Florida, where department of transportation procurement offices cite lifecycle cost modeling as selection criteria.
Global Reflective Materials Market Segmentation
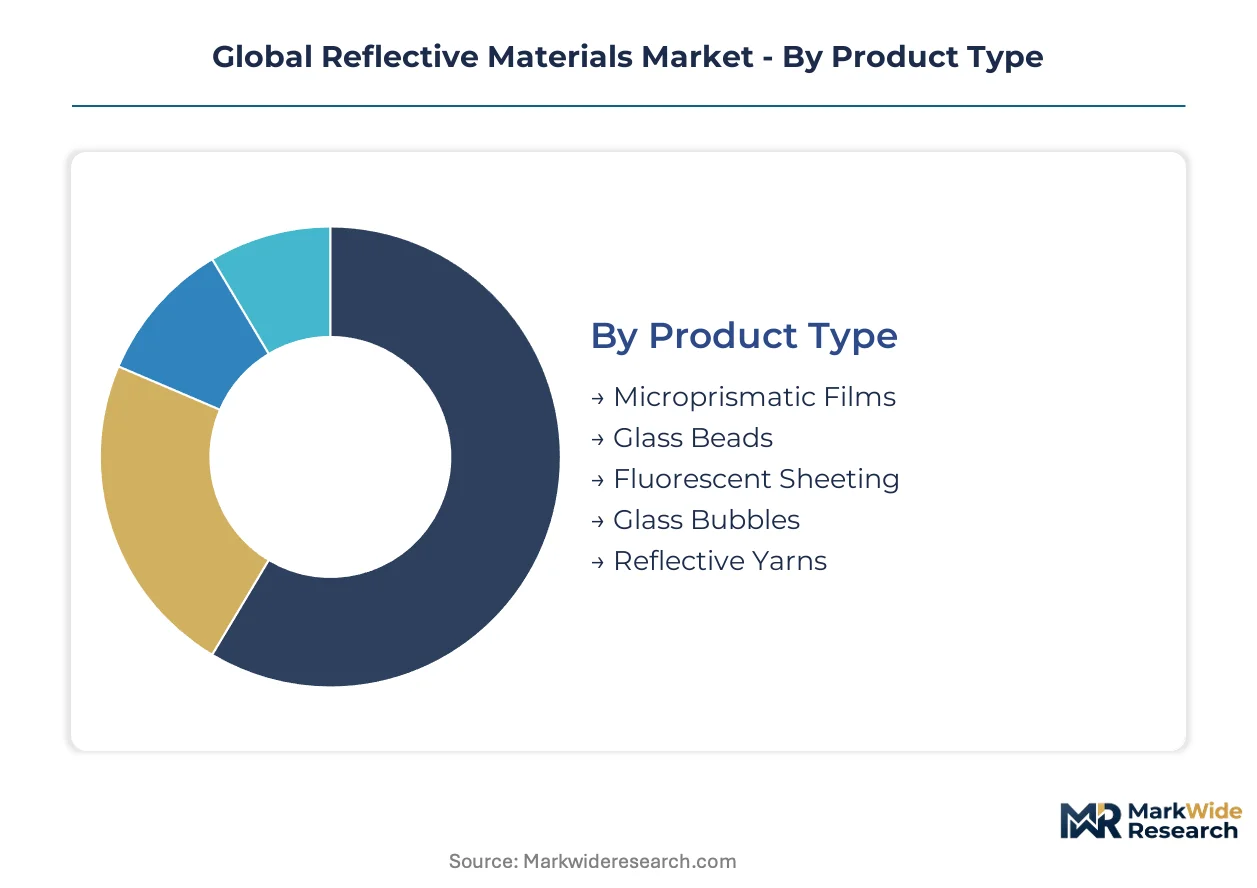
Retroreflective technologies diverge sharply in capital requirements, from precision microreplication equipment demanding eight-figure cleanroom investments to commodity glass bead furnaces operating at far lower fixed costs. Understanding these investment thresholds clarifies why certain segments consolidate under integrated manufacturers while others fragment across regional specialists.
Product Type:
Microprismatic films demand the heaviest upfront commitment, requiring diamond-turned master tooling and vacuum metallization chambers that lock in multi-year amortization schedules.
- Microprismatic Films:Cube-corner arrays manufactured through electroformed nickel tooling deliver superior long-distance retroreflectivity exceeding 1000 cd/lx/m². Highway agencies in Germany and Texas specify these films for autobahn and interstate signage where 300-meter visibility is mandatory. Capital intensity limits viable producers to those with captive resin synthesis and in-house microreplication.
- Glass Beads:Spherical silica particles embedded in thermoplastic binders dominate cost-sensitive road marking applications. Municipal contractors in India and Brazil favor this formulation for high-volume highway striping where initial material cost outweighs durability considerations. Furnace technology is widely available, enabling fragmented regional supply.
- Fluorescent Sheeting:Daytime-visible pigments integrated into retroreflective substrates serve school zone and work area signage. State DOTs in Florida and California specify fluorescent orange for temporary traffic control.
- Glass Bubbles:Hollow microspheres reduce density in buoyant marine marking applications. Coast guard specifications in Japan and Canada drive procurement for channel markers.
- Reflective Yarns:Metallized polyester filaments woven into high-visibility garments. EN ISO 20471 certification requirements across European industrial workplaces are pulling demand from manufacturing and logistics sectors.
Most installed capacity flows through Glass Beads. Expansion is steepest in Reflective Yarns.
Application:
Application segments separate by performance certification tier rather than manufacturing process, with traffic safety commanding the most stringent photometric testing protocols.
- Traffic Safety:Vehicle conspicuity tape and traffic signage must meet FMVSS 108 in the United States, ECE R104 in Europe, and GB/T 18833 in China. NHTSA mandates sustain replacement demand across North American commercial trucking fleets. Dual-certification laboratory requirements erect barriers for suppliers lacking capital for parallel FHWA and CEN testing facilities.
- Road Marking:Pavement striping materials face abrasion from tire wear and UV degradation. Provincial transportation bureaus in China are retrofitting urban signage and tunnel markings with upgraded formulations.
- Personal Protective Equipment:High-visibility garments for industrial workers, cyclists, and emergency responders. European manufacturing and logistics sectors are tightening procurement specifications.
- Signage:Permanent road signs and wayfinding systems. German and French authorities specify long-distance visibility standards for autobahn networks.
- Outdoor Advertising:Billboard facings and building wraps leveraging nighttime visibility. Urban retrofit programs in Chinese megacities consume specialty films.
Traffic Safety commands the dominant revenue share. Personal Protective Equipment is gaining share fastest as workplace safety regulations tighten.
End User Industry:
End user concentration varies by project scale, with public transportation agencies consolidating procurement into multi-year performance contracts while event management remains fragmented.
- Construction:Highway contractors and infrastructure developers specify retroreflective materials for work zone protection and permanent road installations. Consolidated procurement in the United States, China, and Germany compresses supplier margins while demanding extended durability guarantees.
- Public Transportation:State and provincial transportation departments bundle signage, pavement marking, and intelligent transportation system contracts. Texas, California, and Florida DOTs cite lifecycle cost modeling as selection criteria.
- Emergency Services:Fire, police, and ambulance fleet marking requirements. FMVSS 108 mandates apply to commercial emergency vehicle retroreflectivity.
- Marine Services:Coast guard and harbor authority specifications for channel markers and vessel safety equipment. Japanese and Canadian regulations drive standardization.
- Event Management:Temporary crowd control and wayfinding for sporting events and festivals. Fragmented procurement favors distributors with rapid turnaround capability.
Public Transportation channels the majority of contract value. Construction is expanding most quickly as highway agency budgets recover.
Distribution Channel:
Channel selection tracks customer scale and technical service requirements, with direct sales capturing the largest accounts and online retail penetrating small-lot PPE buyers.
- Direct Sales:Manufacturer relationships with state DOTs, large construction contractors, and fleet operators. Technical service engineers assist with specification compliance and installation training.
- Distributors:Regional stocking locations serving municipal contractors and smaller construction firms. ORAFOL Europe GmbH's specialized network anchors European traffic signage film distribution.
- Industrial Suppliers:Integrated safety product catalogs targeting manufacturing plant procurement. Reflective yarns reach European industrial workplaces through this channel.
- Online Retailers:E-commerce platforms serving individual PPE purchasers and small event operators. Product photography and certification documentation substitute for technical sales support.
- Specialty Stores:Safety equipment retailers serving local contractors and maintenance departments. Geographic coverage concentrates in North American and European urban centers.
Direct Sales handles the largest contract volumes. Online Retailers are climbing the fastest as PPE procurement digitizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes microprismatic films at scale through provincial highway bureaus, while Germany enforces stricter photometric thresholds on autobahn signage than any other European jurisdiction. India and Brazil favor cost-driven glass bead formulations for high-volume road marking. The United States sustains replacement demand through NHTSA-mandated fleet retroreflectivity programs.
China
Provincial transportation bureaus in Jiangsu and Guangdong are retrofitting urban signage and tunnel markings with upgraded microprismatic films. GB/T 18833 national standards mandate minimum retroreflectivity thresholds for highway sheeting procurement. Manufacturing clusters in Changzhou and Shanghai supply both domestic highway programs and export markets across Southeast Asia.
United States
State DOTs in Texas, California, and Florida bundle multi-year signage and pavement marking contracts under lifecycle cost selection criteria. NHTSA's FMVSS 108 regulation sustains replacement demand for commercial trailer conspicuity tape across North American trucking fleets. Technical service centers in the Midwest and Southeast support specification compliance for consolidated procurement programs.
Germany
Federal and state road authorities specify cube-corner microprismatic technology for autobahn signage requiring 300-meter nighttime visibility. CEN EN 12899 requirements for road marking materials exceed photometric thresholds enforced in neighboring jurisdictions. Industrial concentration in Baden-Württemberg and Bavaria hosts precision optical engineering capabilities for master tooling production.
India
National highway expansion under the Bharatmala program drives glass bead consumption for cost-sensitive pavement striping across state road networks. Municipal contractors in Maharashtra and Gujarat prioritize initial material cost over durability in high-volume procurement. Regional furnace operations in Rajasthan and Gujarat supply spherical silica to domestic road marking contractors.
Brazil
Federal and state highway departments specify thermoplastic road markings with embedded glass beads for the Transbrasiliana and other corridor programs. ANVISA and national infrastructure agencies coordinate material specifications for federal road concessions. Industrial distribution concentrates in São Paulo state, serving contractors across the Southeast and Center-West regions.
Global Reflective Materials Market Competitive Landscape
North American and European producers anchor the premium microprismatic tier; Asian specialists hold volume positions in glass bead and commodity sheeting segments. Market structure concentrates around integrated manufacturers with captive resin synthesis and in-house microreplication capabilities, while fragmented regional players serve cost-sensitive emerging markets. Two archetypes dominate: vertically integrated optical film manufacturers and specialized glass bead furnace operators. Competitive dynamics center on multi-year performance contracting with state transportation agencies and qualification of solvent-free adhesive formulations for European REACH compliance.
Within the integrated optical film tier, 3M Company and Avery Dennison Corporation exemplify manufacturers with captive resin and microreplication capabilities that sustain positioning in highway retroreflectivity programs. ORAFOL Europe GmbH anchors European distribution networks for traffic signage films. Nippon Carbide Industries Co., Inc. occupies a position among Asian producers with in-house glass bead production and regional technical service infrastructure. These companies represent the structural divide between premium microprismatic supply and high-volume glass bead formulations.
| Leading Market Players |
|---|
| 3M Company |
| Avery Dennison Corporation |
| ORAFOL Europe GmbH |
| Nippon Carbide Industries Co., Inc. |
| Coats Group plc |
| Changzhou Hua R Sheng Reflective Material Co., Ltd. |
| Asian Paints PPG |
| ALANOD GmbH & Co. KG |
| Reflomax |
| Others |
Supply & Pricing Matrix
Precision optical engineering talent concentration in Japan and Germany generates labor-cost differentials that widen pricing-tier spreads between premium microprismatic films and commodity glass bead formulations. Manufacturers with captive microreplication capabilities in Baden-Württemberg command substantial premiums over furnace operators in Rajasthan, where spherical silica production feeds cost-sensitive road marking procurement.
Pricing Analysis
Capacity additions in China are reshaping price floors for glass bead formulations while premium microprismatic films maintain three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on certification grade—dual-certified products for FHWA and CEN protocols command substantial premiums over single-market qualifications—and volume scale, with state DOT bundled contracts securing favorable unit economics. Pricing pressure stems from petroleum-derived resin volatility squeezing film manufacturer margins. Municipal contractors in India and Brazil exhibit highest price sensitivity, while German autobahn authorities prioritize photometric performance over initial material cost.
Supply Chain Analysis
End-of-life film recovery and metallized substrate refurbishment flows remain underdeveloped, constraining circular-economy compliance for EU Green Deal procurement criteria. Geographic supply concentration centers on China, India, and Germany, with Changzhou and Shanghai clusters serving Asian highway programs and Baden-Württemberg hosting precision tooling production. Raw material dependencies draw from acrylic and polycarbonate resin feedstocks, spherical silica for glass bead furnaces, and aluminum metallization sources. Single-source vulnerability pervades Asian glass bead concentration, where over 70 percent of spherical silica supply originates from Chinese and Indian producers. Distribution runs through direct sales for state DOT contracts, regional distributors for municipal contractors, and industrial suppliers for PPE procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where NHTSA's FMVSS 108 mandate for commercial trailer conspicuity tape sustains predictable replacement demand across North American trucking fleets. Success depends on aligning manufacturing capabilities with evolving photometric thresholds and biobased content specifications.
For Market Incumbents: Lock in multi-year performance contracts with state transportation departments by extending durability guarantees against UV degradation and abrasion. Deepen backward integration into captive resin synthesis to defend margin position against petroleum feedstock volatility. Prioritize dual-certification laboratory investments to eliminate redundant FHWA and CEN qualification cycles that delay market access. For New Entrants and Emerging Players: The mid-market price-point gap between 3M-grade microprismatic premiums and Indian glass bead economy tiers offers viable entry positioning. Target Indonesia's underpenetrated Trans-Java toll road expansion where standardized retroreflective specifications remain undefined. Pursue EN ISO 20471 certification for reflective yarns to access European industrial PPE procurement through industrial supplier channels. For Investors and Strategic Acquirers: Specialty chemical conglomerates with infrastructure materials portfolios are the most active acquirer in this space, seeking optical film capabilities to complement existing highway coatings businesses. Long-term viability favors vertically integrated manufacturers with in-house microreplication and captive resin production over pure-play glass bead furnace operators. Monitor ECHA REACH substance restriction timelines for pressure-sensitive adhesive reformulation as inflection indicator for solvent-free process qualification requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Synthesis | Captive acrylic and polycarbonate supply insulates margins from crude oil volatility affecting film manufacturers. |
| Dual-Certification Laboratory Investment | Parallel FHWA and CEN testing facilities eliminate redundant qualification cycles for North American and European procurement access. |
| Solvent-Free Adhesive Qualification | ECHA REACH compliance for pressure-sensitive adhesives maintains CE marking access under evolving substance restrictions. |
| Reflective Yarn Certification Pursuit | EN ISO 20471 qualification opens European industrial PPE procurement channels in manufacturing and logistics sectors. |
| Regional Technical Service Expansion | Provincial transportation bureau relationships in Jiangsu and Guangdong secure retrofit program participation under GB/T 18833 standards. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region informing demand-side validation. Primary interviews incorporated highway agency procurement officers, commercial fleet maintenance directors, reflective material plant managers, and PPE industrial buyer committees. Secondary sources drew from NHTSA regulatory filings, ECHA REACH candidate list updates, FHWA minimum retroreflectivity standards documentation, and Chinese GB/T 18833 national standard protocols. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across product type, application, and end user industry dimensions.
Granularity-level modeling disaggregated volume and value outputs across microprismatic films, glass beads, fluorescent sheeting, and reflective yarns by traffic safety, road marking, personal protective equipment, and signage applications. CAGRs were derived through regression analysis of historical procurement patterns and regulatory mandate implementation timelines. Forecast inputs incorporated highway expansion program budgets, fleet replacement cycles under FMVSS 108, and EN ISO 20471 certification adoption curves across European industrial workplaces.
Caveats apply where petroleum resin price volatility, REACH substance restriction acceleration, or Chinese provincial budget reallocation could materially shift the outlook. Forecasts reflect assumptions around regulatory compliance timelines and infrastructure spending continuity. Practitioners should monitor ECHA persistent organic pollutant scrutiny and biobased content mandate progression for early signals of specification disruption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Performance Chemicals
High Performance Plastics Market
Performance Chemicals
Asia-Pacific Hydrogen Peroxide Market
Performance Chemicals
Global High Performance Polyamides Market
Performance Chemicals
High Performance Epoxy Market
Performance Chemicals
Global Oilfield Production Chemicals Market
Performance Chemicals
Global High Performance Polymers Market
Performance Chemicals
Mecoprop Market
Performance Chemicals
Chemical Feed Systems Market