
 Global Oilfield Production Chemicals Market | 2026-2036
Global Oilfield Production Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Oilfield Production Chemicals Market Foresight
The Middle East is fragmenting as a supply center for oilfield production chemicals, with new blending facilities in Saudi Arabia and the UAE challenging traditional European and North American supply bases. Baker Hughes Company leverages its integrated chemical-manufacturing network across the Gulf Coast to sustain captive supply advantages. Halliburton Company anchors its position through R&D intensity in high-pressure high-temperature formulations. Clariant AG specializes in bio-based demulsifier chemistry that navigates tightening discharge standards.
Oilfield production chemicals comprise formulated surfactants, polymers, and specialty solvents injected into hydrocarbon reservoirs and wellbores to control corrosion, prevent scale deposition, separate emulsions, and maintain flow assurance at temperatures exceeding 150°C and pressures above 10,000 psi. Corrosion inhibitors dominate value pools in mature offshore fields where asset integrity spending commands premium pricing, while demulsifiers represent the fastest-expanding category as heavy-oil and high-water-cut production escalates globally. Enhanced Oil Recovery applications concentrate margin pools where polymer flooding and surfactant-polymer formulations require precise chemical choreography.
The US EPA regulates offshore chemical discharge through NPDES permits and toxicity testing protocols, while REACH in Europe mandates substitution of persistent bioaccumulative substances in subsea applications. Saudi Arabia's national environmental regulator enforces marine discharge limits that shape product registration requirements for offshore platform chemicals. Stakeholders must monitor regulatory divergence between jurisdictions that fragments product portfolios and elevates formulation complexity.
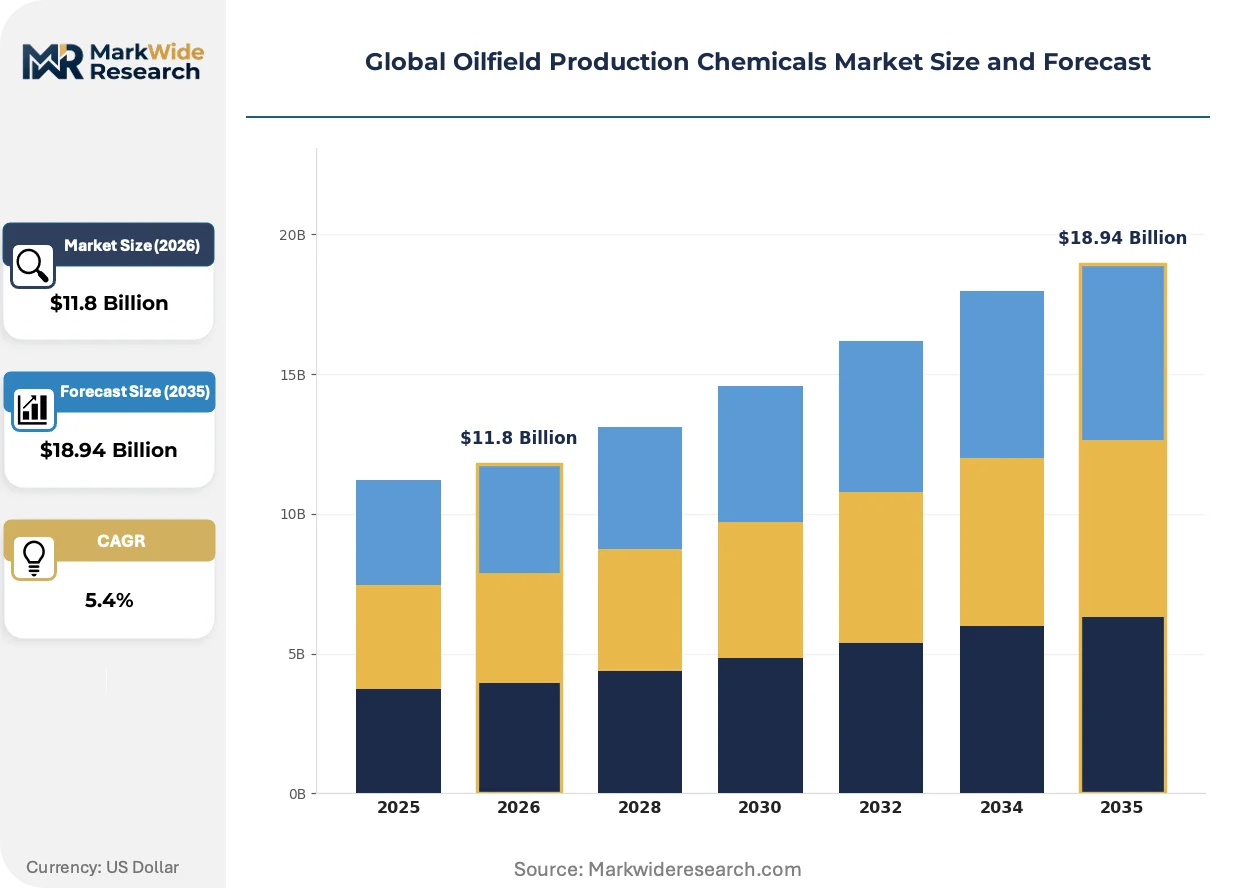
Market Dynamics
Deepwater field maturation off Brazil and West Africa is pulling specialty chemical formulations toward higher thermal stability thresholds, while REACH-driven substitution mandates in Europe force parallel reformulation tracks that fragment product portfolios.
Growth Catalysts
- HPHT reservoir development:Subsea tiebacks in Brazil's pre-salt basins demand corrosion inhibitors rated above 180°C and 15,000 psi, expanding the addressable premium formulation segment.
- REACH substance restrictions:ECHA's phased restrictions on persistent bioaccumulative toxins in offshore discharges are mandating bio-based demulsifier chemistry that commands higher unit economics.
- Tight-oil paraffin management intensity:Permian Basin operators now inject paraffin dispersants at 3-5x the dosage rates of conventional crude systems due to high-wax-content unconventional production.
Market Restraints
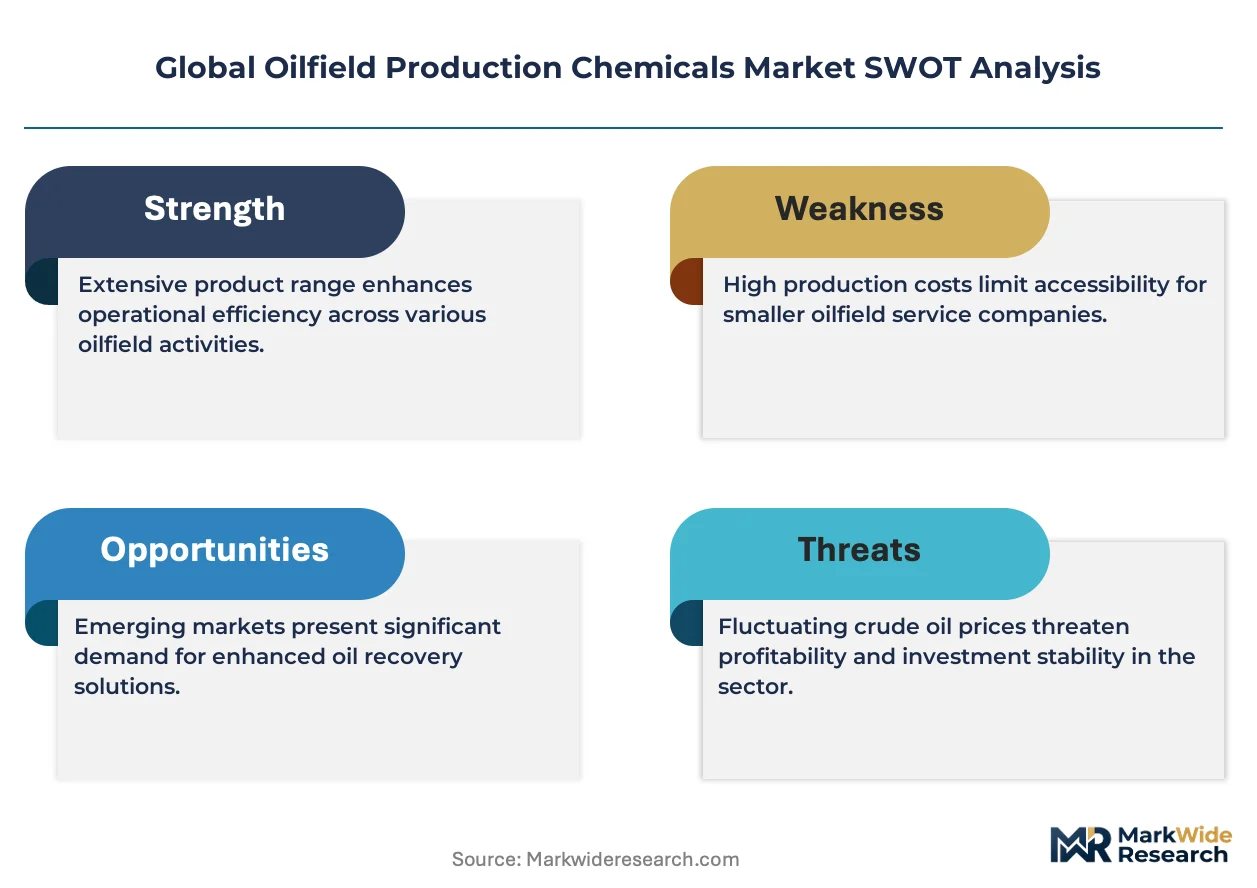
- Ethylene oxide supply concentration:Nonionic surfactant precursors depend on Gulf Coast ethylene oxide capacity where hurricane-related outages create 30-60 day formulation delays.
- Subsea certification timelines:NORSOK M-001 compliance for Norwegian North Sea applications extends product qualification cycles to 18-24 months, freezing out smaller blenders.
- Produced water treatment substitution:Membrane-based separation systems in Saudi Aramco's Marjan expansion are displacing chemical demulsifiers in specific low-viscosity crude streams.
Strategic Opportunities
- Guyana-Suriname basin greenfield development:ExxonMobil's multi-billion-barrel discoveries lack established chemical supply infrastructure, creating first-mover registration advantages for qualified blenders.
- Polymer flooding EOR scale-up:China's Daqing and Shengli fields are expanding surfactant-polymer injection programs that require precision-matched chemical choreography.
- Digital chemical inventory optimization:IoT-enabled tank monitoring and predictive dosing algorithms are opening subscription revenue models that decouple supplier economics from commodity volume.
Industry Challenges
- HPHT formulation chemist scarcity:The specialized skillset combining thermodynamic modeling and surfactant synthesis resides in fewer than 200 practitioners globally, constraining R&D throughput.
- Legacy wellbore chemical incompatibility:Decades-old North Sea infrastructure contains incompatible elastomer seals that fail when exposed to new low-toxicity corrosion inhibitor chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Oilfield Production Chemicals Market |
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $18.94 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
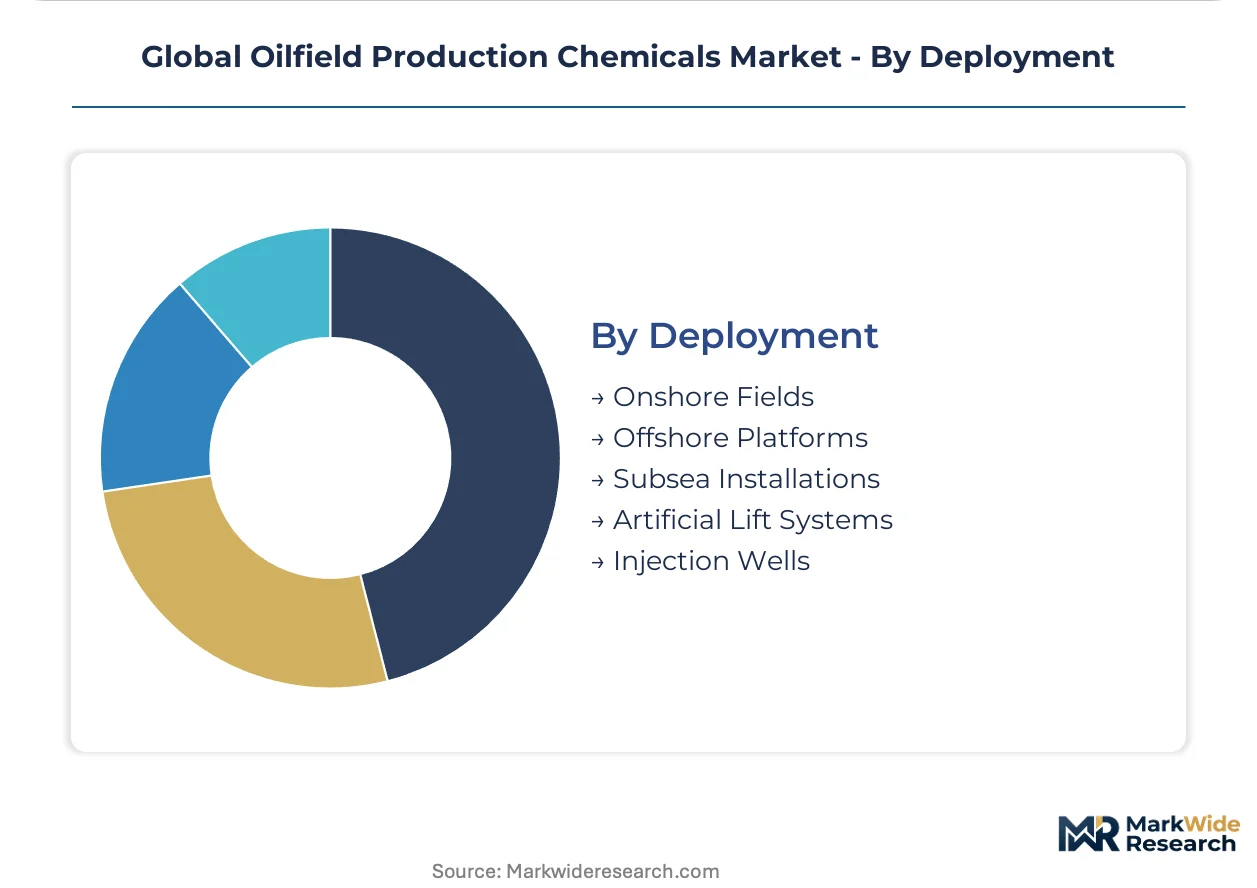
| Segmentation | Product Type: Corrosion Inhibitors, Scale Inhibitors, Demulsifiers, Biocides, Surfactants Application: Enhanced Oil Recovery, Well Stimulation, Drilling Fluids, Production Optimization, Flow Assurance End User: Exploration & Production Companies, Drilling Contractors, Service Operators, Midstream Firms Deployment: Onshore Fields, Offshore Platforms, Subsea Installations, Artificial Lift Systems, Injection Wells |
| Companies Covered | Baker Hughes Company, Halliburton Company, BASF SE, Nouryon, The Lubrizol Corporation, Schlumberger Limited, Clariant AG, Solvay S.A., Dow Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Oilfield Production Chemicals Market Shifts & Advancements
Formulation science is pivoting from commodity scale inhibition toward integrated flow-assurance systems that combine multiple chemistries in single-stream injection, compressing supplier count per field development.
Silicon-based defoamer chemistry is migrating from legacy polydimethylsiloxane fluids toward modified siloxane-polyether copolymers that maintain performance at gas-oil ratios exceeding 5,000 scf/bbl. Gulf of Mexico deepwater operators are adopting these formulations at 15-20% annual substitution rates. The technology is migrating from niche high-GR applications into standard offshore specifications, eroding commodity defoamer volumes.
EPA's updated NPDES general permit for offshore oil and gas (2024) mandates whole-effluent toxicity testing at lower dilution factors, forcing reformulation of biocides and corrosion inhibitors toward rapid biodegradation profiles. The rule compresses allowable discharge concentrations for quaternary ammonium compounds by 40%. US Gulf Coast platform operators are responding by pre-qualifying bio-based alternatives ahead of permit renewal cycles.
Integrated service contracting is consolidating chemical procurement into bundled drilling-completion-production packages where supermajors negotiate enterprise-level formulation supply across multiple basins. This disintermediates regional distributors and transfers inventory risk to chemical suppliers. The model is most visible in BP's and Shell's integrated tender structures for North Sea and Gulf of Mexico assets.
Global Oilfield Production Chemicals Market Segmentation
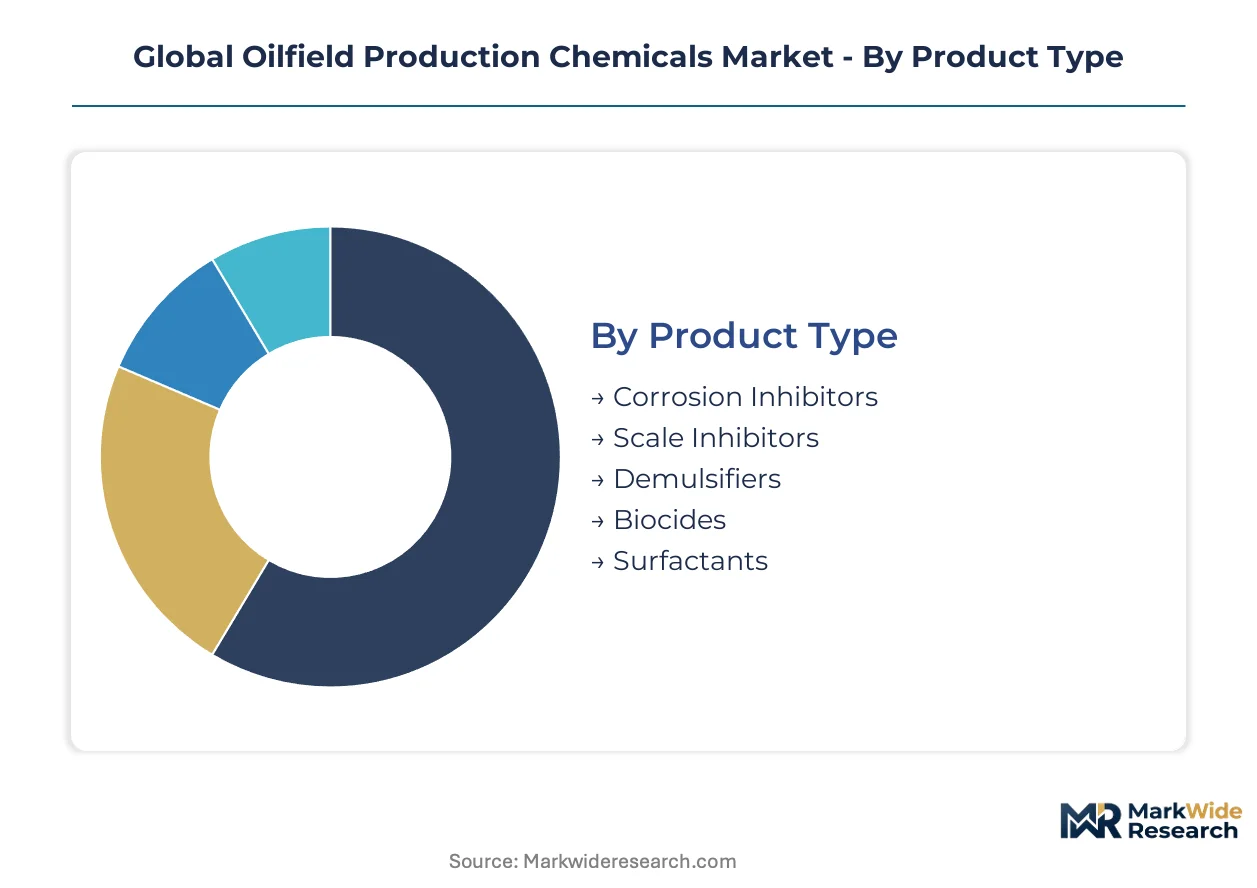
Oilfield production chemicals segment across four critical dimensions that determine formulation specifications, procurement patterns, and margin structures. Product chemistry dictates thermal stability requirements. Application context shapes injection rates and performance guarantees. End-user category influences contract duration and technical service intensity. Deployment environment governs regulatory compliance and logistics complexity.
Product Type:
Cost tier separates commodity inhibitors from specialty demulsifiers and biocides, with pricing spreads reflecting formulation complexity and certification requirements.
- Corrosion Inhibitors:Film-forming amines and imidazoline derivatives protect carbon steel infrastructure in sour gas environments. Demand concentrates in mature offshore fields off Norway and Brazil where asset integrity spending commands premium pricing despite high base chemical costs.
- Demulsifiers:Polymeric surfactants and polyol esters separate water-in-oil emulsions through interfacial tension reduction. The steepest expansion runs through Brazil's pre-salt basins and Canada's oil sands where high-water-cut heavy oil production escalates chemical consumption intensity.
- Scale Inhibitors:Phosphonate and polymer-based formulations prevent mineral deposition in high-temperature reservoirs.
- Biocides:Glutaraldehyde and THPS chemistries control sulfate-reducing bacteria in waterflood systems.
- Surfactants:Nonionic and anionic surface-active agents enable emulsion control and wettability alteration.
Corrosion inhibitors command the established base. The steepest expansion runs through demulsifiers.
Application:
Application context determines whether chemicals serve production maintenance, reservoir enhancement, or drilling support functions, with each use case carrying distinct performance metrics and liability exposure.
- Enhanced Oil Recovery:Polymer flooding and surfactant-polymer formulations mobilize residual oil through viscosity modification and interfacial tension reduction. China's Daqing and Shengli fields anchor global demand for precision-matched chemical choreography in mature waterflood conversions.
- Flow Assurance:Integrated chemical systems prevent hydrate formation, wax deposition, and asphaltene precipitation in subsea tiebacks. Brazil's pre-salt developments drive specification tightening toward chemistries rated above 180°C and 15,000 psi.
- Well Stimulation:Acidizing and fracturing fluid additives enhance near-wellbore permeability.
- Drilling Fluids:Rheology modifiers and shale inhibitors maintain borehole stability.
- Production Optimization:Paraffin dispersants and defoamers sustain throughput in high-GOR wells.
Flow assurance captures the premium formulation segment. Enhanced oil recovery shows the strongest volume trajectory.
End User:
Customer type fragments procurement authority between integrated operators with enterprise chemical contracts and specialized contractors purchasing on a well-by-well basis.
- Exploration & Production Companies:Supermajors and national oil companies negotiate multi-year framework agreements spanning multiple basins. Saudi Aramco, ExxonMobil, and BP bundle chemical supply into integrated drilling-completion-production tenders that disintermediate regional distributors.
- Service Operators:Schlumberger, Halliburton, and Baker Hughes maintain captive blending capacity and technical field service networks. These firms capture margin through formulation customization and just-in-time logistics rather than commodity chemical sales.
- Drilling Contractors:Noble Corporation and Transocean specify drilling fluid chemistry through rig-level procurement.
- Midstream Firms:Pipeline operators and terminal owners purchase corrosion inhibitors and drag reducers for transportation infrastructure.
Exploration and production companies concentrate contract value. Service operators are gaining the fastest procurement influence through integrated service models.
Deployment:
Deployment environment governs logistics complexity, with offshore and subsea applications requiring certified chemistries and specialized supply vessels that constrain supplier eligibility.
- Offshore Platforms:Topside processing facilities in the Gulf of Mexico and North Sea require EPA NPDES-compliant and REACH-registered formulations. Discharge toxicity testing at lower dilution factors is forcing reformulation of biocides and corrosion inhibitors toward rapid biodegradation profiles.
- Subsea Installations:Unmanned wellheads and manifolds demand umbilical-compatible chemistries with decade-long stability in stagnant conditions. NORSOK M-001 compliance extends Norwegian North Sea qualification cycles to 18-24 months.
- Onshore Fields:Permian Basin tight-oil operations require intensive paraffin and scale management at 3-5x conventional dosage rates.
- Artificial Lift Systems:Rod pump and ESP applications need chemical compatibility with elastomer seals and motor fluids.
- Injection Wells:Waterflood and disposal well chemistry must maintain formation injectivity.
Offshore platforms anchor premium value pools. Subsea installations are expanding most quickly as deepwater development accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA's NPDES discharge regulations and REACH substance restrictions create divergent compliance frameworks across major producing regions. Chemical suppliers must maintain parallel formulation tracks to serve multiple regulatory jurisdictions simultaneously.
United States
Permian Basin tight-oil operations consume paraffin dispersants at dosage rates three to five times conventional crude systems. EPA's updated NPDES general permit mandates whole-effluent toxicity testing at lower dilution factors, compressing allowable quaternary ammonium compound discharge concentrations. Houston anchors the Gulf Coast chemical manufacturing corridor where hurricane-related ethylene oxide outages periodically disrupt surfactant precursor supply.
Brazil
Pre-salt deepwater developments drive specification tightening toward chemistries rated above 180°C and 15,000 psi. ANVISA oversees environmental licensing for offshore platform discharges alongside the national petroleum regulator. The Santos Basin cluster demands corrosion inhibitors with decade-long stability in subsea tieback conditions.
Saudi Arabia
SFDA enforces marine discharge limits that shape product registration requirements for offshore platform chemicals. Marjan expansion projects are integrating membrane-based separation systems that displace chemical demulsifiers in specific low-viscosity crude streams. The Eastern Province concentrates new blending facilities challenging traditional European supply bases.
Norway
NORSOK M-001 compliance extends product qualification cycles to 18-24 months for North Sea applications. ECHA's phased restrictions on persistent bioaccumulative toxins mandate bio-based demulsifier chemistry with higher unit economics. Stavanger and Bergen host technical service centers supporting subsea installation chemistry requirements.
China
Daqing and Shengli fields anchor expanding surfactant-polymer injection programs requiring precision-matched chemical choreography. MEE oversees environmental discharge standards for onshore production facilities. The Sichuan-Chongqing region concentrates shale gas development driving biocide demand for waterflood systems.
Global Oilfield Production Chemicals Market Competitive Landscape
Vertically integrated energy service conglomerates and specialized chemical manufacturers split the market into distinct capability tiers. The structure concentrates formulation supply among entities with captive blending networks and field service infrastructure. Three archetypes dominate: integrated oilfield service providers with in-house chemical manufacturing, diversified specialty chemical conglomerates serving multiple industrial verticals, and regional blenders focused on logistics-intensive onshore markets. Competitive moves center on enterprise-level framework agreements bundling chemical supply across multiple basins, and backward integration into ethylene oxide and surfactant precursor production to secure formulation continuity.
Among integrated service providers, Baker Hughes Company and Halliburton Company exemplify the captive-manufacturing archetype through Gulf Coast production networks and R&D intensity in high-pressure high-temperature formulations. Clariant AG represents the specialty chemical conglomerate model with concentrated expertise in bio-based demulsifier chemistry. These three entities occupy positions spanning formulation science, regulatory navigation, and just-in-time logistics coordination across Brazil's pre-salt, the Permian Basin, and the North Sea.
| Leading Market Players |
|---|
| Baker Hughes Company |
| Halliburton Company |
| BASF SE |
| Nouryon |
| The Lubrizol Corporation |
| Schlumberger Limited |
| Clariant AG |
| Solvay S.A. |
| Dow Inc. |
| Others |
Supply & Pricing Matrix
Gulf Coast ethylene oxide undercapacity following hurricane disruptions tightens surfactant precursor availability, forcing blenders to absorb input volatility while supermajors leverage enterprise contracts to lock in formulation continuity. This utilization squeeze transmits directly into supplier pricing power and procurement risk allocation across corrosion inhibitor and demulsifier tiers.
Pricing Analysis
Geographic price spreads widen substantially between North Sea certified formulations and Permian Basin commodity grades, reflecting divergent regulatory compliance burdens. Three-tier pricing structure across premium, standard, and economy levels segments by certification intensity and thermal stability rating, with HPHT-qualified chemistries commanding substantial premia over conventional offshore specifications. Cost compression in standard-tier demulsifiers is intensifying because membrane separation substitution in Saudi Arabian low-viscosity streams erodes volume-based pricing leverage. National oil companies exhibit lowest price sensitivity due to integrated tender structures, while independent Permian operators negotiate aggressively on paraffin dispersant unit economics.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now characterize supermajor procurement contracts, straining working capital for regional blenders lacking supply-chain finance facilities. Manufacturing concentrates in the United States, Saudi Arabia, and Norway, with each hub serving distinct regulatory jurisdictions and thermal stability specifications. Formulation chemistry draws from ethylene oxide, phosphonate intermediates, and bio-based surfactant feedstocks, creating multi-point input exposure. Single-source vulnerability concentrates in Gulf Coast ethylene oxide capacity where weather-related outages cascade through nonionic surfactant production. Distribution runs through integrated service contractors capturing logistics margin alongside formulation supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks the upstream capital expenditure cycle, with deepwater sanctioning momentum off Brazil and Guyana-Suriname signaling recovery-phase inventory rebuilding by chemical suppliers.
For Market Incumbents: Insulate formulation supply through captive ethylene oxide capacity or long-term offtake agreements with Gulf Coast producers, neutralizing hurricane-driven input volatility that disrupts competitor delivery schedules. Deepen technical service intensity in HPHT certification to defend against emerging bio-based specialists capturing REACH-mandated substitution demand. Prioritize NORSOK M-001 pre-qualification investments to extend qualification moats that freeze out smaller blenders from Norwegian North Sea tieback opportunities. For New Entrants and Emerging Players: Pursue white-space registration in Guyana-Suriname where ExxonMobil's discoveries lack established chemical supply infrastructure and first-mover qualification advantages remain available. Target Brazil's pre-salt demulsifier segment where high-water-cut production escalates consumption intensity faster than incumbent capacity expansion. Lead with bio-based chemistry platforms that preempt EPA NPDES permit renewal cycles and command unit economics premia over conventional formulations. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale blenders with existing NORSOK M-001 certification and established umbilical-compatible formulation libraries, assets that appreciate disproportionately as deepwater development accelerates. Long-term viability hinges on regulatory navigation capabilities spanning REACH, EPA NPDES, and SFDA discharge frameworks rather than commodity scale alone. Watch HPHT formulation chemist hiring velocity at integrated service providers as the inflection signal for R&D throughput constraints easing or tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide | Secures surfactant precursor continuity against Gulf Coast weather disruptions that cascade through formulation supply. |
| HPHT Certification Pre-Qualification | Captures Brazil pre-salt and Norway subsea demand where thermal stability requirements exceed 180°C thresholds. |
| Bio-Based Demulsifier Platform Development | Aligns with REACH substance restrictions and EPA NPDES toxicity testing mandates that compress conventional chemistry margins. |
| Integrated Service Contracting Expansion | Bundles chemical supply into drilling-completion-production packages that transfer inventory risk from supermajors to suppliers. |
| Guyana-Suriname Registration First-Mover Investment | Establishes formulation qualification ahead of infrastructure buildout for ExxonMobil's multi-billion-barrel discoveries. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with chemical plant managers, supermajor procurement leads, HPHT formulation chemists, and subsea installation engineers; and secondary validation through SEC 10-K filings, customs and trade data, EPA NPDES permit databases, and ECHA REACH restriction announcements. Bottom-up volume estimates by product chemistry and application were triangulated against top-down spending patterns reported by national oil companies and integrated operators.
Forecast inputs considered HPHT reservoir development trajectories, REACH-driven substitution timelines, and tight-oil paraffin management intensity across the projection horizon. Segmentation modeling incorporated product chemistry tiers, deployment environment specifications, end-user procurement authority structures, and regional regulatory clusters. CAGRs were derived from elasticity-adjusted demand curves reflecting dosage rate intensification and formulation premium capture.
Sensitivities concentrate around ethylene oxide supply disruptions, deepwater project sanctioning delays, and regulatory divergence acceleration between EPA NPDES and REACH frameworks. Forecasts reflect assumptions regarding continued tight-oil production growth and pre-salt development momentum. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Performance Chemicals
Asia-Pacific Hydrogen Peroxide Market
Performance Chemicals
Global Reflective Materials Market
Performance Chemicals
Chemical Feed Systems Market
Performance Chemicals
High Performance Plastics Market
Performance Chemicals
Global High Performance Polyamides Market
Performance Chemicals
Mecoprop Market
Performance Chemicals
High Performance Epoxy Market
Performance Chemicals
Global High Performance Polymers Market