
 Mecoprop Market | 2026-2036
Mecoprop Market Size, Share, and Industry Trends Forecast 2026-2036
Mecoprop Market Foresight
The capital-intensity divergence between integrated manufacturers and formulation specialists is reorganizing competitive dynamics in the mecoprop sector. BASF SE leverages its backward integration into chlorophenoxy acid precursors to sustain margin stability across herbicide blends. Syngenta AG anchors its position through proprietary adjuvant technologies that enhance mecoprop uptake in cool-season grasses. Nufarm Limited competes on geographic reach, with manufacturing assets positioned to serve Australian and North American turf markets without cross-border tariff exposure.
Mecoprop, a chlorophenoxy herbicide of the phenoxypropionic acid class, functions as a systemic post-emergent selective agent that mimics auxin growth hormones to disrupt broadleaf weed development in turf and lawns while preserving monocotyledonous grasses. Commercial formulations typically contain the racemic mixture or purified R-enantiomer (mecoprop-P) at acid equivalent concentrations ranging from 37% to 60% in liquid concentrates. Liquid concentrate formulations command the widest addressable footprint due to their compatibility with spray tank mixing systems and retail shelf presence, though emulsifiable concentrate variants retain preference among professional applicators seeking extended foliar adhesion. Turf management applications generate the most durable demand pull, driven by recurring maintenance cycles across municipal parks, golf courses, and residential lawn care contracts where seasonal reapplication creates predictable offtake.
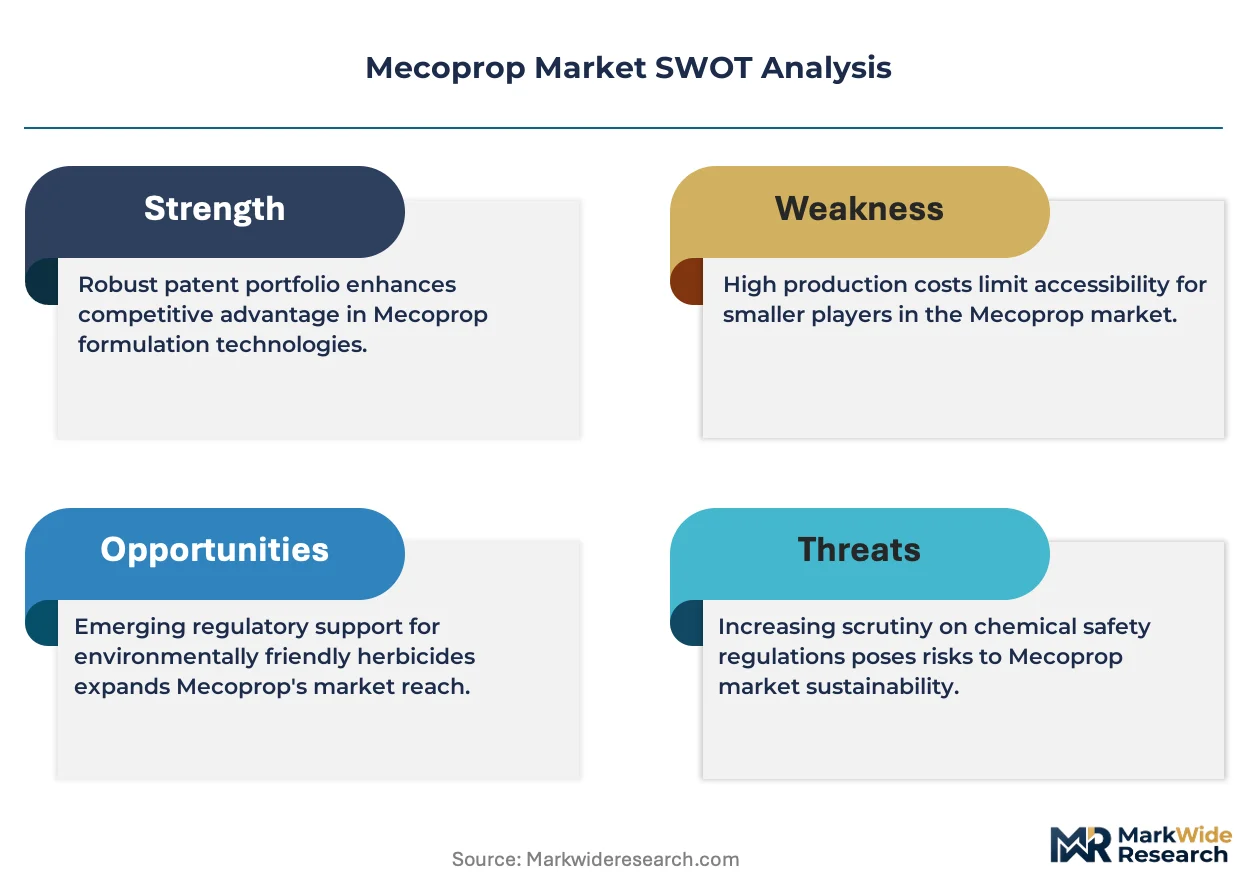
The EPA governs mecoprop registration under FIFRA, with re-registration eligibility decisions dictating label restrictions on application rates and buffer zones near aquatic ecosystems. REACH compliance in Europe mandates full substance dossiers for phenoxy herbicide imports, creating documentation barriers for non-EU formulators seeking market access. The EU Green Deal's Farm to Fork strategy targets synthetic pesticide reduction thresholds, pressuring mecoprop inclusion in integrated weed management protocols rather than standalone broadcast programs. Stakeholders must monitor regulatory divergence between jurisdictions that preserve phenoxy herbicide access and those accelerating substitution timelines, as this split will determine where formulation investments concentrate and which product registrations retain long-term commercial viability.
Market Dynamics
EPA's re-registration review of phenoxy herbicides under FIFRA is compressing formulation flexibility and forcing blend redesigns across North American turf management, while the EU Green Deal's Farm to Fork pesticide reduction targets are accelerating integrated weed management adoption in European markets.
Growth Catalysts
- Turf maintenance intensity:Golf courses and sports fields in the United States are intensifying weed control protocols, creating recurring demand cycles for selective herbicide applications.
- REACH compliance architecture:European substance dossier requirements for phenoxy herbicide imports create documentation barriers that favor established formulators with regulatory infrastructure.
- Adjuvant technology advancement:Proprietary uptake enhancement systems for cool-season grasses are improving mecoprop efficacy and extending application windows.
Market Restraints
- Chlorophenoxy acid precursor concentration:Backward-integrated manufacturers control critical raw material supply, squeezing margin flexibility for standalone formulation specialists.
- Aquatic buffer zone restrictions:EPA label limitations near water bodies reduce treatable acreage for municipal park and golf course applicators.
- Synthetic pesticide substitution pressure:Bioherbicide alternatives and mechanical weed control systems are capturing share in organic-certified turf segments.
Strategic Opportunities
- Integrated weed management protocols:EU Green Deal Farm to Fork mandates are creating demand for mecoprop as a component in rotation programs rather than standalone broadcast applications.
- Emulsifiable concentrate premiumization:Professional applicators seeking extended foliar adhesion are shifting toward EC variants with higher margin profiles.
- Australian turf export corridor:Manufacturing assets positioned to serve Australian markets without cross-border tariff exposure capture margin advantages in Pacific region distribution.
Industry Challenges
- Regulatory divergence management:Formulators must maintain parallel registration dossiers for jurisdictions preserving phenoxy herbicide access versus those accelerating substitution timelines.
- R-enantiomer purification capex:Investment in chiral separation technology for mecoprop-P production requires significant capital deployment with extended payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mecoprop Market |
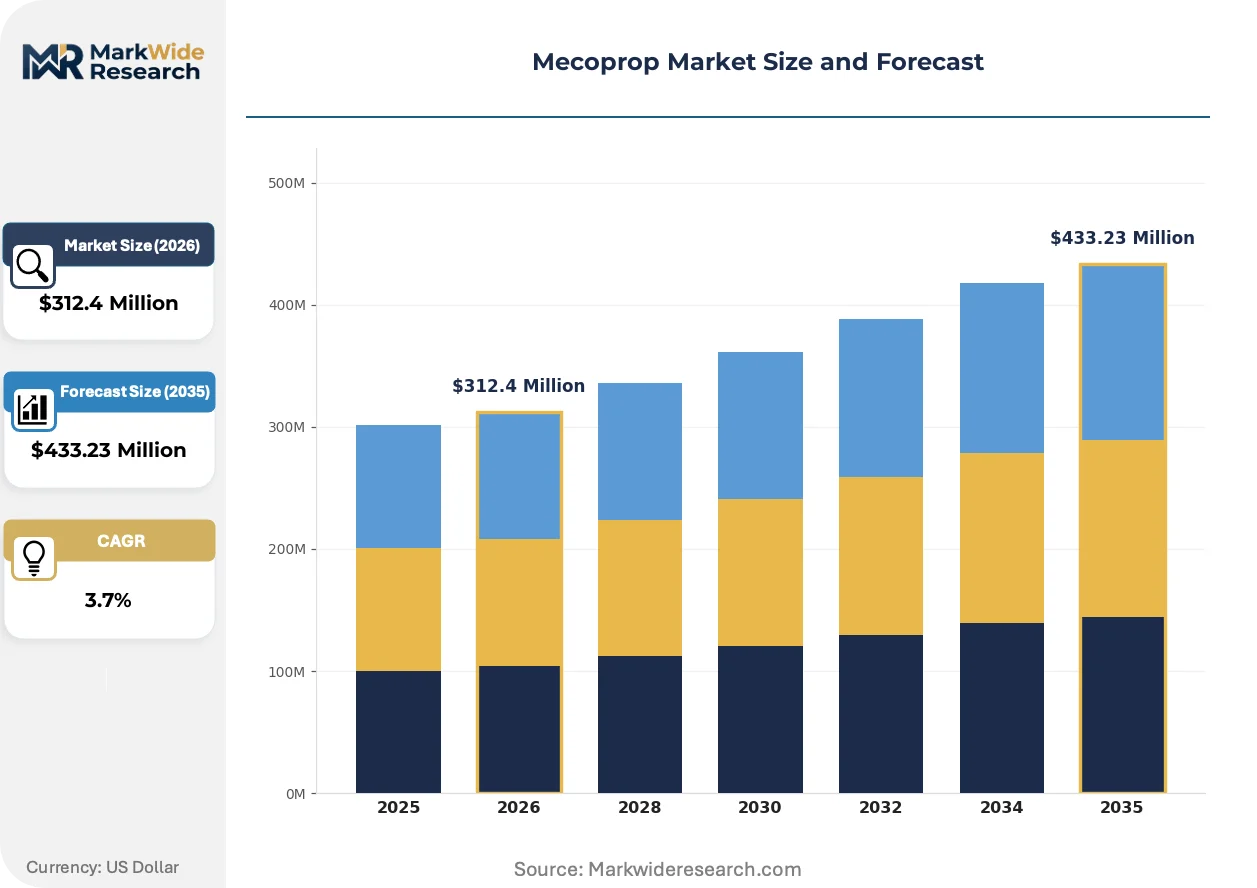
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $433.23 Million |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Liquid Concentrate, Soluble Powder, Emulsifiable Concentrate Application: Agricultural Crops, Turf Management, Ornamental Plants, Industrial Areas End User: Agricultural Producers, Landscape Professionals, Lawn Care Companies, Government Agencies Distribution Channel: Online Retail, Direct Sales, Wholesale Distribution, Agricultural Supply Stores |
| Companies Covered | BASF SE, Syngenta AG, Bayer CropScience, Corteva Agriscience, Nufarm Limited, FMC Corporation, ADAMA Agricultural Solutions Ltd., UPL Limited, Dow AgroSciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mecoprop Market Shifts & Advancements
Formulation chemistry and application precision are converging to reshape competitive positioning in selective herbicide markets, with regulatory compliance costs and efficacy demands driving technology investment priorities.
Chiral separation technology for R-enantiomer purification is displacing racemic mixture formulations in premium turf segments. Golf course superintendents and high-end lawn care services are adopting mecoprop-P concentrates at accelerated rates. This displacement is compressing margin pools for standard-grade formulators while rewarding producers with in-house chiral synthesis capability.
REACH substance dossier requirements and EU Green Deal pesticide reduction frameworks are tightening market access conditions. Full chemical characterization and environmental fate documentation now constitute significant entry costs for non-EU suppliers. Formulation specialists with established European regulatory infrastructure are consolidating share as new entrants face documentation barriers.
Service-based procurement contracts are replacing transactional product purchases in municipal and commercial turf management. Lawn care operators and park maintenance departments are bundling herbicide supply with application scheduling and efficacy guarantees. This shift is most pronounced in United States metropolitan markets where contract penetration remains highest globally.
Mecoprop Market Segmentation
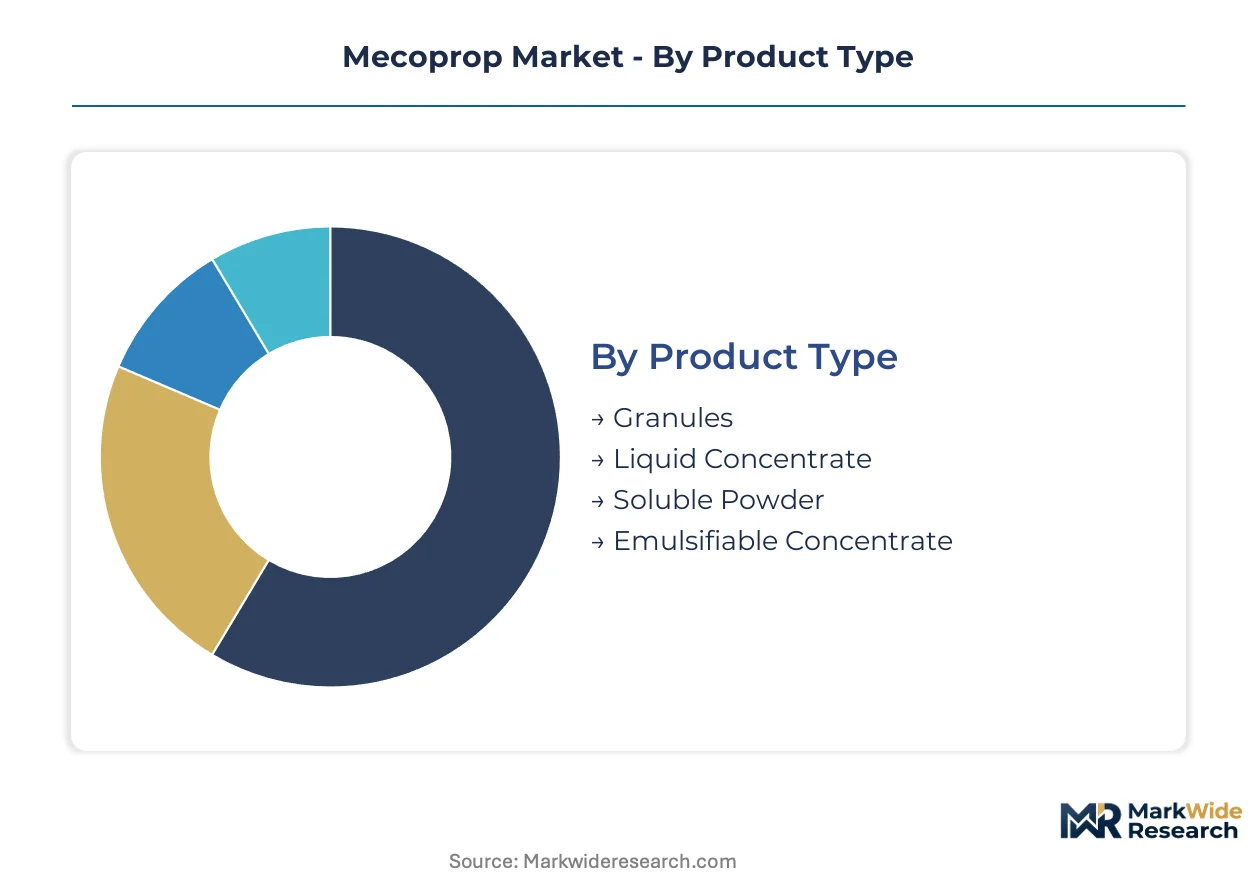
Mecoprop formulations diverge sharply across product types and application contexts, with regulatory pressure on phenoxy herbicides reshaping which segments command investment priority. Understanding these fault lines clarifies where margin pools concentrate and which customer relationships offer durable revenue.
Product Type:
REACH dossier requirements and EPA label restrictions differentiate formulation viability across regulatory jurisdictions, concentrating commercial advantage with producers possessing multi-territory registration infrastructure.
- Liquid Concentrate:Formulations containing 37% to 60% acid equivalent in aqueous solution dominate retail shelf presence and spray tank compatibility. Municipal park departments in the United States specify liquid concentrates for recurring broadleaf control programs, though aquatic buffer zone restrictions constrain treatable acreage near water features.
- Emulsifiable Concentrate:Oil-based carriers with extended foliar adhesion properties command premium positioning among professional applicators. Golf course superintendents favor EC variants for cool-season grass efficacy, particularly where adjuvant-enhanced uptake justifies higher per-acre treatment costs.
- Granules:Slow-release particulate formulations suit broadcast spreader application in residential lawn care contracts.
- Soluble Powder:Dry concentrate formats reduce shipping weight for export markets with freight cost sensitivity.
Established volume favors Liquid Concentrate; emerging adoption favors Emulsifiable Concentrate.
Application:
End-use intensity varies dramatically by maintenance cycle frequency and certification requirements, with recurring seasonal demand separating durable revenue streams from one-off procurement.
- Turf Management:Golf courses, sports fields, and municipal parks generate predictable reapplication cycles through seasonal weed control protocols. United States metropolitan markets exhibit the highest lawn care service penetration globally, anchoring demand concentration for selective herbicide programs.
- Agricultural Crops:Pasture and forage applications utilize mecoprop for broadleaf weed suppression in grass-based systems. Australian producers represent a distinct demand pocket where manufacturing assets positioned without cross-border tariff exposure capture margin advantages.
- Ornamental Plants:Nursery and landscape maintenance applications require precision application to avoid phytotoxicity on desirable broadleaf specimens.
- Industrial Areas:Rights-of-way and utility corridor maintenance programs specify phenoxy herbicides for vegetation management.
Turf Management retains the deepest recurring revenue; Agricultural Crops offers the steepest expansion trajectory in Pacific region distribution.
End User:
Procurement sophistication separates volume purchasers with technical specification capability from price-sensitive retail buyers, reshaping service bundling requirements across customer tiers.
- Lawn Care Companies:Service-based contractors bundle herbicide supply with application scheduling and efficacy guarantees. United States metropolitan markets show the most pronounced shift from transactional purchases to outcome-based contracts.
- Landscape Professionals:Design-build and maintenance firms specify formulations based on ornamental plant safety profiles and re-entry interval requirements.
- Agricultural Producers:Pasture managers prioritize cost-per-acre metrics and tank-mix compatibility with fertilizer applications.
- Government Agencies:Municipal park departments and transportation authorities operate under public procurement rules with extended vendor qualification timelines.
Commercial service providers concentrate margin capture; institutional buyers concentrate volume throughput.
Distribution Channel:
Channel economics reflect customer technical support needs and order fragmentation patterns, with direct relationships commanding premium positioning in professional segments.
- Wholesale Distribution:Regional agrichemical distributors maintain inventory positions and technical field support for professional applicators. EPA label complexity and state-level registration variations favor distributors with regulatory compliance infrastructure.
- Direct Sales:Manufacturer relationships with national lawn care chains and municipal procurement departments bypass margin-sharing intermediaries. Contract penetration in United States metropolitan markets drives direct channel investment.
- Agricultural Supply Stores:Independent retailers serve hobby farmers and residential lawn care purchasers with smaller pack sizes.
- Online Retail:E-commerce platforms capture price-comparison shoppers with limited technical consultation requirements.
Professional-grade volume flows through Wholesale Distribution; emerging procurement patterns favor Direct Sales consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in mecoprop formulations tilt toward net-importing markets with intensive turf maintenance regimes, while manufacturing concentration in select chemical clusters shapes regional supply reliability.
United States
Municipal park departments and golf course superintendents drive recurring seasonal demand for selective herbicide programs. EPA's FIFRA re-registration review compresses formulation flexibility and mandates buffer zone restrictions near aquatic ecosystems. Metropolitan markets across the Sun Belt and Midwest exhibit the highest lawn care service contract penetration globally.
Germany
REACH compliance infrastructure and substance dossier requirements favor established formulators with regulatory documentation capabilities. ECHA's phenoxy herbicide evaluation timelines influence label restrictions across the European Economic Area. The Rhine-Ruhr chemical corridor anchors backward-integrated production of chlorophenoxy acid precursors.
Australia
Pasture and forage applications in grass-based livestock systems sustain steady offtake for broadleaf weed suppression. The country's national agricultural chemical regulator maintains stringent import documentation parallel to REACH-equivalent standards. Manufacturing assets positioned to serve Australian markets without cross-border tariff exposure capture margin advantages in Pacific distribution.
United Kingdom
Professional lawn care contractors and municipal grounds maintenance departments generate predictable reapplication cycles. Post-Brexit divergence from EU pesticide approval frameworks creates parallel registration requirements for formulators. The Southeast England turf production cluster around Cambridgeshire supplies certified sod to sports stadium and golf course developers.
France
Nursery and landscape maintenance applications require precision formulations to avoid phytotoxicity on ornamental broadleaf specimens. The EU Green Deal's Farm to Fork strategy accelerates integrated weed management adoption, pressuring mecoprop inclusion in rotation programs. The Pays de la Loire ornamental plant production region concentrates demand for selective herbicide safety profiles.
Mecoprop Market Competitive Landscape
Concentration sits with backward-integrated agrochemical conglomerates that control chlorophenoxy acid precursor supply. The vendor base stratifies across three tiers: multinational conglomerates with captive raw material production, regional formulation specialists with regulatory infrastructure depth, and generic manufacturers competing on price. Dominant competitive moves include capacity consolidation in high-barrier jurisdictions and technology licensing for chiral separation capabilities.
Among European-based chemical conglomerates, BASF SE and Syngenta AG exemplify the integrated archetype with upstream control over phenoxypropionic acid synthesis. Nufarm Limited occupies a position among Asia-Pacific-anchored formulators with geographic manufacturing dispersion. These three entities represent the competitive core around which regional specialists and generic suppliers organize their market participation.
| Leading Market Players |
|---|
| BASF SE |
| Syngenta AG |
| Bayer CropScience |
| Corteva Agriscience |
| Nufarm Limited |
| FMC Corporation |
| ADAMA Agricultural Solutions Ltd. |
| UPL Limited |
| Dow AgroSciences |
| Others |
Supply & Pricing Matrix
Chlorophenoxy acid precursor capacity utilization at BASF's Ludwigshafen complex and Syngenta's Monthey facility shapes both supply concentration and price floors across mecoprop formulations. These integrated producers leverage captive raw material production to maintain margin stability while squeezing standalone formulation specialists facing volatile spot market inputs.
Pricing Analysis
Professional lawn care contractors anchor pricing stratification across premium, standard, and economy tiers in the United States metropolitan markets. Price differentiation rests on chiral purity grade and EPA registration tier, with mecoprop-P concentrates commanding substantial premiums over racemic mixtures. Cost compression in standard-grade formulations is intensifying because backward-integrated manufacturers control precursor supply. Municipal park departments exhibit highest price sensitivity due to public procurement constraints, while golf course superintendents demonstrate lowest sensitivity where efficacy guarantees justify per-acre premiums.
Supply Chain Analysis
Germany and the United States anchor chlorophenoxy acid precursor production through the Rhine-Ruhr chemical corridor and Gulf Coast petrochemical complexes. Formulation draws from 2,4-D acid intermediates, propionic acid derivatives, and proprietary adjuvant packages. Single-source vulnerability concentrates in European substance dossier holders under REACH, where ECHA documentation requirements create regulatory moats. Distribution runs through regional agrichemical distributors with EPA label compliance infrastructure, though direct sales channels are consolidating share among national lawn care chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from application scheduling and efficacy guarantee contracts is expanding faster than standalone herbicide product sales, particularly in United States metropolitan markets where outcome-based procurement now dominates.
For Market Incumbents: Compound defensive positioning through chiral separation technology investment and captive precursor capacity expansion in high-barrier jurisdictions. Bioherbicide substitution pressure in organic-certified turf segments threatens racemic mixture volume, making backward integration into phenoxypropionic acid synthesis the priority lever for margin defense. For New Entrants and Emerging Players: Anchor in Australian pasture and forage applications where tariff-exposed manufacturing assets capture Pacific distribution advantages. The most penetrable white space sits in emulsifiable concentrate premiumization for professional golf course applicators, accessible through adjuvant technology licensing partnerships rather than greenfield synthesis investment. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors formulators with established REACH dossier infrastructure and in-house chiral synthesis capability. Long-term viability hinges on regulatory divergence management between jurisdictions preserving phenoxy herbicide access versus those accelerating substitution timelines. Watch EPA FIFRA re-registration eligibility decisions as the critical inflection signal for North American asset valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Chiral Separation Technology Investment | Mecoprop-P purification capability captures premium turf segment pricing power from racemic mixture displacement. |
| Backward Integration into Precursor Synthesis | Captive chlorophenoxy acid production insulates margin stability from spot market volatility. |
| REACH Dossier Infrastructure Expansion | Full substance documentation creates regulatory barriers against non-EU generic entrants. |
| Service-Based Contract Bundling | Application scheduling and efficacy guarantees lock in recurring revenue with municipal and golf course accounts. |
| Geographic Manufacturing Dispersion | Australian and North American production assets eliminate cross-border tariff exposure in Pacific distribution. |
Research Methodology
A standing panel of turf management superintendents, lawn care service procurement directors, agrichemical distribution channel managers, and EPA regulatory affairs specialists provided ongoing calibration throughout the study. Primary interview insights combined with secondary validation from EPA FIFRA registration databases, ECHA substance dossier filings, customs trade flow records, and SEC 10-K agrichemical segment disclosures. Bottom-up volume builds across formulation types and application segments triangulated against top-down market sizing from producer capacity disclosures.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework modeled segmentation across formulation chemistry tier, end-use application intensity, regional regulatory cluster, and chiral purity grade. CAGRs derived from historical shipment patterns, capacity expansion announcements, and substitution elasticity estimates for bioherbicide alternatives. Forecast inputs incorporated EPA re-registration timelines, EU Green Deal pesticide reduction mandates, and turf maintenance contract penetration rates in United States metropolitan markets.
Material uncertainties — EPA label restriction severity, ECHA phenoxy herbicide evaluation outcomes, and bioherbicide substitution acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory continuity and turf maintenance cycle stability. Recalibration cycles align with material shifts in FIFRA re-registration decisions and Farm to Fork implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Performance Chemicals
Global Oilfield Production Chemicals Market
Performance Chemicals
Global High Performance Polymers Market
Performance Chemicals
Global High Performance Polyamides Market
Performance Chemicals
Global Reflective Materials Market
Performance Chemicals
Chemical Feed Systems Market
Performance Chemicals
High Performance Plastics Market
Performance Chemicals
Asia-Pacific Hydrogen Peroxide Market
Performance Chemicals
High Performance Epoxy Market