
 Asia-Pacific Hydrogen Peroxide Market | 2026-2036
Asia-Pacific Hydrogen Peroxide Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Hydrogen Peroxide Market Insights
Pulp and paper demand is rebalancing toward electronics and water treatment as semiconductor fabrication and municipal infrastructure expand across the region. Arkema leverages its specialty peroxide portfolio to serve high-purity electronics applications in South Korea and Taiwan. TAEKWANG INDUSTRIAL CO LTD anchors Korean supply through integrated hydrogen peroxide-to-caprolactam production at its Ulsan complex. Solvay competes on technology leadership in ultra-high-purity grades for advanced chip nodes.
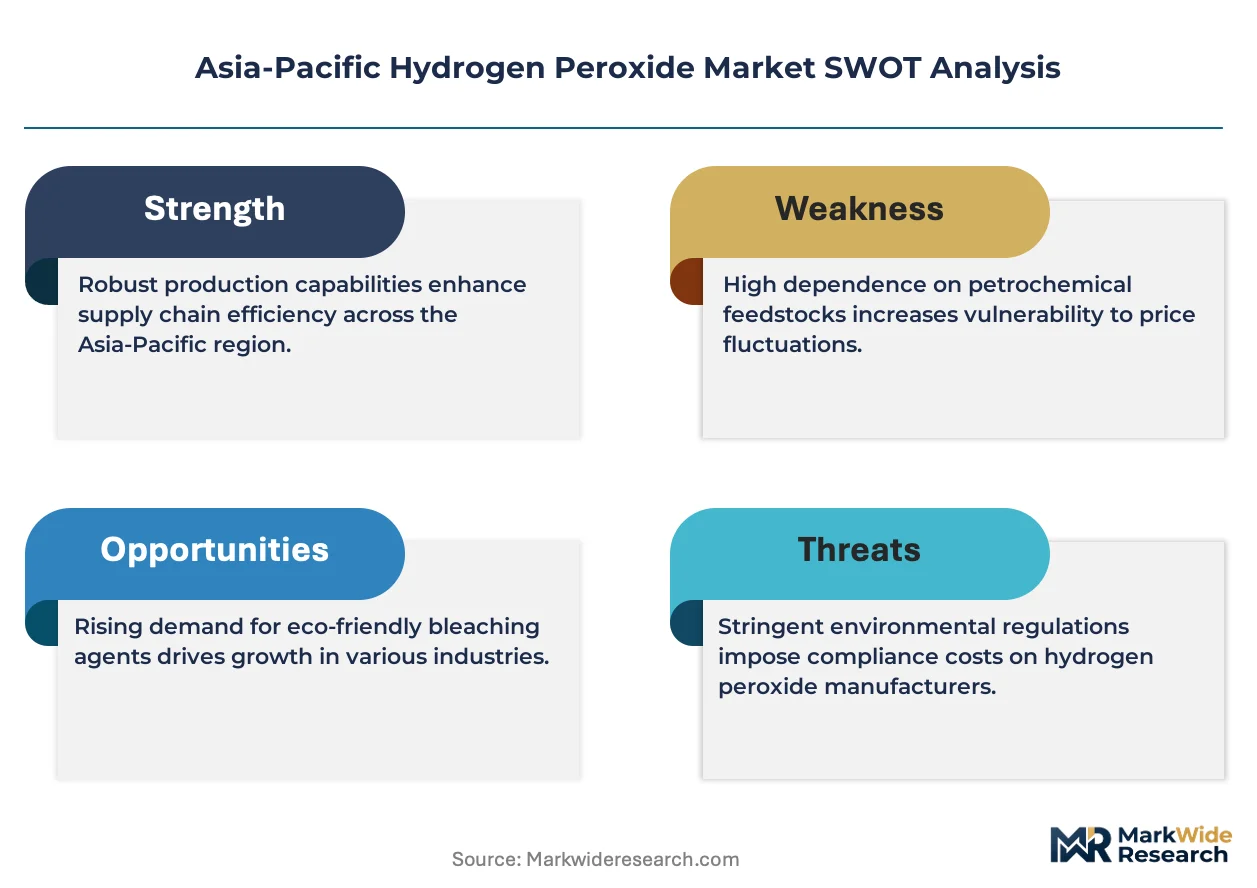
Hydrogen peroxide is an inorganic peroxide compound with the chemical formula H₂O₂, typically manufactured through the anthraquinone auto-oxidation process and supplied in concentrations ranging from dilute aqueous solutions to concentrated grades above 70 percent for specialized industrial use. Its primary commercial purpose centers on oxidation, bleaching, and sterilization across pulp processing, textile finishing, wastewater treatment, and semiconductor wafer cleaning. Concentrated solution grades command the strongest margin pools due to purity requirements in electronics manufacturing, while stabilized formulations dominate volume through pulp and paper bleaching. The electronics application segment is expanding fastest as foundries in Taiwan and South Korea scale advanced node capacity.
China's MEE enforces stricter COD discharge limits that directly expand hydrogen peroxide demand in textile and paper mill effluent treatment. Japan's METI chemical substance management framework and South Korea's K-REACH alignment with EU chemical safety standards shape product registration and import compliance costs. India's CDSCO and BIS quality mandates govern peroxide grades entering pharmaceutical and food-contact applications. Stakeholders must monitor how divergent national chemical safety implementations across China, Japan, South Korea, and India reshape formulation requirements and cross-border certification burdens.
Market Dynamics
Electronics-grade hydrogen peroxide demand is concentrating in South Korea and Taiwan as semiconductor foundries advance to sub-3nm nodes, tightening purity specifications and reshaping supplier qualification timelines across the Asia-Pacific supply base.
Growth Catalysts
- MEE Wastewater Rules:China's Ministry of Ecology and Environment enforces stricter COD discharge limits for textile and paper mills, mandating chlorine-free bleaching chemistry that expands peroxide consumption in effluent treatment systems.
- Semiconductor Node Migration:Advanced chip fabrication in Hsinchu and Pyeongtaek requires ultra-high-purity hydrogen peroxide for wafer cleaning, creating specification premiums that pull investment toward electronics-grade capacity.
- Caprolactam Integration:Korean and Chinese chemical corridors deepen captive peroxide-to-derivative production, locking in dedicated offtake and stabilizing regional supply security.
Market Restraints
- Anthraquinone Feedstock Volatility:Hydrogen peroxide production depends on 2-alkylanthraquinone and hydrogen supply, with energy-intensive hydrogen generation exposing margins to electricity cost swings in China and India.
- K-REACH Registration Burden:South Korea's chemical substance management framework imposes compliance costs on imported formulations, creating friction for non-Korean suppliers seeking electronics-grade market entry.
- Peracetic Acid Substitution:Food and beverage sterilization applications in Japan and Australia increasingly specify peracetic acid blends, displacing standard peroxide in select downstream segments.
Strategic Opportunities
- India Pharmaceutical Grade Expansion:CDSCO and BIS quality mandates for hydrogen peroxide entering drug synthesis and medical device sterilization create certification-driven entry barriers that favor early compliance investment.
- Green Hydrogen Coupling:Electrolytic hydrogen production linked to renewable energy projects in Australia and Japan enables carbon-intensity claims for peroxide sold into EU-destined exports.
- On-Site Generation Systems:Modular electrochemical peroxide synthesis units allow pulp mills and electronics fabs to reduce transport costs and inventory risk, opening equipment-plus-chemistry service models.
Industry Challenges
- Semiconductor Fab Qualification Timelines:Electronics-grade certification requires 18-24 month validation cycles with foundry customers, compressing supplier cash conversion and demanding sustained technical service investment.
- Cross-Border Formulation Harmonization:Divergent national implementations of chemical safety standards across China, Japan, South Korea, and India force producers to maintain multiple product specifications, fragmenting batch economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Hydrogen Peroxide Market |
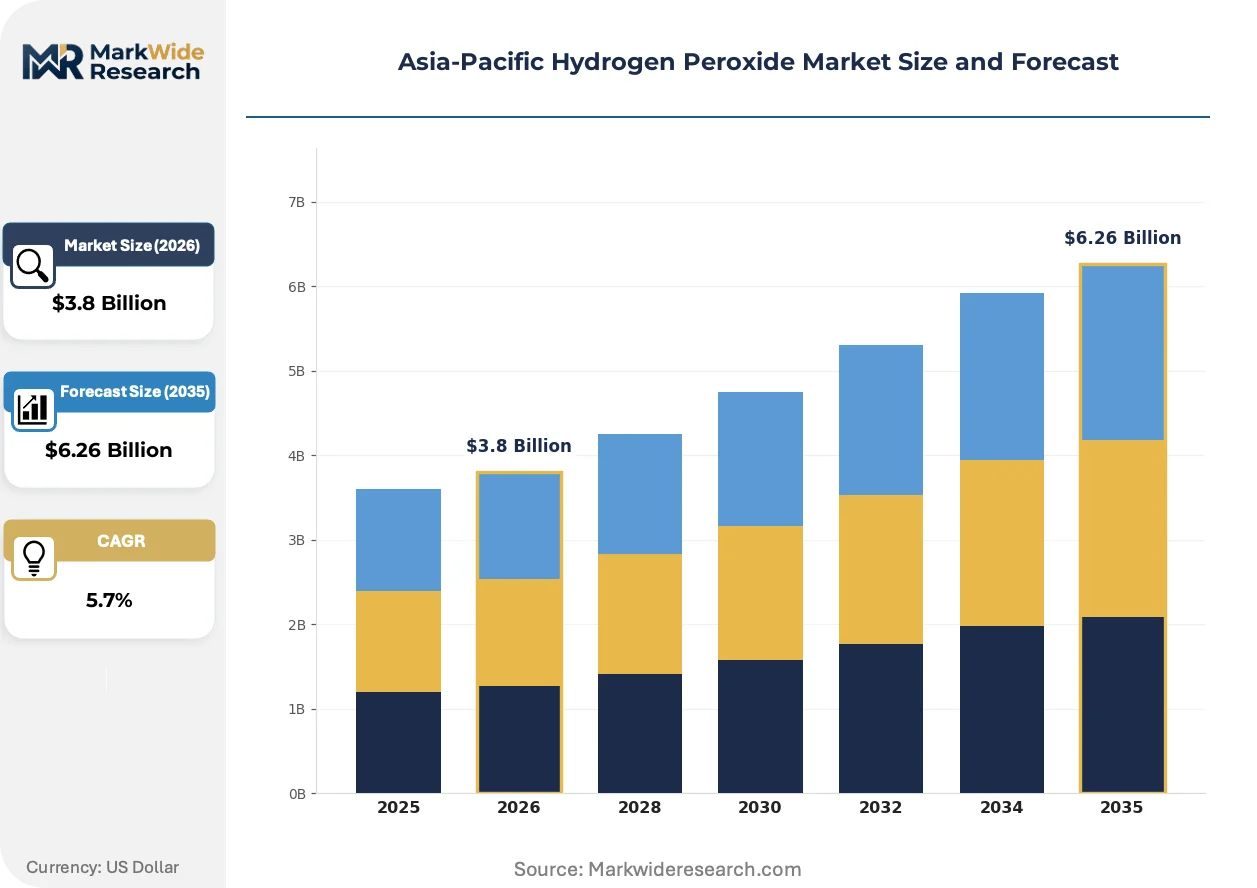
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stabilized, Weak Solution, Concentrated Solution, Anhydrous Application: Pulp & Paper, Textile, Water Treatment, Electronics End User: Industrial, Healthcare, Agriculture, Household Delivery Mode: Liquid, Solid, Gas, Others |
| Companies Covered | Arkema, TAEKWANG INDUSTRIAL CO LTD, Hodogaya Chemical Co Ltd, Evonik Industries AG, MITSUBISHI GAS CHEMICAL COMPANY INC, HENAN JINHE INDUSTRY CO LTD, Solvay, National Peroxide Limited, AkzoNobel N V, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Hydrogen Peroxide Market Trends and Innovations
Process intensification and regulatory tightening are converging to transform how hydrogen peroxide is manufactured, certified, and delivered across the Asia-Pacific region.
Membrane electrolysis for on-site hydrogen peroxide generation is rewriting supply economics for remote industrial clusters. Australian mining operations and Indonesian pulp facilities pilot containerized electrochemical units that eliminate concentrated peroxide transport from centralized anthraquinone plants. This distributed production model compresses working capital requirements and reduces hazmat logistics exposure for buyers in archipelago geographies.
METI's chemical substance management framework in Japan tightens reporting thresholds for hydrogen peroxide derivatives used in semiconductor cleaning formulations. The policy accelerates substitution toward pre-stabilized, trace-metal-controlled grades that reduce downstream effluent treatment burden. Japanese electronics chemical distributors respond by consolidating supplier panels to those with documented substance flow accountability.
Foundry procurement teams in Taiwan and South Korea now specify total cost-of-ownership contracts that bundle hydrogen peroxide supply with spent chemical recovery and reprocessing services. This performance-based sourcing displaces traditional volume-offtake agreements and shifts supplier selection toward integrated chemical management providers. The model concentrates most visibly at Samsung and TSMC supplier days, where sustainability metrics weight alongside purity specifications.
Asia-Pacific Hydrogen Peroxide Market Segmentation
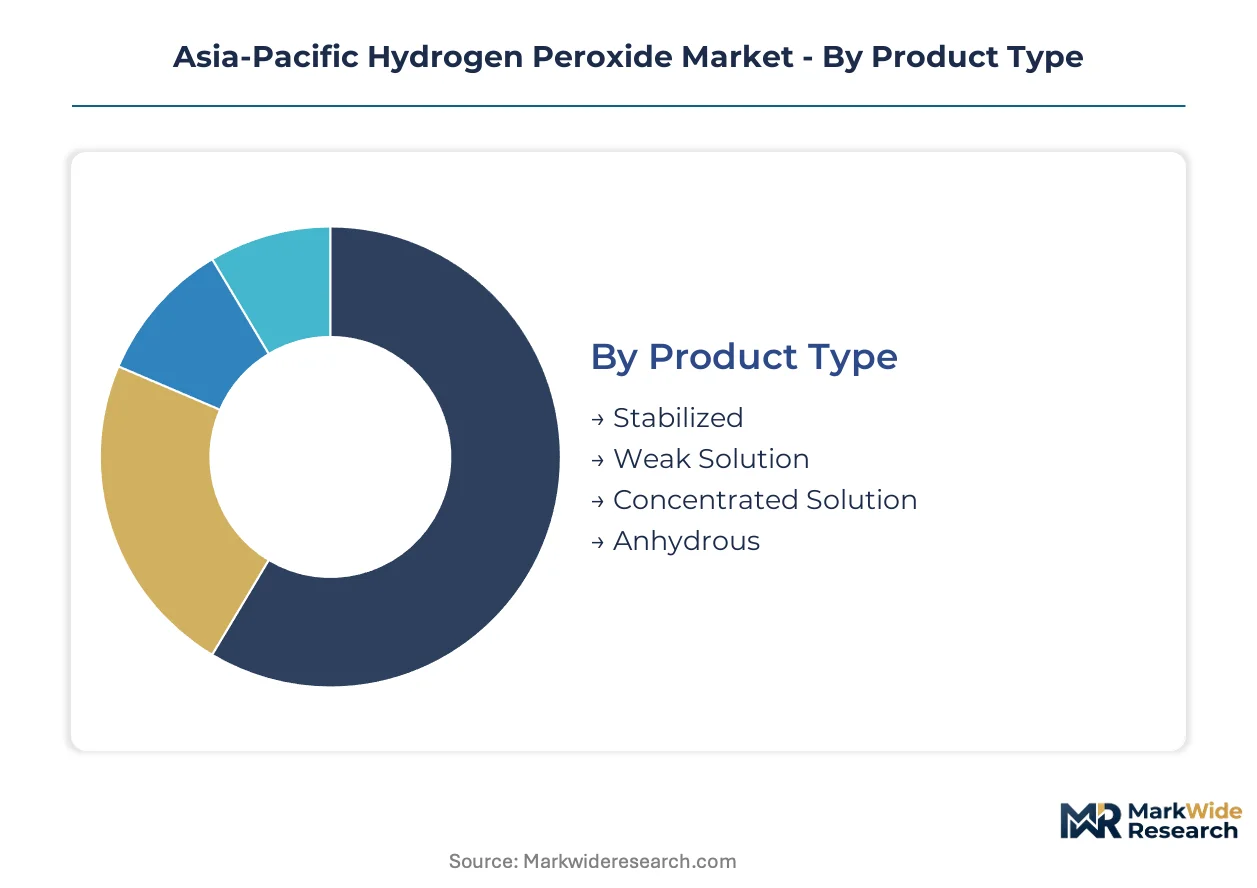
Segmentation in the Asia-Pacific hydrogen peroxide market reflects divergent purity requirements and delivery constraints across electronics fabrication, pulp bleaching, and pharmaceutical sterilization. Buyers select grades based on trace-metal specifications, concentration thresholds, and compatibility with existing dosing infrastructure.
Product Type:
Purchasers prioritize concentration stability and shelf-life performance when selecting product grades for their specific oxidation chemistry.
- Stabilized:Formulations incorporate phosphates or stannates to suppress decomposition during storage and transport. Pulp mills across eastern China specify stabilized grades for continuous bleaching sequences under MEE discharge compliance timelines.
- Concentrated Solution:Grades exceeding 70 percent concentration serve semiconductor wafer cleaning in Hsinchu and Pyeongtaek fabs, where sub-ppb trace-metal limits justify specification premiums and extended supplier qualification cycles.
- Weak Solution:Dilute aqueous formulations below 30 percent concentration support household disinfection and small-scale textile processing across Southeast Asian manufacturing clusters.
- Anhydrous:Water-free peroxide enables specialized organic synthesis and propellant applications with stringent moisture sensitivity requirements.
Volume sits with stabilized formulations for pulp and paper; growth tilts toward concentrated solutions for electronics-grade applications.
Application:
End-use selection tracks regional industrial structure, with semiconductor investment patterns in Taiwan and South Korea diverging from pulp capacity expansion in China and Indonesia.
- Electronics:Ultra-high-purity peroxide removes photoresist and particulate contamination from silicon wafers during advanced node fabrication. TSMC and Samsung foundries in Hsinchu and Pyeongtaek drive specification tightening for trace metals and particle counts.
- Pulp & Paper:Chlorine-free bleaching sequences rely on peroxide for delignification and brightening. Chinese mills under MEE COD discharge mandates convert from chlorine-based chemistry, expanding peroxide demand in Shandong and Guangdong provinces.
- Water Treatment:Advanced oxidation processes degrade refractory organics in textile dyehouse effluent and municipal wastewater across Indian industrial corridors.
- Textile:Bleaching and desizing operations in Bangladesh and Vietnam apparel manufacturing consume standard-grade peroxide for cotton preparation.
Electronics commands the steepest expansion trajectory; pulp and paper retains the largest absolute consumption base.
End User:
Customer-type segmentation reveals how regulatory frameworks shape grade requirements and certification burdens across divergent downstream channels.
- Industrial:Chemical manufacturing, mining, and metallurgical operations consume bulk peroxide for oxidation reactions and effluent treatment. Korean caprolactam producers at Ulsan anchor captive demand through backward-integrated anthraquinone units.
- Healthcare:Sterilization-grade peroxide for medical device disinfection and pharmaceutical synthesis faces CDSCO and BIS quality mandates in India, creating compliance-driven supplier selection.
- Agriculture:Seed treatment and soil fumigation applications in Australian broadacre farming specify stabilized formulations compatible with irrigation injection systems.
- Household:Consumer disinfectant and laundry applications across Southeast Asian retail channels favor dilute, pre-packaged solutions with extended shelf stability.
Industrial buyers absorb the highest tonnage; healthcare certification requirements are climbing fastest.
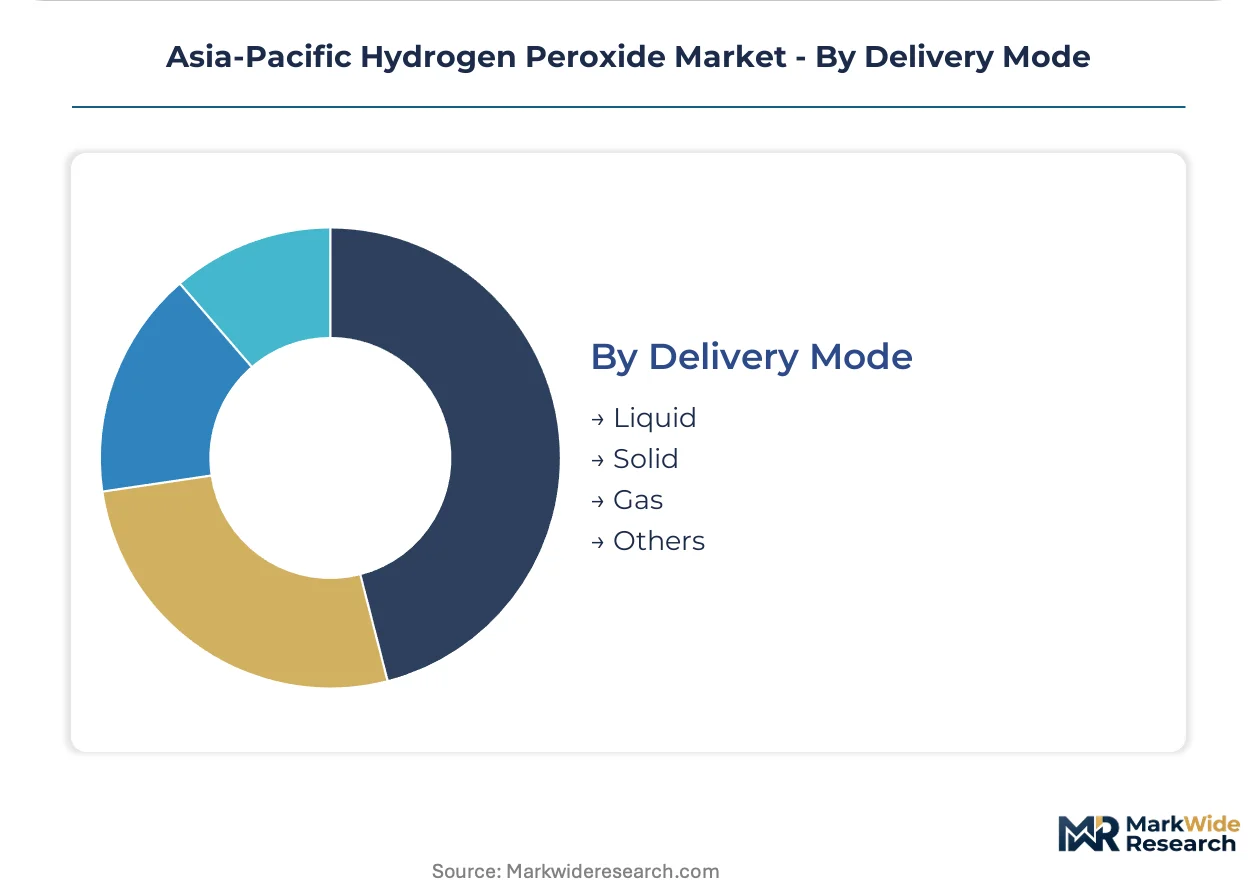
Delivery Mode:
Logistics constraints and safety regulations determine whether buyers receive bulk liquid, solid precursors, or on-site generated gas.
- Liquid:Tanker and drum delivery dominates industrial offtake, with concentrated solutions requiring temperature-controlled transport and specialized unloading infrastructure at receiving sites.
- Solid:Percarbonate and perborate derivatives enable stable storage and controlled release in remote mining and agricultural applications across Indonesian archipelago geographies.
- Gas:Vapor-phase delivery supports specialized sterilization chambers and semiconductor process tools requiring precise concentration control.
- Others:Modular electrochemical generation units produce peroxide on demand for Australian mining camps and Indonesian pulp facilities, eliminating hazardous material transport.
Liquid delivery handles current volume leadership; solid and on-site generation formats are gaining share in geographically dispersed operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones attract hydrogen peroxide capacity through tax incentives for chlorine-free chemical manufacturing, concentrating investment in Jiangsu and Zhejiang provinces.
China
MEE wastewater discharge mandates drive mill conversions to peroxide bleaching across Shandong and Guangdong provinces. The dual carbon goals accelerate captive integration in eastern chemical corridors. Ningbo and Shanghai anchor electronics-grade demand as semiconductor fabs diversify supply chains.
South Korea
TSMC and Samsung foundries in Pyeongtaek tighten purity specifications for sub-3nm wafer cleaning. K-REACH registration burdens filter imported formulations, favoring domestic supply security. Ulsan's integrated caprolactam-peroxide complex locks in dedicated chemical offtake.
Taiwan
Hsinchu Science Park fabs consume ultra-high-purity grades for advanced node production, extending supplier qualification timelines. Total cost-of-ownership contracts now bundle supply with spent chemical recovery. Tainan and Taichung clusters concentrate electronics chemical demand.
Japan
METI chemical substance management tightens reporting thresholds for semiconductor cleaning derivatives. Pre-stabilized, trace-metal-controlled grades reduce downstream effluent treatment burden. Kyushu and Kansai electronics corridors consolidate supplier panels to substance-flow-accountable providers.
India
CDSCO and BIS quality mandates govern peroxide entering pharmaceutical synthesis and medical device sterilization. Textile dyehouse effluent treatment expands peroxide demand in Gujarat and Maharashtra industrial corridors. Certification-driven entry barriers favor early compliance investment.
Asia-Pacific Hydrogen Peroxide Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with electronics-grade purity requirements concentrating supply among qualified specialists while standard industrial grades fragment across regional producers. Three archetypes dominate: integrated chemical conglomerates with captive anthraquinone capacity, high-purity specialists serving semiconductor fabs, and regional distributors managing logistics for dispersed pulp and textile mills. Capacity expansion and backward integration into hydrogen supply represent the dominant competitive vectors as electricity costs reshape production economics.
Among Asia-Pacific-based industrial groups, TAEKWANG INDUSTRIAL CO LTD anchors Korean supply through its Ulsan complex structure, while HENAN JINHE INDUSTRY CO LTD occupies a position within China's eastern manufacturing corridor. Solvay represents the multinational specialist archetype competing on technology leadership in ultra-high-purity grades. These three exemplify how geographic concentration, captive integration, and purity certification stratify competitive positioning across the regional supply base.
| Leading Market Players |
|---|
| Arkema |
| TAEKWANG INDUSTRIAL CO LTD |
| Hodogaya Chemical Co Ltd |
| Evonik Industries AG |
| MITSUBISHI GAS CHEMICAL COMPANY INC |
| HENAN JINHE INDUSTRY CO LTD |
| Solvay |
| National Peroxide Limited |
| AkzoNobel N V |
| Others |
Pricing and Supply Chain Analysis
China's dual carbon goals gate both qualified supply and premium-tier pricing access, filtering producers through emissions-intensity thresholds that concentrate electronics-grade capacity in Jiangsu and Zhejiang provinces while elevating certification costs for chlorine-free bleaching chemistry.
Pricing Analysis
Short lead-time premiums dominate electronics-grade procurement, with TSMC and Samsung foundries paying specification premiums for 18-24 month qualified supply against spot-market discounts for unqualified inventory. Three-tier pricing structure across electronics-grade, industrial-grade, and standard bleaching formulations separates trace-metal-controlled purity from commodity peroxide. Cost compression in industrial-grade supply is intensifying because Korean and Chinese caprolactam producers deepen captive integration. Pulp mills under MEE discharge mandates prove most price-sensitive; semiconductor fabs show least sensitivity due to qualification lock-in.
Supply Chain Analysis
Specialized chemical engineering talent shortages in eastern China's manufacturing corridor and Ulsan's industrial complex constrain anthraquinone unit expansion timelines. Supply concentrates in China, South Korea, and Japan, with production anchored in the Yangtze River Delta, Pyeongtaek chemical parks, and Kyushu electronics corridors. Feedstock dependencies rest on 2-alkylanthraquinone, hydrogen supply, and palladium catalysts. Single-source vulnerability from concentrated anthraquinone precursor manufacturing exposes regional supply security. Distribution runs through tanker and drum networks for liquid grades, with solid derivatives and modular electrochemical units gaining share in archipelago geographies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane electrolysis for on-site generation is displacing centralized anthraquinone production, compressing working capital requirements and rewriting supply economics for remote industrial clusters across the region.
For Market Incumbents: Deepen backward integration into electrolytic hydrogen production to insulate margin structures from electricity cost volatility in China and India. Expand electronics-grade capacity in Jiangsu and Zhejiang provinces to capture specification premiums from TSMC and Samsung sub-3nm node migration. Peracetic acid substitution in Japanese food sterilization applications threatens standard peroxide volumes; respond with pre-stabilized, trace-metal-controlled grade portfolios that reduce downstream effluent burden. For New Entrants and Emerging Players: Modular electrochemical generation technology offers a technology-first wedge into Indonesian pulp facilities and Australian mining camps where hazmat transport costs erode centralized supply economics. Target pharmaceutical-grade certification in India under CDSCO and BIS mandates, where compliance-driven entry barriers favor early movers. Deploy equipment-plus-chemistry service models that bundle on-site generation units with performance-based maintenance contracts. For Investors and Strategic Acquirers: Samsung and TSMC supplier day announcements expanding total cost-of-ownership contract coverage is the leading indicator that integrated chemical management providers will consolidate electronics-grade supply relationships. Position for five-to-ten year viability through acquisition of qualified high-purity specialists with documented substance flow accountability under Japan's METI framework. Monitor K-REACH registration completion timelines as inflection signal for Korean market access viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrolytic Hydrogen | Captive hydrogen production at Ulsan and Ningbo complexes insulates margin exposure from electricity cost swings. |
| Electronics-Grade Capacity Expansion | Jiangsu and Zhejiang investments capture specification premiums from Hsinchu and Pyeongtaek fab demand. |
| Modular Electrochemical Generation Deployment | Containerized units at Indonesian pulp mills eliminate concentrated peroxide transport from centralized plants. |
| Pharmaceutical-Grade Certification Investment | CDSCO and BIS compliance creates defensible positioning in Indian drug synthesis and medical device sterilization. |
| Total Cost-of-Ownership Contract Structuring | TSMC and Samsung bundled supply-plus-recovery agreements displace traditional volume-offtake relationships. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across plant managers at anthraquinone units, procurement leads at semiconductor foundries, distribution channel partners in chemical corridors, and technical R&D directors at specialty peroxide formulators. Bottom-up capacity and demand modeling triangulated against top-down trade flow analysis from China Customs, Korea Customs Service, and Japan Ministry of Finance datasets.
Segment-level granularity modeled grade tier purity specifications, end-use industry concentration across pulp, electronics, and pharmaceutical channels, packaging format delivery modes, and regional production hub cost structures. CAGRs derived from installed capacity expansion timelines, foundry capital expenditure patterns, and MEE regulatory enforcement trajectories across the projection horizon. Hydrogen supply cost curves and electricity tariff differentials fed regional production economics.
Several conditions sit outside the modeled scope, including unannounced semiconductor fab construction delays, abrupt K-REACH substance list amendments, and renewable energy project commissioning failures affecting green hydrogen coupling claims. Forecasts reflect documented assumptions on regulatory enforcement intensity and node migration timelines. Material deviation in foundry qualification cycle completion or MEE inspection frequency warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Performance Chemicals
Mecoprop Market
Performance Chemicals
Global Reflective Materials Market
Performance Chemicals
Chemical Feed Systems Market
Performance Chemicals
High Performance Plastics Market
Performance Chemicals
Global High Performance Polyamides Market
Performance Chemicals
Global High Performance Polymers Market
Performance Chemicals
Global Oilfield Production Chemicals Market
Performance Chemicals
High Performance Epoxy Market