
 Global High Performance Polymers Market | 2026-2036
Global High Performance Polymers Market Size, Share, and Industry Trends Forecast 2026-2036
Global High Performance Polymers Market Foresight
REACH is consolidating the cost-of-entry calculus for European compounders, forcing reformulation of legacy halogenated systems ahead of sunset clauses. Solvay S.A. leverages its vertically integrated fluoropolymer chain to sustain margin capture across aerospace-certified grades. Victrex plc anchors its position through captive PEEK resin production and dedicated medical-device compounding lines in the United Kingdom.
High performance polymers are thermally stable, chemically resistant macromolecules—typically aromatic or semi-crystalline structures with continuous-use temperatures exceeding 150°C—engineered to replace metals and ceramics in load-bearing, corrosive, or dielectric applications. Polyetheretherketone dominates structural aerospace and implantable medical segments where fatigue resistance and biocompatibility command premium positioning. Polyphenylene sulfide competes aggressively in automotive under-hood electrical connectors, while polyimide films occupy the flexible electronics substrate tier where dimensional stability under thermal cycling determines yield.
EPA and FDA frameworks in the United States govern emissions from fluoropolymer production and biocompatibility of implantable grades, respectively, while REACH and the EU Green Deal in Europe restrict perfluorinated precursor chemistries and mandate recyclability disclosures. China's MIIT enforces GB standards for halogen-free flame retardancy in electrical enclosures, shaping import eligibility for foreign compounders. Stakeholders must monitor regulatory divergence between Brussels and Beijing on per- and polyfluoroalkyl substance restrictions, as misalignment threatens to fragment material qualification protocols across major supply corridors.
Market Dynamics
REACH sunset clauses on halogenated flame retardants are forcing European compounders into expensive reformulation cycles, while aerospace procurement in Germany and the United States concentrates demand for certified PEEK and PPS grades.
Growth Catalysts
- Aerospace Thermal Management:German and US manufacturers are expanding procurement of polyphenylene sulfide and polyetheretherketone for engine-adjacent components requiring continuous-use temperatures above 300°C.
- China's Electrical Corridor:Domestic producers in China's eastern industrial belt are scaling capacity for electronics-grade polymers to serve EV battery housings and high-voltage connectors.
- REACH Compliance Deadlines:The European Union's phased restrictions on perfluorinated precursor chemistries are accelerating qualification of halogen-free formulations ahead of 2025-2027 sunset clauses.
Market Restraints
- Fluoromonomer Feedstock Volatility:Perfluorinated precursor supply concentrates among Chinese and Belgian producers, exposing compounders to price swings and allocation risk.
- Biocompatibility Certification Burden:FDA 510(k) and EU MDR pathways for implantable grades extend qualification timelines to 18-36 months, freezing out mid-scale entrants.
- Metal Substitution Ceiling:Load-bearing aerospace brackets above 200°C still favor titanium alloys where fatigue performance outweighs polymer weight savings.
Strategic Opportunities
- India's Medical Device Manufacturing:CDSCO's harmonization with ISO 13485 and production-linked incentive schemes create import-substitution openings for implantable-grade PEEK compounders.
- Hydrogen Infrastructure Polymers:High-pressure hydrogen storage and fuel cell bipolar plates demand chemically resistant grades that incumbent suppliers have not yet optimized.
- Recyclability Mandates:The EU Green Deal's recyclability disclosure requirements favor suppliers with closed-loop PEEK reclamation capabilities, disadvantaging virgin-resin-only players.
Industry Challenges
- Specialized Polymer Processing Talent:Melt-processing expertise for high-temperature aromatic polymers concentrates among aging technician cohorts in Germany and Japan, constraining capacity expansion.
- Multi-Regulatory Qualification Overlap:Simultaneous EPA emissions compliance, FDA biocompatibility clearance, and REACH substance restrictions force redundant testing spend.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global High Performance Polymers Market |
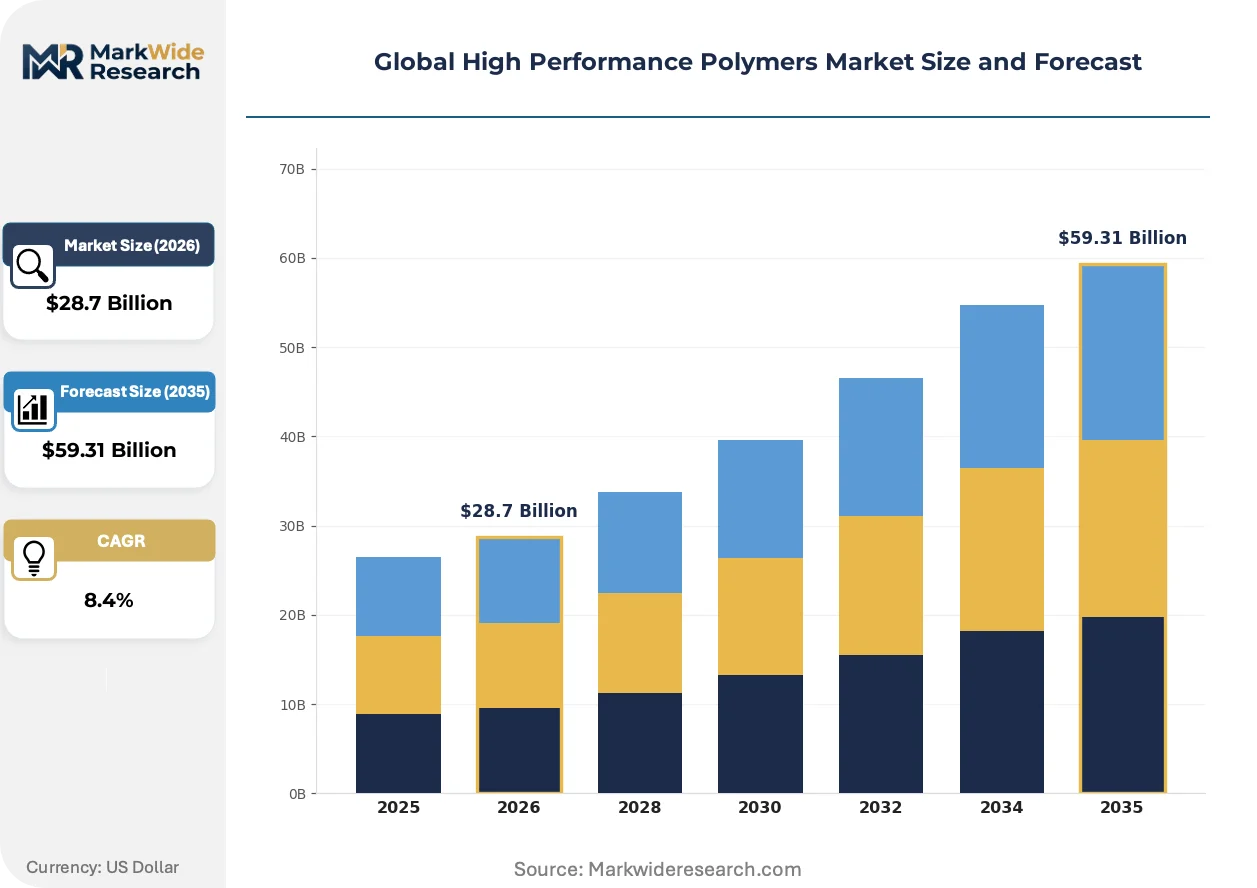
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $59.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Polymer Type: Polyetheretherketone, Polyphenylene Sulfide, Polyimide, Polyetherimide, Polysulfone Grade/Form: Pellets, Films, Powders, Rods, Sheets Application: Automotive Components, Aerospace Parts, Electrical & Electronics, Medical Devices, Industrial Machinery End User Industry: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers, Transportation Equipment Manufacturers |
| Companies Covered | Solvay S.A., SABIC, BASF SE, Arkema S.A., Victrex plc, DuPont de Nemours, Inc., Evonik Industries AG, Covestro AG, Celanese Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global High Performance Polymers Market Shifts & Advancements
Automation of compounding lines and real-time viscosity control are compressing batch-to-batch variation, while regulatory divergence between Brussels and Beijing fragments material qualification protocols.
Continuous fiber-reinforced PEEK tape placement is automating the layup of aerospace thermoplastic composite structures, cutting cycle times from hours to minutes. Tier-1 aerostructures suppliers in Germany and the United States are qualifying these automated fiber placement lines for wing and fuselage components. This automation is compressing the cost gap between thermoset and thermoplastic composites in primary load-bearing applications.
REACH restrictions on per- and polyfluoroalkyl substances are tightening precursor availability for fluoropolymer production across European compounding operations. The F-Gas Regulation's phasedown of hydrofluorocarbons is compounding feedstock pressure for FEP and PVDF grades. Medical-device and semiconductor-fluid-handling segments are accelerating qualification of partially fluorinated alternatives to maintain supply continuity.
Consolidated procurement by Chinese EV battery manufacturers is compressing supplier margins and demanding just-in-sequence delivery of flame-retardant PPS compounds. CATL and BYD's purchasing cooperatives now specify GB-standard halogen-free certification as a table-stakes requirement, displacing smaller compounders lacking in-country testing capabilities. This concentration is most visible in Ningbo and Suzhou, where domestic polymer producers have captured 60% of connector-grade volume.
Global High Performance Polymers Market Segmentation
High performance polymers demand precise segmentation because thermal stability, chemical resistance, and processing requirements vary dramatically across polymer families and end-use specifications. Manufacturers must align compounding investments with qualification timelines that stretch from automotive under-hood components to implantable medical devices.
Polymer Type:
Capital intensity peaks with aromatic crystalline polymers requiring specialized monomer synthesis and purification infrastructure, while amorphous high-heat grades demand less upfront but constrain margin through feedstock volatility.
- Polyetheretherketone:Semi-crystalline aromatic polymer with continuous-use temperature exceeding 250°C and exceptional fatigue resistance. German and US aerospace manufacturers specify this grade for engine-adjacent brackets and thermoplastic composite structures where metal substitution justifies premium positioning.
- Polyphenylene Sulfide:Crystalline polymer with inherent flame retardancy and dimensional stability under thermal cycling. China's eastern industrial corridor concentrates demand for electrical connector housings serving CATL and BYD battery procurement cooperatives.
- Polyimide:Aromatic heterocyclic polymer delivering the highest thermal endurance among commercial organic materials, essential for flexible electronics substrates.
- Polyetherimide:Amorphous high-heat polymer balancing processability with elevated temperature performance, common in medical sterilization trays and aircraft interior components.
- Polysulfone:Transparent high-heat amorphous polymer with hydrolytic stability, specified for membrane filtration housings and food-service equipment.
Polyetheretherketone absorbs the bulk of installed capacity; Polyphenylene Sulfide is expanding most quickly.
Grade/Form:
Processing method determines working capital requirements, with continuous extrusion formats locking up resin inventory longer than discrete molding grades.
- Pellets:Standard injection molding feedstock requiring compounders to maintain broad viscosity distributions across customer specifications.
- Films:Biaxially oriented and cast formats for flexible circuit substrates and capacitor dielectrics, where thickness uniformity dictates yield.
- Powders:Compression molding and coating feedstocks for fluoropolymer linings and sintered bearing surfaces.
- Rods:Machining stock for prototype development and low-volume precision components in semiconductor handling equipment.
- Sheets:Thermoforming blanks for aircraft interior panels and medical device housings requiring tight thickness tolerance.
Pellets command the largest production footprint; Films are climbing the fastest as flexible electronics manufacturing scales.
Application:
Qualification burden varies sharply, with implantable medical and primary aerospace structures demanding 18-36 month certification timelines versus 6-12 months for industrial machinery.
- Automotive Components:Under-hood electrical connectors, sensor housings, and thermal management modules replacing metal where weight reduction meets 150°C-plus continuous service.
- Aerospace Parts:Primary and secondary structural components, including continuous fiber-reinforced thermoplastic composites for wing and fuselage sections.
- Electrical & Electronics:High-voltage connectors, battery housings, and flexible circuit substrates where halogen-free flame retardancy is becoming mandatory.
- Medical Devices:Implantable spinal cages, dental fixtures, and surgical instruments requiring FDA 510(k) or EU MDR clearance.
- Industrial Machinery:Seals, bearings, and pump components in chemical processing and oilfield equipment.
Automotive Components consume the greatest compound volume; Medical Devices are gaining share fastest through aging demographics and procedural volume expansion.
End User Industry:
Supply chain position shapes technical service intensity, with OEMs demanding co-development partnerships while aftermarket providers prioritize inventory availability.
- OEMs:Original equipment manufacturers in aerospace and medical device sectors specifying custom formulations with exclusive compounding arrangements.
- Tier-1 Suppliers:Aerostructures and automotive subsystem integrators qualifying materials against OEM specifications with limited reformulation latitude.
- Aftermarket Providers:Distributors and service organizations stocking standard grades for replacement parts and repair operations.
- Vehicle Assemblers:Final automotive manufacturers consolidating polymer procurement through platform-level supply agreements.
- Transportation Equipment Manufacturers:Rail, marine, and off-highway equipment builders with extended product lifecycles and conservative material change protocols.
Tier-1 Suppliers anchor the largest procurement volume; Medical device OEMs are expanding most quickly through dedicated compounding lines and captive resin production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's eastern industrial corridor operates as the dominant concentration zone, with special economic zones in Jiangsu and Zhejiang provinces offering preferential tax treatment for polymer compounding facilities serving EV battery supply chains.
China
CATL and BYD's procurement cooperatives concentrate demand for flame-retardant PPS compounds in Ningbo and Suzhou, where domestic producers have captured connector-grade volume. MIIT enforces GB standards for halogen-free certification as a table-stakes import requirement. The Yangtze River Delta hosts the fastest capacity scaling for electrical and electronics-grade polymers.
Germany
Aerospace manufacturers in Bavaria and Baden-Württemberg expand procurement of PEEK and PPS grades for engine-adjacent thermal management components. REACH sunset clauses on halogenated flame retardants force expensive reformulation cycles among compounders. The Stuttgart industrial cluster anchors qualification of continuous fiber-reinforced thermoplastic composites for wing structures.
United States
EPA emissions compliance and FDA 510(k) pathways create overlapping qualification burdens for implantable-grade and aerospace-certified polymers. The Pacific Northwest and Southeast manufacturing belts concentrate melt-processing expertise for high-temperature aromatic polymers. Tier-1 aerostructures suppliers in Washington and South Carolina automate fiber placement lines for primary load-bearing applications.
India
CDSCO's harmonization with ISO 13485 and production-linked incentive schemes open import-substitution opportunities for implantable-grade PEEK compounders. Maharashtra and Gujarat host emerging medical device manufacturing clusters seeking domestic polymer supply. The Delhi-NCR corridor attracts compounders qualifying halogen-free formulations for electrical enclosure exports.
Japan
METI supports domestic capacity for polyimide films serving flexible electronics substrates where dimensional stability under thermal cycling determines yield. The Kansai and Chubu regions concentrate aging technician cohorts with specialized expertise in high-temperature polymer processing. Osaka-based compounders maintain qualification advantages for semiconductor-fluid-handling grades.
Global High Performance Polymers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct capability tiers. The market structure consolidates around three archetypes: integrated resin producers with captive monomer supply, independent compounders serving qualification-intensive segments, and regional processors capturing cost-sensitive volume. Dominant competitive moves include backward integration into precursor chemistries and dedicated compounding lines for medical-device and aerospace certification tracks.
Within the integrated-resin tier, Solvay S.A. and Victrex plc occupy positions defined by upstream control over fluoropolymer and PEEK resin production respectively. SABIC represents the diversified-conglomerate archetype, leveraging cross-polymer technology platforms and Middle Eastern feedstock access. These three companies exemplify how vertical integration sustains margin capture across certification-intensive grades where qualification timelines extend 18-36 months.
| Leading Market Players |
|---|
| Solvay S.A. |
| SABIC |
| BASF SE |
| Arkema S.A. |
| Victrex plc |
| DuPont de Nemours, Inc. |
| Evonik Industries AG |
| Covestro AG |
| Celanese Corporation |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between aerospace-qualified and industrial-standard polymers manifests in pricing premiums of 40-60% for PEEK and PPS grades bearing FAA and EASA airworthiness documentation, while supply chains bifurcate between captive resin producers serving long-term offtake contracts and merchant compounders exposed to fluoromonomer spot volatility.
Pricing Analysis
Lead-time compression commands measurable premiums, with spot buyers of medical-device-grade PEEK paying 25-35% above contract rates for sub-8-week delivery windows. Pricing stratifies across premium, standard, and economy tiers, where FDA 510(k) clearance and REACH SVHC compliance separate top-tier quotations from commodity grades. Cost compression in electrical-connector PPS runs through CATL and BYD procurement cooperatives consolidating volume. Automotive Tier-1 suppliers exhibit highest price sensitivity, while implantable medical OEMs absorb premiums for biocompatibility certification.
Supply Chain Analysis
Specialized melt-processing expertise concentrates among aging technician cohorts in Germany, Japan, and the United States, constraining capacity expansion regardless of capital availability. Raw material dependencies center on Chinese and Belgian perfluorinated precursor producers, Japanese polyimide monomer specialists, and Middle Eastern feedstock for polyetherimide grades. Single-source vulnerability pervades aerospace-certified resin supply, where Victrex and Solvay maintain effective duopoly positions. Distribution runs through authorized distributor networks for medical and aerospace grades, while industrial segments accept direct mill sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous fiber-reinforced thermoplastic composites are displacing thermoset prepregs in primary aerostructures, compressing cycle times and reshaping qualification requirements across the value chain.
For Market Incumbents: To counter fluoromonomer feedstock volatility, Solvay and Arkema should deepen backward integration into precursor chemistries through long-term offtake agreements with Chinese producers. Certification investment in EU MDR and FDA dual-track pathways for implantable grades locks out mid-scale challengers and sustains margin capture in medical-device compounding. For New Entrants and Emerging Players: Tier-1 automotive subsystem integrators present the most penetrable channel, particularly in India's emerging EV battery corridor where CDSCO harmonization with ISO 13485 lowers regulatory barriers. Target hydrogen infrastructure applications—high-pressure storage vessels and fuel cell bipolar plates—where incumbent suppliers have not yet optimized chemically resistant grades. Qualification partnerships with German automotive OEMs accelerate market access. For Investors and Strategic Acquirers: Re-rating potential sits with captive PEEK resin producers given REACH sunset clauses on halogenated alternatives and accelerating metal substitution in thermal management. Long-term viability over a 5-10 year horizon favors compounders with closed-loop reclamation capabilities aligned to EU Green Deal recyclability mandates. The signal to watch is CATL and BYD procurement cooperative specifications migrating to GB-standard halogen-free certification as mandatory import eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Chemistries | Secures fluoromonomer supply continuity for FEP and PVDF grades amid REACH restrictions. |
| Dual-Track FDA and EU MDR Certification Investment | Creates 18-36 month qualification moats around implantable PEEK medical devices. |
| Closed-Loop PEEK Reclamation Capability Buildout | Aligns compounder operations with EU Green Deal recyclability disclosure requirements. |
| Continuous Fiber-Reinforced Tape Placement Automation | Compresses thermoplastic composite cycle times for German and US aerostructures suppliers. |
| Halogen-Free Formulation Qualification for GB Standards | Unlocks connector-grade volume in Ningbo and Suzhou EV battery manufacturing clusters. |
Research Methodology
Multi-period observation of aerospace procurement patterns, REACH compliance timelines, and EV battery manufacturing capacity anchored the trend analysis, supplemented by interviews with polymer plant managers, procurement leads at Tier-1 automotive suppliers, technical R&D directors at compounders, and distribution channel partners. Secondary validation drew from customs and trade data, SEC 10-K filings, ECHA SVHC candidate list updates, and MIIT GB standard releases. Bottom-up resin capacity modeling and top-down end-use demand estimation were triangulated against reported segment revenues.
Segment-weighting across polymer type, grade form, application, and end-user industry shaped the analytical framework, with polymer family thermal performance tiers and regional regulatory clusters as cross-cutting dimensions. CAGRs were derived from installed capacity expansion announcements, OEM platform-level procurement disclosures, and qualification timeline benchmarks across the projection horizon. Forecast inputs incorporated fluoromonomer feedstock allocation patterns and technician cohort retirement schedules in Germany and Japan.
Several conditions sit outside the modeled scope, including force majeure disruptions to Chinese perfluorinated precursor production, unilateral EPA emissions rulemaking beyond current frameworks, and breakthrough metal-alloy formulations reclaiming aerospace thermal management applications. Forecasts reflect assumptions about regulatory implementation schedules and OEM platform adoption curves. Material deviation in REACH sunset clause enforcement, CATL and BYD procurement cooperative specification migration, or German aerospace production rates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Performance Chemicals
Global High Performance Polyamides Market
Performance Chemicals
Asia-Pacific Hydrogen Peroxide Market
Performance Chemicals
Global Reflective Materials Market
Performance Chemicals
Chemical Feed Systems Market
Performance Chemicals
Global Oilfield Production Chemicals Market
Performance Chemicals
High Performance Epoxy Market
Performance Chemicals
High Performance Plastics Market
Performance Chemicals
Mecoprop Market