
 Saudi Arabia Electric Vehicle Market | 2026-2036
Saudi Arabia Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Electric Vehicle Market Insights
Premium battery specification tiers with extended range certification above 500 kilometers is unwinding consumer hesitation in the Saudi Arabia electric vehicle space. Lucid Group leverages its domestic manufacturing facility in King Abdullah Economic City to anchor production scale for Gulf export markets. Ceer Motors differentiates through localized SUV platforms designed for regional climate conditions. Tesla Inc. competes on supercharger network density along the Riyadh-Jeddah corridor.
The Saudi Arabia electric vehicle comprises battery-electric and plug-in hybrid propulsion systems utilizing lithium-ion cell packs with nickel-cobalt-manganese cathode chemistry, thermal management systems rated for ambient temperatures exceeding 50 degrees Celsius, and onboard power electronics converting direct current to alternating current for traction motors; these systems serve private mobility, commercial fleet operations, and public transit decarbonization objectives. SUV configurations currently dominate unit shipments as family-oriented buyers prioritize cabin space and all-terrain capability. Fast charging infrastructure represents the fastest-expanding segment within charging deployment as petroleum retailer partnerships accelerate highway corridor coverage. Fleet operators constitute the most concentrated margin pool among end user categories due to volume procurement contracts and predictable utilization cycles.
SFDA vehicle safety protocols, SASO technical regulations for electromagnetic compatibility, and the Saudi Energy Efficiency Center's consumption labeling requirements collectively shape product homologation timelines and component sourcing decisions for market entrants. The Public Investment Fund's equity stakes in domestic manufacturers create preferential financing channels that influence competitive access. Stakeholders must monitor how NEOM's autonomous vehicle integration mandates and the Kingdom's giga-project construction schedules reshape fleet procurement specifications and charging infrastructure standards.
Market Dynamics
The Saudi Arabia electric vehicle market is compressing around fleet procurement mandates from state-affiliated logistics operators and petroleum retailers retrofitting service stations for fast-charging deployment.
Growth Catalysts
- SFDA streamlined homologation:Safety certification timelines for imported EV models have collapsed from eighteen months to under six, accelerating model availability for Riyadh and Jeddah showrooms.
- Aramco fleet electrification mandates:The national petroleum producer's last-mile delivery and executive transport pools are converting to battery-electric powertrains, creating predictable offtake for domestic distributors.
- Lithium-iron-phosphate cell chemistry:Thermal stability improvements in phosphate-based cathodes are reducing cooling system complexity for vehicles operating in ambient conditions exceeding fifty degrees Celsius.
Market Restraints
- Nickel-cobalt supply concentration:Cathode material dependency on Indonesian and Congolese mining operations exposes battery pack pricing to geopolitical disruption and ESG compliance costs.
- SASO electromagnetic compatibility testing:Equipment certification for onboard power electronics requires specialized Riyadh laboratory capacity, creating bottlenecks for new market entrants without established local partnerships.
- Grid interconnection standards:Distribution network reinforcement specifications from the Saudi Electricity Company delay charging hub commissioning in secondary cities beyond the Riyadh-Jeddah corridor.
Strategic Opportunities
- NEOM autonomous vehicle integration:The giga-project's zero-emission mobility mandates create specification pull-through for vehicle-to-infrastructure communication modules and swappable battery architectures.
- Red Sea coastal tourism clusters:Resort developments between Jeddah and the Jordanian border are procuring electric shuttle fleets, opening a hospitality-aligned buyer segment distinct from urban private ownership.
- Islamic Development Bank green financing:Sharia-compliant leasing structures for commercial EV procurement are reducing upfront capital barriers for SME logistics operators in Dammam and Khobar.
Industry Challenges
- High-voltage technician certification gaps:Vocational training programs for battery pack diagnostics and thermal management system repair remain underdeveloped relative to deployment timelines.
- Desert dust ingress protocols:IP rating validation for sealed battery enclosures and motor housings requires extended field testing cycles that compress model refresh windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Electric Vehicle Market |
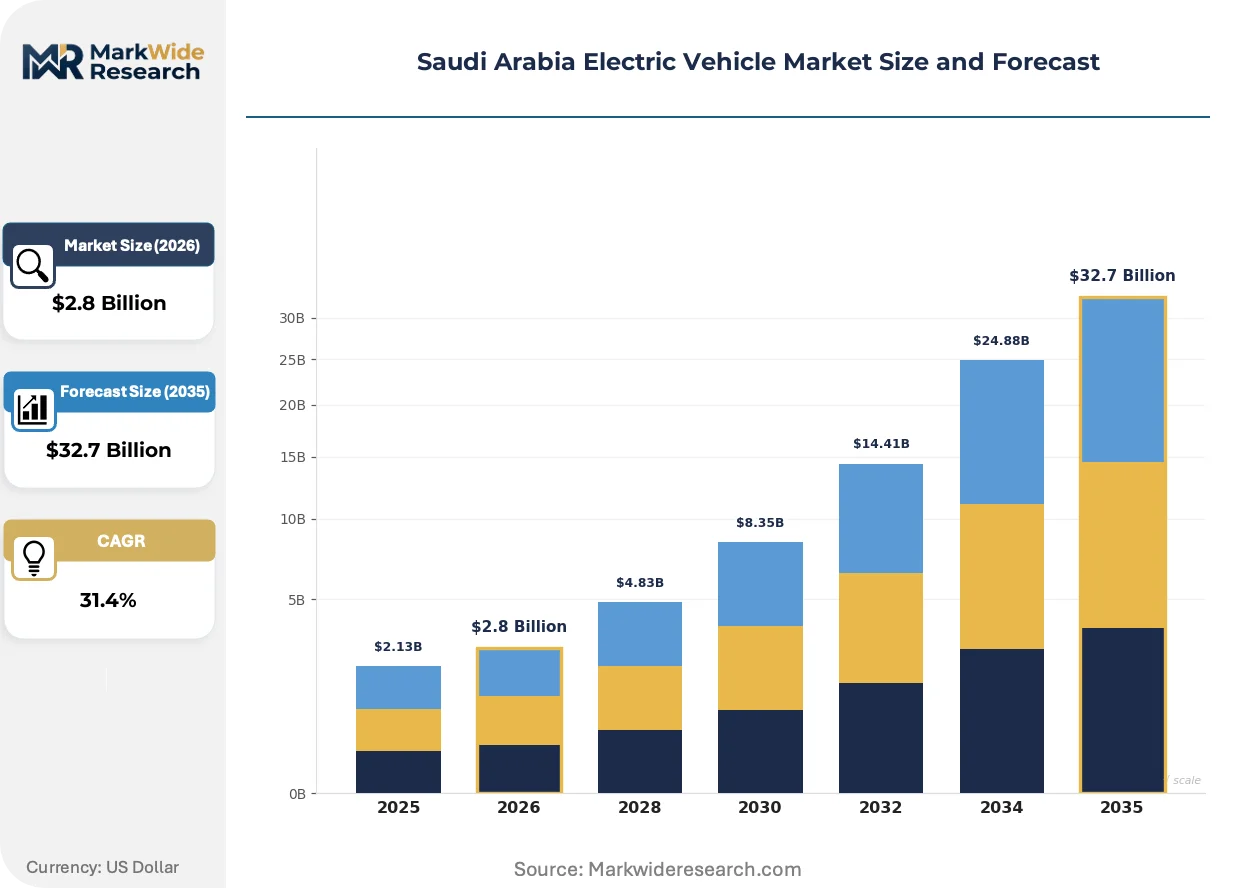
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $32.7 Billion |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Two-Wheeler, Sedan, SUV, Hatchback Charging Infrastructure: Home Charging, Public Charging, Fast Charging, Supercharging Battery Technology: Lithium-Ion, Solid-State, Nickel-Metal Hydride, Lead-Acid End User: Individual Consumers, Fleet Operators, Public Transportation, Government |
| Companies Covered | Lucid Group, Ceer Motors, Tesla Inc., Nissan Motor Corporation, BMW AG, Hyundai Motor Company, BYD Auto, Kia Corporation, MG Motor, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Electric Vehicle Market Trends and Innovations
Thermal management architectures and charging infrastructure deployment models are diverging sharply between premium long-range configurations and fleet-optimized economy platforms.
Solid-state battery prototyping is bifurcating research investment across two distinct pathways. Oxide-based electrolyte designs from domestic research institutes target energy density thresholds for premium SUV applications. Sulfide-based alternatives prioritize manufacturing scalability for fleet procurement volumes. This technology split is compressing supplier consolidation timelines as cathode material specialists select alignment with specific solid-state roadmaps.
SASO efficiency labeling mandates now require real-world consumption disclosure under standardized Saudi driving cycles. Manufacturers must submit telemetry from vehicles operated in ambient temperatures above forty-five degrees Celsius. This regulatory pressure is forcing recalibration of advertised range figures and accelerating adoption of active battery cooling systems in mid-tier product lines.
Fleet operators are consolidating procurement decisions through centralized tendering platforms administered by the Public Investment Fund's portfolio companies. Individual dealership relationships are losing influence as volume contracts specify direct manufacturer relationships with standardized service level agreements. This channel compression is most visible in Riyadh, where municipal waste management and airport ground service fleets have migrated to multi-year single-source agreements.
Saudi Arabia Electric Vehicle Market Segmentation
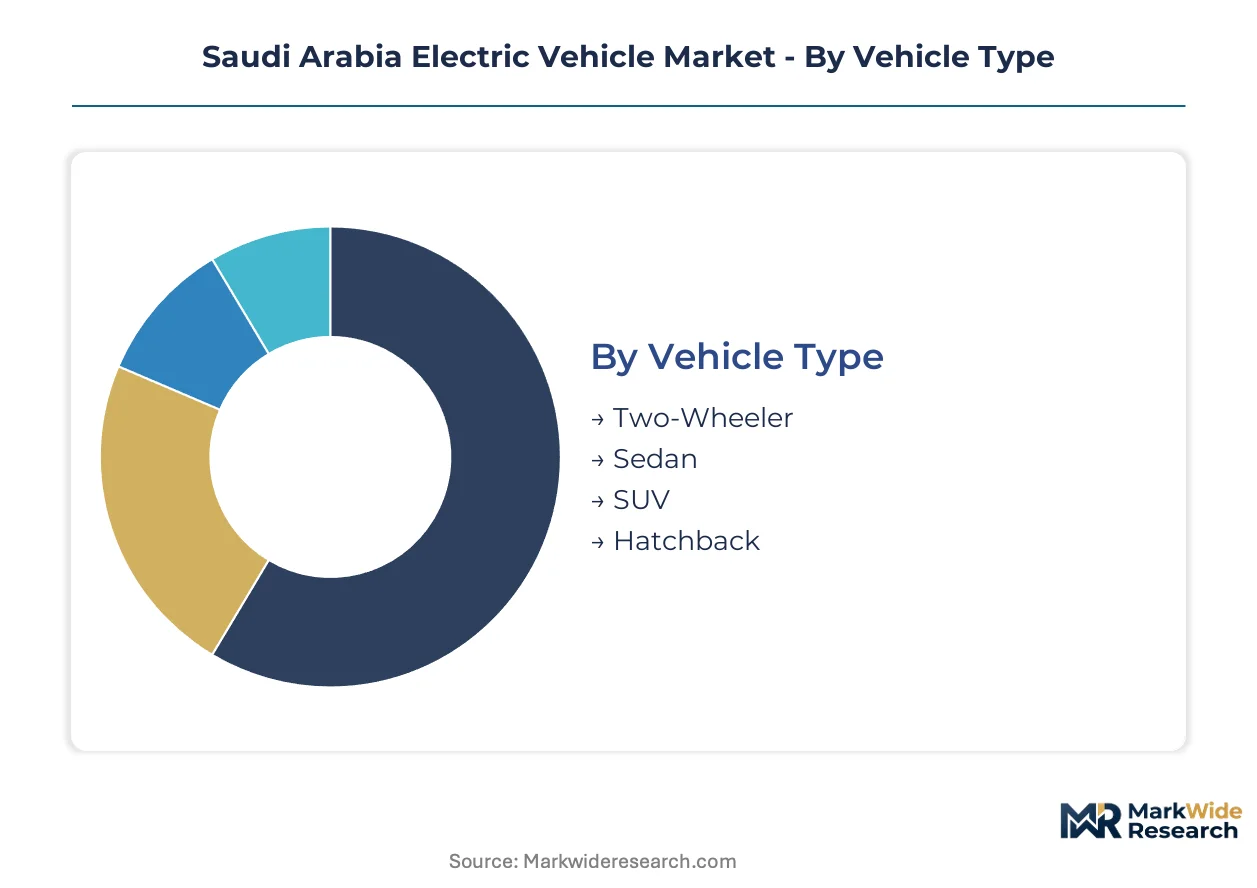
Segmentation in the Saudi Arabia electric vehicle market reveals how procurement concentration and climate-specific engineering requirements reshape competitive priorities across vehicle categories, charging modalities, and battery chemistries.
Vehicle Type:
Substitution pressure from internal combustion engine alternatives remains strongest in family mobility segments where total cost of ownership calculations now favor electrification across Riyadh and Jeddah commuting patterns.
- SUV:Configurations with extended wheelbases and elevated thermal management capacity dominate family-oriented procurement in the Kingdom. Cabin space requirements and all-terrain capability specifications align with Saudi consumer preferences, particularly in Riyadh where municipal fleet electrification programs prioritize SUV platforms for government transport pools.
- Sedan:Lower center-of-gravity designs with optimized aerodynamic profiles serve executive transport and ride-hailing fleet operators. Corporate procurement from Saudi Aramco and major financial institutions concentrates demand in Jeddah's commercial districts, where charging infrastructure density supports daily utilization cycles.
- Hatchback:Compact urban mobility solutions target secondary city deployment with price-sensitive positioning.
- Two-Wheeler:Last-mile delivery applications in dense urban cores represent emerging electrification opportunities.
SUV retains volume leadership; sedan holds the steepest expansion curve.
Charging Infrastructure:
Cost tier differentiation separates premium installation specifications from standardized deployment models as petroleum retailers retrofit service station networks.
- Fast Charging:Direct current systems delivering power above 50 kilowatts anchor highway corridor coverage between Riyadh and Jeddah. Partnerships between domestic fuel distributors and international equipment providers accelerate commissioning timelines, though grid interconnection standards from the Saudi Electricity Company create deployment bottlenecks in secondary cities.
- Supercharging:Proprietary connector architectures with liquid-cooled cable assemblies enable sustained high-power sessions for long-range battery configurations. Network density along the Riyadh-Jeddah corridor serves premium vehicle owners, with expansion targeting NEOM construction logistics and Red Sea coastal tourism clusters.
- Public Charging:Standardized alternating current installations serve urban destination charging at retail and commercial properties.
- Home Charging:Residential wall-mounted units with smart grid integration capabilities support overnight replenishment patterns.
Fast charging commands deployment capital concentration; supercharging gains share fastest among premium vehicle owners.
Battery Technology:
Application-specific requirements drive divergence between energy density optimization and thermal stability prioritization in ambient conditions exceeding fifty degrees Celsius.
- Lithium-Ion:Nickel-cobalt-manganese cathode chemistry with active liquid cooling systems dominates current production scale. SFDA safety certification protocols and SASO efficiency labeling mandates require real-world consumption disclosure under standardized Saudi driving cycles, forcing manufacturers to recalibrate advertised range figures.
- Solid-State:Oxide-based electrolyte designs from domestic research institutes target premium SUV energy density thresholds, while sulfide-based alternatives prioritize manufacturing scalability for fleet procurement volumes through Ceer Motors and Lucid Group production facilities.
- Nickel-Metal Hydride:Mature chemistry retains presence in hybrid auxiliary power applications with lower thermal management requirements.
- Lead-Acid:Legacy technology persists in low-voltage auxiliary systems and aftermarket replacement cycles.
Lithium-ion retains volume leadership; solid-state climbs the fastest in research investment allocation.
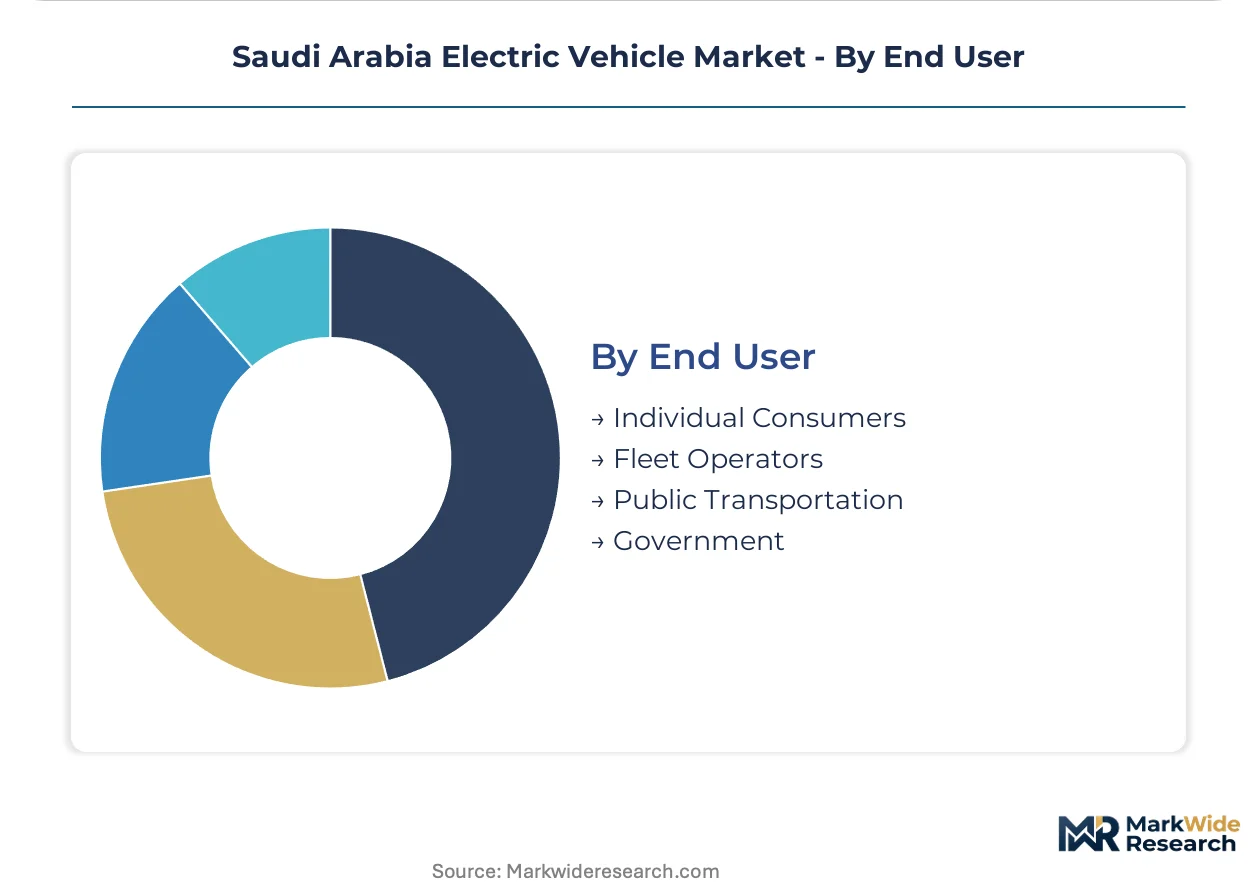
End User:
Customer type concentration determines margin structure, with volume procurement contracts offering predictable utilization cycles distinct from fragmented private ownership patterns.
- Fleet Operators:Centralized tendering platforms administered by Public Investment Fund portfolio companies consolidate logistics and last-mile delivery procurement. Saudi Aramco's electrification mandates for executive transport and delivery pools create multi-year single-source agreements with standardized service level specifications.
- Government:Municipal waste management, airport ground service, and public sector transport pools in Riyadh migrate to battery-electric platforms under procurement directives tied to giga-project construction schedules and NEOM zero-emission mobility mandates.
- Individual Consumers:Private ownership concentrates in Riyadh and Jeddah where charging infrastructure density and showroom availability align.
- Public Transportation:Electric shuttle procurement for Red Sea coastal tourism clusters and urban bus electrification pilots represent emerging demand.
Fleet operators retain volume leadership; government holds the steepest expansion curve tied to procurement mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across Saudi Arabia's electric vehicle demand centers, with fleet operators in Riyadh and Jeddah absorbing premium specifications while secondary city buyers remain highly sensitive to upfront capital requirements.
Riyadh
Municipal fleet electrification programs and government transport pools anchor demand concentration in the capital. SFDA vehicle safety standards and SASO efficiency mandates compress homologation timelines for new model introductions. The King Abdullah Financial District and diplomatic quarter host the densest fast-charging corridor deployment outside the Riyadh-Jeddah highway.
Jeddah
Commercial district ride-hailing electrification and Saudi Aramco executive transport procurement drive sedan-category volume. Corporate procurement from financial institutions concentrates demand near the Red Sea coast where charging infrastructure density supports intensive utilization cycles. The Jeddah Islamic Port logistics cluster is piloting battery-electric last-mile delivery fleets.
Eastern Province
Petrochemical industry fleet operators and industrial logistics pools represent emerging commercial demand. Aramco's downstream operations are electrifying maintenance and inspection vehicle pools under internal decarbonization mandates. The Dammam-Khobar metropolitan area is receiving priority grid interconnection upgrades for charging hub commissioning.
NEOM Northwest
The giga-project's zero-emission mobility mandates create specification pull-through for autonomous vehicle integration and swappable battery architectures. Construction logistics fleets operate under strict electrification requirements tied to project financing conditions. The linear city development is prototyping vehicle-to-infrastructure communication modules at scale.
Western Region
Red Sea coastal tourism clusters between Jeddah and the Jordanian border are procuring electric shuttle fleets for resort developments. Hospitality-aligned buyer segments operate distinctly from urban private ownership patterns. The King Abdullah Economic City manufacturing zone anchors Lucid Group's domestic production facility for Gulf export markets.
Saudi Arabia Electric Vehicle Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes in the Saudi Arabia electric vehicle market. Domestic manufacturing facilities and Gulf export positioning characterize one consolidated tier, while import-dependent distributors with petroleum retailer partnerships occupy a fragmented secondary layer. Three strategic archetypes dominate: vertically integrated domestic producers, premium-range specialists with supercharger network investments, and volume-scale Asian manufacturers with price-optimized platforms. Competitive moves concentrate on charging infrastructure partnerships and fleet procurement contract consolidation.
Among domestic-anchored producers, Lucid Group and Ceer Motors exemplify the integrated manufacturing archetype with King Abdullah Economic City production scale. Tesla Inc. occupies the premium-tier position through supercharger network density along the Riyadh-Jeddah corridor. These three entities represent distinct competitive vectors: domestic production scale, premium infrastructure ownership, and technology-forward positioning.
| Leading Market Players |
|---|
| Lucid Group |
| Ceer Motors |
| Tesla Inc. |
| Nissan Motor Corporation |
| BMW AG |
| Hyundai Motor Company |
| BYD Auto |
| Kia Corporation |
| MG Motor |
| Others |
Pricing and Supply Chain Analysis
Lucid Group's King Abdullah Economic City manufacturing scale anchors production cost floors for domestic assembly, compressing import-dependent distributor margins while elevating price competition along the Riyadh-Jeddah corridor. This capacity concentration enables localized SUV platforms to undercut fully-imported alternatives, reshaping how fleet operators negotiate volume procurement contracts.
Pricing Analysis
SASO efficiency labeling mandates dictate the pricing tier structure across the Saudi Arabia electric vehicle market, separating premium long-range configurations with active thermal management from standard economy platforms with passive cooling. Price differentiation rests on certification grade for desert climate operation and after-sales service bundling through petroleum retailer partnerships. Cost compression in the standard tier intensifies as Chinese manufacturers expand Gulf export volumes. Fleet operators exhibit lowest price sensitivity due to predictable utilization cycles, while individual consumers in secondary cities remain highly responsive to upfront capital requirements.
Supply Chain Analysis
China, South Korea, and Indonesia anchor cathode material supply for lithium-ion cell production feeding Saudi assembly operations. Battery pack manufacturing draws from nickel-cobalt-manganese precursor chemicals and high-purity lithium carbonate, with thermal management components sourced from Japanese and German specialists. Single-source vulnerability concentrates in Indonesian nickel processing capacity exposed to export restriction risk. Distribution runs through Aramco-affiliated petroleum retailers retrofitting service stations for fast-charging deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Saudi Arabia electric vehicle market is recovering from infrastructure-led cyclical troughs as giga-project construction schedules accelerate fleet procurement timelines. NEOM zero-emission mandates and Red Sea tourism cluster development justify capacity expansion planning.
For Market Incumbents: Consolidate charging infrastructure partnerships with petroleum retailers to defend against new entrant network access. Secure backward integration into battery thermal management component supply through Saudi-based manufacturing incentives. Lock multi-year fleet procurement contracts with Public Investment Fund portfolio companies before tendering platforms further centralize. For New Entrants and Emerging Players: Lead with specialized desert climate certification as the differentiation anchor for secondary city dealership penetration. Target Eastern Province industrial logistics pools where electrification mandates from Aramco downstream operations create procurement urgency. Pursue direct manufacturer relationships with municipal waste management fleets bypassing consolidated tendering platforms. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among charging infrastructure operators with petroleum retailer exclusivity arrangements. Acquisition targets should demonstrate service level agreement execution with at least one Public Investment Fund portfolio company. Monitor NEOM construction logistics fleet procurement announcements as inflection indicators for swappable battery architecture adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures nickel-cobalt-manganese cathode chemistry access for King Abdullah Economic City production scale. |
| Charging Infrastructure Partnership | Accelerates highway corridor coverage through Aramco service station retrofitting commitments. |
| Desert Climate Certification Investment | Validates IP ratings for sealed battery enclosures under SFDA extended field testing protocols. |
| Geographic Manufacturing Footprint | Positions Lucid Group and Ceer Motors for Gulf export market access with localized content advantages. |
| Software-Defined Vehicle Investment | Enables vehicle-to-infrastructure communication modules required for NEOM autonomous integration mandates. |
Research Methodology
Operator-level perspectives from fleet procurement managers, charging infrastructure developers, battery system engineers, and petroleum retailer partnership leads anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against SASO technical filings, Saudi Electricity Company grid interconnection standards, vehicle registration databases, and customs import records. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Sensitivity analysis tested forecast robustness across alternative adoption scenarios for fleet electrification mandates and charging infrastructure deployment rates. The analytical framework modeled vehicle class, propulsion architecture, battery chemistry, and end-user category dimensions throughout the projection horizon. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns in comparable climate markets, with inputs including petroleum retailer partnership announcements and Public Investment Fund equity deployment timelines.
Forecasts assume regulatory continuity in SFDA vehicle safety protocols and SASO efficiency labeling regimes; material policy shifts would require re-modeling. Specific risks include nickel-cobalt supply disruption, grid interconnection standard revisions, and NEOM construction schedule delays. Recalibration cycles align with material shifts in fleet procurement tendering volumes and giga-project milestone announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
South America Electric Vehicles Market
Electric Vehicles
Middle East Electric Vehicle Market
Electric Vehicles
EV Thermal System Market
Electric Vehicles
Electric Vehicle Operations Management Solutions Market
Electric Vehicles
48V Mild Hybrid Battery Pack Systems Market
Electric Vehicles
Global Golf Cart and Neighborhood Electric Vehicle (NEV) Market
Electric Vehicles
Global Automotive Inductive Wireless Charging Systems Market
Electric Vehicles
Europe Electric Truck Market
Electric Vehicles
Electric Vehicle on Board Charger Market
Electric Vehicles
Electric Vehicle Skateboard Chassis Market
Electric Vehicles
Global EV on-Board Chargers Market
Electric Vehicles
India Electric Vehicle Financing Market
Electric Vehicles
United States Electric Pick-Up Trucks Market
Electric Vehicles
Electric Mobility Market
Electric Vehicles
Electric Transporters Market
Electric Vehicles
Worldwide EV Range Extender Market