
 UV LED Market | 2026-2036
UV LED Market Size, Share, and Industry Trends Forecast 2026-2036
UV LED Market Analysis
Modular UV-C emitter arrays is restructuring buyer choice in disinfection systems, letting end users scale wattage without full fixture replacement. Seoul Viosys Co., Ltd. dominates deep-UV chip supply through in-house aluminum nitride substrate growth. NICHIA CORPORATION anchors high-power UV-A curing modules with proprietary gallium nitride epitaxy. Crystal IS, Inc. specializes in semiconductor-grade substrates that sustain wavelength precision below 280 nanometers.
UV LED denotes a solid-state semiconductor device that emits ultraviolet radiation through electroluminescence in III-nitride materials, typically operating at wavelengths from 100 to 400 nanometers with drive currents between 100 and 700 milliamperes. Its primary commercial purpose replaces mercury-based lamps in sterilization, photochemical curing, and spectroscopic detection. UV-C solid-state emitters lead disinfection deployments where mercury bans tighten, while surface-mount configurations capture consumer electronics integration for portable sanitization. Continuous-wave technology holds mature share in industrial curing lines, and pulsed architectures are gaining fastest in precision medical sterilization where peak irradiance matters more than average dose.
The EPA regulates antimicrobial device claims in the United States, forcing UV LED manufacturers to validate efficacy data before marketing. REACH restricts hazardous substances in European-sold electronics, shaping solder and encapsulant selection for surface-mount packages. Japan's METI promotes mercury-free lighting transitions through efficiency benchmarks that UV LED systems now satisfy. Stakeholders must monitor how substrate supply concentration in East Asia interacts with evolving efficacy standards to time capacity commitments.
Market Dynamics
Mercury-phaseout mandates are compressing substitution timelines across sterilization and curing applications, forcing capital planners to revalue total-cost-of-ownership equations for solid-state emitters against legacy vapor-lamp infrastructure.
Growth Catalysts
- EU RoHS Directive:Binding restrictions on mercury content in lighting products are eliminating incumbent lamp technologies from new installations in member states.
- Aluminum nitride substrate availability:Semiconductor-grade AIN wafer production in East Asian clusters is resolving the primary supply bottleneck for deep-UV chip fabrication.
- Water treatment utilities:Municipal disinfection facilities across Asia-Pacific are retrofitting UV-C systems to meet zero-mercury operational mandates.
Market Restraints
- Substrate cost volatility:Aluminum nitride wafer pricing fluctuates with semiconductor cycle demand, compressing emitter gross margins during peak memory-chip investment periods.
- East Asian supply concentration:Over 80 percent of qualified AIN substrate growth capacity sits within Japan and South Korea, creating single-source vulnerability for deep-UV chip fabricators elsewhere.
- Wavelength precision limits:Current epitaxy techniques struggle to maintain sub-280 nanometer output stability across thermal operating ranges, restricting medical sterilization deployment.
Strategic Opportunities
- Portable consumer sanitization:Surface-mount UV-C packages are penetrating smartphone accessory and personal electronics hygiene markets previously unserved by lamp-based systems.
- Japan METI efficiency benchmarks:National mercury-free lighting transition programs are creating preferential procurement channels for domestic UV LED system integrators.
- Pulsed architecture convergence:Integration of solid-state pulsing electronics with UV-C emitters is opening precision medical sterilization applications where peak irradiance requirements exceed continuous-wave capability.
Industry Challenges
- III-nitride epitaxy talent scarcity:Deep-UV chip fabrication requires specialized MOCVD process engineers, with training pipelines failing to match capacity expansion timelines.
- EPA antimicrobial claim validation:Efficacy data requirements for disinfection device marketing are extending product launch cycles by 12-18 months for US market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UV LED Market |
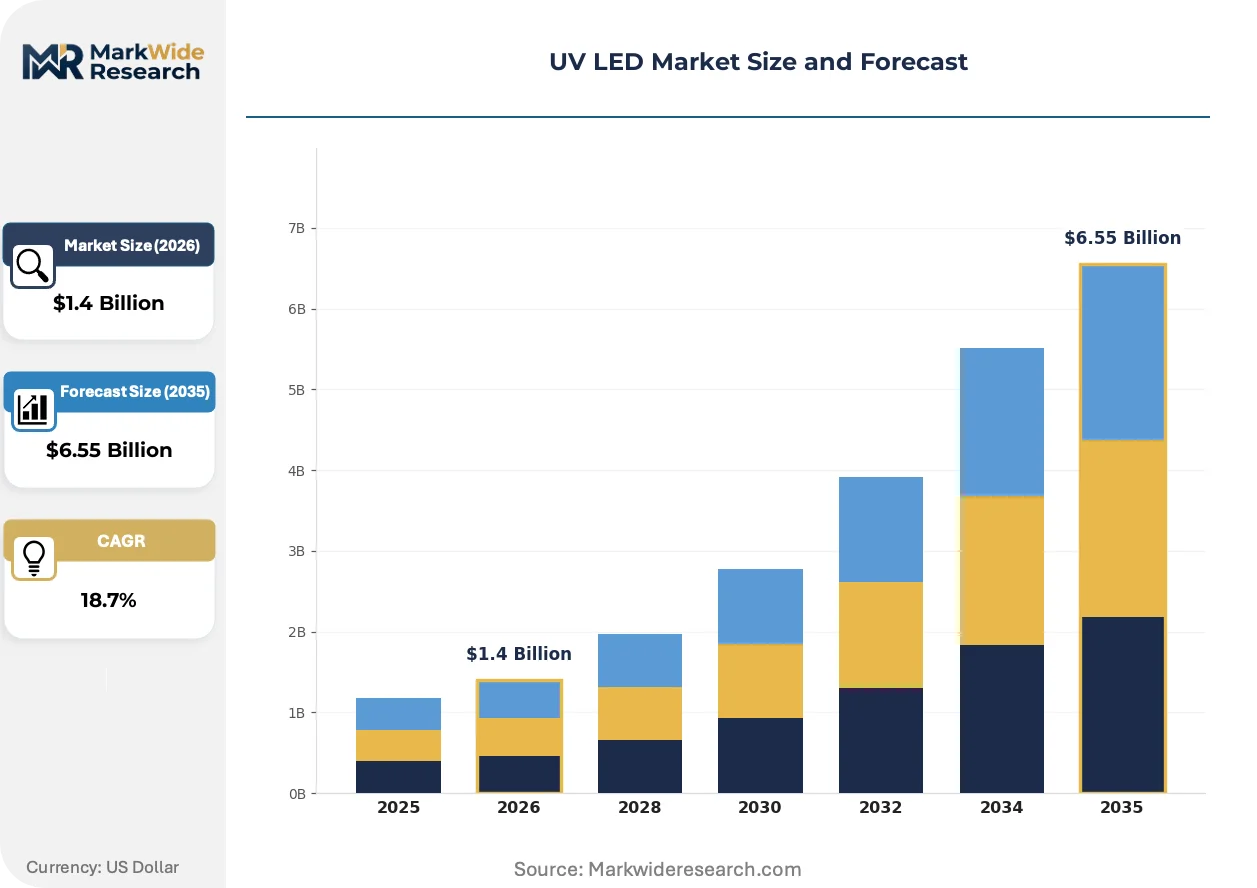
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $6.55 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid State, Surface Mount, UV-C, UV-A Application: Disinfection, Curing, Water Treatment, Plant Growth End User: Healthcare, Industrial, Aquaculture, Consumer Electronics Technology: Monochromatic, Broadband, Pulsed, Continuous Wave |
| Companies Covered | Seoul Viosys Co., Ltd., NICHIA CORPORATION, STANLEY ELECTRIC CO., LTD., ams-OSRAM AG, Crystal IS, Inc., Lumileds Holding BV, Lite-On Technology, Inc., EVERLIGHT ELECTRONICS CO., LTD., Luminus, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UV LED Market Emerging Trajectories
Emitter architecture evolution and regulatory compliance automation are redefining competitive differentiation, with modular system designs and smart monitoring capabilities emerging as primary value vectors.
Aluminum nitride single-crystal substrates are overtaking sapphire and silicon carbide as the foundation for deep-UV emitters below 280 nanometers. Water treatment OEMs in Germany and Japan are qualifying AIN-based systems for mercury-free retrofit contracts. This substrate transition is overtaking incumbent material platforms in applications where thermal conductivity and lattice matching directly determine device lifetime and output stability.
REACH substance restrictions are reshaping encapsulant and solder selection for surface-mount UV LED packages sold into European electronics supply chains. ECHA compliance documentation requirements now extend to full material disclosure for photonic components in consumer-facing applications. Medical device manufacturers in Ireland and the Netherlands are redesigning supply agreements to pre-certify upstream material streams against evolving SVHC candidate lists.
Buyer preference is compressing toward validated efficacy guarantees rather than nominal wattage specifications in institutional procurement. Healthcare facility engineering departments in the United States are demanding third-party microbial kill-rate data as a condition of UV-C system purchase. This specification shift is elevating the competitive position of suppliers with captive testing laboratory relationships and published clinical validation studies.
UV LED Market Segmentation
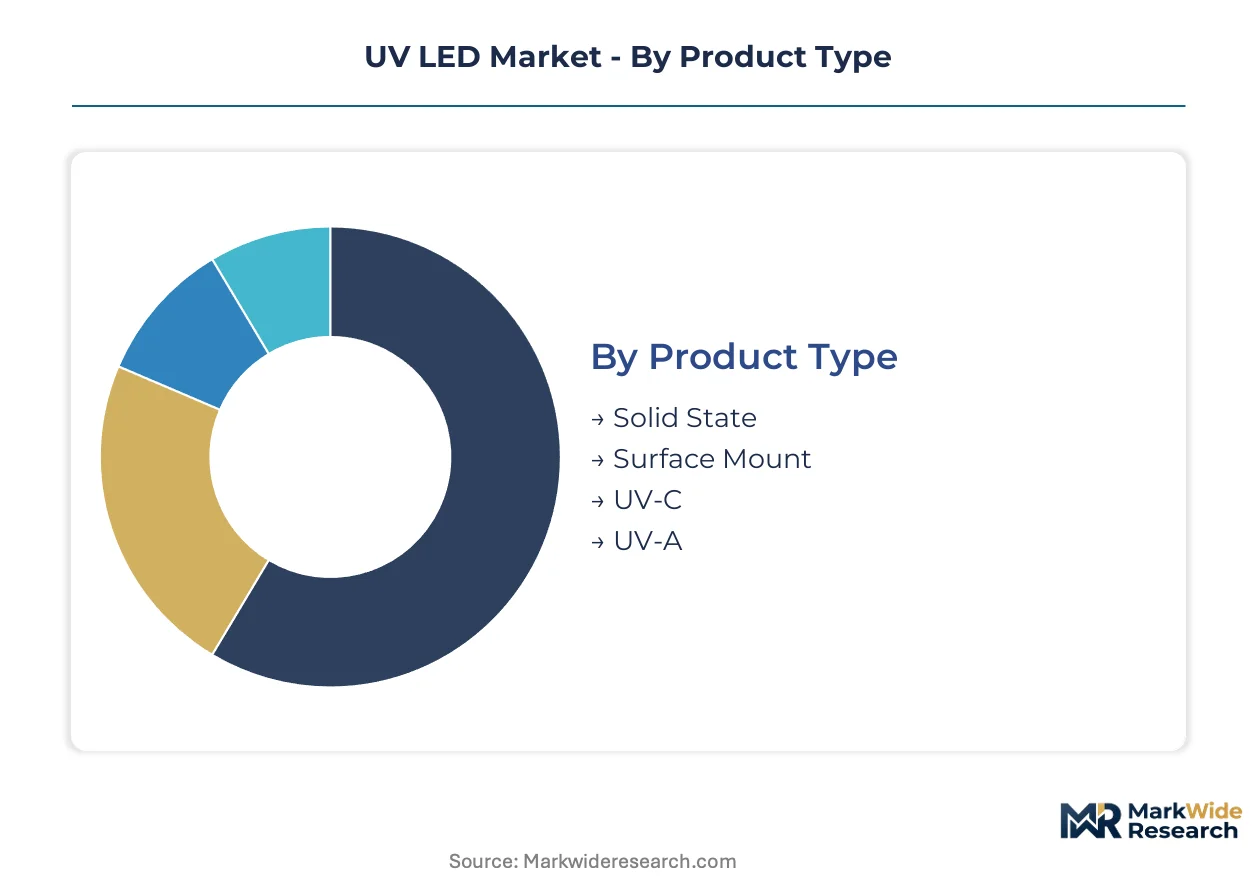
UV LED procurement decisions split across wavelength specificity, mounting architecture, and operational mode. Buyers in healthcare and water treatment prioritize germicidal efficacy and regulatory compliance over unit cost, while industrial curing operators emphasize irradiance stability and thermal management.
Product Type:
Technology and mounting geometry define replacement compatibility and thermal design requirements for system integrators.
- Solid State:Discrete chip-on-board configurations dominate high-power industrial installations where thermal interface materials and heat sink integration determine operational lifespan. Municipal water treatment facilities in Japan specify solid-state architectures for mercury-free retrofit compliance under METI efficiency benchmarks.
- Surface Mount:Compact package formats enable direct integration onto consumer electronics PCBs for portable sanitization accessories. South Korean smartphone accessory manufacturers are qualifying surface-mount UV-C emitters for integration into charging case disinfection modules.
- UV-C:Sub-280 nanometer emitters serve germicidal applications where photon energy exceeds DNA disruption thresholds. EPA antimicrobial claim validation requirements extend product launch timelines for UV-C system vendors targeting US healthcare procurement.
- UV-A:Longer wavelength output powers photochemical curing lines for adhesives and coatings in automotive manufacturing. German industrial OEMs specify UV-A modules for conveyor-integrated paint curing systems.
Surface Mount leads on scale; UV-C leads on momentum.
Application:
End-use environment dictates wavelength selection, irradiance specifications, and regulatory documentation burdens.
- Disinfection:Germicidal deployment requires validated kill-rate data against specified pathogens under defined exposure conditions. US hospital engineering departments now mandate third-party microbial efficacy studies as standard procurement criteria.
- Curing:Photopolymerization applications demand precise spectral matching to photoinitiator absorption bands. Japanese automotive coating lines specify UV-A curing modules with gallium nitride epitaxy for throughput consistency.
- Water Treatment:Municipal utilities require continuous-flow disinfection with dose monitoring and redundancy protocols. Asia-Pacific water treatment operators are retrofitting UV-C arrays to satisfy zero-mercury operational mandates.
- Plant Growth:Horticultural applications exploit UV-B stress responses to enhance secondary metabolite production in high-value crops. Dutch greenhouse operators trial UV-A supplementation for tomato flavonoid enhancement.
Water Treatment leads on scale; Plant Growth leads on momentum.
End User:
Buyer sophistication and validation requirements vary sharply across institutional, industrial, and consumer channels.
- Healthcare:Medical facilities demand published clinical validation and FDA device registration for UV-C surface disinfection systems. Irish hospital procurement frameworks now require REACH-compliant material disclosure for all installed electronics.
- Industrial:Manufacturing operators prioritize total-cost-of-ownership calculations incorporating energy consumption and lamp replacement intervals. German automotive paint shops specify UV-A curing modules with predictive maintenance telemetry.
- Aquaculture:Recirculating aquaculture systems deploy UV-C for pathogen control without chemical residuals. Norwegian salmon farming operations integrate UV LED arrays into land-based tank systems.
- Consumer Electronics:Portable device manufacturers seek surface-mount packages with minimal power draw and compact footprints. South Korean smartphone accessory vendors drive demand for integrated sanitization modules.
Industrial leads on scale; Consumer Electronics leads on momentum.
Technology:
Operational mode and spectral characteristics determine application fit and electronics integration complexity.
- Monochromatic:Narrow spectral output enables targeted photochemical reactions with minimal thermal loading. Precision medical sterilization applications specify monochromatic UV-C for selective pathogen inactivation.
- Broadband:Extended spectral coverage accommodates mixed photoinitiator formulations in multi-material curing processes. German coating manufacturers specify broadband UV-A sources for complex substrate adhesion.
- Pulsed:Peak irradiance exceeding continuous-wave capability enables rapid microbial inactivation in time-critical medical workflows. Pulsed architectures are gaining fastest in surgical instrument sterilization where average dose matters less than peak photon flux.
- Continuous Wave:Steady-state output supports industrial curing lines requiring uniform exposure across moving substrates. Japanese automotive assembly plants specify continuous-wave UV-A modules for robotic paint curing stations.
Continuous Wave leads on scale; Pulsed leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UV LED technology originated in Japanese semiconductor research facilities during the 1990s before commercial scaling shifted to Korean and Chinese manufacturing clusters. The industry now distributes across East Asian substrate production centers, European regulatory-driven retrofit markets, and North American healthcare validation corridors.
Japan
Municipal water treatment utilities in Osaka and Tokyo are retrofitting mercury-free UV-C arrays under METI efficiency benchmarks. The national regulator promotes solid-state lighting transitions through procurement preference programs. Kansai and Kanto industrial corridors host concentrated aluminum nitride substrate growth operations that supply deep-UV chip fabricators.
South Korea
Seoul-based smartphone accessory manufacturers are qualifying surface-mount UV-C emitters for portable sanitization modules. The MFDS regulates medical device efficacy claims, extending validation timelines for healthcare applications. Busan-Ulsan semiconductor clusters enable captive supply chains for III-nitride epitaxy equipment and process engineering talent.
Germany
Automotive paint shops in Bavaria and Baden-Württemberg specify UV-A curing modules with predictive maintenance telemetry for robotic assembly lines. REACH substance restrictions reshape encapsulant selection for European electronics supply chains. Frankfurt-Rhine-Main water treatment OEMs are qualifying AIN-based systems for municipal retrofit contracts.
United States
Hospital engineering departments in Boston and Houston demand third-party microbial kill-rate data as standard UV-C procurement criteria. EPA antimicrobial claim validation extends product launch cycles by 12-18 months for disinfection device vendors. California consumer electronics integrators drive demand for surface-mount packages in portable hygiene accessories.
China
Industrial coating lines in the Yangtze River Delta deploy UV-A modules for adhesive curing in electric vehicle battery assembly. MIIT promotes domestic semiconductor equipment substitution, including MOCVD systems for III-nitride epitaxy. Shenzhen electronics manufacturers are vertically integrating UV LED packages into smartphone accessory supply chains.
UV LED Market Vendor Landscape
Premium-margin players sit above commodity-margin players across substrate control and wavelength precision capabilities. The vendor base stratifies into three tiers: captive substrate growers commanding supply security premiums, system integrators with validated efficacy databases, and commodity package assemblers competing on unit cost. Two strategic archetypes dominate: aluminum nitride substrate specialists and full-stack system validators. Competitive moves concentrate on backward integration into substrate growth and geographic expansion through efficacy certification reciprocity.
Within the substrate-specialist tier, Seoul Viosys Co., Ltd. and Crystal IS, Inc. occupy positions defined by supply chain control over deep-UV chip foundations. NICHIA CORPORATION exemplifies the full-stack archetype, combining epitaxy expertise with module-level system integration. These three entities represent divergent strategic bets on whether competitive advantage derives from upstream material control or downstream validation capabilities. Korean and Japanese-origin players respectively anchor each vector, reflecting national industrial policy support for mercury-free lighting transitions.
| Leading Market Players |
|---|
| Seoul Viosys Co., Ltd. |
| NICHIA CORPORATION |
| STANLEY ELECTRIC CO., LTD. |
| ams-OSRAM AG |
| Crystal IS, Inc. |
| Lumileds Holding BV |
| Lite-On Technology, Inc. |
| EVERLIGHT ELECTRONICS CO., LTD. |
| Luminus, Inc. |
| Others |
Supply Flow & Price Mechanics
Aluminum nitride wafer costs cascade through UV LED pricing tiers from substrate growth through packaged emitter sales, with Japanese and South Korean substrate specialists commanding premium positioning against commodity package assemblers in China. Water treatment OEMs absorb higher unit prices for validated efficacy data while consumer electronics buyers drive cost compression in surface-mount segments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates captive substrate growers from system integrators and commodity assemblers. Price differentiation rests on certification grade and volume scale, with EPA-validated UV-C modules commanding substantial premiums over uncertified alternatives. Cost compression in the economy tier is intensifying because Chinese package houses are expanding MOCVD capacity. Healthcare procurement teams show least price sensitivity; smartphone accessory manufacturers exhibit highest.
Supply Chain Analysis
Regional distribution centers in Osaka, Seoul, and Shenzhen orchestrate hub-and-spoke patterns for emitter delivery to system integrators. Supply concentrates in Japan, South Korea, and China, with over 80 percent of qualified aluminum nitride substrate growth anchored in East Asian clusters. Raw material dependencies include high-purity ammonia, trimethylgallium, and semiconductor-grade sapphire carriers. Single-source vulnerability for deep-UV chip fabricators outside Japan and South Korea creates structural risk. Distribution runs through authorized distributor networks serving industrial OEMs and direct procurement channels for municipal utilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UV LED market compounds steadily as mercury-phaseout mandates across jurisdictions guarantee replacement demand for legacy vapor-lamp infrastructure.
For Market Incumbents: Extend substrate supply agreements to lock in aluminum nitride wafer allocation ahead of memory-chip cycle competition. Deepen captive III-nitride epitaxy capabilities to defend margin position against emerging Chinese MOCVD equipment vendors. Prioritize EPA efficacy validation reciprocity to compress US market entry timelines for modular system lines. For New Entrants and Emerging Players: Water treatment OEMs in Germany and the United States represent the most penetrable channel partner type for unvalidated UV-C array suppliers seeking first commercial reference. Target portable consumer sanitization accessories where surface-mount package specifications remain undemanding. Pursue private-label arrangements with South Korean smartphone accessory manufacturers as the fastest go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for substrate-specialist targets because aluminum nitride wafer supply concentration creates durable pricing power for qualified growers. Five-to-ten-year viability hinges on regulatory ratification of mercury bans in additional jurisdictions. Watch for MFDS medical device efficacy guideline harmonization with EPA standards as the inflection signal for accelerated healthcare penetration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Growth | Captive aluminum nitride supply secures deep-UV chip fabrication against memory-cycle competition. |
| EPA Efficacy Validation Investment | Published kill-rate data unlocks US healthcare procurement previously blocked by antimicrobial claim requirements. |
| Surface-Mount Package Miniaturization | Compact UV-C emitters penetrate smartphone accessory markets unreachable by lamp-based systems. |
| Pulsed Architecture Development | Peak irradiance capability opens surgical instrument sterilization workflows demanding rapid microbial inactivation. |
| REACH Compliance Certification | Full material disclosure pre-qualifies European electronics supply chain access for encapsulant vendors. |
Methodological Framework
Direct dialogue with MOCVD process engineers, water treatment utility procurement directors, semiconductor equipment sales specialists, and hospital biomedical engineering heads grounded qualitative findings in operational reality. Secondary validation drew from EPA antimicrobial device registrations, METI efficiency benchmark publications, ECHA SVHC candidate list updates, and SEC filings of publicly traded LED manufacturers. Bottom-up emitter shipment estimates triangulated against top-down municipal retrofit contract values across the analysis window.
Bottom-up modeling aggregated wavelength-specific package shipments by mounting architecture and operational mode; top-down verification cross-checked against national mercury-phaseout expenditure commitments. Segmentation dimensions included product type, application environment, end-user sophistication, and technology operational characteristics. CAGRs derived from slope-intercept fitting of disclosed contract values and announced capacity expansions. Forecast inputs incorporated aluminum nitride substrate yield improvement trajectories and evolving EPA validation timeline assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to III-nitride epitaxy talent pipeline expansion and REACH substance restriction scope creep. Outputs reflect documented assumptions around regulatory ratification schedules and substrate cost volatility patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
LED Floodlight Drivers Market
LED
US LED Downlight Market
LED
India Indoor LED Lighting Market
LED
France Outdoor LED Lighting Market
LED
LED High Bay Drivers Market
LED
LED Display Market
LED
Infrared (IR) LED Market
LED
Small Pitch LED Display Market
LED
Architectural LED Products Market
LED
Smart LED Indoor Signage Market
LED
LED Modular Display Market
LED
Arrow LED Displays Market
LED
LED Street Light Drivers Market
LED
Organic Light Emitting Diode (OLED) Market
LED
India LED Lighting Market
LED
LED Control Unit Market