
 Herbal Shampoo Market | 2026-2036
Herbal Shampoo Market Size, Share, and Industry Trends Forecast 2026-2036
Herbal Shampoo Market Analysis
Millennial and Gen Z consumers is reorganizing demand patterns in the herbal shampoo sector, pulling volume away from mass-market synthetic alternatives toward transparency-backed botanical claims. Patanjali Ayurved leverages its Ayurvedic heritage to dominate rural and tier-two Indian distribution networks. Himalaya Wellness Company anchors its position through pharmacy-led channels and clinician endorsements across South Asia. Burt's Bees competes in North American natural retail through stringent ingredient sourcing protocols and cruelty-free certification.
Herbal shampoo denotes a surfactant-based cleansing formulation incorporating plant-derived extracts, essential oils, or botanical actives as primary functional ingredients, typically excluding synthetic sulfates, parabens, or silicones in premium positioning. Manufacturing employs cold-process extraction or supercritical CO2 methods to preserve volatile compound integrity, yielding products marketed for scalp health, hair fiber repair, or sebum regulation. The ingredient type dimension shows Ayurvedic and organic sub-categories capturing margin pools due to certification complexity and supply scarcity, while natural extracts sustain volume leadership through lower price points and broader retail placement. End-user segmentation reveals women as the established core demographic, though men represents the fastest-growing buyer archetype as grooming routines expand.
The EU Green Deal and REACH frameworks mandate granular ingredient traceability and restrict certain synthetic preservatives, elevating compliance costs for non-European exporters while creating preferential access for certified organic suppliers. India's BIS and CDSCO oversee cosmetic safety standards and Ayurvedic product claims, requiring clinical substantiation that advantages domestic heritage brands with existing research infrastructure. Stakeholders must monitor evolving biodegradability mandates and packaging waste regulations across their priority markets to anticipate reformulation cycles and channel qualification requirements.
Market Dynamics
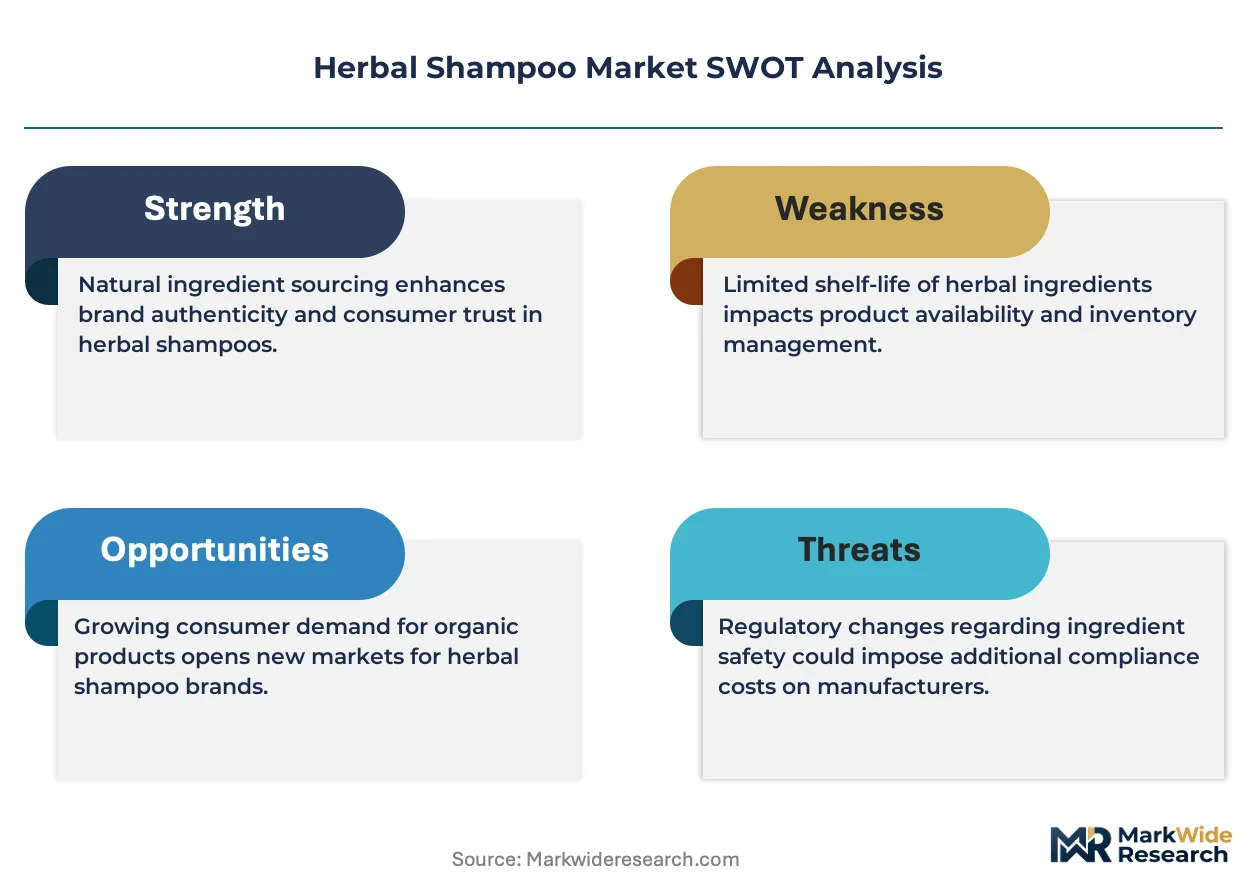
Regulatory tightening on synthetic preservatives and surfactants is forcing reformulation cycles across the herbal shampoo sector, while supply scarcity for certified organic botanicals concentrates margin capture among vertically integrated processors.
Growth Catalysts
- EU Green Deal compliance mandates:REACH frameworks require granular ingredient traceability, accelerating procurement of certified organic botanicals from established European suppliers with existing documentation infrastructure.
- Men's grooming routine expansion:Male consumers in urban India and Southeast Asian metros are adopting multi-step hair care regimens, creating incremental volume for herbal formulations positioned against synthetic sports-oriented brands.
- Supercritical CO2 extraction:This cold-process technology preserves volatile compound integrity in essential oil extraction, enabling premium positioning for scalp-therapeutic claims that cold-pressed alternatives cannot substantiate.
Market Restraints
- Organic certification cost inflation:USDA Organic and EU Organic certification timelines stretch 18-24 months with annual audit costs, compressing margins for mid-tier brands without captive farming operations.
- Indian monsoon-dependent supply:Amla, shikakai, and reetha harvesting concentrates in Maharashtra and Karnataka agricultural belts, exposing processors to climate volatility and price spikes.
- Synthetic surfactant performance gap:Sodium cocoyl isethionate and other plant-derived alternatives deliver inferior lather stability versus sodium lauryl sulfate, limiting adoption in performance-conscious salon channels.
Strategic Opportunities
- Men's specialized formulations:Underpenetrated male segments in Brazil and Mexico present whitespace for Ayurvedic-inspired brands with existing clinical substantiation infrastructure.
- Pharmacy-digital hybrid distribution:Direct-to-consumer subscription models integrated with dermatologist telehealth platforms enable recurring revenue capture and scalp health data accumulation.
- Biodegradability mandate alignment:France's AGEC law and emerging EU packaging waste regulations reward brands with compostable packaging and river-safe surfactant formulations.
Industry Challenges
- Formulation chemist scarcity:Natural preservation system expertise—particularly in hurdle technology combining mild heat with botanical antimicrobials—commands premium salaries that strain R&D budgets.
- Clinical substantiation timelines:India's CDSCO requires 12-week scalp microbiome studies for therapeutic claims, extending product development cycles versus cosmetic-only positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Herbal Shampoo Market |
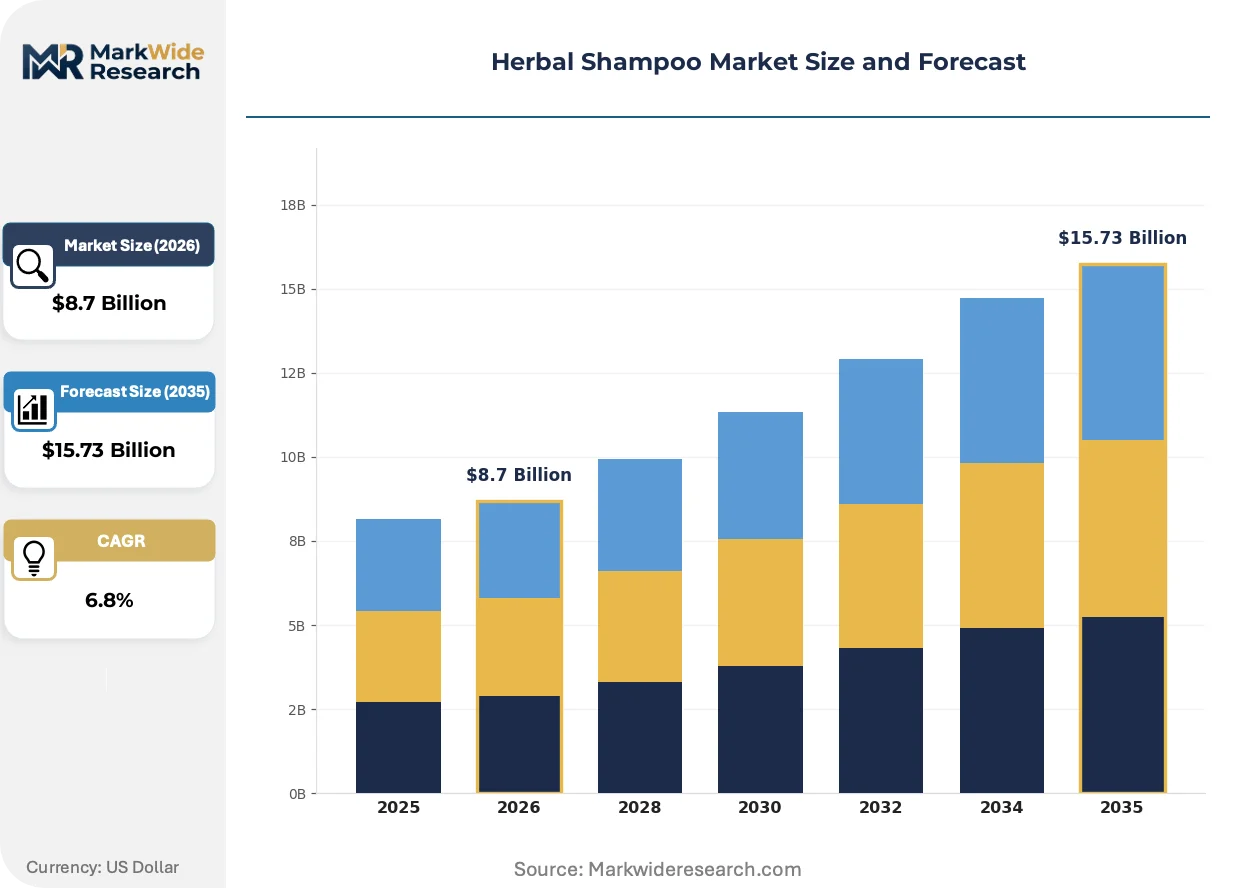
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conditioner, Treatment, Rinse, Gel Ingredient Type: Ayurvedic, Organic, Natural Extracts, Essential Oils End User: Men, Women, Children, Seniors Packaging Type: Bottles, Jars, Pouches, Tubes |
| Companies Covered | Avalon Organics, Patanjali Ayurved, Shiseido Company Limited, Lotus Herbals Pvt. Ltd., Himalaya Wellness Company, Amway Corp., Dabur India Limited, Burt's Bees, Hain Celestial, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Herbal Shampoo Market Emerging Trajectories
Waterless and solid format innovations are compressing packaging costs and logistics footprints, while biotechnology-derived botanical alternatives reduce agricultural land dependency for high-volume brands.
Biotechnology platforms utilizing precision fermentation are displacing conventional field-grown botanicals for high-demand actives like squalane and ceramides. Premium brands in South Korea and California are adopting these lab-cultured ingredients to bypass climate supply risk. This molecular manufacturing approach is displacing traditional extract supply chains in the prestige tier, compressing price premiums for rare botanical provenance claims.
India's BIS and CDSCO are tightening Ayurvedic product claim substantiation through mandatory clinical trial protocols for dandruff and hair fall indications. Domestic heritage brands with captive research facilities are absorbing compliance costs more efficiently than import-dependent competitors. Salon professionals in tier-one Indian cities are now prioritizing CDSCO-registered therapeutic shampoos over cosmetic-grade alternatives for client retention.
Ingredient transparency apps and blockchain-verified sourcing are reshaping purchase validation behavior among urban millennial buyers. Specialty retailers in Germany and the Netherlands are deploying QR-linked supply chain visualization as a shelf-edge conversion tool. This verification-driven preference shift is most pronounced in Scandinavian markets where the Nordic Swan Ecolabel commands price premiums exceeding conventional organic certification.
Herbal Shampoo Market Segmentation
Herbal shampoo segmentation reveals how formulation philosophy, procurement certification, and demographic targeting determine channel access and margin structure. Understanding these divides enables stakeholders to align R&D investment with the specific compliance and positioning requirements of each slice.
Product Type:
Channel mix varies sharply by format viscosity and usage occasion, with treatment products commanding salon placement while rinse formats dominate mass retail.
- Conditioner:Cream-based formulations with higher lipid content for cuticle sealing. Pharmacy and beauty specialty channels in Germany and South Korea concentrate demand for silicone-free variants with ceramide botanical substitutes.
- Treatment:Intensive scalp-focused products with elevated active concentrations requiring leave-in or pre-wash protocols. Salon professionals in Mumbai and São Paulo drive volume for therapeutic-grade positioning with clinical substantiation.
- Rinse:Lightweight formulations designed for frequent use with minimal residue. Mass-market retail and e-commerce platforms in Southeast Asian metros capture volume through unit economics suited to price-sensitive daily-use purchasing.
- Gel:Clear, low-viscosity formats with polymer-thickened botanical bases. Men's grooming specialists and athletic retail channels in urban India show expanding uptake for non-greasy sensorial profiles.
Treatment dominates installed base value. Gel is where expansion concentrates.
Ingredient Type:
Cost tier stratification separates heritage-provenance positioning from accessible natural claims, with certification burden determining margin capture.
- Ayurvedic:Formulations incorporating classical Indian medicinal botanicals such as bhringraj, brahmi, and neem with traditional processing protocols. Domestic Indian brands with captive BIS-compliant manufacturing infrastructure control supply and pricing in this heritage-tier segment.
- Organic:Certified USDA or EU Organic products with full supply chain audit trails. European specialty retailers and premium e-commerce platforms absorb the 30-40% price premium driven by 18-24 month certification timelines and annual compliance costs.
- Natural Extracts:Plant-derived actives without full organic certification, utilizing conventional agricultural sourcing. Volume leadership in emerging markets rests on lower price points and broader retail placement across supermarket and convenience channels.
- Essential Oils:Fragrance-functional formulations leveraging terpene-rich volatile compounds for aromatherapeutic positioning. Direct-to-consumer subscription models in North American urban centers exploit repeat-purchase loyalty for premium-priced scalp wellness routines.
Natural Extracts dominates installed base. Organic is climbing the fastest.
End User:
Customer type determines marketing spend allocation and formulation complexity, with demographic-specific claims requiring distinct clinical substantiation pathways.
- Men:Simplified ingredient lists with performance-oriented claims around hair fall control and scalp oil regulation. Barbershop partnerships and male-focused e-commerce platforms in Brazil and Mexico are expanding most quickly as grooming routines extend beyond basic cleansing.
- Women:Multi-step regimen integration with conditioning and treatment adjacencies. Pharmacy-led channels across South Asia and dermatologist endorsement networks sustain core volume for this historically dominant segment.
- Children:Tear-free, mild surfactant systems with simplified preservative packages. Pediatrician recommendation programs and mother-centric digital communities in tier-one Indian and Chinese cities concentrate demand for safety-verified positioning.
- Seniors:Scalp health and gray hair management formulations with anti-inflammatory botanical actives. Clinic-based dispensing and Medicare-adjacent retail in Japan and Western Europe capture this aging-demographic opportunity.
Women dominates installed base. Men is where expansion concentrates.
Packaging Type:
Volume-maturity dynamics separate established formats from emerging sustainability-driven alternatives, with logistics cost structure determining geographic penetration.
- Bottles:Conventional PET or post-consumer recycled polymer containers with pump or flip-cap dispensing. Established retail infrastructure across all major markets sustains volume leadership despite emerging regulatory pressure on single-use plastics.
- Jars:Wide-mouth containers for thick treatment masques and scalp scrubs. Salon professional channels and premium beauty retailers in France and Italy favor this format for tactile product interaction and perceived value.
- Pouches:Flexible laminate sachets and stand-up pouches with minimal material weight. Rural distribution networks and price-conscious emerging market segments in Indonesia and Nigeria exploit logistics cost advantages for single-use and trial-size offerings.
- Tubes:Collapsible aluminum or laminated plastic for controlled dispensing and portability. Travel retail and gym-channel placement in compact Asian urban centers show steepest expansion trajectory for on-the-go usage occasions.
Bottles dominates installed base. Tubes is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Millennial and Gen Z buyers in urban centers are reorganizing regional demand patterns, pulling procurement toward transparency-backed botanical claims and pharmacy-validated formulations. Salon professionals and specialty retailers across multiple geographies are expanding their botanical procurement accordingly.
India
Ayurvedic heritage brands command deep distribution networks in rural Maharashtra and tier-two Karnataka cities. The BIS and CDSCO mandate clinical substantiation for therapeutic claims, advantaging domestic players with captive research infrastructure. Mumbai and Bengaluru salon clusters now prioritize CDSCO-registered therapeutic shampoos over cosmetic-grade alternatives.
United States
Natural retail channels and direct-to-consumer subscription models concentrate demand in California and New York metro areas. The FDA oversees cosmetic safety labeling while USDA Organic certification drives 30-40% price premiums. Los Angeles-based formulators are integrating blockchain-verified sourcing to capture millennial verification preferences.
Germany
Specialty retailers in Berlin and Munich deploy QR-linked supply chain visualization as shelf-edge conversion tools. The EU Green Deal and REACH frameworks enforce granular ingredient traceability, elevating compliance costs for non-European exporters. Hamburg distribution clusters favor Nordic Swan Ecolabel products commanding premiums above conventional organic certification.
South Korea
Biotechnology-derived botanical alternatives are displacing field-grown actives in Seoul and Busan formulation labs. The MFDS regulates cosmetic safety standards while precision fermentation platforms reduce agricultural land dependency. Gyeonggi-do manufacturing corridors are adopting lab-cultured squalane and ceramides for prestige-tier positioning.
Brazil
Barbershop partnerships and male-focused e-commerce platforms in São Paulo and Rio de Janeiro are expanding rapidly as grooming routines extend beyond basic cleansing. ANVISA oversees cosmetic registration requirements. The Southeast region's urban male demographic represents underpenetrated whitespace for Ayurvedic-inspired brands with existing clinical substantiation.
Herbal Shampoo Market Vendor Landscape
Player mix skews toward heritage Ayurvedic houses and North American natural specialists, with mid-tier brands struggling to absorb certification cost inflation. Structure concentrates margin capture among vertically integrated processors with captive farming operations. Three archetypes dominate: domestic Indian heritage brands with BIS-compliant infrastructure, US-based cruelty-free certified specialists, and Japanese precision-fermentation innovators. Competitive moves center on pharmacy-digital hybrid distribution partnerships and biodegradability mandate alignment for EU market access.
Within the heritage Ayurvedic tier, Patanjali Ayurved and Dabur India Limited exemplify domestic market anchoring through rural distribution depth and CDSCO-registered therapeutic positioning. Among North American natural specialists, Burt's Bees occupies a position defined by stringent ingredient sourcing protocols and cruelty-free certification. Himalaya Wellness Company represents the pharmacy-led channel archetype, leveraging clinician endorsement networks across South Asia. These three players illustrate how regulatory infrastructure investment and channel-specific validation systems determine competitive access.
| Leading Market Players |
|---|
| Avalon Organics |
| Patanjali Ayurved |
| Shiseido Company Limited |
| Lotus Herbals Pvt. Ltd. |
| Himalaya Wellness Company |
| Amway Corp. |
| Dabur India Limited |
| Burt's Bees |
| Hain Celestial |
| Others |
Supply Flow & Price Mechanics
Cold-process extraction capacity utilization in Maharashtra and Karnataka determines margin floors across the herbal shampoo sector, compressing price competition among processors lacking captive amla and shikakai cultivation while elevating entry barriers for import-dependent formulators.
Pricing Analysis
Cost-plus contracts with indexed organic botanical feedstock clauses dominate procurement between Indian heritage brands and Maharashtra farming cooperatives. Three-tier pricing structure across premium organic, certified natural, and conventional extract tiers separates EU Green Deal-compliant suppliers from BIS-registered domestic players and unverified import brands. Pricing pressure stems from 18-24 month USDA Organic certification timelines compressing mid-tier margins. Mass-market rinse formats in Southeast Asian convenience channels exhibit highest price sensitivity, while CDSCO-registered therapeutic treatments in Mumbai salon clusters sustain lowest elasticity.
Supply Chain Analysis
Inventory cycles for monsoon-dependent amla, shikakai, and reetha harvests extend formulation lead times to 8-12 weeks during July-September procurement windows. Agricultural concentration in Maharashtra and Karnataka exposes processors to climate volatility, while European supercritical CO2 extraction equipment draws from German and Italian precision engineering supply chains. Single-source vulnerability concentrates in Indian monsoon belts for heritage Ayurvedic inputs. Distribution runs through pharmacy-led channels in South Asia, specialty retailers in Germany and South Korea, and direct-to-consumer subscriptions in North American urban centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal compliance mandates are accelerating a regulatory inflection that advantages vertically integrated botanical processors over import-dependent competitors, compressing the window for supply chain repositioning.
For Market Incumbents: Consolidate backward integration into captive organic cultivation in Maharashtra and Karnataka to secure BIS-compliant feedstock against monsoon price spikes. Lock in CDSCO-registered therapeutic claims through 12-week scalp microbiome studies before India's clinical substantiation timelines extend. Defend pharmacy channel access in South Asia against direct-to-consumer subscription encroachment. For New Entrants and Emerging Players: Anchor in Brazil's underpenetrated male grooming segment, where São Paulo barbershop partnerships offer whitespace for Ayurvedic-inspired brands with existing clinical substantiation infrastructure. Exploit biodegradable surfactant formulation gaps ahead of France's AGEC law enforcement. Pursue precision-fermentation ingredient sourcing from South Korean biotechnology platforms to bypass agricultural supply risk. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer subscription models with dermatologist telehealth integration, offering data asset accumulation alongside product sales. Long-term viability across the analysis window favors acquisition targets with captive organic certification infrastructure and CDSCO-registered therapeutic positioning. Monitor EU packaging waste regulation enforcement as inflection signal for compostable format adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Cultivation | Maharashtra farming cooperatives secure BIS-compliant feedstock against monsoon volatility and price spikes. |
| CDSCO Therapeutic Claim Registration | Clinical substantiation enables salon professional channel access in Mumbai and Bengaluru metro clusters. |
| Precision Fermentation Partnership | South Korean biotechnology platforms displace field-grown actives with lab-cultured squalane for prestige positioning. |
| Pharmacy-Digital Hybrid Distribution | Dermatologist telehealth integration captures recurring revenue and scalp health data in tier-one Indian cities. |
| Biodegradable Format Development | Compostable packaging and river-safe surfactants align with France's AGEC law and emerging EU regulations. |
Methodological Framework
Initial hypotheses were tested against primary input from formulation chemists at heritage Ayurvedic houses, procurement leads at German specialty retailers, CDSCO regulatory affairs specialists, and salon professional channel managers, then refined through secondary validation against BIS cosmetic safety filings, EU REACH substance databases, USDA Organic certification records, and Indian customs botanical export data. Bottom-up volume estimates from Maharashtra and Karnataka agricultural belts were triangulated with top-down category spending projections across the analysis window.
Variance decomposition across ingredient type, product format, end-user demographic, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from segmented growth rate reconciliation against macroeconomic anchors. Forecast inputs incorporated supercritical CO2 extraction capacity expansion timelines, CDSCO clinical trial protocol changes, and EU Green Deal enforcement trajectory assumptions throughout the projection horizon.
Decision-makers should treat outputs as directional under sustained EU regulatory tightening and Indian monsoon pattern stability; material deviation in biotechnology-derived ingredient adoption rates or packaging waste regulation acceleration would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Global Probiotic Cosmetic Products Market
Beauty & Personal Care
Delivery Systems in Personal Care Market
Beauty & Personal Care
Personalized Beauty Devices Market
Beauty & Personal Care
Facial Massager Market
Beauty & Personal Care
Global Organic Hair Color Market
Beauty & Personal Care
Asia Pacific Beauty Fridges Market
Beauty & Personal Care
Depilatories Market
Beauty & Personal Care
Herbal Cosmetics Market
Beauty & Personal Care
Europe Male Grooming Products Market
Beauty & Personal Care
ASEAN Organic Cosmetics Market
Beauty & Personal Care
Saudi Arabia Hair Care Market
Beauty & Personal Care
Organic Personal Care Market
Beauty & Personal Care
Salon Service Market
Beauty & Personal Care
Color Cosmetics Market
Beauty & Personal Care
Cosmetics and Personal Care Products Direct Selling Market
Beauty & Personal Care
Cosmetics and Toiletries Market