
 Cosmetics and Toiletries Market | 2026-2036
Cosmetics and Toiletries Market Size, Share, and Industry Trends Forecast 2026-2036
Cosmetics and Toiletries Market Analysis
ISO 22716 Good Manufacturing Practices certification is bifurcating the competitive landscape into compliant multinationals and excluded regional challengers. L'Oréal leverages integrated R&D campuses across France and the United States to sustain formulation leadership in active skincare. Estée Lauder anchors its premium positioning through controlled distribution in travel retail and department store concessions. Beiersdorf specializes in dermocosmetic science, competing on clinical validation rather than celebrity marketing.
Cosmetics and toiletries encompass chemically formulated preparations applied to the skin, hair, or body for cleansing, protection, fragrance, or aesthetic enhancement, typically manufactured through emulsification, compounding, or aerosol filling processes with specified pH ranges and preservative systems. The primary commercial purpose centers on consumer hygiene maintenance and personal appearance optimization across daily grooming rituals. Skincare commands the largest margin pool as consumers prioritize ingredient transparency and dermatological credibility over basic moisturization. Fragrance and makeup segments face structural pressure from channel shift, with online platforms now capturing substantial volume previously routed through specialty stores and department counters.
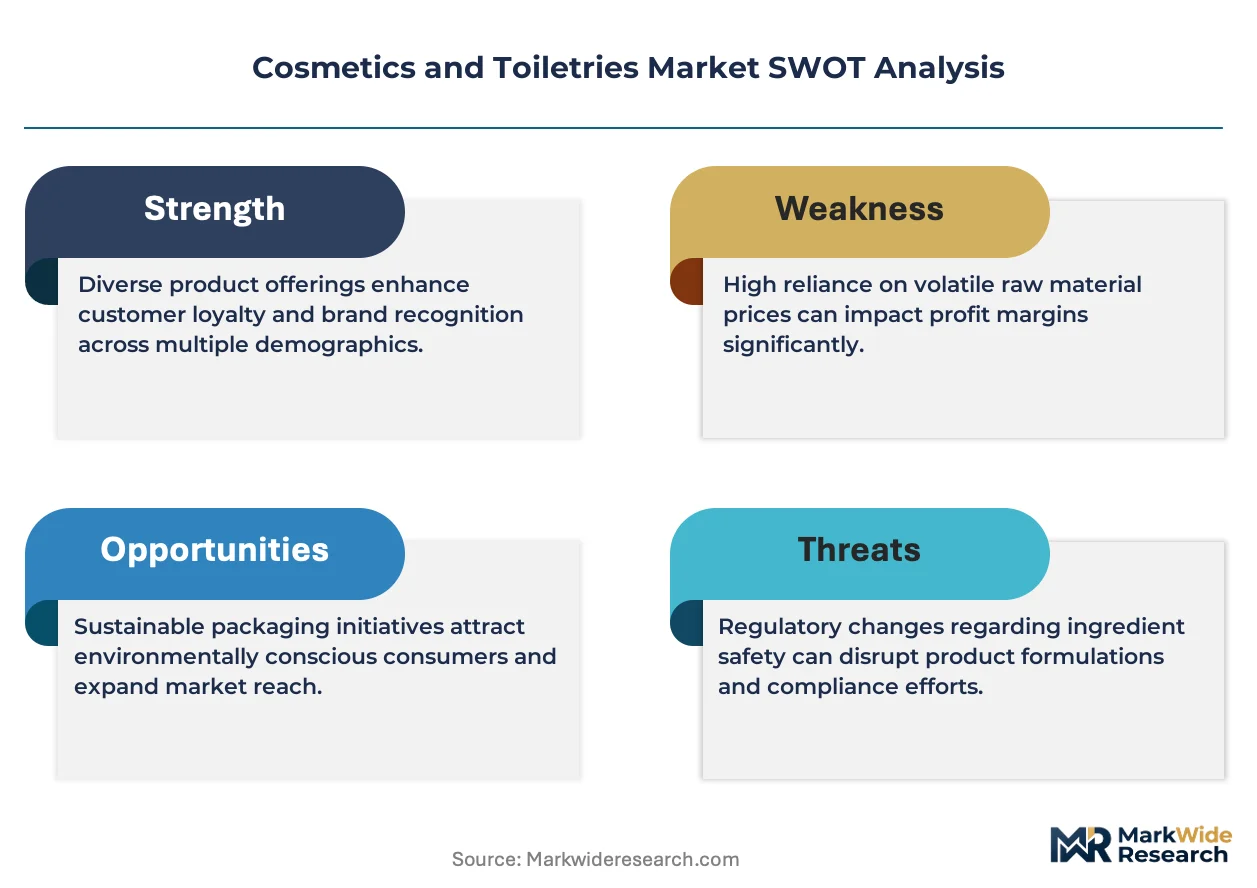
FDA oversight of cosmetic safety in the United States, combined with EU REACH chemical restrictions and MoCRA modernization requirements, is elevating compliance costs while simultaneously creating barriers against unvalidated entrants. EMA-aligned cosmetic ingredient assessments in Europe and state-level clean beauty legislation in California are fragmenting the regulatory map that multinationals must navigate. Stakeholders must monitor diverging national safety standards while building formulation flexibility that permits rapid regional adaptation without full product line redevelopment.
Market Dynamics
EU REACH chemical restrictions are forcing wholesale reformulation across European supply chains, bifurcating the competitive landscape between compliant multinationals and excluded regional challengers while simultaneously elevating R&D expenditure thresholds.
Growth Catalysts
- Prestige beauty spending:Professional women in metropolitan centers are elevating expenditure on heritage and domestic labels alike, particularly in China's tier-one cities where disposable income concentration supports premium positioning.
- MoCRA modernization:The FDA's updated cosmetic safety framework in the United States is accelerating compliance investments that simultaneously validate market entrants with robust safety documentation.
- Biotechnology fermentation:Lab-grown active ingredients are displacing botanical extraction, enabling supply security and batch consistency for dermocosmetic formulations targeting clinical validation.
Market Restraints
- Raw material volatility:Specialty lipid and peptide feedstock costs fluctuate with agricultural commodity cycles and energy prices, compressing margin predictability for mid-tier manufacturers.
- Regulatory fragmentation:Divergent safety standards between California's state-level clean beauty legislation, EU REACH, and FDA oversight create compliance complexity requiring parallel formulation tracks.
- Preservative system limitations:Clean-label demands are restricting traditional paraben and formaldehyde-releasing chemistries, narrowing the viable antimicrobial toolkit for water-based emulsions.
Strategic Opportunities
- Travel retail recovery:Airport and duty-free channels are rebounding as premium brands rebuild controlled distribution networks previously anchored by department store concessions.
- ISO 22716 certification arbitrage:Good Manufacturing Practices compliance creates procurement preference among pharmacy and professional channels, excluding uncertified regional competitors from institutional contracts.
- Men's grooming penetration:Underdeveloped male-specific skincare routines in South Korea and Japan present white space for gender-targeted dermocosmetic lines with simplified regimen positioning.
Industry Challenges
- Formulation scientist scarcity:The intersection of cosmetic chemistry, dermatological science, and regulatory affairs commands premium compensation, constraining R&D expansion for emerging brands.
- Preservative-free stability engineering:Alternative antimicrobial systems require extended validation timelines and accelerated aging studies, delaying product launch cycles by 12-18 months.
- Supply chain reconfiguration:Regional manufacturing mandates and chemical substance restrictions are forcing redundant production footprints, elevating capital intensity for geographic coverage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cosmetics and Toiletries Market |
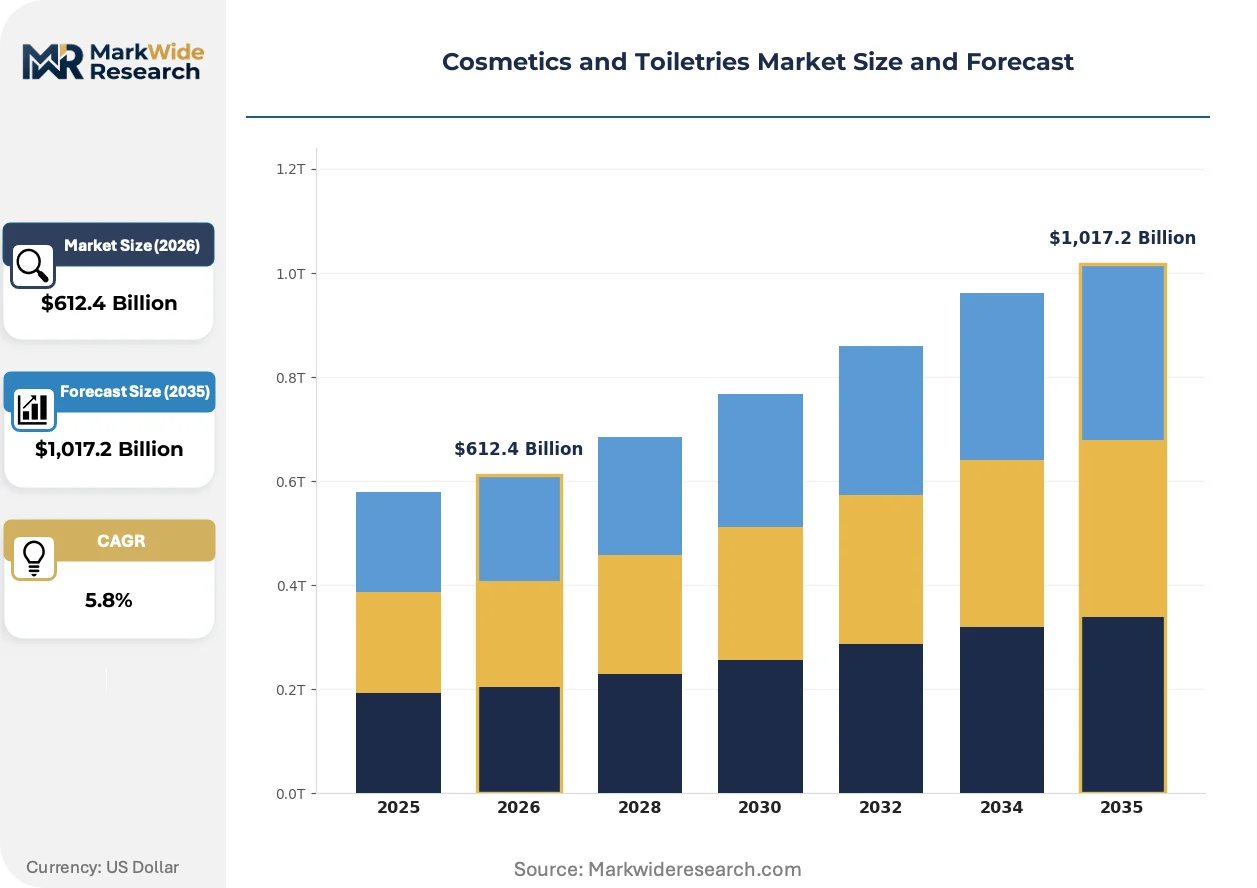
| Market Size in 2026 | $612.4 Billion |
| Market Size in 2035 | $1,017.2 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Haircare, Fragrance, Makeup End User: Women, Men, Children, Unisex Distribution Channel: Online, Supermarkets, Specialty Stores, Pharmacies Packaging Type: Tubes, Jars, Sprays, Bottles |
| Companies Covered | Procter & Gamble, Chanel, L'Oréal, Shiseido, Beiersdorf, Unilever, LVMH, Coty, Estée Lauder, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cosmetics and Toiletries Market Emerging Trajectories
Active ingredient delivery systems are converging with dermatological credibility demands, compressing the gap between cosmetic and pharmaceutical efficacy claims while reshaping how brands validate product performance.
Encapsulation technology using lipid nanoparticles and microspheres is miniaturizing active ingredient delivery, enabling targeted penetration of retinoids and antioxidants without irritation. Prestige skincare brands in South Korea and France are adopting these systems at scale. This convergence is compressing the efficacy gap between professional treatments and at-home regimens, forcing clinic-channel brands to accelerate innovation cycles.
REACH authorization requirements for endocrine-disrupting chemicals are eliminating legacy preservative and UV filter chemistries from European formulations. Manufacturers are rebuilding supply chains around ECHA-approved alternatives, with sunscreen and baby care categories facing the steepest reformulation burdens. Brands with integrated R&D campuses are responding faster than contract manufacturers dependent on shared ingredient libraries.
Ingredient transparency preferences are shifting purchasing authority toward verification platforms and third-party certification bodies. Clean beauty retailers and pharmacy channels are displacing traditional department store counters as primary discovery venues, particularly among millennial and Gen Z demographics. This rotation is most visible in Germany and the Netherlands, where environmental and health certifications carry decisive weight in household purchasing decisions.
Cosmetics and Toiletries Market Segmentation
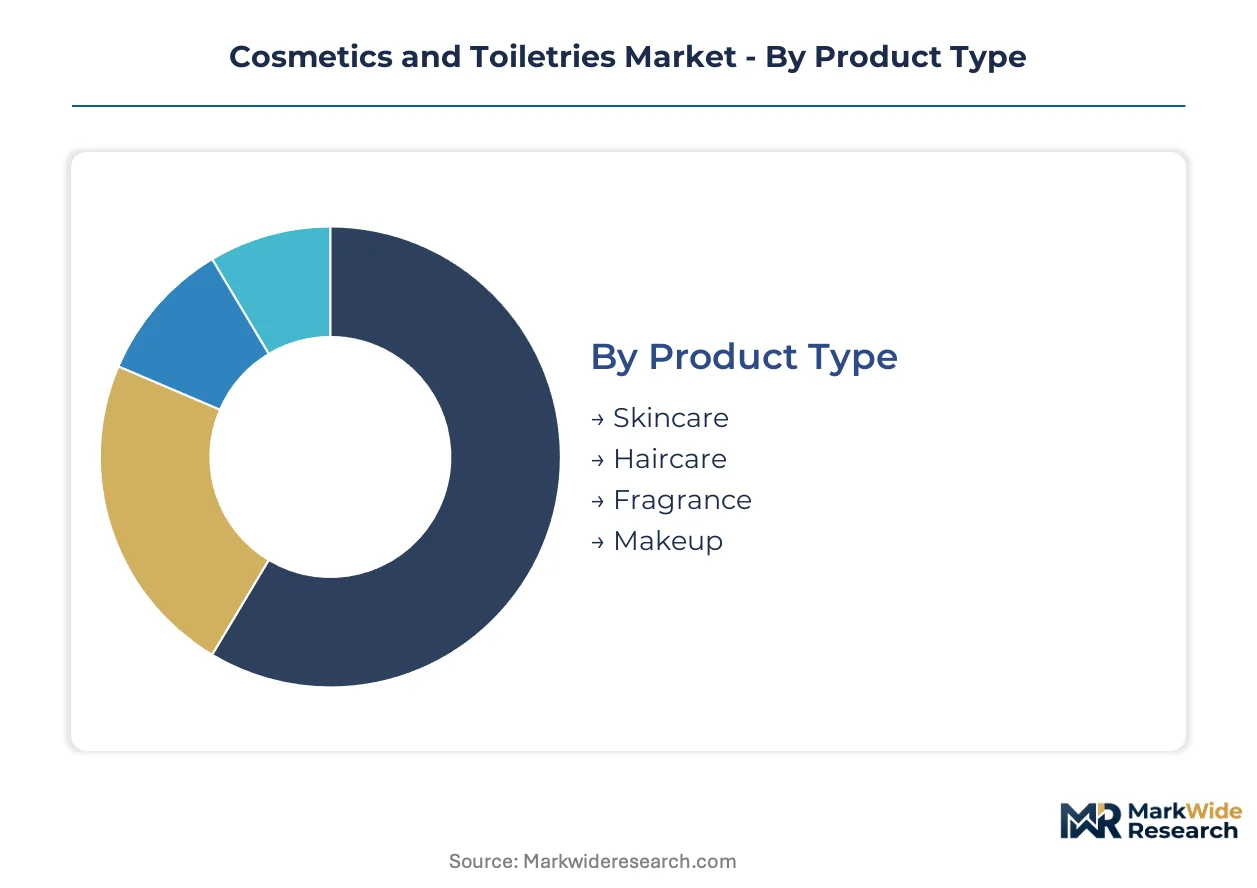
Segmentation in cosmetics and toiletries reveals how margin pools shift between clinical validation and mass accessibility. Manufacturers configure formulation intensity, channel strategy, and packaging engineering differently for each slice of demand.
Product Type:
Margin concentration follows dermatological credibility rather than volume throughput in this category.
- Skincare:Active ingredient formulations with specified pH ranges and preservative systems command premium positioning. Demand concentrates in China's tier-one cities where domestic brands compete aggressively with heritage Western labels on clinical validation claims.
- Haircare:Emulsification-based preparations targeting scalp health and aesthetic enhancement span mass to professional salon channels. Professional women in metropolitan centers elevate spending on solutions bridging cosmetic and trichological science.
- Fragrance:Aerosol-filled and compounded scent preparations face structural channel pressure from online platforms capturing volume previously routed through department counters.
- Makeup:Color cosmetic formulations manufactured through compounding processes confront similar digital displacement, with specialty store foot traffic declining relative to e-commerce discovery.
Skincare holds installed capacity. Haircare is rotating up the share rankings.
End User:
Application context determines formulation complexity and regulatory pathway in this dimension.
- Women:Multi-step regimen expectations drive the broadest SKU proliferation across cleansing, treatment, and protection categories. Prestige beauty spending from professional women in metropolitan centers sustains premium tier expansion.
- Men:Simplified positioning and gender-specific dermocosmetic lines target underdeveloped skincare routines in South Korea and Japan where male grooming penetration remains below female benchmarks.
- Children:Mild preservative systems and tear-free chemistries impose stricter safety documentation requirements under FDA and EU REACH frameworks.
- Unisex:Neutral positioning and minimalist ingredient lists appeal to shared household purchasing decisions, particularly in Germany and the Netherlands where environmental certifications carry decisive weight.
Women anchor current revenue contribution. Men is expanding most quickly as gender-targeted lines gain distribution.
Distribution Channel:
Channel selection dictates compliance requirements and discovery mechanics simultaneously.
- Online:Direct-to-consumer platforms and marketplace aggregators now capture substantial fragrance and makeup volume. Third-party verification platforms are shifting purchasing authority away from traditional counters.
- Supermarkets:Mass-market skincare and haircare move through high-velocity retail formats where price-per-unit sensitivity dominates selection.
- Specialty Stores:Controlled environment concessions anchor premium positioning for heritage labels, though foot traffic erosion pressures this channel's historical role in discovery.
- Pharmacies:ISO 22716 certification creates procurement preference among professional channels, excluding uncertified regional competitors from institutional contracts.
Pharmacies hold installed capacity. Online is climbing the fastest as platform infrastructure matures.
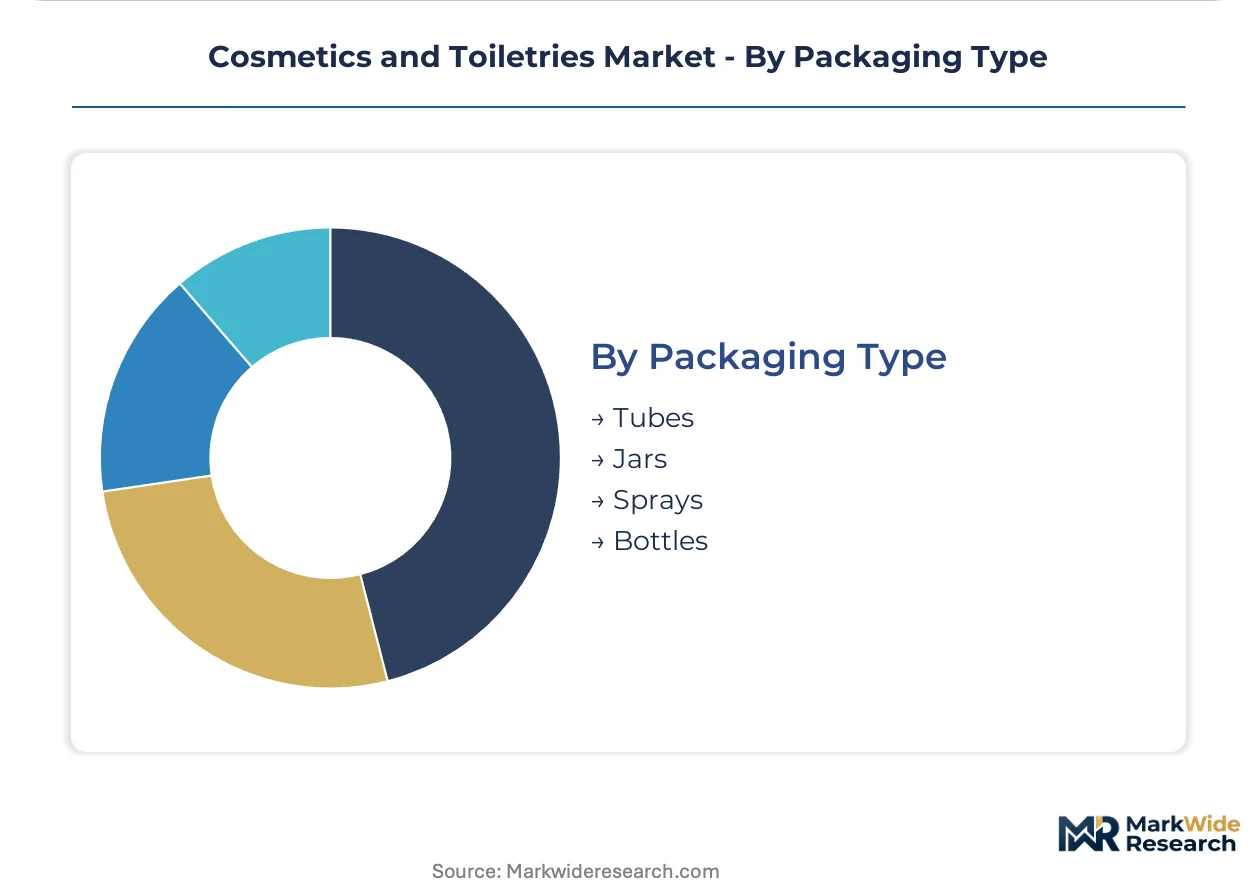
Packaging Type:
Engineering specifications align with product rheology and usage ritual expectations.
- Tubes:Collapsible aluminum and laminate structures suit viscous emulsions and toothpaste-format products. Squeeze-dispense mechanics support controlled dosing for concentrated actives.
- Jars:Wide-mouth containers accommodate cream and balm textures requiring finger application. Oxygen exposure risks necessitate robust preservative systems or airless pump adaptations.
- Sprays:Aerosol and mechanical pump systems deliver fine mist coverage for fragrance and sunscreen categories facing steep EU REACH reformulation burdens on propellant and UV filter chemistries.
- Bottles:Rigid PET and glass formats with flip-top or pump closures dominate liquid formulations across shampoo, conditioner, and body care segments.
Bottles hold installed capacity. Sprays is gaining share fastest as aerosol technology advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Professional women in metropolitan centers anchor demand concentration, with tier-one cities in China, France, Germany, Japan, and the United States generating disproportionate prestige beauty expenditure. Disposable income polarization between urban cores and peripheral regions is intensifying geographic targeting precision.
United States
MoCRA modernization is accelerating compliance investments among domestic and imported brands alike. FDA facility registration mandates and serious adverse event reporting requirements are elevating documentation burdens. New York and Los Angeles metropolitan clusters concentrate prestige beauty spending, with professional women driving elevated expenditure on heritage labels and clinical-positioned skincare.
China
Domestic brands in Shanghai and Beijing are competing aggressively with heritage Western labels on clinical validation claims. NMPA cosmetic registration pathways and ingredient disclosure requirements are fragmenting market access timelines. The Yangtze River Delta manufacturing corridor is absorbing reformulation investments as brands rebuild supply chains around GB standards compliance.
Germany
EMA-aligned cosmetic ingredient assessments and BfR safety opinions are eliminating legacy chemistries from formulations. Dermocosmetic credibility commands decisive weight in pharmacy channel procurement decisions. The Rhine-Ruhr industrial belt hosts concentrated production capacity, with ISO 22716 certification creating procurement preference among institutional buyers.
France
ANSM oversight of cosmetic safety and ECHA REACH authorization requirements are forcing wholesale reformulation across supply chains. Paris and Lyon anchor heritage brand headquarters and integrated R&D campuses. The Île-de-France cluster sustains formulation leadership in active skincare through proximity to dermatological research institutions.
Japan
MFDS-equivalent standards and quasi-drug classification pathways impose distinct regulatory burdens on functional skincare claims. Tokyo and Osaka metropolitan areas concentrate male grooming white space opportunity. METI industrial policy is channeling fermentation biotechnology investments toward lab-grown active ingredient production.
Cosmetics and Toiletries Market Vendor Landscape
Player mix skews toward integrated multinationals with captive R&D infrastructure and certified manufacturing footprints. Tiered competitive structure separates heritage prestige houses, mass-market conglomerates, and regional dermocosmetic specialists. Strategic archetypes include clinical-validation leaders, travel-retail anchoring brands, and biotechnology fermentation pioneers. Dominant competitive moves encompass geographic licensing partnerships and backward integration into active ingredient supply.
Within the heritage prestige tier, L'Oréal and Estée Lauder occupy positions exemplifying integrated R&D campus strategies. Beiersdorf represents the dermocosmetic specialist archetype, competing on clinical validation rather than celebrity marketing. Chanel anchors the luxury fragrance and color cosmetic positioning, sustaining controlled distribution through department store concessions and travel retail networks.
| Leading Market Players |
|---|
| Procter & Gamble |
| Chanel |
| L'Oréal |
| Shiseido |
| Beiersdorf |
| Unilever |
| LVMH |
| Coty |
| Estée Lauder |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts with specialty lipid suppliers lock in both feedstock access and cost visibility for dermocosmetic manufacturers navigating EU REACH reformulation mandates. These arrangements insulate integrated multinationals from agricultural commodity volatility while compressing margin predictability for mid-tier competitors dependent on spot-market peptide sourcing.
Pricing Analysis
Cost-plus contracts indexed to palm kernel oil and shea butter benchmarks dominate raw material procurement for mass-market emulsion manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 22716-certified pharmacy brands from uncertified regional challengers and private-label supermarket suppliers. Pricing pressure stems from clean-label reformulation costs as brands rebuild preservative systems around ECHA-approved alternatives. Mass-market supermarket buyers exhibit highest price sensitivity, while pharmacy channel procurement prioritizes clinical validation over unit economics.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for fragrance houses sourcing compounded essential oils from Grasse and synthetic musk suppliers from Guangzhou. Manufacturing gravity centers on France, China, and Germany, with the Yangtze River Delta and Île-de-France clusters feeding global distribution networks. Specialty lipid and peptide feedstocks draw from Malaysian palm plantations and Danish biotechnology fermentation facilities. Single-source vulnerability concentrates in UV filter chemistries facing REACH authorization delays. Distribution runs through pharmacy and travel retail channels for premium tiers, online platforms for fragrance and makeup discovery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment creates durable defensive moats as compliance documentation burdens compound faster than emerging brands can assemble qualified formulation teams.
For Market Incumbents: Secure captive supply of lab-grown active ingredients through backward integration into biotechnology fermentation capacity, insulating margin structures from botanical extraction volatility. Lock in ISO 22716 certification arbitrage by excluding uncertified regional competitors from pharmacy channel procurement contracts, reinforcing institutional buyer relationships against digital-native challengers. For New Entrants and Emerging Players: Anchor in men's grooming white space across South Korea and Japan, where simplified regimen positioning meets underdeveloped male-specific skincare routines. Target unisex minimalist lines for German and Dutch households where environmental certifications carry decisive weight in shared purchasing decisions. Deploy third-party verification platform partnerships to bypass traditional department store discovery economics. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among dermocosmetic specialists with pharmacy channel anchoring and subscription-format regimen products. Long-term viability favors acquisition targets with integrated R&D campuses and captive fermentation capacity rather than contract-manufacturing-dependent brands. Monitor ECHA authorization timelines for endocrine-disrupting chemical replacements as the critical inflection signal for reformulation cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Biotechnology Fermentation Scale-Up | Lab-grown active ingredient production secures batch consistency for clinical-validation claims under EU REACH. |
| ISO 22716 Certification Investment | Good Manufacturing Practices compliance unlocks pharmacy channel procurement preference against uncertified competitors. |
| Direct-to-Consumer Platform Launch | Online discovery infrastructure captures fragrance and makeup volume shifting from eroding department store counters. |
| Men's Grooming Line Extension | Gender-targeted dermocosmetic positioning addresses underpenetrated male skincare routines in South Korea and Japan. |
| Clean-Label Reformulation Program | Preservative system rebuilding around ECHA-approved alternatives satisfies California state-level legislation and EU REACH. |
Methodological Framework
Operator-level perspectives from formulation scientists, pharmacy procurement managers, brand regulatory affairs leads, and contract manufacturing executives anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through FDA MoCRA facility registration databases, ECHA REACH authorization filings, NMPA cosmetic registration records, and customs trade flow data for specialty lipid and peptide feedstocks. Bottom-up SKU-level volume estimates triangulated against top-down category expenditure models.
Sensitivity analysis tested forecast robustness across regulatory implementation timelines and biotechnology fermentation cost curves. Segmentation dimensions modeled include product type, end user archetype, distribution channel, and geographic regulatory cluster. CAGRs derived from regression-adjusted historical growth patterns applied to penetration and pricing assumptions. Key inputs encompassed REACH authorization progress for endocrine-disrupting chemicals and travel retail passenger traffic recovery trajectories.
Material uncertainties — regulatory authorization delays, agricultural commodity price spikes, and channel shift acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions on compliance cost pass-through rates and pharmacy channel share evolution. Practitioners should keep alternative scenarios live as ECHA substance evaluation priorities and MoCRA enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Emea Beauty Devices Market
Beauty & Personal Care
South Korea Dermocosmetics Market
Beauty & Personal Care
Facial Rollers Market
Beauty & Personal Care
DIY Face Mask Machine Market
Beauty & Personal Care
UK Vegan Cosmetics Market
Beauty & Personal Care
Europe Cosmeceuticals Market
Beauty & Personal Care
Luxury Personal Care and Cosmetics Market
Beauty & Personal Care
Color Protection Shampoo Market
Beauty & Personal Care
Beauty Oils Market
Beauty & Personal Care
United States Male Grooming Products Market
Beauty & Personal Care
India Hair Oil Market
Beauty & Personal Care
Oil Control Shampoo Market
Beauty & Personal Care
France Dermocosmetics Market
Beauty & Personal Care
Anti-Aging Beauty Device Market
Beauty & Personal Care
Japan Beauty and Personal Care Products Market
Beauty & Personal Care
Saudi Arabia Hair Care Market