
 Baby Care and Mother Care Market | 2026-2036
Baby Care and Mother Care Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Care and Mother Care Market Analysis
Chinese diaper manufacturers is decoupling from imported pulp dependency by building regional fluff-pulp capacity. Procter & Gamble leverages its North American supply chain to sustain shelf dominance in mass retail. Kimberly-Clark anchors its competitive edge through intensive R&D in absorbent core polymers. Philips differentiates via medical-grade breast pump technology that commands hospital procurement channels.
Baby Care and Mother Care encompasses formulated hygiene products, feeding equipment, and dermatological preparations engineered with pH-balanced surfactants, hypoallergenic emollients, and FDA Class II medical device specifications for suction-based lactation support. Diapers and baby lotions generate the deepest margin pools due to repeat-purchase frequency and brand loyalty, while breast pumps are capturing the fastest growth trajectory driven by workplace lactation mandates and insurance reimbursement expansion. Online retail is displacing supermarket dominance as the primary distribution vector, particularly among subscription-based replenishment models targeting sleep-deprived parent segments.
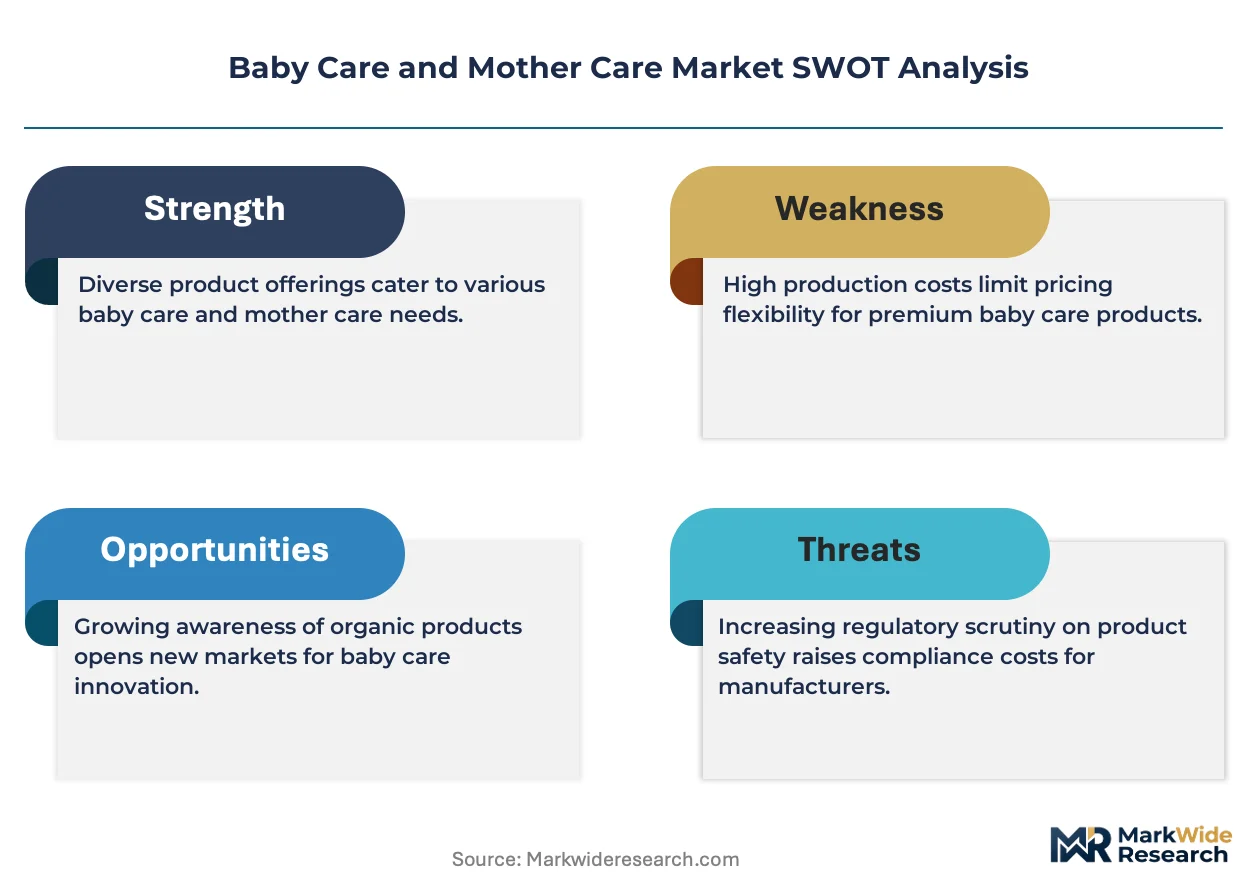
FDA medical device classification, EU REACH chemical restrictions, and China's GB standards on infant product safety collectively elevate compliance costs while screening out subscale competitors. These frameworks reshape demand by mandating clinical validation for breast pumps and restricting phthalate content in plastic feeding accessories. Stakeholders must monitor evolving insurance coverage parity for maternal care devices and anticipate which formulation standards will next converge across major import jurisdictions.
Market Dynamics
Millennial and Gen Z parents are demanding organic formulations and smart monitoring devices, forcing manufacturers to reformulate supply chains around bio-based surfactants and FDA Class II medical device compliance for lactation technology.
Growth Catalysts
- Workplace lactation mandates:Insurance reimbursement expansion for breast pumps in the United States is accelerating medical-grade device adoption among working mothers.
- EU REACH chemical restrictions:Phthalate bans in plastic feeding accessories are screening out subscale competitors and consolidating market share among compliant formulators.
- Fluff-pulp regionalization:Chinese diaper manufacturers are building captive pulp capacity, reducing import dependency and stabilizing input costs for absorbent core production.
Market Restraints
- Superabsorbent polymer concentration:Three chemical conglomerates control global SAP supply, exposing diaper manufacturers to input price volatility and allocation risk.
- GB standards compliance costs:China's infant product safety testing requirements impose six-figure certification burdens that bar regional entrants from national distribution.
- Reusable diaper substitution:Cloth diaper subscription services are capturing environmentally conscious parents in urban coastal markets, compressing disposable volume growth.
Strategic Opportunities
- Subscription replenishment models:Sleep-deprived parent segments in India are adopting auto-replenishment for diapers and lotions through direct-to-consumer platforms.
- Sensor-embedded wearables:Convergence of IoT moisture detection with dermatological monitoring is creating premium diaper tiers with real-time skin health alerts.
- PLI scheme manufacturing incentives:India's production-linked incentive framework for medical devices is attracting breast pump assembly investment for export to Southeast Asia.
Industry Challenges
- Biopolymer scale-up timelines:Bio-based absorbent materials require 18-24 month validation cycles that delay organic product line launches past competitor windows.
- Cross-border formulation harmonization:Divergent FDA, REACH, and GB preservative limits force manufacturers to maintain parallel SKUs, inflating inventory complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Care and Mother Care Market |
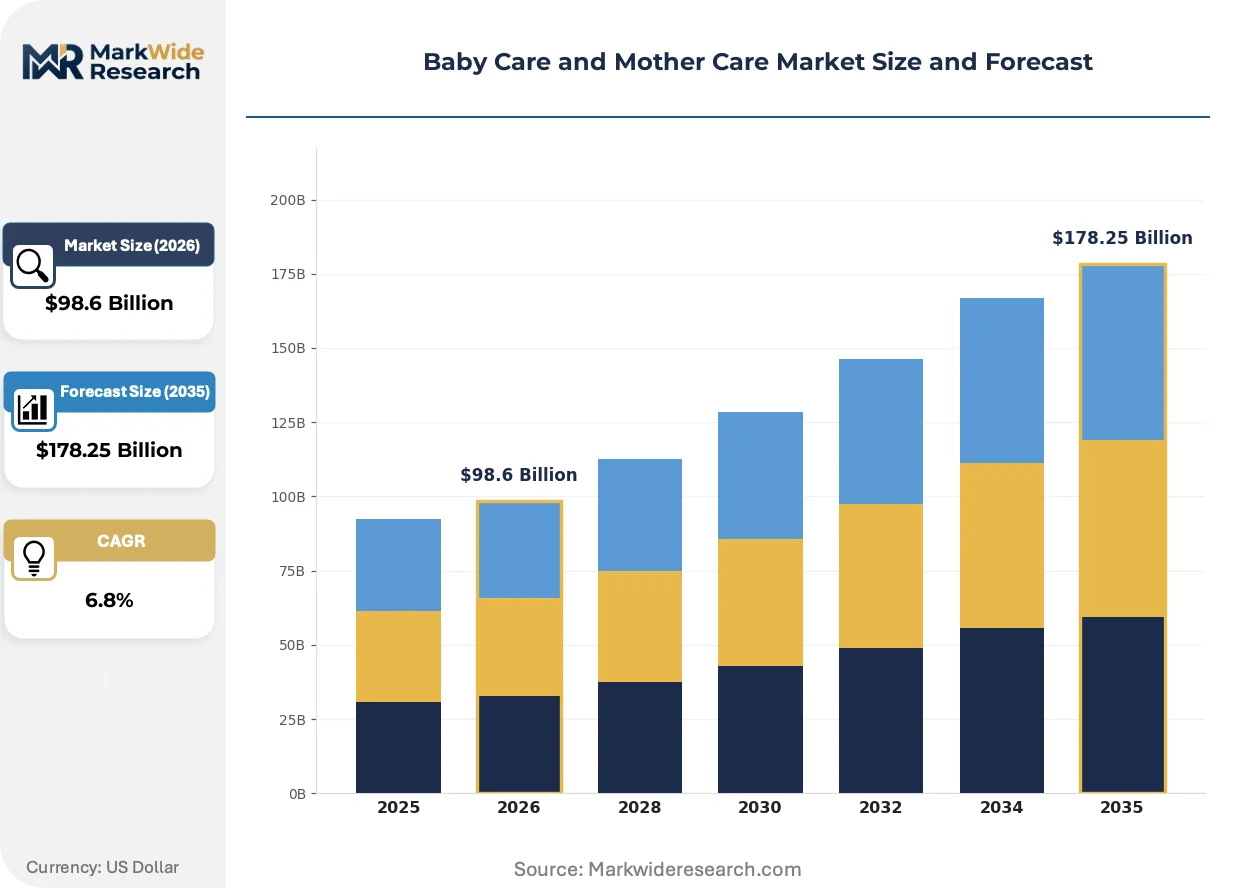
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $178.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
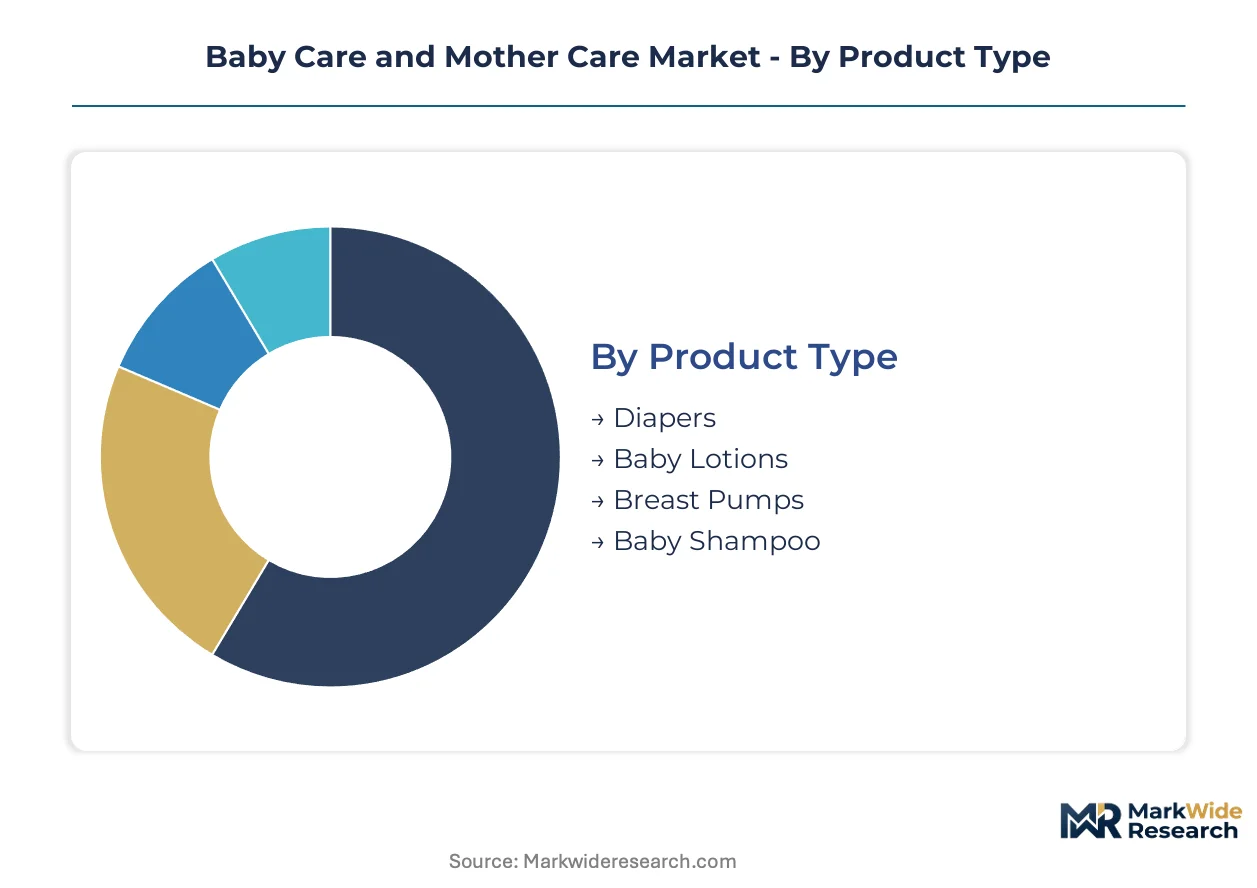
| Segmentation | Product Type: Diapers, Baby Lotions, Breast Pumps, Baby Shampoo Application: Infant Care, Maternal Care, Skin Protection, Hygiene End User: Parents, Caregivers, Healthcare Providers, Retailers Distribution Channel: Online Retail, Supermarkets, Pharmacies, Specialty Stores |
| Companies Covered | Kimberly-Clark, Nestlé, Procter & Gamble, Artsana, Philips, Johnson & Johnson, Unilever, Medela, Pigeon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Care and Mother Care Market Emerging Trajectories
Formulation science and connected hardware are converging to create predictive care ecosystems, while regulatory fragmentation is forcing modular compliance architectures across jurisdictions.
Smart breast pump technology is electrifying the maternal care segment through app-integrated suction modulation and milk volume analytics. Working mothers in the United States and Germany are adopting these devices at triple the rate of conventional pumps. This capability compression is enabling remote lactation consulting and insurance-preferred procurement tiers that marginalize basic mechanical alternatives.
EU MDR medical device classification is extending clinical validation requirements to previously exempt feeding accessories. Manufacturers must now submit biocompatibility testing for silicone nipples and bottle assemblies. The breast pump segment faces the steepest compliance burden, with European market entry timelines extending by 8-12 months for non-notified bodies.
Parent buying patterns are fragmenting across channel types, with subscription platforms displacing supermarket bulk purchases for routine replenishment categories. Mass retailers are responding with private-label organic tiers and in-store telehealth kiosks for lactation support. This channel diversification is most pronounced in Chinese tier-1 cities and US coastal metropolitan areas where delivery speed outweighs price sensitivity.
Baby Care and Mother Care Market Segmentation
Segmentation in the Baby Care and Mother Care market reveals how purchasing authority, usage context, and channel access reshape product development priorities. Manufacturers must align formulations and device specifications with distinct buyer workflows across infant hygiene, maternal health, and dermatological protection.
Product Type:
Buyers in this category segment by replenishment frequency and margin durability, separating disposable consumables from durable medical devices.
- Diapers:Engineered with superabsorbent polymer cores and breathable outer layers to manage moisture retention across 8-12 hour wear cycles. Demand clusters in China, India, and the United States where birth-rate recovery and premium tier expansion are compressing economy share. Regional fluff-pulp capacity builds are stabilizing input costs for absorbent core production.
- Baby Lotions:pH-balanced emulsions incorporating hypoallergenic humectants and barrier-forming occlusives for infant epidermal protection. Parents in Germany and the United Kingdom are prioritizing organic-certified formulations, forcing reformulation cycles around bio-based surfactants. EU REACH chemical restrictions are screening out non-compliant suppliers.
- Breast Pumps:FDA Class II medical devices with suction modulation and milk volume analytics for workplace lactation compliance.
- Baby Shampoo:Tear-free surfactant systems with mild cleansing agents and conditioning polymers for scalp and hair maintenance.
Diapers lead volumes today; breast pumps are gaining share fastest.
Application:
Usage context determines formulation rigor and regulatory classification, from cosmetic-grade skin protection to medical-device maternal support.
- Infant Care:Encompasses hygiene management, nutritional feeding, and sleep-environment products for neonates through toddlers. Demand concentrates in Chinese tier-1 cities and Indian metropolitan clusters where nuclear family structures amplify per-capita spending. GB standards compliance costs are consolidating supplier bases.
- Maternal Care:Postpartum recovery devices, lactation support technology, and perineal hygiene formulations for birthing parents. Workplace lactation mandates in the United States and Germany are accelerating medical-grade breast pump procurement through insurance channels. EU MDR classification is extending clinical validation timelines.
- Skin Protection:Barrier creams, diaper rash treatments, and eczema management formulations with colloidal oatmeal or zinc oxide actives.
- Hygiene:Surface disinfection, bottle sterilization, and laundry additives for pathogen reduction in infant environments.
Infant care commands the largest revenue pool; maternal care is expanding most quickly.
End User:
Purchasing authority splits between direct consumers and institutional intermediaries, each imposing distinct validation and procurement workflows.
- Parents:Primary decision-makers for routine replenishment categories, prioritizing convenience, safety certification, and subscription availability. Millennial and Gen Z cohorts in the United States and coastal China are displacing supermarket dominance with direct-to-consumer platforms. Sleep-deprived segments favor auto-replenishment for diapers and lotions.
- Caregivers:Grandparents, nannies, and daycare professionals executing purchases on behalf of employed parents.
- Healthcare Providers:Hospitals, birthing centers, and lactation consultants specifying medical-grade devices for institutional procurement. Insurance reimbursement expansion in the United States is consolidating purchasing through hospital-preferred supplier tiers. FDA medical device classification mandates clinical validation for breast pump recommendations.
- Retailers:Category managers and private-label buyers curating assortment mixes for mass, specialty, and pharmacy channels.
Parents dominate transaction volume; healthcare providers are capturing the steepest expansion trajectory.
Distribution Channel:
Channel selection reflects urgency tolerance, price sensitivity, and the need for tactile evaluation before purchase.
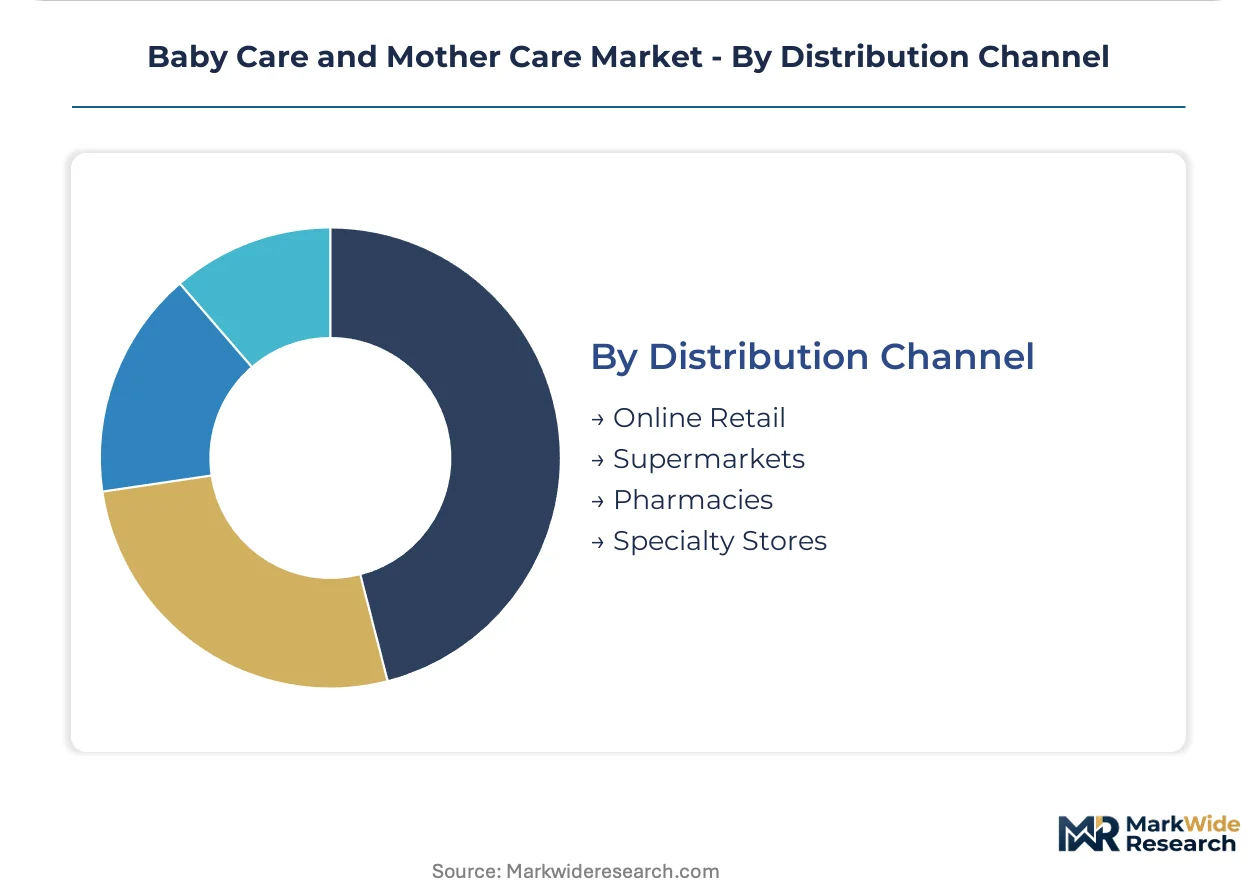
- Online Retail:Direct-to-consumer platforms and marketplace aggregators enabling subscription replenishment and rapid delivery. Urban parents in Mumbai, Shanghai, and New York are prioritizing delivery speed over in-store price comparison. Sensor-embedded wearables and smart breast pumps are concentrating in this channel due to detailed technical content requirements.
- Supermarkets:Mass retail chains with high-frequency foot traffic for emergency replenishment and bulk economy purchases.
- Pharmacies:Licensed dispensaries with pharmacist consultation for dermatological treatments and medical-device guidance. EU markets favor this channel for eczema formulations and nipple care products requiring clinical recommendation.
- Specialty Stores:Maternity boutiques and organic-focused retailers curating premium and niche formulations.
Supermarkets retain the largest footprint; online retail is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping manufacturing footprints as producers migrate toward jurisdictions with streamlined compliance pathways for infant product safety. Cost-of-compliance gaps between REACH-regulated Europe and GB-standard China are accelerating regional capacity builds. Divergent medical device classification timelines are fragmenting breast pump market entry strategies.
China
Domestic diaper manufacturers are constructing captive fluff-pulp mills in Shandong and Guangdong provinces to sever import dependency. SAMR enforcement of GB standards on phthalate content in feeding accessories imposes six-figure certification costs that consolidate supplier bases. The Yangtze River Delta cluster around Shanghai anchors smart breast pump assembly for Southeast Asian export markets.
United States
Workplace lactation mandates in California and New York are accelerating insurance-reimbursed breast pump procurement through hospital-preferred tiers. FDA Class II medical device requirements for suction-based lactation technology extend validation timelines but screen out subscale competitors. The Midwest manufacturing belt sust absorbent core polymer production for North American diaper supply chains.
Germany
Millennial parents in Berlin and Munich are prioritizing organic-certified baby lotions, forcing reformulation around bio-based surfactants. ECHA REACH restrictions on preservative concentrations in infant dermatological products mandate parallel SKU maintenance for export markets. The Baden-Württemberg region concentrates precision injection molding for medical-grade feeding accessories.
India
Nuclear family structures in Mumbai and Delhi-NCR are amplifying per-capita spending on premium diaper tiers and subscription replenishment models. The PLI scheme for medical devices is attracting breast pump assembly investment in Tamil Nadu and Karnataka for ASEAN export. BIS certification requirements for infant product safety are consolidating domestic manufacturing toward scaled players.
Brazil
Urban coastal demand in São Paulo and Rio de Janeiro is fragmenting between disposable diaper bulk purchases and cloth subscription services. ANVISA pharmaceutical-grade requirements for nipple care products channel distribution through licensed pharmacy networks. The Southeast industrial corridor anchors imported polymer conversion for absorbent hygiene products serving Mercosur markets.
Baby Care and Mother Care Market Vendor Landscape
North American producers anchor the premium medical-device tier; Asian fabricators hold volume manufacturing positions in absorbent hygiene. The market structures around three strategic archetypes: diversified consumer health conglomerates with infant nutrition and dermatology portfolios, specialized maternal care device manufacturers with hospital procurement relationships, and regional hygiene specialists with pulp-to-diaper integration. Competitive moves concentrate on backward integration into superabsorbent polymer supply and geographic licensing partnerships for formulation technology.
Among diversified consumer health conglomerates, Kimberly-Clark and Procter & Gamble occupy positions defined by North American retail shelf dominance and absorbent core R&D investment. Philips exemplifies the medical-device specialist archetype through hospital-preferred breast pump procurement channels. These three entities represent distinct competitive vectors: pulp supply security, retail distribution density, and clinical validation depth.
| Leading Market Players |
|---|
| Kimberly-Clark |
| Nestlé |
| Procter & Gamble |
| Artsana |
| Philips |
| Johnson & Johnson |
| Unilever |
| Medela |
| Pigeon Corporation |
| Others |
Supply Flow & Price Mechanics
EU REACH chemical restrictions on phthalate content in plastic feeding accessories gate both qualified supply and premium-tier pricing access, forcing manufacturers to absorb six-figure certification costs or exit the market entirely. This regulatory filter concentrates pricing power among compliant formulators while compressing margins for subscale competitors unable to amortize validation investments across volume.
Pricing Analysis
Retailer markup layers in mass retail channels absorb margin before products reach shelf, while direct-to-consumer subscription platforms bypass intermediaries entirely. Three-tier pricing structure across premium, standard, and economy levels separates medical-grade breast pumps with FDA Class II validation from basic mechanical alternatives. Cost compression in economy diaper tiers is intensifying because Chinese fluff-pulp regionalization has stabilized input costs and triggered volume competition. Millennial parents in coastal US cities demonstrate lowest price sensitivity, prioritizing organic certification and delivery speed over unit economics.
Supply Chain Analysis
Dual-sourcing requirements for superabsorbent polymers have become standard practice among major diaper manufacturers after supply allocation disruptions exposed single-source vulnerability. Production concentrates in China, the United States, and Germany, with absorbent core polymer production anchored in the US Midwest and precision molding concentrated in Germany's Baden-Württemberg region. Raw material dependencies center on fluff-pulp, superabsorbent polymers, and medical-grade silicone. Tariff exposure on imported pulp feeds into pricing volatility for non-integrated manufacturers. Distribution runs through direct-to-consumer platforms for premium tiers and mass retail for emergency replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by Millennial and Gen Z parent demand-shift toward organic-certified formulations and smart monitoring devices with clinical validation.
For Market Incumbents: Deepen backward integration into superabsorbent polymer supply to defend against input price volatility controlled by three chemical conglomerates. Expand captive fluff-pulp capacity in Shandong and Guangdong provinces to sever import dependency and stabilize absorbent core costs. Prioritize R&D investment in bio-based surfactant formulations ahead of converging EU REACH and China GB preservative standards.
For New Entrants and Emerging Players: Capture subscription replenishment white space in Indian metropolitan clusters where nuclear family structures amplify per-capita spending and auto-replenishment adoption lags coastal China. Target sensor-embedded wearable diapers with real-time moisture detection for premium-tier entry. Deploy direct-to-consumer platform strategy with telehealth integration to bypass mass retail shelf dominance.
For Investors and Strategic Acquirers: Roll-up economics work for regional hygiene specialists with pulp-to-diaper integration because GB standards compliance costs are consolidating fragmented domestic manufacturing bases toward scaled players. Five-to-ten year viability hinges on regulatory convergence across FDA, REACH, and GB frameworks. Watch insurance reimbursement expansion for maternal care devices as the signal for medical-grade breast pump procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluff-Pulp Supply | Chinese manufacturers in Shandong province are severing import dependency to stabilize absorbent core input costs. |
| FDA Class II Medical Device Submission | Breast pump manufacturers gain hospital-preferred procurement tiers through clinical validation and insurance reimbursement pathways. |
| Direct-to-Consumer Platform Launch | Subscription replenishment models capture sleep-deprived parent segments in Mumbai and Delhi-NCR with auto-replenishment convenience. |
| Bio-Based Surfactant Reformulation | German Millennial parents in Berlin and Munich are forcing organic-certified baby lotion transitions ahead of REACH restrictions. |
| Smart Sensor Wearable Integration | IoT moisture detection convergence creates premium diaper tiers with real-time dermatological monitoring for urban coastal markets. |
Methodological Framework
Multiple input streams — primary interviews with supply chain directors at absorbent hygiene manufacturers, regulatory affairs leads navigating FDA and EU MDR classifications, and hospital procurement managers specifying medical-grade devices — were reconciled against secondary validation from customs trade data, SEC 10-K filings, and GPO contract databases. Bottom-up modeling of diaper, lotion, and breast pump unit economics was cross-checked against top-down market sizing from retail audit data and insurance reimbursement filings.
Data-stream reconciliation across product type, application context, end-user purchasing authority, and distribution channel density shaped the analytical framework over the projection horizon. CAGRs were derived from segmented demand elasticity modeling and input cost trajectory assumptions. Forecast inputs incorporated birth-rate recovery patterns in China, India, and the United States alongside workplace lactation mandate expansion and organic certification adoption curves.
Regulatory timeline delays, raw material allocation disruptions, and insurance reimbursement parity shifts are the dominant revision risks to modeled outputs. Deviation in EU MDR medical device classification enforcement would shift the breast pump segment outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Baby Changing Light Market
Baby Products
Baby Products Detergents Market
Baby Products
Breastfeeding Accessories Market
Baby Products
Smart Pacifier Market
Baby Products
Baby Care Products Market
Baby Products
Baby Swing Market
Baby Products
LAMEA Baby Care Products Market
Baby Products
Baby Food Dispensing Spoon Market
Baby Products
Baby Bottle Market
Baby Products
Stroller Rental Market
Baby Products
Asia-Pacific Baby Care Products Market
Baby Products
Smart Crib Market
Baby Products
Baby Seat Liners Market
Baby Products
AI Smart Baby Monitors Market
Baby Products
Baby Bottle Warmer and Sterilizer Market
Baby Products
Baby Stroller Market