
 Europe Male Grooming Products Market | 2026-2036
Europe Male Grooming Products Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Male Grooming Products Market Intelligence
Capital-intensity divergence between mass-market manufacturers and premium specialists is rotating competitive dynamics across the category. L'Oréal S.A. leverages its dermatological research infrastructure to anchor premium pricing in facial care sub-segments. Beiersdorf AG sustains brand equity through sustained Nivea Men investment across Central and Eastern European retail channels. Procter & Gamble Company dominates mass shaving preparations through Gillette's controlled shelf positioning in hypermarket chains.
Europe male grooming products encompass topical preparations and mechanical tools designed for hair management, skin conditioning, and beard maintenance, typically formulated with emollients, surfactants, and active ingredients such as salicylic acid or hyaluronic acid at concentrations between 0.5% and 2%. These products serve commercial purposes ranging from daily hygiene maintenance to professional barber service support across salon and retail environments. Facial cleanser and beard oil formulations now capture expanding margin pools as male consumers cross-purchase from basic shaving cream routines into dedicated skincare regimens. The hair wax segment competes with clay and paste alternatives for styling versatility among urban professionals, while daily care application volumes outpace special occasion purchasing through subscription and auto-replenishment channels.
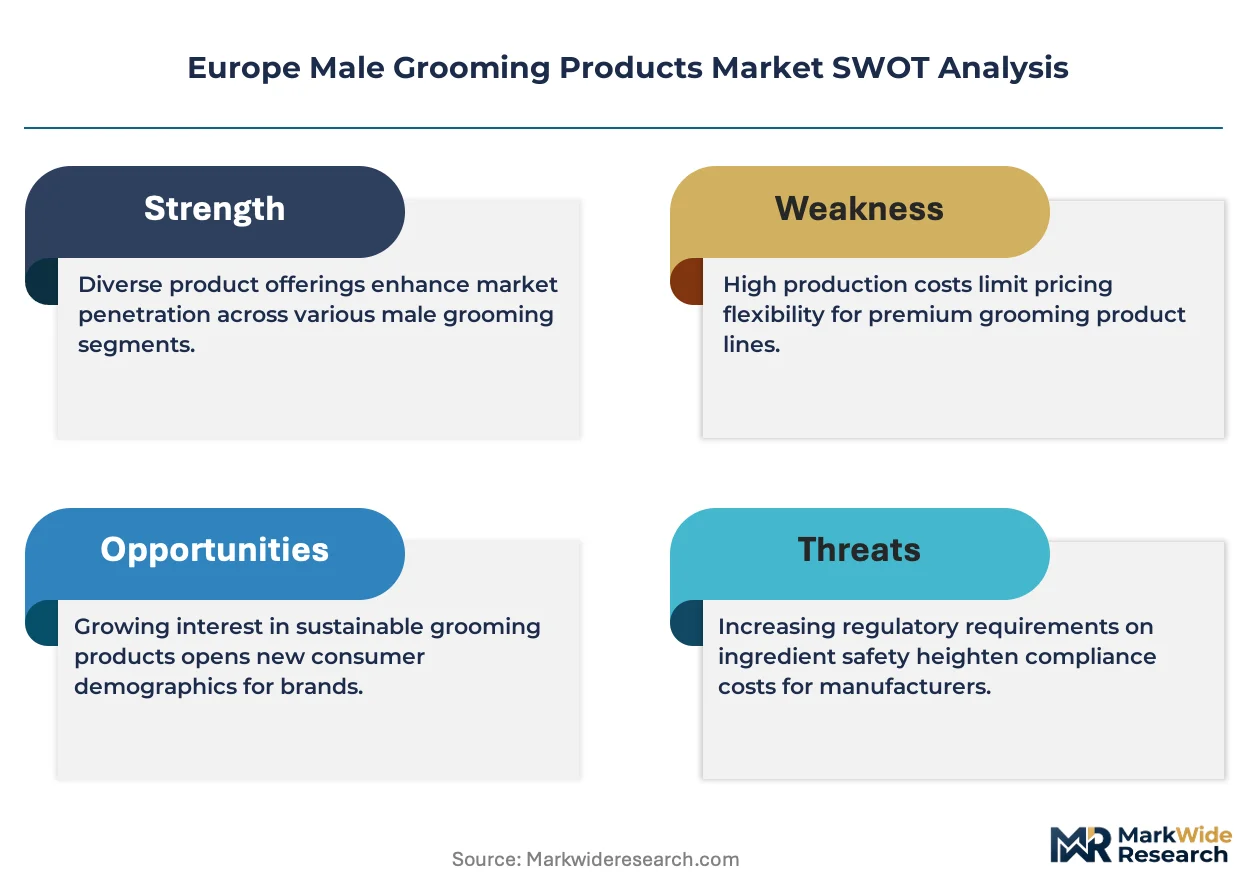
REACH enforcement through ECHA and the EU Green Deal packaging mandates through national environmental agencies are elevating compliance costs for preservative systems and single-use plastic components. EMA cosmetic ingredient classifications and country-level dermatological testing protocols in Germany and France further fragment product registration requirements across the region. Stakeholders must monitor evolving CSRD disclosure obligations and ingredient transparency demands as sustainability credentials become a primary purchase filter rather than a secondary brand attribute.
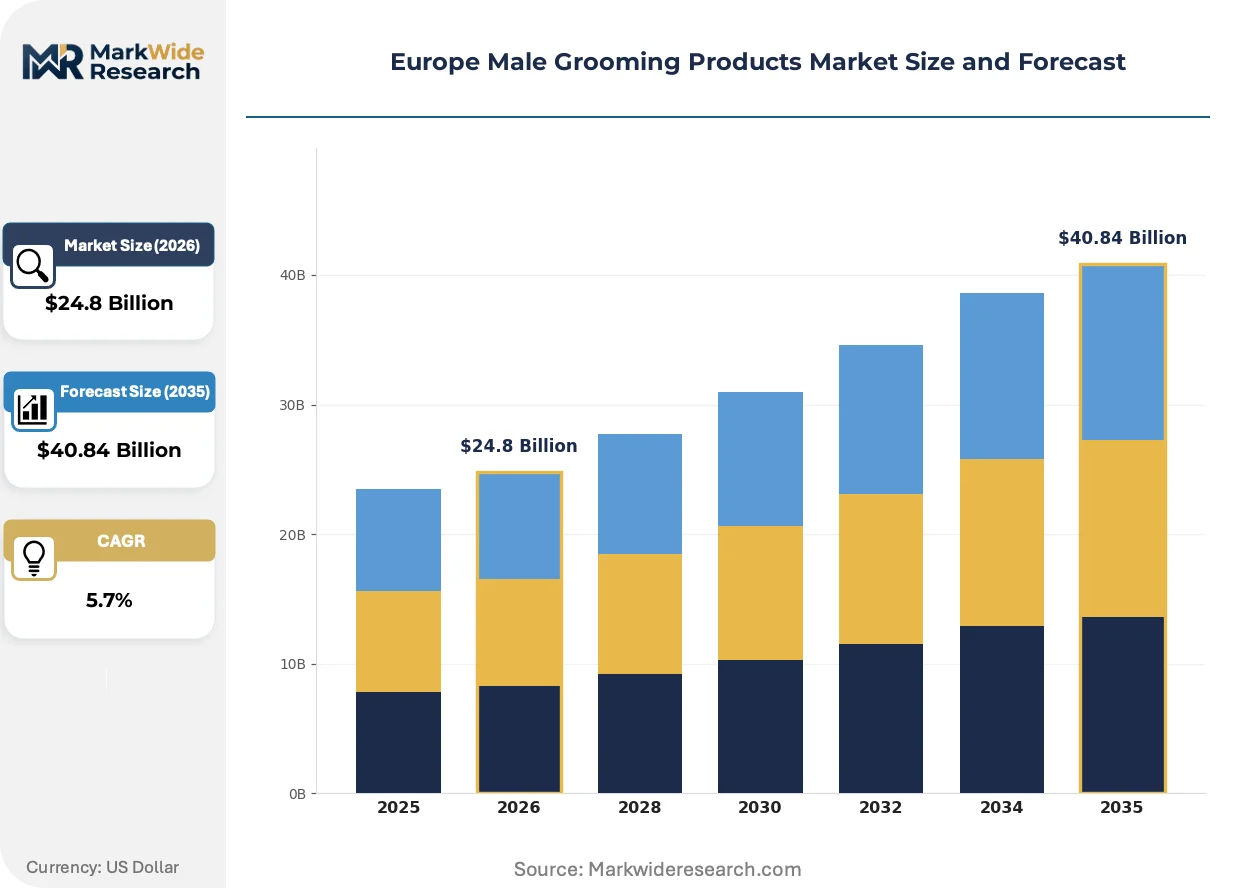
Market Dynamics
REACH compliance and the EU Green Deal are forcing simultaneous reformulation of preservative systems and packaging substrates, compressing margin structures while accelerating premium product development cycles across Western European metropolitan markets.
Growth Catalysts
- Professional salon channel expansion:Barber services across Germany, France, and the United Kingdom are extending treatment menus into dedicated male facial protocols, pulling premium product volumes upward through service bundling.
- CSRD disclosure obligations:Corporate sustainability reporting mandates are elevating ingredient transparency from secondary brand attribute to primary purchase filter among institutional buyers and educated consumers.
- Hyaluronic acid concentration optimization:Formulation advances enabling 1.5% to 2% active concentrations in mass-market cleansers are expanding accessible premium skincare without dermatological consultation barriers.
Market Restraints
- Preservative system cost volatility:ECHA scrutiny of paraben alternatives has concentrated supply of approved phenoxyethanol and ethylhexylglycerin blends among three specialty chemical producers, amplifying input cost exposure.
- Single-use plastic packaging mandates:National environmental agencies in Germany and France are enforcing EU Green Deal timelines that require capital-intensive mold transitions before existing inventory amortizes.
- Biodegradable surfactant performance limitations:Alkyl polyglucoside alternatives to sodium lauryl sulfate exhibit inferior foaming stability in hard water regions of Southern Europe, constraining universal formulation deployment.
Strategic Opportunities
- Central and Eastern European underpenetration:Male skincare routines in Poland, Romania, and Czech Republic remain 40% below Western European per-capita consumption, presenting white space for dedicated men's line launches.
- Auto-replenishment channel development:Subscription mechanics for beard oil and facial cleanser categories are capturing recurring revenue streams that bypass traditional retail margin stacking.
- EMA cosmetic ingredient pre-approval pathways:Early engagement with centralized regulatory assessment is compressing time-to-market for novel active delivery systems versus fragmented national notification procedures.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation expertise bridging dermatological efficacy claims with REACH-compliant preservative architecture commands 35% salary premiums, constraining mid-cap R&D expansion.
- Multi-jurisdictional testing protocols:Divergent dermatological validation requirements between Germany's BfArM and France's ANSM fragment clinical trial designs, extending product registration timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Male Grooming Products Market |
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $40.84 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shaving Cream, Beard Oil, Hair Wax, Facial Cleanser Application: Daily Care, Special Occasion, Professional Use, Travel End User: Millennials, Gen Z, Professionals, Athletes Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Salons |
| Companies Covered | Unilever PLC, Shiseido Company, Beiersdorf AG, The Estée Lauder Companies, Reckitt Benckiser Group, Procter & Gamble Company, Edgewell Personal Care Company, Colgate-Palmolive Co, L'Oréal S.A., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Male Grooming Products Market Strategic Shifts & Innovations
Formulation science, regulatory architecture, and channel mechanics are converging to compress traditional category boundaries between mass and premium male grooming segments.
Microbiome-targeted skincare ingredients are fragmenting established cleansing categories by introducing live culture and postbiotic formulations that challenge surfactant-based foam conventions. Urban professional segments in London and Paris are adopting these products at triple-digit trial rates relative to baseline. This technology is fragmenting shelf-space allocation in pharmacy channels, forcing traditional emollient brands to defend position through reformulation rather than marketing expenditure.
REACH Annex XIV authorization requirements are elevating compliance documentation burdens for fragrance allergens and UV filters across all member states. Manufacturers must now submit comprehensive safety dossiers for substances previously grandfathered under transitional provisions. The facial care sub-segment is responding fastest, with German and French brands accelerating natural fragrance substitution programs ahead of 2027 sunset deadlines.
Subscription-based replenishment models are displacing promotional-driven bulk purchasing in beard maintenance and daily skincare categories. Direct-to-consumer platforms and pharmacy loyalty programs are capturing recurring purchase commitments that reduce price sensitivity and improve demand forecasting precision. This behavioral shift is most visible in Nordic markets where digital pharmacy penetration exceeds 60% and male consumers demonstrate higher auto-replenishment enrollment than Southern European counterparts.
Europe Male Grooming Products Market Segmentation
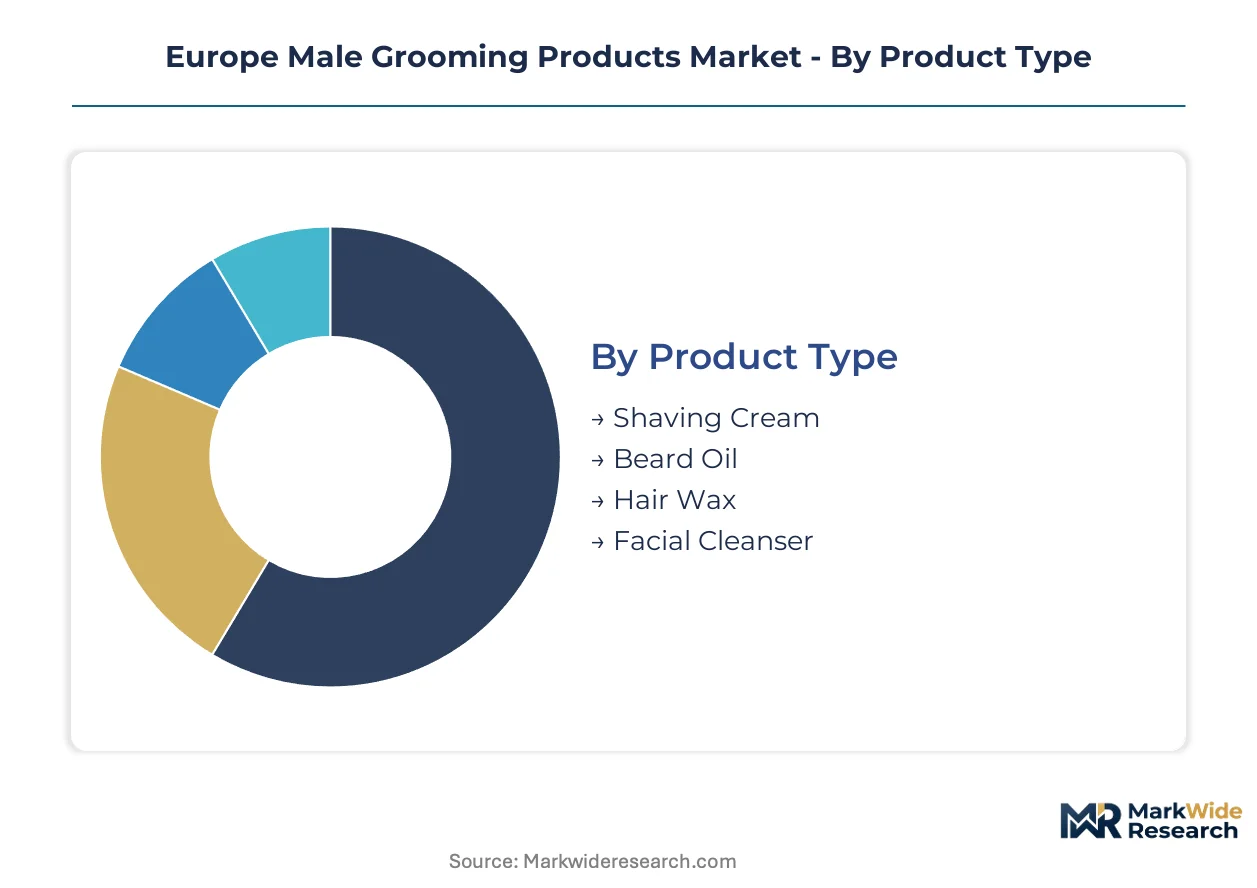
Segment boundaries in Europe male grooming products are dissolving as consumers cross-purchase across traditional price tiers and application occasions. Understanding substitution patterns between product formats and channel behaviors reveals where margin pools are concentrating versus commoditizing.
Product Type:
Beard Oil and Facial Cleanser face the most acute substitution pressure from hybrid skincare-makeup formats and unisex dermatological lines, while Shaving Cream and Hair Wax defend position through ritual-based repurchase loyalty.
- Facial Cleanser:Formulations incorporating 1.5% to 2% hyaluronic acid concentration now match professional-grade efficacy without clinic consultation barriers. Demand concentrates in London, Paris, and Berlin metropolitan markets where male skincare routines rival female category penetration, driven by pharmacy channel expansion and subscription auto-replenishment mechanics.
- Beard Oil:Carrier oil blends with jojoba, argan, and vitamin E at 3% to 5% active concentration target conditioning and styling versatility. Growth accelerates through professional salon bundling in Germany, France, and the United Kingdom, where barber services extend into dedicated male facial protocols.
- Shaving Cream:Emollient-rich preparations with glycerin and stearic acid bases serve daily hygiene maintenance across mass-market retail. Ritual repurchase patterns sustain volume despite electric razor substitution.
- Hair Wax:Petroleum and water-based pomades compete with clay and paste alternatives for styling hold and reworkability. Urban professional segments in Western European capitals drive premium positioning.
Shaving Cream retains volume leadership; Facial Cleanser holds the steepest expansion curve.
Application:
Professional Use commands the widest margin spread as salon service bundling elevates product price realization, while Travel and Special Occasion formats face compression from multi-use product substitution.
- Professional Use:Barber-grade formulations with elevated active concentrations support service protocols in Germany, France, and UK salons. ECHA preservative compliance and REACH documentation requirements elevate entry barriers for mass-market suppliers.
- Daily Care:Subscription mechanics for cleanser and beard oil categories capture recurring revenue streams that bypass traditional retail margin stacking. Nordic digital pharmacy penetration exceeds 60% enrollment rates.
- Special Occasion:Gift sets and limited-edition packaging target seasonal purchasing concentrated in Q4 calendar periods. Price sensitivity limits expansion beyond promotional windows.
- Travel:TSA-compliant sizing and solid-format alternatives address portability constraints. Compression from carry-on liquid restrictions and multi-use product substitution constrains standalone growth.
Daily Care captures the highest purchase frequency; Professional Use delivers the strongest per-unit economics.
End User:
Gen Z and Millennials exhibit the most volatile brand loyalty as social media discovery displaces heritage brand preference, while Professionals and Athletes demonstrate sticky repurchase through routine-based regimen adherence.
- Gen Z:TikTok and Instagram discovery drives trial of microbiome-targeted and postbiotic formulations at triple-digit rates relative to baseline in London and Paris. Sustainability credentials filter purchase decisions ahead of price.
- Millennials:Subscription enrollment and auto-replenishment adoption peak in this cohort, with Nordic markets showing highest platform penetration. Cross-purchase from basic shaving into dedicated skincare regimens accelerates.
- Professionals:Urban workplace grooming standards sustain premium positioning for hair wax and facial cleanser categories. Regimen adherence produces predictable repurchase cycles.
- Athletes:Sweat-resistant and quick-absorption formulations address post-exercise application needs. Niche positioning limits mass-market scale.
Millennials anchor current revenue contribution; Gen Z is climbing the fastest toward majority spend share.
Distribution Channel:
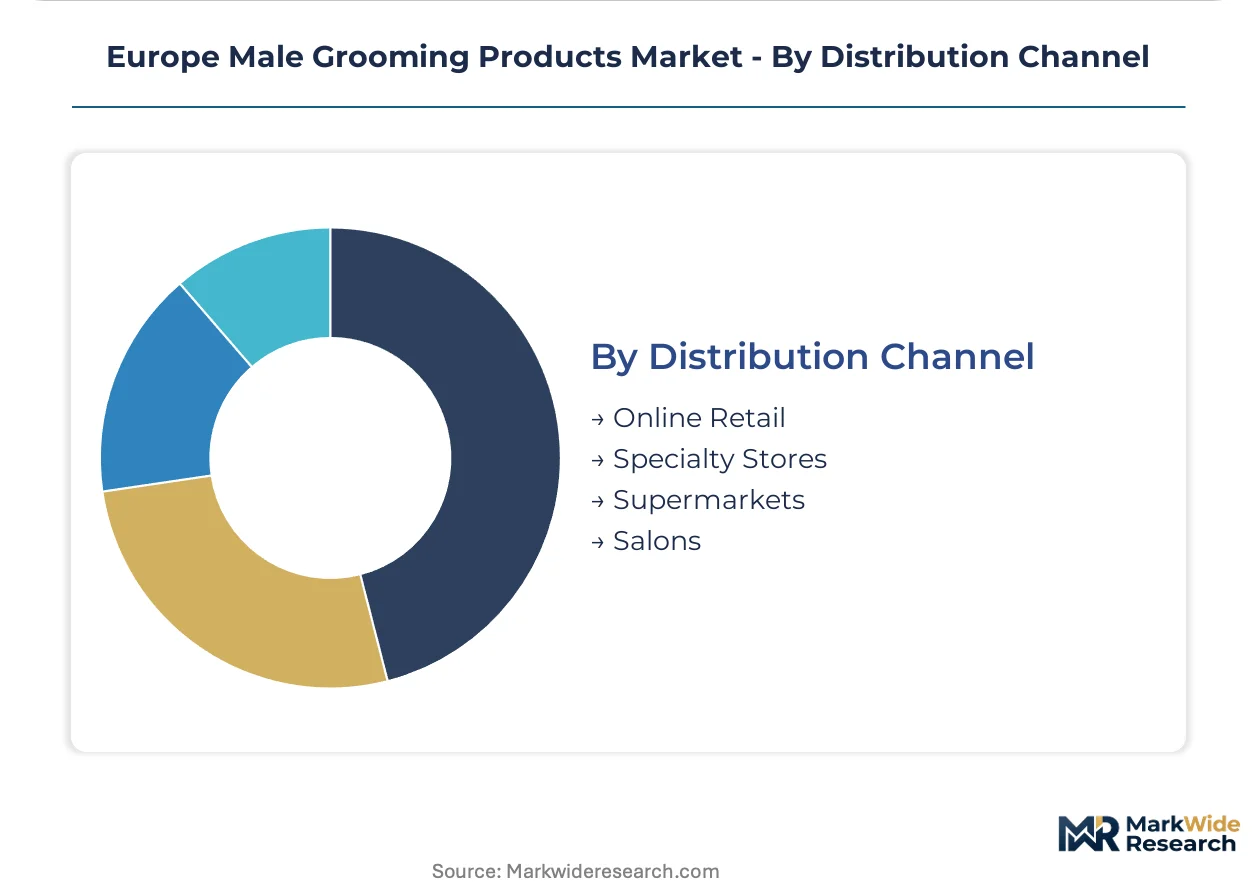
Online Retail and Salons are displacing Supermarket and Specialty Store volumes as discovery and replenishment mechanics fragment across digital and service-integrated channels.
- Salons:Service bundling in German, French, and UK barber shops pulls premium product volumes upward through treatment protocol integration. REACH-compliant formulations with full ingredient disclosure satisfy institutional procurement standards.
- Online Retail:Direct-to-consumer platforms and pharmacy loyalty programs capture recurring purchase commitments that reduce price sensitivity. Auto-replenishment enrollment exceeds 60% in Nordic markets.
- Specialty Stores:Pharmacy and beauty retailer channels defend position through dermatologist endorsement and sampling programs. EMA cosmetic ingredient classification requirements elevate compliance documentation burdens.
- Supermarkets:Hypermarket chains sustain mass-market shaving preparation volumes through controlled shelf positioning. Promotional-driven bulk purchasing faces displacement from subscription models.
Supermarkets retain the broadest reach; Online Retail is gaining share fastest through recurring revenue mechanics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German consumers favor pharmacy-dispensed facial cleansers with documented active concentrations, while British buyers accelerate subscription enrollment for beard maintenance products. French metropolitan markets sustain premium salon-channel bundling unavailable in Southern Europe.
Germany
Pharmacy channel expansion drives facial cleanser volumes in Berlin and Munich metropolitan corridors. BfArM dermatological testing protocols elevate compliance documentation for preservative systems. The Rhine-Ruhr industrial cluster concentrates contract manufacturing capacity serving Central European private-label programs.
United Kingdom
Barber shop service bundling in London and Manchester pulls premium beard oil volumes through treatment protocol integration. CSRD disclosure mandates elevate ingredient transparency requirements for institutional procurement. The Southeast England logistics corridor supports direct-to-consumer fulfillment infrastructure for subscription mechanics.
France
Salon-grade facial protocols in Paris and Lyon sustain premium positioning for professional-use formulations. ANSM cosmetic ingredient classifications fragment product registration timelines versus centralized EMA pathways. The Île-de-France region anchors headquarters operations for heritage men's grooming brands.
Italy
Hair wax and styling pomades capture urban professional demand in Milan and Rome workplace grooming segments. National environmental agencies enforce EU Green Deal packaging timelines ahead of neighboring markets. The Lombardy chemical manufacturing base supplies surfactant inputs for Southern European formulation networks.
Poland
Underpenetrated male skincare routines in Warsaw and Kraków present white-space expansion for dedicated men's line launches. REACH compliance costs concentrate among importers versus domestic producers. The Silesian industrial region develops contract packaging capacity serving Central European distribution networks.
Europe Male Grooming Products Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier competing on formulation differentiation and channel access. Mass-market manufacturers defend shelf positioning through controlled hypermarket relationships, while premium specialists anchor pricing through dermatological endorsement and salon service integration. The competitive landscape features three archetypes: multinational consumer goods conglomerates with dermatological research infrastructure, mid-cap specialists with concentrated men's portfolio focus, and private-label contract manufacturers serving retail channel programs. Dominant competitive moves include portfolio diversification into hybrid skincare-makeup formats and strategic partnerships with professional salon networks for service-bundled distribution.
Among European-headquartered players, L'Oréal S.A. and Beiersdorf AG occupy positions at the integrated leader tier, with the former representing dermatological research-backed premium positioning and the latter exemplifying sustained brand equity investment across retail channel depth. Procter & Gamble Company anchors the mass-market shaving preparation segment through heritage brand recognition and controlled shelf positioning in hypermarket chains. These three entities collectively illustrate the capital-intensity divergence between scale-driven manufacturers and premium specialists that is rotating competitive dynamics across the category.
| Leading Market Players |
|---|
| Unilever PLC |
| Shiseido Company |
| Beiersdorf AG |
| The Estée Lauder Companies |
| Reckitt Benckiser Group |
| Procter & Gamble Company |
| Edgewell Personal Care Company |
| Colgate-Palmolive Co |
| L'Oréal S.A. |
| Others |
Cost & Logistics Intelligence
REACH Annex XIV authorization requirements gate both supplier qualification and price differentiation simultaneously, forcing manufacturers to absorb documentation burdens for fragrance allergens and UV filters while premium brands leverage compliance transparency to justify elevated positioning.
Pricing Analysis
Long-term offtake contracts for phenoxyethanol and ethylhexylglycerin blends dominate preservative procurement, insulating large manufacturers from spot volatility that squeezes mid-cap formulators. Three-tier pricing structure across premium, standard, and economy levels separates salon-grade facial protocols from mass-market shaving preparations, with certification grade and volume scale as primary differentiation levers. Cost compression in the mid-tier intensifies because REACH reformulation expenses concentrate among suppliers lacking dermatological research infrastructure. Institutional buyers in German pharmacy channels exhibit lowest price sensitivity; promotional-driven supermarket shoppers in Southern Europe show highest elasticity.
Supply Chain Analysis
Specialty chemical production for compliant preservative systems concentrates in the Rhine-Ruhr corridor, with jojoba and argan carrier oil sourcing tethered to Moroccan and Israeli agricultural networks. Formulation draws from German surfactant manufacturing, French fragrance compounding, and Italian packaging mold fabrication. Single-source vulnerability runs through the three approved phenoxyethanol producers serving ECHA-compliant markets. Distribution runs through hypermarket chains for mass-market volumes, while salon-integrated service bundling and direct-to-consumer platforms capture premium and recurring revenue segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must navigate substitution defense against hybrid skincare-makeup formats and unisex dermatological lines that are fragmenting traditional male grooming category boundaries.
For Market Incumbents: Shield brand equity through accelerated natural fragrance substitution programs ahead of 2027 REACH sunset deadlines. Deepen backward integration into preservative system production to reduce exposure to the three-supplier concentration in phenoxyethanol blends. Channel control through professional salon network partnerships remains the priority defensive lever against direct-to-consumer challengers.
For New Entrants and Emerging Players: Lead with microbiome-targeted formulations in Warsaw and Kraków, where male skincare penetration trails Western European benchmarks by substantial margins. The most penetrable geography is Central and Eastern Europe, specifically Poland, Romania, and Czech Republic white-space markets. A direct-to-consumer auto-replenishment platform with pharmacy loyalty integration offers the cleanest go-to-market angle.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across facial cleanser sub-segments as hyaluronic acid concentration optimization requires dermatological research infrastructure. The five-to-ten-year viability window favors targets with established EMA pre-approval engagement and salon channel access. Acquisition target archetype: mid-cap specialists with REACH-compliant preservative architecture and subscription platform enrollment. Watch ECHA substance authorization timelines as the inflection signal for input cost compression or expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Salon Service Integration | Barber protocol bundling in London and Paris elevates product price realization above retail benchmarks. |
| Auto-Replenishment Platform Launch | Nordic digital pharmacy penetration exceeding sixty percent enables recurring revenue capture with reduced price sensitivity. |
| Natural Fragrance Substitution Program | German and French brands accelerate reformulation ahead of REACH Annex XIV 2027 sunset deadlines. |
| Central European Distribution Expansion | Warsaw and Kraków underpenetration presents white-space for dedicated men's line launches with pharmacy channel anchoring. |
| Microbiome Formulation Development | Postbiotic and live culture products fragment cleansing categories through triple-digit trial rates in metropolitan markets. |
Research Approach
Desk research of customs records, Nielsen retail audit data, and ECHA substance registration databases preceded structured interviews with brand managers at heritage grooming houses, category buyers at German and French pharmacy chains, formulation chemists at contract manufacturers, and supply planners at specialty chemical distributors. Primary fieldwork combined with secondary validation through SEC filings of listed parent companies and BfArM cosmetic notification records. Bottom-up volume builds across product type, application, end user, and distribution channel dimensions triangulated against top-down market sizing from trade association estimates.
Variance decomposition across segmentation dimensions isolates volume and value drivers throughout the forecast period. The analytical framework models product type substitution patterns, end user cohort migration from Gen Z through Professional segments, and channel shift mechanics from supermarket to online and salon integration. CAGRs derive from fitted growth curves against historical penetration benchmarks and regulatory timeline impacts. Industry-specific inputs include REACH authorization sunset schedules and CSRD disclosure adoption curves across member states.
The analysis sits within stated boundaries; outcomes outside sustained salon channel expansion or accelerated CSRD compliance adoption would require recalibration. Forecasts reflect documented assumptions regarding preservative system cost trajectories and Central European market development pace. Practitioners should keep alternative scenarios live as ECHA substance review timelines and EU Green Deal packaging enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Bath and Body Products Market
Beauty & Personal Care
Australia Beauty and Personal Care Products Market
Beauty & Personal Care
Brazil Sustainable Personal Care Market
Beauty & Personal Care
Beeswax for Cosmetics Market
Beauty & Personal Care
Delivery Systems in Personal Care Market
Beauty & Personal Care
Asia-Pacific Perms and Relaxants Market
Beauty & Personal Care
United Kingdom Cosmetics Products Market
Beauty & Personal Care
Depilatories Market
Beauty & Personal Care
Malaysia Aromatherapy Products Market
Beauty & Personal Care
Beauty Pillowcases Market
Beauty & Personal Care
Skincare Market
Beauty & Personal Care
Global Bath Bomb Market
Beauty & Personal Care
Aftershave Market
Beauty & Personal Care
Anti-Acne Cosmetics Market
Beauty & Personal Care
Natural and Organic Personal Care Market
Beauty & Personal Care
Organic Beauty and Personal Care Ingredients Market