
 Depilatories Market | 2026-2036
Depilatories Market Size, Share, and Industry Trends Forecast 2026-2036
Depilatories Market Analysis
A capital-intensity divergence between mass-market manufacturers and specialized professional-grade suppliers is redrawing competitive boundaries in depilatory formulations. Reckitt Benckiser Group leverages its chemical R&D infrastructure to sustain cost leadership in alkaline cream production across European retail channels. L'Oréal anchors premium positioning through dermatological testing protocols that command shelf space in French pharmacy networks. Edgewell Personal Care competes in North American mass retail by controlling distribution density through exclusive supermarket partnerships.
Depilatories comprise topical or applied preparations designed to chemically dissolve or mechanically remove unwanted hair from epidermal surfaces, typically employing thioglycolate salts at pH 11-12.5 or resin-based wax matrices that adhere to hair shafts for mechanical extraction. Cream formulations dominate unit volume through accessibility and low-skill application, while wax segments capture disproportionate margin pools in professional service channels. Natural formulation sub-categories are expanding fastest as botanical extracts replace synthetic fragrances and preservatives in product positioning. Online retail distribution is displacing pharmacy channels for first-time purchases, though supermarkets retain replenishment loyalty through impulse-placement economics.
FDA cosmetic labeling requirements and EPA chemical substance reporting obligations govern product composition disclosures and manufacturing facility standards in the United States. REACH registration mandates in Europe constrain thioglycolate concentration thresholds and mandate comprehensive safety data sheets for professional salon products. Stakeholders must monitor evolving state-level cosmetic ingredient bans in California and New York, as these jurisdictions increasingly precede federal rulemaking on depilatory chemical safety.
Market Dynamics
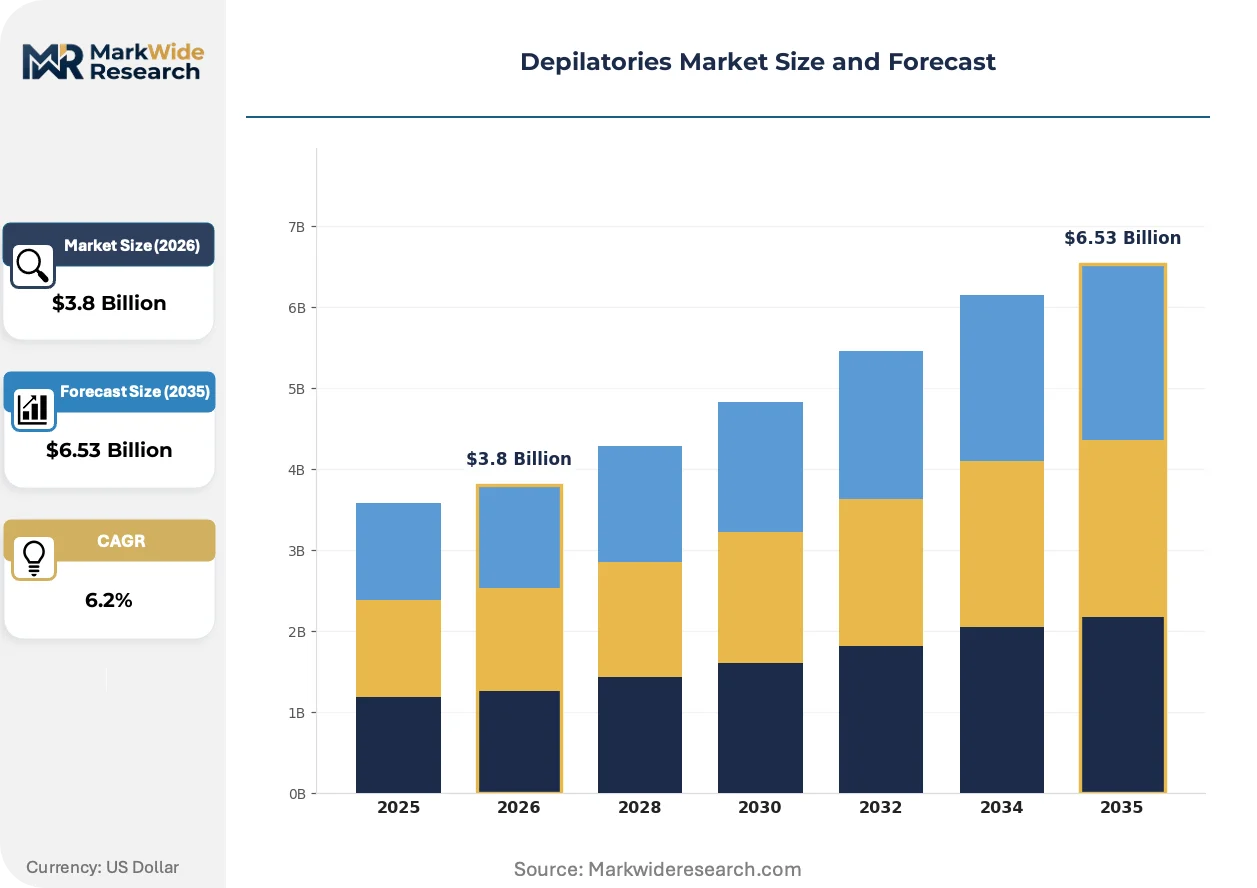
REACH compliance is compressing thioglycolate-based formulations while Southeast Asian urban consumers abandon threading for cream-based home-use products, forcing manufacturers to rebuild supply chains around plant-derived actives.
Growth Catalysts
- EU REACH Thioglycolate Restrictions:Tightening concentration thresholds accelerate botanical extract substitution, opening premium positioning for compliant formulations.
- Brazilian Salon Service Expansion:Professional aesthetic clinics in São Paulo and Rio de Janeiro add premium waxing and sugaring menus, lifting professional-grade resin demand.
- Indonesian Urban Transition:Jakarta and Surabaya consumers switch from traditional threading to home-use depilatory creams, expanding mass-market unit volumes.
Market Restraints
- Caustic Input Cost Volatility:Sodium hydroxide and calcium thioglycolate prices fluctuate with chlor-alkali capacity constraints in China.
- Professional-Grade Supply Concentration:High-performance wax resin production clusters in Germany and Italy, creating single-source vulnerability for North American salon chains.
- Skin Sensitivity Technical Limits:pH 11-12.5 alkaline chemistry cannot penetrate below epidermal layers without irritation, capping efficacy on coarse hair types.
Strategic Opportunities
- Vietnam Underpenetration:Ho Chi Minh City and Hanoi retail channels carry limited professional wax SKUs, offering first-mover shelf space for imported salon brands.
- Online-First Channel Convergence:Direct-to-consumer subscription models bypass pharmacy intermediaries, capturing replenishment loyalty through auto-ship algorithms.
- EU Green Deal Biomass Incentives:R&D tax credits for carbon-neutral feedstocks accelerate sugar-based polymer development for biodegradable wax matrices.
Industry Challenges
- Formulation Chemist Talent Scarcity:Cosmetic chemistry programs produce insufficient graduates familiar with both alkaline depilatory mechanisms and botanical compatibility testing.
- Multi-Jurisdiction Certification Timelines:Parallel FDA cosmetic labeling and EPA facility reporting create 18-24 month product launch delays for US market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Depilatories Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.53 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Creams, Waxes, Gels, Powders Application: Facial Hair Removal, Body Hair Removal, Bikini Line, Sensitive Areas Formulation: Natural, Synthetic, Herbal, Chemical Distribution Channel: Online Retail, Supermarkets, Pharmacies, Specialty Stores |
| Companies Covered | Reckitt Benckiser Group, Church & Dwight, Procter & Gamble, Coty, L'Oréal, Edgewell Personal Care, American International Industries, Nad's Corporation, Jolen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Depilatories Market Emerging Trajectories
Portable at-home laser devices and enzymatic hair-dissolution technologies are compressing the boundary between professional salon efficacy and consumer convenience, while regulatory pressure on alkaline agents accelerates biomaterial substitution.
Diode laser technology is miniaturizing into handheld home-use devices with integrated skin-tone sensors. Upper-middle-income consumers in South Korea and Japan adopt these units for facial hair management. This technology is miniaturizing professional-grade energy delivery into countertop appliances, eroding salon visit frequency for maintenance sessions.
REACH Annex XVII amendments now mandate comprehensive safety data sheets for thioglycolate concentrations exceeding 2.5% in professional salon products. European manufacturers reformulate toward cysteamine derivatives and enzymatic keratinases. Professional-grade suppliers in France and Germany face 12-18 month re-registration cycles, compressing SKU refresh rates.
Subscription-based replenishment models displace supermarket impulse purchases for cream depilatories. Urban Indonesian and Thai consumers auto-replenish via e-commerce platforms, bypassing pharmacy counters. This shift concentrates buyer power with platform algorithms rather than retail merchandisers, altering margin distribution across the value chain.
Depilatories Market Segmentation
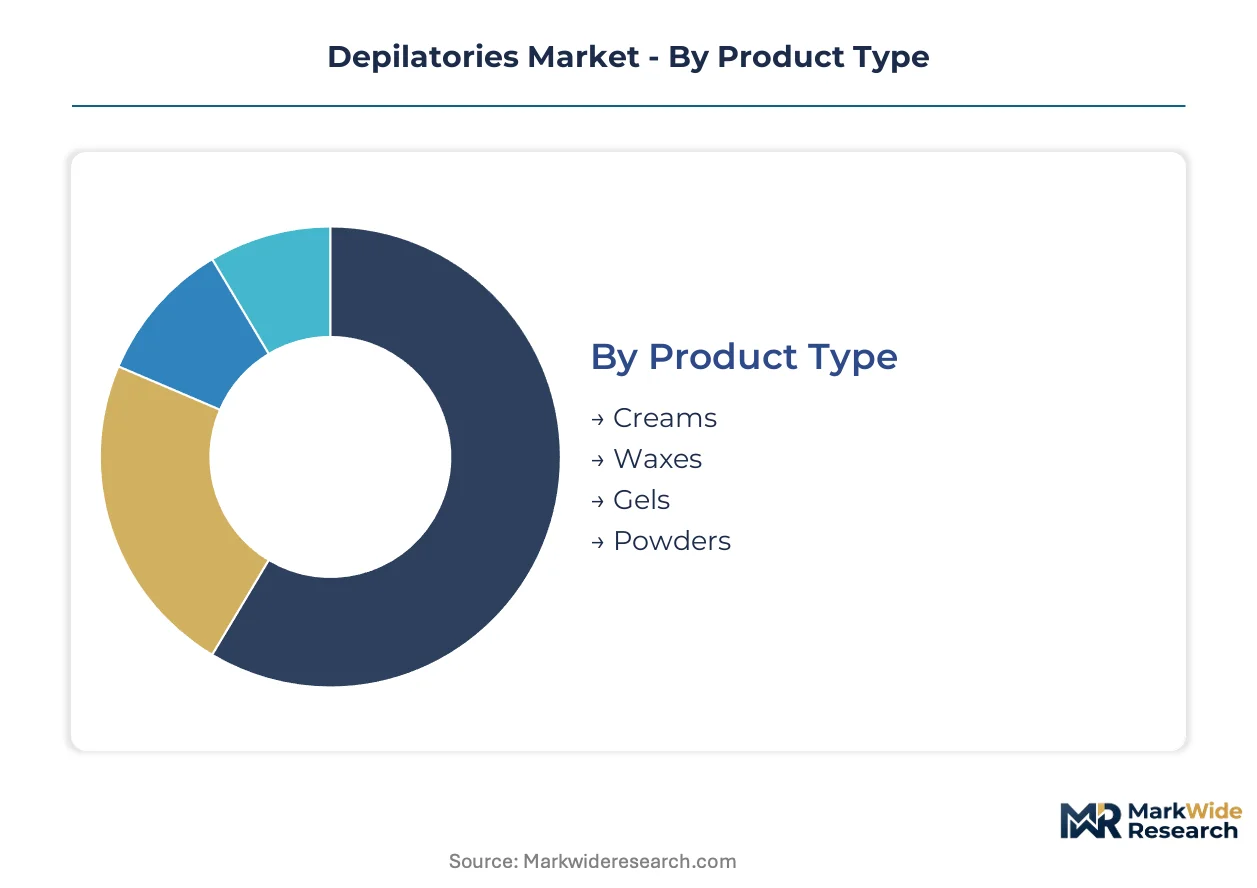
Depilatory manufacturers align R&D portfolios and distribution investments against distinct demand profiles. Each segment carries unique regulatory exposure and margin architecture that shapes competitive positioning.
Product Type:
Cream formulations serve domestic mass-market consumption across Indonesia and Vietnam, while wax exports concentrate through German and Italian professional-grade suppliers.
- Creams:Thioglycolate-based alkaline formulations at pH 11-12.5 dissolve keratin bonds within 5-10 minutes. Demand concentrates in Jakarta and Surabaya households transitioning from threading, constrained by REACH concentration thresholds on professional salon variants.
- Waxes:Resin-based matrices—synthetic or sugar-derived—adhere to hair shafts for mechanical extraction. Brazilian aesthetic clinics in São Paulo and Rio de Janeiro drive professional-grade demand, lifting margin pools through premium service menus.
- Gels:Transparent polymer carriers enable precise facial application; South Korean consumers favor these for upper-lip management.
- Powders:Dry thioglycolate blends require water activation; niche positioning in cost-sensitive Southeast Asian rural markets.
Creams command the established base. The steepest expansion runs through waxes.
Application:
Volume concentrates in body hair removal through mass-market retail, while facial and bikini applications sustain premium pricing through specialized formulation requirements.
- Facial Hair Removal:Precision formulations with reduced pH sensitivity target upper-lip and eyebrow zones. Japanese and South Korean consumers adopt miniaturized diode laser devices, compressing chemical depilatory frequency for maintenance.
- Body Hair Removal:High-volume leg and arm applications drive unit economics for cream manufacturers. Indonesian urban households auto-replenish through e-commerce platforms, bypassing pharmacy intermediaries.
- Bikini Line:Low-fragrance, dermatologically tested variants command shelf space in French pharmacy networks.
- Sensitive Areas:Botanical extract formulations replace synthetic preservatives; EU Green Deal biomass incentives accelerate sugar-based polymer development.
Body hair removal anchors volume throughput. Facial applications are gaining share fastest through device substitution effects.
Formulation:
Natural and herbal variants concentrate production in Southeast Asian export facilities, while synthetic chemistry clusters in European REACH-compliant manufacturing.
- Natural:Plant-derived actives—enzymatic keratinases, cysteamine derivatives—substitute for restricted thioglycolates. French and German manufacturers face 12-18 month re-registration cycles.
- Synthetic:Petrochemical-derived fragrances and preservatives retain cost advantage in mass-market cream production.
- Herbal:Ayurvedic and traditional Chinese medicine extracts position in Indian and Chinese domestic channels.
- Chemical:Alkaline thioglycolate salts face tightening concentration caps; sodium hydroxide input costs fluctuate with Chinese chlor-alkali capacity.
Chemical formulations hold the incumbent position. Natural variants are climbing the fastest on regulatory pressure.
Distribution Channel:
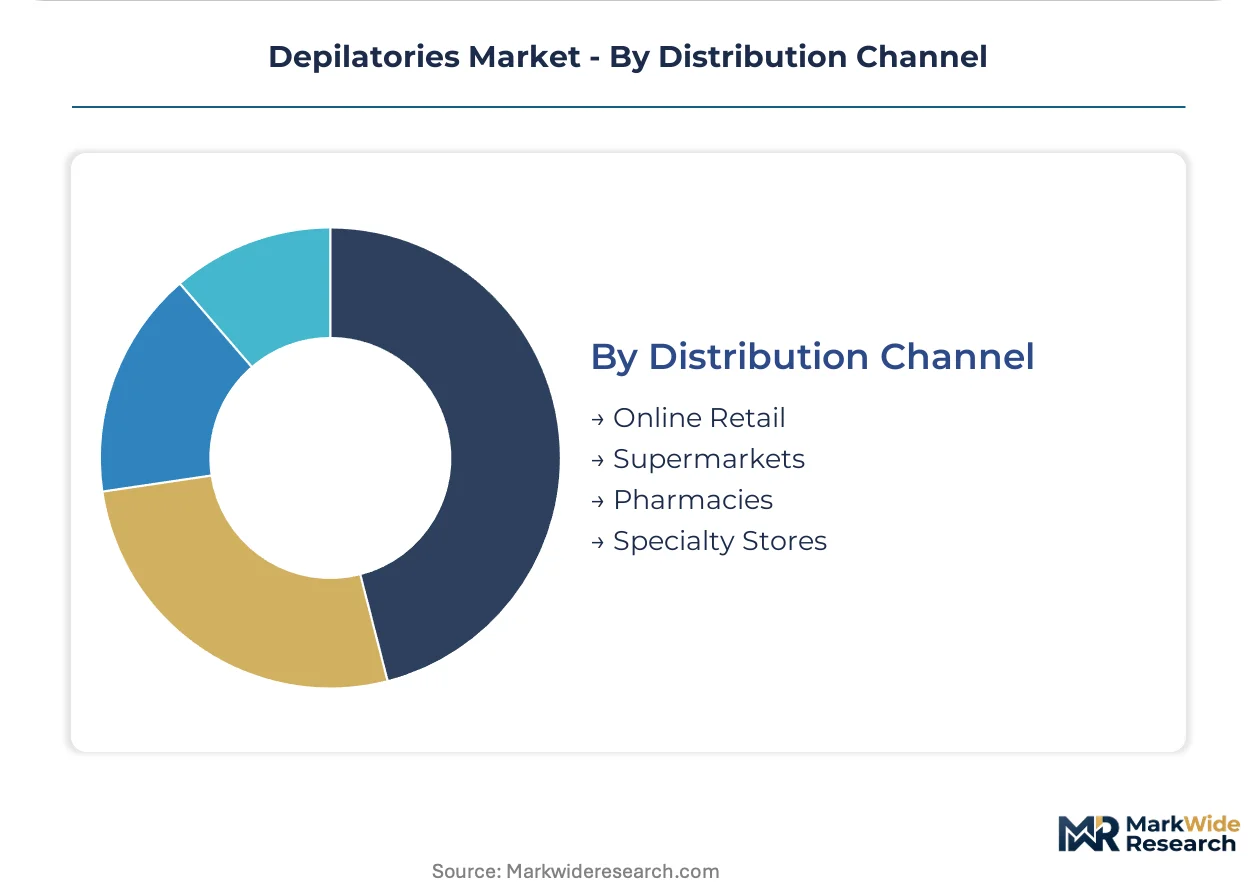
Online retail displaces first-time purchases in Indonesian and Thai urban markets, while supermarkets retain replenishment loyalty through impulse-placement economics in European and North American geographies.
- Online Retail:Direct-to-consumer subscription models capture replenishment loyalty through auto-ship algorithms. Platform algorithms concentrate buyer power, altering margin distribution.
- Supermarkets:Exclusive partnerships with North American mass retailers control distribution density for Edgewell Personal Care and comparable suppliers.
- Pharmacies:French dermocosmetic networks command premium shelf space through dermatological testing protocols.
- Specialty Stores:Professional salon supply channels in Brazil and Germany carry high-performance wax resin SKUs with concentrated supply risk.
Supermarkets maintain the established base. Online retail is expanding most quickly through subscription conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German professional-grade resin supply while Indonesian mass-market cream volumes compress margins. French pharmacy networks command premium shelf space through dermatological protocols. Brazilian aesthetic clinics in São Paulo drive service-menu expansion for wax and sugaring treatments.
United States
FDA cosmetic labeling requirements and EPA facility reporting obligations govern formulation disclosures and manufacturing standards. State-level ingredient bans in California and New York increasingly precede federal rulemaking on thioglycolate safety. Edgewell Personal Care controls distribution density through exclusive supermarket partnerships across North American mass retail channels.
Germany
REACH Annex XVII amendments mandate comprehensive safety data sheets for thioglycolate concentrations exceeding 2.5% in professional salon products. ECHA registration constraints compress SKU refresh rates to 12-18 month cycles. High-performance wax resin production clusters in Italian and German facilities, creating single-source vulnerability for North American salon chains.
Brazil
ANVISA regulates cosmetic ingredient thresholds while professional aesthetic clinics in São Paulo and Rio de Janeiro expand premium waxing and sugaring service menus. Salon service expansion lifts professional-grade resin demand through premium positioning. Brazilian consumers demonstrate strong loyalty to imported European wax formulations for sensitive-area applications.
Indonesia
Jakarta and Surabaya households transition from traditional threading to cream-based home-use depilatory products. Urban consumers auto-replenish through e-commerce platforms, bypassing pharmacy intermediaries and concentrating buyer power with platform algorithms. The country's national cosmetic regulator monitors thioglycolate concentration limits aligned with ASEAN harmonization efforts.
France
L'Oréal anchors premium positioning through dermatological testing protocols that command shelf space in French pharmacy networks. ANSM oversees cosmetic safety assessments while EU Green Deal biomass incentives accelerate sugar-based polymer development for biodegradable wax matrices. Paris-based formulation chemists face talent scarcity amid competing demand from dermocosmetic and fragrance sectors.
Depilatories Market Vendor Landscape
Concentration sits with mass-market chemical manufacturers and specialized professional-grade suppliers operating in parallel tiers. The vendor base separates into consolidated multinational personal care conglomerates controlling retail distribution density and fragmented regional specialists serving salon supply channels. Three archetypes dominate: alkaline cream mass producers, premium wax resin formulators, and natural botanical extract developers. Competitive moves center on exclusive retail partnerships and REACH-compliant formulation re-registration cycles.
Within the mass-market tier, Reckitt Benckiser Group and Church & Dwight occupy positions anchored by chemical R&D infrastructure and North American retail channel control. L'Oréal exemplifies the premium-tier archetype through dermatological testing protocols and French pharmacy network penetration. Edgewell Personal Care represents distribution-density specialists competing through supermarket exclusivity arrangements rather than formulation differentiation.
| Leading Market Players |
|---|
| Reckitt Benckiser Group |
| Church & Dwight |
| Procter & Gamble |
| Coty |
| L'Oréal |
| Edgewell Personal Care |
| American International Industries |
| Nad's Corporation |
| Jolen |
| Others |
Supply Flow & Price Mechanics
REACH Annex XVII compliance gates both European market access and professional-grade price premiums simultaneously, compressing thioglycolate-based formulations while rewarding compliant botanical alternatives with shelf space and margin expansion. Manufacturers face dual qualification hurdles: ECHA registration cycles and dermatological certification protocols that separate mass-market alkaline creams from pharmacy-tier positioning.
Pricing Analysis
The customization-premium spread separates standard supermarket SKUs from configured-to-order professional salon formulations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with French pharmacy networks commanding highest price realization through dermatological testing protocols. Price erosion runs through Indonesian mass-market cream segments as platform algorithms concentrate buyer power. Supermarket replenishment buyers exhibit lowest price sensitivity due to impulse-placement economics, while Vietnamese first-time purchasers online demonstrate highest elasticity.
Supply Chain Analysis
China and Germany anchor thioglycolate active production and high-performance wax resin manufacturing respectively. Sodium hydroxide and calcium thioglycolate feed from Chinese chlor-alkali capacity, while sugar-based polymer development centers on Italian and French facilities. Single-source vulnerability concentrates in German-Italian wax resin supply for North American salon chains. Distribution runs through supermarket exclusivity arrangements in North America and platform algorithms in Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Depilatories represent early-cycle expansion as Southeast Asian urban consumers abandon threading for cream-based home-use convenience, with Brazilian salon service menus simultaneously lifting professional-grade resin demand.
For Market Incumbents: Compound defensive positioning through exclusive supermarket partnerships that lock in replenishment loyalty against platform algorithm concentration. Accelerate REACH-compliant botanical R&D to capture pharmacy-tier premium migration as thioglycolate thresholds tighten. Vertical integration into sugar-based polymer feedstocks secures margin control against resin supply concentration. For New Entrants and Emerging Players: EU Green Deal certification fast-track offers white-space entry through biodegradable wax matrix development with R&D tax credit capture. Target Vietnamese underpenetration in professional wax SKUs for first-mover shelf space before imported salon brands establish presence. Direct-to-consumer subscription models bypass pharmacy intermediaries entirely. For Investors and Strategic Acquirers: REACH Annex XVII re-registration deadlines reshape the acquisition landscape toward compliant formulation assets with shortened due diligence windows. Five-to-ten year viability favors professional-grade suppliers with botanical substitution capabilities over mass-market alkaline exposure. Monitor Indonesian e-commerce platform concentration ratios as inflection indicator for margin distribution shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Botanical Formulation Repositioning | ECHA registration compliance opens pharmacy-tier shelf space in French and German networks. |
| Direct-to-Consumer Subscription Launch | Platform algorithms in Jakarta and Surabaya capture replenishment loyalty from supermarket impulse placement. |
| Professional Salon Supply Expansion | São Paulo and Rio de Janeiro aesthetic clinics lift resin demand through premium service menu additions. |
| Backward Integration into Sugar Polymers | EU Green Deal biomass incentives accelerate carbon-neutral wax matrix development in Italian facilities. |
| Southeast Asian E-Commerce Partnership | Vietnamese retail channel underpenetration offers first-mover advantage before European salon brands establish presence. |
Methodological Framework
Cross-validation between primary interviews with formulation chemists, salon supply distributors, and pharmacy category managers anchors the qualitative findings against secondary validation from ECHA registration databases, ANVISA cosmetic filings, and ASEAN harmonization protocols. Bottom-up demand modeling from Indonesian and Vietnamese urban household penetration rates triangulates with top-down value chain analysis across German resin supply and Chinese chlor-alkali capacity.
Sensitivity analysis frameworks test thioglycolate concentration threshold scenarios and platform algorithm concentration effects across the projection horizon. Segmentation dimensions span product type, application zone, formulation chemistry, and distribution channel with regional regulatory cluster overlays. CAGRs derive from penetration curve modeling against threading-to-cream transition velocities in Jakarta and Surabaya, with Brazilian salon service expansion rates and REACH re-registration cycle impacts as industry-specific inputs.
Underlying assumptions cover REACH Annex XVII amendment timelines and Indonesian e-commerce platform consolidation trajectories, with deviation risk concentrated in Chinese chlor-alkali capacity constraints and Vietnamese retail channel development velocity. Forecasts reflect these documented conditions with recalibration cycles aligning with material shifts in ECHA regulatory enforcement and Southeast Asian urban consumer behavior transitions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Germany Lip Care Products Market
Beauty & Personal Care
Lip and Cheek Tint Market
Beauty & Personal Care
Cosmetics Face Serum Market
Beauty & Personal Care
South America Hair Styling Products Market
Beauty & Personal Care
Hair Thickener Serum Market
Beauty & Personal Care
Facial Steamer Market
Beauty & Personal Care
Hair Removal Products Market
Beauty & Personal Care
Anti-Acne Cosmetics Market
Beauty & Personal Care
Liquid Soap Market
Beauty & Personal Care
Global Organic Personal Care Products Market
Beauty & Personal Care
China Eyelash Serum Market
Beauty & Personal Care
Lip Care Products Market
Beauty & Personal Care
Color Protection Shampoo Market
Beauty & Personal Care
Global Lash Extension Market
Beauty & Personal Care
Facial Oil Market
Beauty & Personal Care
Gua Sha Tools Market