
 Delivery Systems in Personal Care Market | 2026-2036
Delivery Systems in Personal Care Market Size, Share, and Industry Trends Forecast 2026-2036
Delivery Systems in Personal Care Market Analysis
Buyer concentration among multinational personal care brands is restructuring procurement dynamics across the delivery systems supply base. Evonik Industries AG leverages its peptide encapsulation expertise to serve premium skin care formulators. BASF SE anchors large-volume emulsion supply contracts with mass-market hair care manufacturers. Croda International Plc differentiates through lipid nanoparticle technology leadership in sun care applications.
Delivery systems in personal care encompass engineered carriers, vesicles, and structured matrices that stabilize actives, control release kinetics, and enhance skin penetration, typically formulated with phospholipids, surfactants, or polymeric wall materials at particle sizes below 500 nanometers for optimal bioavailability. Their commercial purpose centers on transforming ingredient efficacy into measurable consumer-perceivable benefits that justify price premiums. Emulsions dominate current volume flows due to established manufacturing infrastructure and broad compatibility with conventional filling lines. Skin care captures the deepest margin pools as brands allocate formulation budgets toward clinically positioned anti-aging and brightening platforms. Natural formulation demand is accelerating fastest, though synthetic carriers still control cost-sensitive segments in mass hair care and oral hygiene.
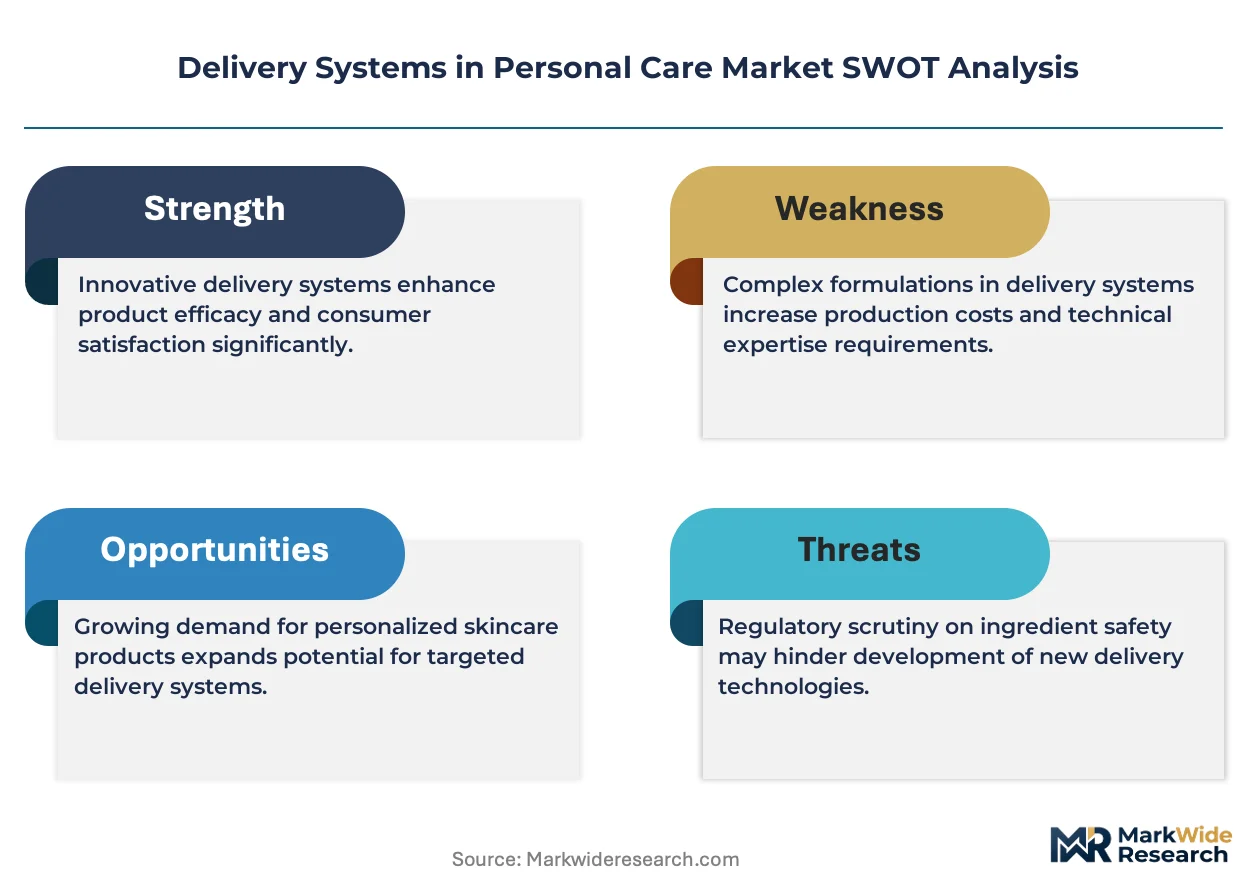
FDA oversees cosmetic ingredient safety through the Modernization of Cosmetics Regulation Act framework, while REACH mandates full nanomaterial registration and hazard communication across European supply chains. ECHA's evolving guidance on microplastic-free formulations is forcing reformulation of conventional encapsulation shells toward biodegradable alternatives. Stakeholders must monitor regulatory divergence between US and European nano-ingredient disclosure thresholds when designing platform technologies for cross-border brand portfolios.
Market Dynamics
Encapsulation technology maturation is concentrating procurement power among premium skin care brands that demand clinically validated bioavailability claims, forcing mid-tier suppliers to invest in peptide stabilization and controlled-release R&D or exit the category.
Growth Catalysts
- MoCRA framework implementation:FDA's Modernization of Cosmetics Regulation Act mandates ingredient safety substantiation, accelerating demand for third-party validated delivery platforms that demonstrate active stability and skin penetration kinetics.
- Liposome platform adoption:K-beauty manufacturers in South Korea are pioneering niosome and transfersome variants for high-efficacy brightening formulations, creating technology pull across Asian supply chains.
- Phospholipid feedstock expansion:Soy and sunflower lecithin processors are scaling pharmaceutical-grade refining capacity, reducing input cost volatility for vesicle-based carriers.
Market Restraints
- REACH nanomaterial registration burden:ECHA's full hazard communication requirements for sub-100nm particles impose documentation costs that disproportionately burden small and mid-sized European formulators.
- Ethanolamine surfactant supply concentration:Ethoxylated amine production clusters in the US Gulf Coast and northwestern Europe, exposing buyers to hurricane and energy price shocks.
- Silicone microemulsion substitution:Dimethicone copolyol alternatives offer comparable skin feel at lower formulation complexity, compressing margins for polymeric encapsulation specialists.
Strategic Opportunities
- Biodegradable shell materials:ECHA's evolving microplastic-free formulation guidance creates first-mover advantage for suppliers developing chitosan and alginate-based encapsulation matrices.
- Scalp care application expansion:Hair care brands are repurposing liposome technology from facial serums to scalp treatments, opening volume channels beyond traditional skin care.
- Direct-to-physician channel emergence:Medical aesthetic clinics are sourcing clinical-grade delivery systems directly, bypassing traditional distributor markups for post-procedure recovery formulations.
Industry Challenges
- Formulation chemist scarcity:The intersection of colloid science and cosmetic regulatory compliance requires specialized talent that outpaces current university pipeline output.
- Scale-up validation timelines:Translating lab-scale vesicle uniformity to manufacturing-line consistency demands 18-24 month validation cycles that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Delivery Systems in Personal Care Market |
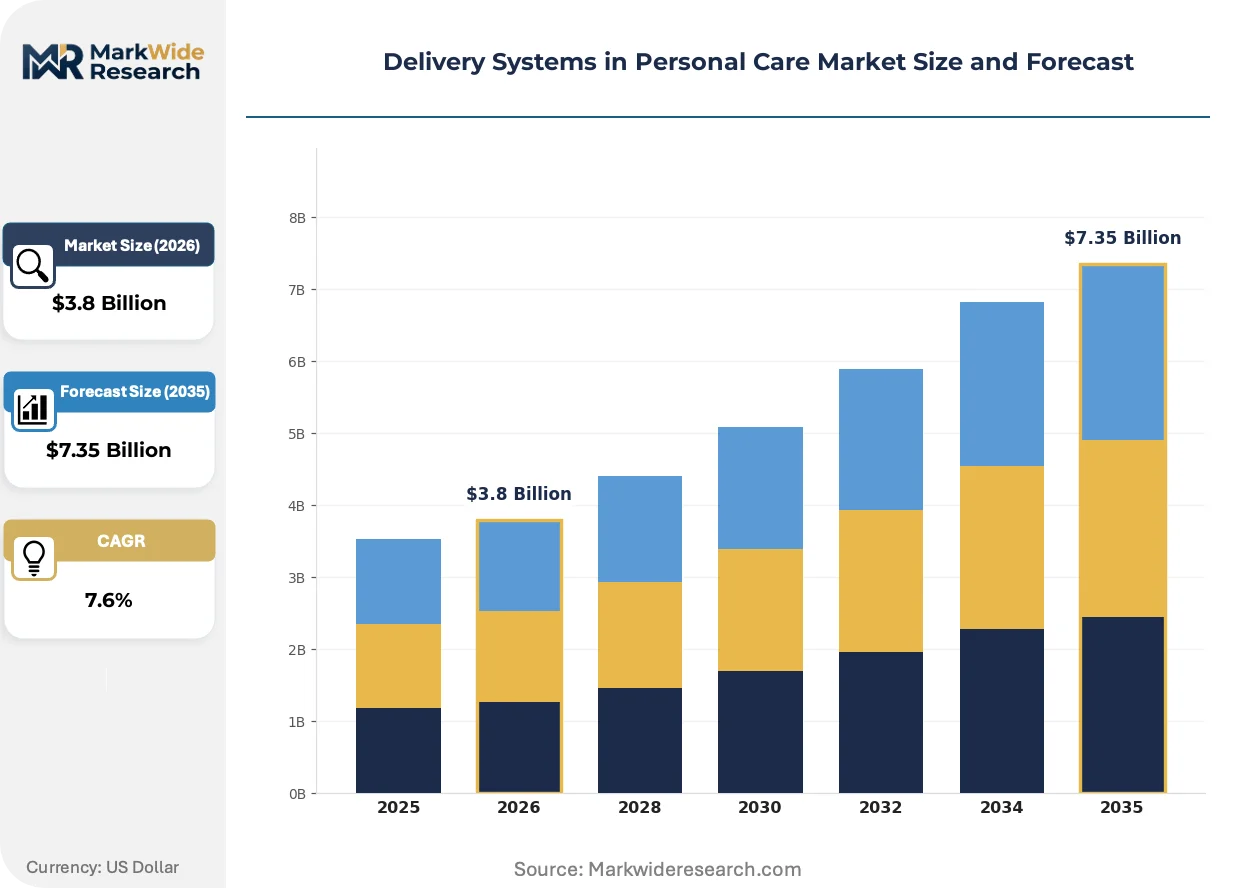
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsions, Gels, Sprays, Powders Application: Skin Care, Hair Care, Oral Hygiene, Fragrance Formulation: Natural, Organic, Synthetic, Vegan Packaging Type: Tubes, Bottles, Jars, Sachets |
| Companies Covered | Evonik Industries AG, BASF SE, Clariant AG, Croda International Plc, Lipotec S.A.U., Salvona Technologies Inc., Lonza Group Ltd., Ashland Global Holdings Inc., Lubrizol Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Delivery Systems in Personal Care Market Emerging Trajectories
Delivery system architectures are converging toward multifunctional platforms that simultaneously stabilize oxidation-sensitive actives, control release profiles, and enhance dermal penetration without compromising sensory aesthetics.
Hybrid lipid-polymer nanoparticles is unifying the structural integrity of polymeric shells with the biocompatibility of phospholipid bilayers. Premium anti-aging brands are adopting these platforms for retinol and vitamin C stabilization. This convergence is compressing the traditional segmentation between emulsion and vesicle technologies.
ECHA's microplastic-free formulation guidance is forcing reformulation of conventional encapsulation shells toward biodegradable alternatives. Suppliers are accelerating chitosan and pullulan-based matrix development. Sun care applications face the steepest compliance timelines due to water-resistance requirements.
Brand technical teams are consolidating supplier relationships around integrated platform providers that offer encapsulation, stability testing, and regulatory documentation as bundled services. Mass-market hair care manufacturers are displacing fragmented multi-vendor procurement. This concentration is most visible in Germany and France where technical service expectations are highest.
Delivery Systems in Personal Care Market Segmentation
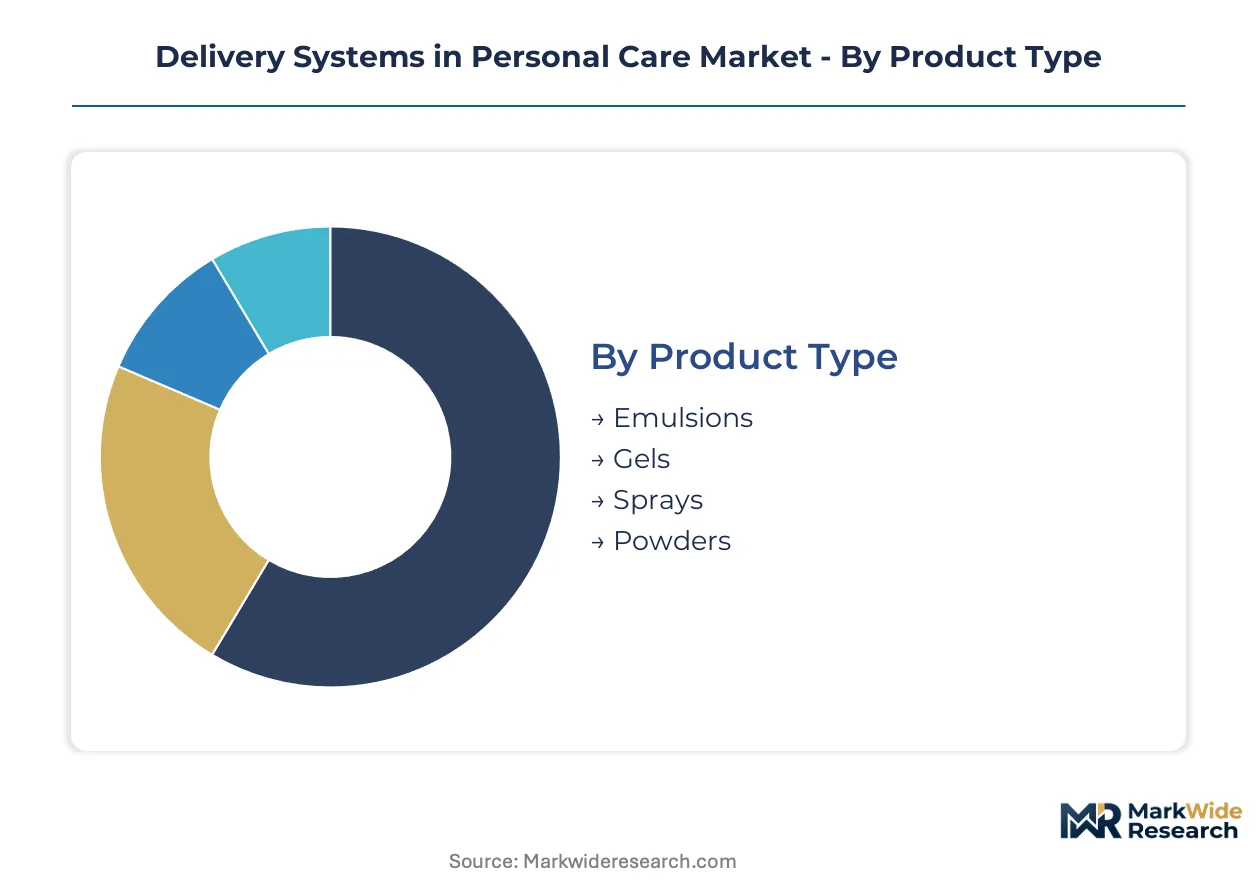
Delivery systems in personal care span multiple functional and commercial dimensions that determine manufacturing scale, margin structure, and regulatory pathway. Each segmentation axis reveals distinct procurement patterns and technology requirements that suppliers must address.
Product Type:
Emulsions dominate volume flows through established filling infrastructure, while premium positioning concentrates in alternative formats with specialized stability demands.
- Emulsions:Oil-in-water and water-in-oil matrices formulated with phospholipid or surfactant stabilizers at particle sizes below 500 nanometers. Mass-market hair care manufacturers in Germany and the United States anchor procurement volumes, though margin compression from silicone microemulsion substitutes constrains pricing power.
- Gels:Cross-linked polymeric networks or liquid crystal structures that suspend actives with tunable rheological profiles. K-beauty formulators in South Korea are pioneering gel-based liposome integration for brightening serums, pulling phospholipid feedstock demand toward pharmaceutical-grade specifications.
- Sprays:Aerosol and pump-dispersed microemulsions for even topical distribution.
- Powders:Encapsulated solid particles for anhydrous formulations and extended shelf stability.
Mature deployment sits with Emulsions across mass-market manufacturing lines. Newer deployment is concentrated in Gels as premium brands seek differentiated sensory profiles.
Application:
Margin pools vary sharply across end-use categories, with clinical positioning commanding formulation budgets that mass-market segments cannot support.
- Skin Care:Anti-aging and brightening platforms drive the deepest R&D investment, with retinol and vitamin C stabilization requiring hybrid lipid-polymer nanoparticles. Direct-to-physician channels for medical aesthetic recovery formulations are bypassing traditional distributors in France and Switzerland.
- Hair Care:Scalp care applications are repurposing facial liposome technology, opening volume expansion beyond traditional skin care boundaries. Ethanolamine surfactant supply concentration in the US Gulf Coast exposes formulators to hurricane disruption risk.
- Oral Hygiene:Controlled-release matrices for active ingredients in toothpastes and mouthwashes.
- Fragrance:Encapsulation systems for prolonged scent release and alcohol-free delivery.
Skin Care commands the steepest technology premiums. Hair Care is expanding most quickly as scalp treatments absorb transferred liposome expertise.
Formulation:
Regulatory pressure on microplastic content is bifurcating procurement between biodegradable shell investments and legacy synthetic maintenance.
- Natural:Chitosan, alginate, and pullulan-based encapsulation matrices developed in response to ECHA microplastic-free guidance. Sun care applications face accelerated compliance timelines due to water-resistance requirements that biodegradable shells must satisfy.
- Synthetic:Polymeric and silicone-derived carriers retain cost-sensitive segments in mass hair care and oral hygiene where ECHA registration burdens have not yet forced conversion.
- Organic:Certified feedstock chains with full agricultural input traceability.
- Vegan:Plant-derived phospholipid alternatives to animal-sourced lecithin.
Synthetic formulations retain scale advantages in cost-driven segments. Natural formulations are gaining share fastest under European regulatory pressure.
Packaging Type:
Primary packaging selection constrains delivery system viscosity, oxidation exposure, and dispensing precision requirements.
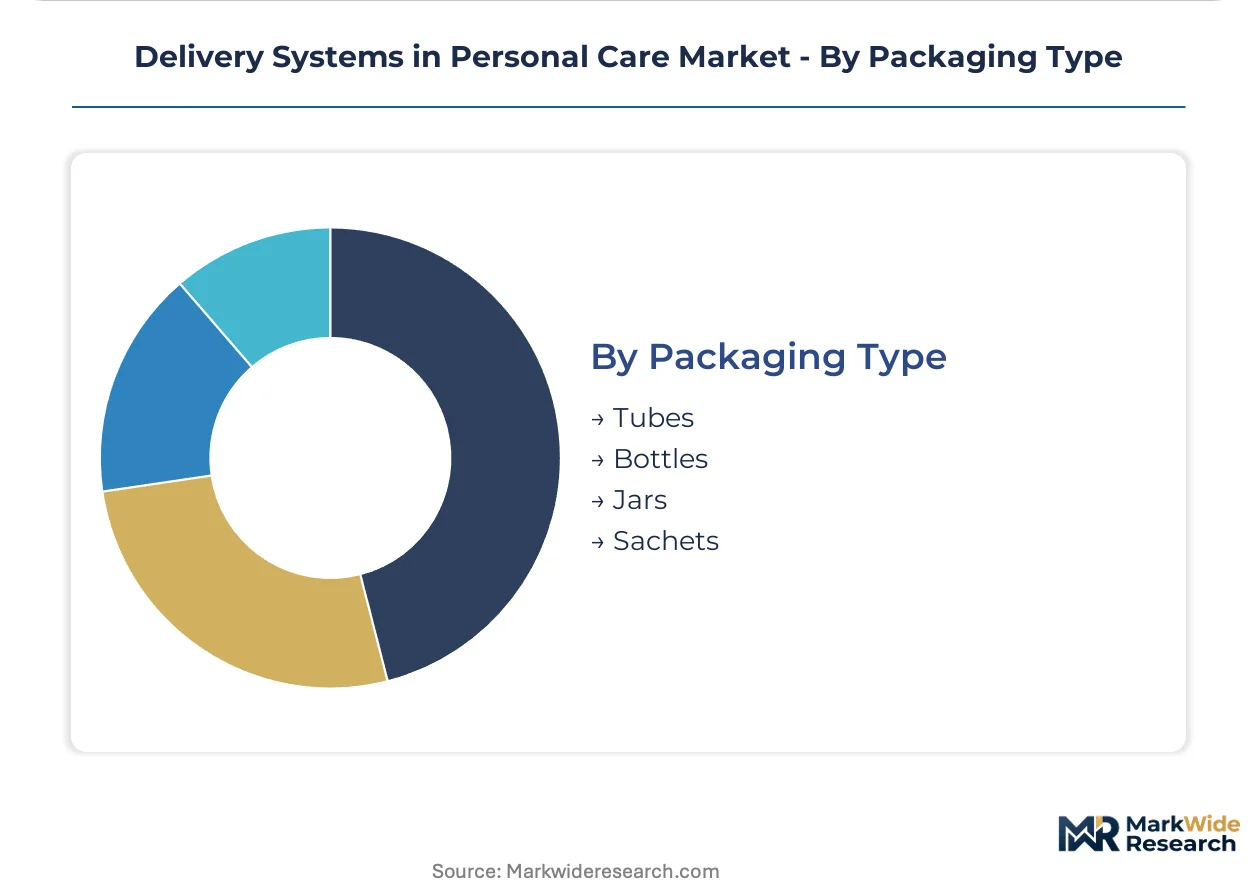
- Tubes:Laminate and mono-material structures for viscous emulsions and gels with high active loading.
- Bottles:Glass and polymer containers for liquid serums and spray formulations.
- Jars:Wide-mouth containers for anhydrous balms and powder-based products requiring scoop access.
- Sachets:Single-dose flexible packaging for travel formats and sampling programs with minimal preservative requirements.
Tubes and Bottles represent established filling infrastructure. Sachets are climbing the fastest as sampling economics and preservative reduction converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Soy and sunflower lecithin feedstock concentration in the US Midwest and Ukrainian Black Sea corridor anchors phospholipid supply chains for vesicle-based carriers. Procurement patterns track these agricultural inputs toward refining clusters in Germany, the Netherlands, and South Korea.
United States
Midwest phospholipid processors supply pharmaceutical-grade lecithin to domestic encapsulation specialists. FDA's MoCRA framework mandates ingredient safety substantiation that accelerates third-party validated delivery platform demand. New Jersey and California host technical service hubs where brands validate stability testing protocols.
Germany
Mass-market hair care manufacturers anchor emulsion procurement volumes through established filling infrastructure. ECHA's REACH nanomaterial registration requirements impose documentation burdens on sub-100nm particle formulations. North Rhine-Westphalia concentrates surfactant production clusters exposed to energy price volatility.
South Korea
K-beauty manufacturers pioneer niosome and transfersome variants for brightening formulations that pull phospholipid feedstock toward pharmaceutical-grade specifications. MFDS cosmetic safety standards align with export market requirements. Seoul Capital Area formulators transfer facial liposome expertise to emerging scalp care applications.
France
Medical aesthetic clinics in Paris and Lyon source clinical-grade delivery systems directly for post-procedure recovery formulations. ANSM oversees cosmetic ingredient safety alongside EU REACH compliance obligations. Île-de-France technical teams consolidate supplier relationships around integrated platform providers.
Switzerland
Swissmedic regulates clinical-grade carrier systems used in dermatological applications with precision documentation requirements. Zurich and Basel host precision formulation laboratories serving premium anti-aging brands. Direct-to-physician channels bypass traditional distributor markups for high-efficacy platforms.
Delivery Systems in Personal Care Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue biodegradable shell materials and medical aesthetic channels. The supplier base concentrates around integrated platform providers that bundle encapsulation, stability testing, and regulatory documentation. Three archetypes dominate: multinational chemical conglomerates with peptide expertise, lipid technology specialists, and regional service-focused formulators. Competitive moves center on capacity expansion for pharmaceutical-grade phospholipid refining and strategic partnerships with K-beauty manufacturers.
Within the multinational tier, Evonik Industries AG and BASF SE exemplify divergent scale strategies. Evonik's German corporate structure positions it within peptide encapsulation specialization. BASF SE anchors large-volume supply relationships through its European headquarters configuration. Croda International Plc occupies the lipid technology specialist position with UK-based corporate origins.
| Leading Market Players |
|---|
| Evonik Industries AG |
| BASF SE |
| Clariant AG |
| Croda International Plc |
| Lipotec S.A.U. |
| Salvona Technologies Inc. |
| Lonza Group Ltd. |
| Ashland Global Holdings Inc. |
| Lubrizol Corporation |
| Others |
Supply Flow & Price Mechanics
Colloid science specialists concentrated in Germany's North Rhine-Westphalia and New Jersey's technical corridors drive labor-cost differentials that widen pricing-tier spreads between premium clinical-grade platforms and commodity emulsion supply. Formulation chemist scarcity inflates compensation premiums for peptide stabilization expertise, compressing margins at mid-tier suppliers while reinforcing pricing power among integrated platform providers.
Pricing Analysis
Volume flows concentrate in mass-market emulsion supply at compressed margins, while premium skin care and medical aesthetic channels capture value through clinically validated bioavailability claims. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade liposome platforms from industrial emulsion contracts and silicone microemulsion substitutes. Pricing pressure stems from dimethicone copolyol alternatives offering comparable skin feel at lower formulation complexity. Mass-market hair care manufacturers exhibit highest price sensitivity, whereas direct-to-physician medical aesthetic clinics absorb premiums for post-procedure recovery formulations.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Hamburg, and Busan anchor hub-and-spoke patterns for phospholipid feedstock movement toward encapsulation specialists. Soy and sunflower lecithin processors in the US Midwest and Ukrainian Black Sea corridor draw from agricultural inputs refined in Germany, the Netherlands, and South Korea. Single-source vulnerability concentrates in ethoxylated amine production clusters along the US Gulf Coast and northwestern Europe. Distribution runs through integrated platform providers bundling encapsulation, stability testing, and regulatory documentation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Delivery systems suppliers are pursuing a vertical-integration race to secure pharmaceutical-grade phospholipid refining capacity and captive peptide stabilization capabilities that lock in margin capture.
For Market Incumbents: Cement peptide encapsulation expertise through backward integration into pharmaceutical-grade lecithin refining, particularly in South Korea where K-beauty manufacturers pull feedstock toward premium specifications. Expand technical service hubs in New Jersey and California to defend against emerging biodegradable shell specialists threatening conventional polymeric carrier margins. For New Entrants and Emerging Players: Launch via direct-to-physician channels in France and Switzerland where medical aesthetic clinics bypass traditional distributor markups for clinical-grade platforms. Target biodegradable chitosan and alginate matrix development for sun care applications facing accelerated ECHA microplastic-free compliance timelines. For Investors and Strategic Acquirers: Re-rating potential sits with lipid technology specialists given ECHA's evolving microplastic-free formulation guidance forcing reformulation of conventional encapsulation shells. Long-term viability favors suppliers with integrated regulatory documentation capabilities spanning REACH nanomaterial registration and FDA MoCRA compliance. Watch phospholipid feedstock cost volatility as the inflection indicator for margin compression at non-integrated formulators.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade Lecithin Refining Capacity Expansion | Captures margin from K-beauty manufacturers demanding premium phospholipid specifications for niosome platforms. |
| Biodegradable Shell Material R&D Partnership | Positions suppliers ahead of ECHA microplastic-free compliance deadlines in water-resistant sun care applications. |
| Direct-to-Physician Channel Development | Bypasses distributor markups in French and Swiss medical aesthetic clinics sourcing post-procedure recovery formulations. |
| Regulatory Documentation Service Bundling | Consolidates brand relationships around integrated REACH nanomaterial and FDA MoCRA compliance offerings. |
| Scalp Care Application Technology Transfer | Repurposes facial liposome expertise from Seoul Capital Area formulators into expanding hair care volume channels. |
Methodological Framework
Multi-period observation of phospholipid feedstock pricing, encapsulation technology patent filings, and regulatory guidance evolution anchored the trend analysis, supplemented by interviews with formulation chemists at premium skin care brands, procurement leads at mass-market hair care manufacturers, technical directors at phospholipid processors, and regulatory affairs specialists navigating REACH and FDA frameworks. Secondary validation drew from ECHA substance registration databases, FDA MoCRA implementation guidance, customs trade data for lecithin imports, and SEC filings of multinational chemical conglomerates. Bottom-up triangulation across end-use segment demand and top-down supply-side capacity assessment converged on market sizing.
The input-output matrix framed projections across product type, application, formulation, and packaging segmentation dimensions over the projection horizon. CAGRs derived from segment-level growth rate blending weighted by current revenue contribution. Industry-specific forecast inputs included K-beauty export volume trajectories and ECHA microplastic-free formulation compliance timeline assumptions.
Regulatory divergence between US and European nano-ingredient disclosure thresholds, phospholipid feedstock supply disruption from agricultural yield volatility, and substitution acceleration toward silicone microemulsion alternatives are the dominant revision risks. Forecasts reflect documented assumptions subject to these vectors. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
North America Hair Removal Wax Market
Beauty & Personal Care
Hair Removal Creams for Private Parts Market
Beauty & Personal Care
False Eyelashes Market
Beauty & Personal Care
Europe Beauty and Personal Care Products Market
Beauty & Personal Care
Global Bath Salts Market
Beauty & Personal Care
India Cosmetics Products Market
Beauty & Personal Care
Europe Hair and Skincare Market
Beauty & Personal Care
Facial Oil Market
Beauty & Personal Care
Spain Sustainable Personal Care Market
Beauty & Personal Care
Anti-Aging Beauty Device Market
Beauty & Personal Care
Organic Personal Care Market
Beauty & Personal Care
Bath Oil Market
Beauty & Personal Care
US Sustainable Personal Care Market
Beauty & Personal Care
DIY Face Mask Machine Market
Beauty & Personal Care
Europe Professional Beauty Services Market
Beauty & Personal Care
Colombia Hair Care Market