
 Global Fresh Berries Market | 2026-2036
Global Fresh Berries Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fresh Berries Market Analysis
Controlled-environment agriculture is fragmenting traditional open-field berry production as hydroponic and greenhouse systems spread across temperate and semi-arid zones. Driscoll's leverages proprietary genetics programs to sustain premium pricing in branded strawberry and raspberry lines. Hortifrut anchors South American supply through vertically integrated farm networks stretching from Chile to Peru. California Giant Berry Farms competes on scale via cooperative packing infrastructure serving Western US retail channels.
Fresh berries comprise the edible, uncooked fruit of vascular plants in the botanical berry category and accessory fruit types, harvested at physiological maturity with soluble solids typically exceeding eight percent and maintained under cold chain conditions between zero and four degrees Celsius to preserve shelf life and phytochemical integrity; their primary commercial purpose is direct human consumption as whole fruit or ingredient inputs across retail, food service, and processing industries. Strawberries occupy the dominant value position within product type segmentation due to year-round greenhouse availability and universal retail placement. Blueberries lead growth velocity as functional food positioning drives household penetration in Asia-Pacific markets. Clamshell packaging dominates the margin pool by reducing mechanical damage and extending retail display life relative to punnets or bulk boxes.
FDA food safety modernization rules and EPA pesticide residue thresholds shape US import acceptance criteria for fresh berry shipments, while EU REACH and MDR-adjacent phytosanitary protocols govern European market access for non-member state suppliers. China's SAMR and GB standards for maximum residue limits create additional compliance layers for exporters targeting domestic retail channels. Stakeholders must monitor divergence between regional chemical tolerance standards and accelerated breeding timelines for low-spray cultivars.
Market Dynamics
Controlled-environment agriculture is fragmenting traditional open-field berry production as hydroponic and greenhouse systems spread across temperate and semi-arid zones, while EU Green Deal mandates redirect capital toward lower-chemical cultivation protocols.
Growth Catalysts
- EU Green Deal sustainable agriculture mandates:Farm investment is redirecting toward lower-chemical cultivation protocols across member states, creating compliant supply for premium retail channels.
- Food service sector expansion:Operators are adding antioxidant-rich berry ingredients to menus, pulling volume from traditional retail into commercial kitchens and hospitality.
- Mexico year-round production capacity:North American supply concentration is expanding as protected agriculture investments in Baja California and Jalisco enable continuous harvest cycles.
Market Restraints
- Labor cost volatility:Hand-harvesting requirements for delicate berries expose producers to wage inflation in California, Spain, and Morocco sourcing regions.
- Input cost concentration:Substrate, nutrient, and energy inputs for controlled-environment systems cluster supplier power with Dutch and Israeli equipment providers.
- Pesticide residue threshold divergence:EPA, EU REACH, and China SAMR maintain incompatible maximum residue limits, forcing parallel compliance tracks for exporters.
Strategic Opportunities
- India domestic retail penetration:FSSAI standards alignment and cold chain infrastructure buildout create first-mover positioning in underdeveloped fresh berry consumption.
- Functional food positioning in Asia-Pacific:Blueberry antioxidant marketing is driving household penetration in South Korea and Japan health-conscious demographics.
- Clamshell packaging innovation:Modified atmosphere technologies are extending retail display life and reducing mechanical damage premiums in premium channels.
Industry Challenges
- Accelerated breeding timeline compression:Low-spray cultivar development must outpace regulatory tightening across FDA, EFSA, and SAMR jurisdictions simultaneously.
- Cold chain integrity maintenance:Zero-to-four-degree Celsius requirements through last-mile distribution demand capital-intensive reefer infrastructure in emerging markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fresh Berries Market |
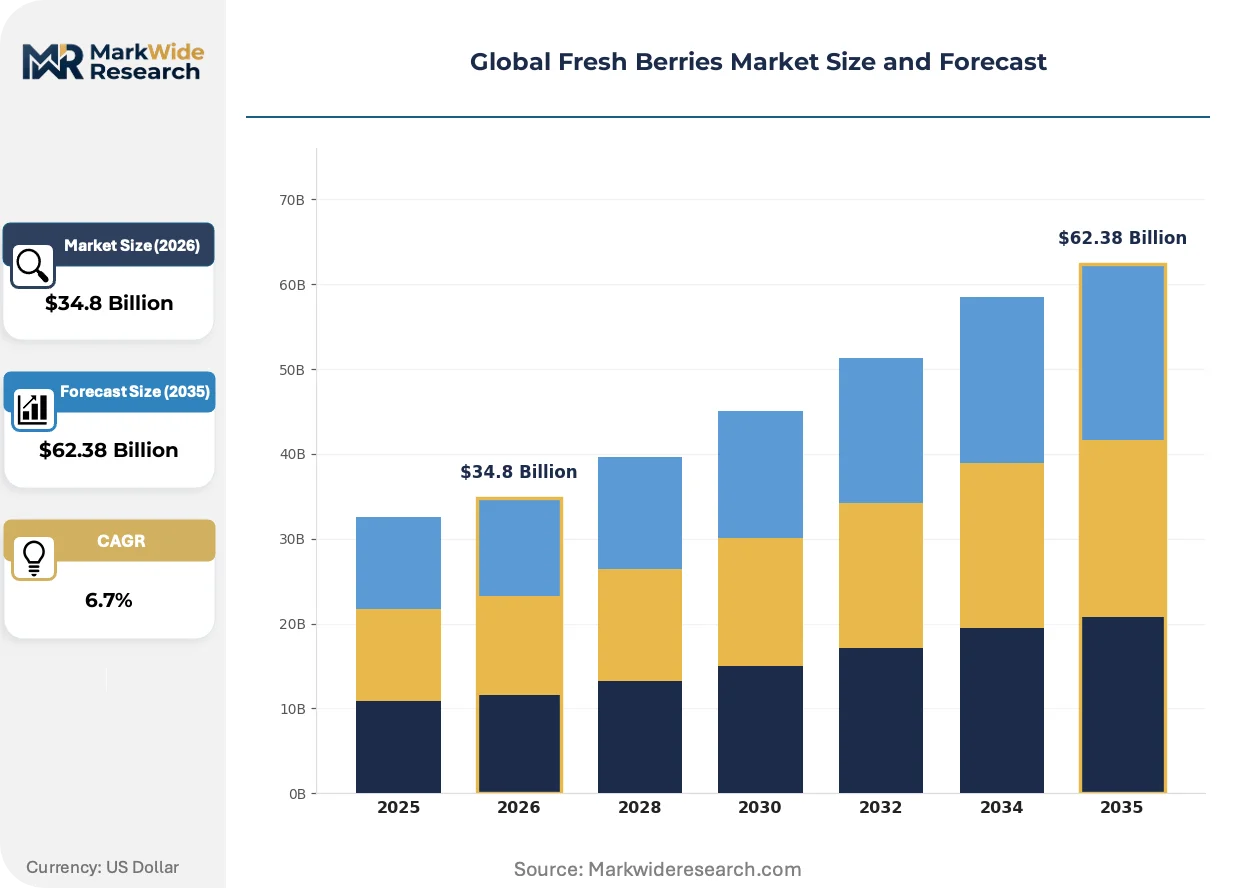
| Market Size in 2026 | $34.8 Billion |
| Market Size in 2035 | $62.38 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blueberries, Strawberries, Raspberries, Blackberries Distribution Channel: Supermarkets, Online Retailers, Farmers Markets, Wholesalers Packaging Type: Plastic Containers, Boxes, Punnets, Clamshells End User: Households, Food Service, Retailers, Processors |
| Companies Covered | Hortifrut, San Lucar, Driscoll's, Tout Berry Farms, Mirak Group, Naturipe, Ocean Spray Cranberry Inc, Frutas Borja, California Giant Berry Farms, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fresh Berries Market Emerging Trajectories
Fresh berry production is undergoing systematic transformation through environmental control technologies, regulatory chemistry restrictions, and shifting procurement relationships between growers and retail consolidators.
Sensor networks and climate automation systems are digitizing greenhouse operations across Iberian and Mexican production zones. Large-scale berry marketers are deploying these systems to compress variation in sugar content and shelf-life metrics. The technology is digitizing quality assurance workflows that previously required manual sampling protocols.
EU REACH phytosanitary protocols and MDR-adjacent residue standards are tightening import acceptance criteria for non-member state suppliers. Exporters must now maintain parallel certification tracks for European and North American destinations. Latin American growers targeting EU retail channels are investing most heavily in compliance infrastructure.
Retail procurement consolidation is compressing supplier relationships toward direct grower contracts and away from wholesale intermediaries. German and Dutch supermarket chains are leading this shift through volume commitments tied to exclusive varietal access. The pattern is most visible in strawberry and raspberry categories where branded genetics create differentiation.
Global Fresh Berries Market Segmentation
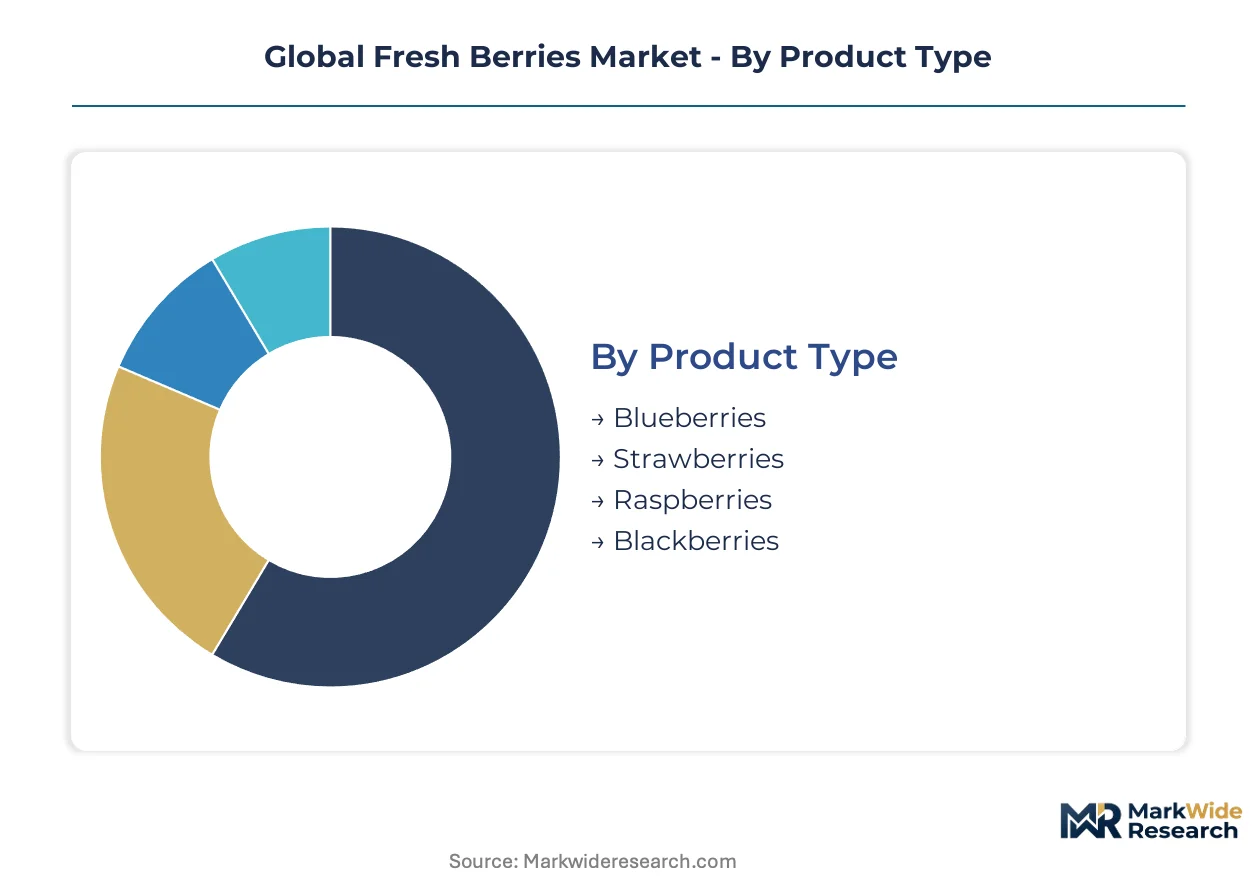
Fresh berry segmentation reveals how supply chain configuration, consumption context, and preservation requirements create distinct margin pools. Each dimension shapes procurement relationships, pricing power, and investment priorities differently across the value chain.
Product Type:
Volume concentration and growth velocity diverge sharply across botanical categories, with year-round availability and functional positioning driving divergent commercial strategies.
- Strawberries:Greenhouse production systems deliver continuous harvest cycles, securing universal retail placement and stable procurement contracts. Mexico and Spain dominate protected agriculture supply for North American and European retail channels respectively, with varietal breeding programs targeting brix consistency and shelf-life extension.
- Blueberries:Functional food marketing emphasizing anthocyanin content accelerates household penetration in South Korea and Japan. Chile and Peru anchor Southern Hemisphere counter-seasonal supply, while Pacific Northwest growers in Oregon and Washington maintain summer dominance.
- Raspberries:Delicate texture limits mechanical harvesting adoption, concentrating production in Mexico's protected agriculture zones and Morocco's Souss-Massa region for European export.
- Blackberries:Niche positioning in premium retail and food service channels sustains smaller cultivation footprints across California's Central Valley and Mexican highland operations.
Strawberries command the established base. The steepest expansion runs through blueberries.
Distribution Channel:
Channel selection determines cold chain intensity, margin capture, and buyer concentration, with retail consolidation reshaping power dynamics across each pathway.
- Supermarkets:German and Dutch chains drive direct grower contracting, eliminating wholesale intermediaries through volume commitments tied to exclusive varietal access. Private label penetration concentrates procurement with fewer, larger suppliers capable of year-round consistency.
- Online Retailers:Last-mile cold chain requirements in India and Southeast Asia strain infrastructure, creating first-mover advantages for platforms investing in reefer networks and predictive demand algorithms.
- Farmers Markets:Local provenance premiums sustain direct-to-consumer pricing in California, France, and Italy, though scale limitations restrict participation to smallholder cooperatives.
- Wholesalers:Consolidating food service demand in the United States and Spain maintains intermediary relevance for restaurant and hospitality procurement, particularly for processors seeking volume flexibility.
Supermarkets anchor volume flows. Online channels are climbing the fastest.
Packaging Type:
Preservation technology and mechanical protection requirements create tiered margin structures, with innovation concentration in premium retail-facing formats.
- Clamshells:Modified atmosphere technologies extend retail display life while reducing mechanical damage premiums. Dutch equipment providers dominate sealing machinery supply, creating input cost concentration for growers scaling protected agriculture.
- Plastic Containers:Standardized formats serve bulk retail and food service channels where turnover velocity minimizes shelf-life risk, particularly in Mexican and Spanish supermarket supply.
- Punnets:Traditional cardboard-based formats retain cost advantages for local distribution in France and Italy, though moisture sensitivity limits export applicability.
- Boxes:Bulk formats concentrate in processor and wholesale channels across the United States and Germany, optimizing logistics efficiency over presentation quality.
Clamshells capture premium positioning. Modified atmosphere variants are gaining share fastest.
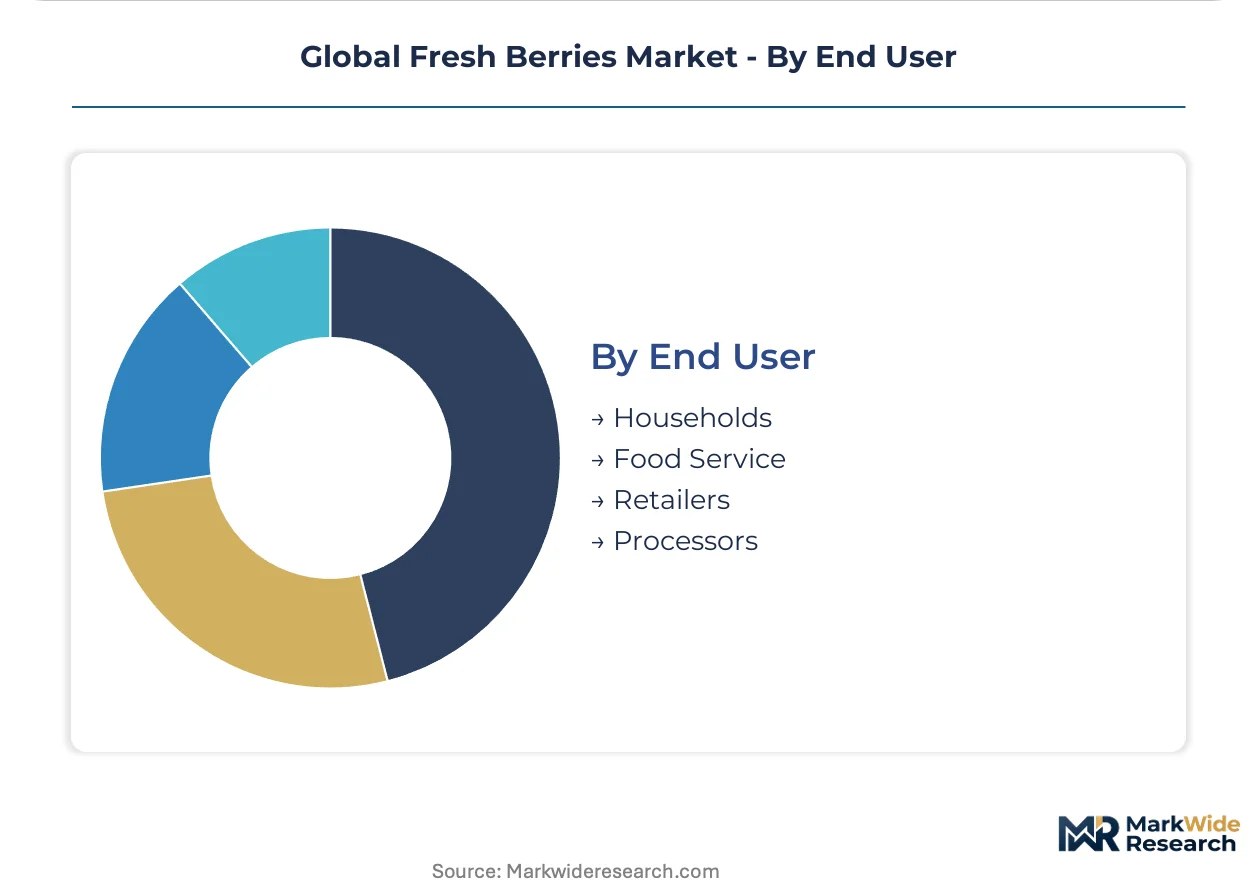
End User:
Consumption context shapes quality specifications, volume predictability, and price sensitivity, with food service emergence redirecting supply relationships.
- Households:Snack-format consumption drives clamshell preference in Japan and South Korea, while European buyers prioritize organic certification and local provenance claims.
- Food Service:Restaurant and hospitality operators in the United States and United Kingdom are expanding antioxidant-rich menu applications, pulling volume from traditional retail into commercial kitchens with differentiated specification requirements.
- Retailers:Direct grower contracting by German, Dutch, and US supermarket chains compresses wholesale margins while securing varietal exclusivity in strawberry and raspberry categories.
- Processors:IQF and puree demand from California and Florida operations sustains bulk procurement for ingredient manufacturing, with brix specifications diverging from fresh-market standards.
Households maintain volume dominance. Food service is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supermarket procurement consolidation in Germany and the United States is concentrating supplier relationships around direct grower contracts. Year-round protected agriculture investments in Mexico and Spain are reshaping seasonal supply patterns. Cold chain infrastructure gaps in India and Southeast Asia create first-mover advantages for platforms investing in reefer networks.
United States
Food service operators in California and New York are expanding antioxidant-rich berry applications across commercial kitchens. FDA food safety modernization rules shape import acceptance criteria for Mexican and Chilean shipments. The Pacific Northwest cluster in Oregon and Washington anchors summer blueberry supply for domestic retail channels.
Germany
Retail consolidation at Aldi and Lidl is eliminating wholesale intermediaries through volume commitments tied to exclusive varietal access. EU REACH phytosanitary protocols govern import acceptance for non-member state suppliers. The Lower Saxony greenhouse corridor is digitizing operations through Dutch-supplied climate automation systems.
Mexico
Protected agriculture investments in Baja California and Jalisco enable continuous strawberry and raspberry harvest cycles for North American export. SADER and SENASICA phytosanitary standards align with EPA pesticide residue thresholds for US market access. The Bajío region is attracting Dutch equipment providers for substrate-based blueberry cultivation.
China
SAMR and GB standards for maximum residue limits create compliance layers for exporters targeting domestic retail channels. Dual carbon goals are redirecting farm investment toward lower-energy greenhouse protocols. The Shandong Peninsula cluster is expanding controlled-environment strawberry production for premium urban markets.
India
FSSAI standards alignment and cold chain infrastructure buildout create first-mover positioning in underdeveloped fresh berry consumption. Import duty structures on planting material constrain varietal diversification for domestic growers. The Maharashtra-Pune corridor is piloting clamshell packaging lines for supermarket retail penetration.
Global Fresh Berries Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Large-scale berry marketers leverage proprietary genetics and direct retail contracts to secure premium placement, while cooperative structures compete on volume throughput. Three archetypes dominate: vertically integrated genetics-to-shelf operators, cooperative packing networks, and regional protected-agriculture specialists. Capacity expansion in Mexican protected agriculture and strategic partnerships for cold chain access represent the dominant competitive moves.
Within the genetics-driven tier, Driscoll's and Hortifrut exemplify contrasting approaches to market positioning. Driscoll's occupies a position anchored in proprietary breeding programs and branded retail presence across North American and European channels. Hortifrut represents the South American vertically integrated model, with operations stretching from Chile to Peru. California Giant Berry Farms sits within the cooperative-scale archetype, competing through packing infrastructure serving Western US retail channels.
| Leading Market Players |
|---|
| Hortifrut |
| San Lucar |
| Driscoll's |
| Tout Berry Farms |
| Mirak Group |
| Naturipe |
| Ocean Spray Cranberry Inc |
| Frutas Borja |
| California Giant Berry Farms |
| Others |
Supply Flow & Price Mechanics
Reefer corridor costs between Baja California and Los Angeles distribution centers compress margin pools for Mexican strawberry exporters while amplifying price spreads between clamshell-packaged premium tiers and bulk food service deliveries. Dutch equipment providers extract rent from climate automation hardware, concentrating supplier power and forcing downstream price differentiation between integrated greenhouse operators and open-field growers.
Pricing Analysis
Cost-plus contracts with Dutch equipment providers indexed to euro-denominated input baskets dominate protected agriculture financing arrangements. Pricing stratifies across premium branded genetics, standard certified organic, and economy conventional tiers based on residue testing compliance and shelf-life metrics. Cost compression in the economy tier intensifies because Moroccan and Mexican open-field growers compete on wage arbitrage. Food service buyers exhibit highest price sensitivity due to volume procurement and specification flexibility, while Japanese retail channels show lowest sensitivity tied to anthocyanin content marketing and gift-format packaging.
Supply Chain Analysis
Tariff exposure between Mexico and the United States under USMCA rules dominates supply chain risk calculations for North American berry marketers. Geographic supply concentrates in Mexico, Spain, and Morocco for strawberry and raspberry categories, with Chile and Peru anchoring Southern Hemisphere blueberry counter-seasonal flows. Raw material dependencies center on Dutch substrate formulations, Israeli drip irrigation components, and proprietary nutrient blends. Distribution runs through direct retail contracts eliminating wholesale intermediaries in Germany and the United States, while reefer-dependent last-mile networks strain infrastructure in India and Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from frozen and processed berry formats capturing food service volume as operators prioritize cost stability over fresh provenance claims. Defense requires entrenching varietal exclusivity and cold chain control.
For Market Incumbents: Entrench proprietary genetics programs through exclusive retail contracts with German and Dutch supermarket chains, locking out competitor access to premium shelf placement. Deepen backward integration into Mexican protected agriculture zones to capture year-round harvest cycles and reduce exposure to California labor cost volatility. Prioritize low-spray cultivar R&D acceleration to outpace EPA and EU REACH residue threshold tightening.
For New Entrants and Emerging Players: Establish a beachhead in India's domestic retail channel by aligning with FSSAI standards and investing in clamshell packaging infrastructure ahead of cold chain maturation. Target Maharashtra-Pune corridor supermarket penetration as the most penetrable geography given underdeveloped incumbent presence. Deploy modified atmosphere packaging technology as a differentiated go-to-market angle to extend retail display life and reduce mechanical damage premiums.
For Investors and Strategic Acquirers: Carve-out targets emerge from cooperative packing networks seeking capital for climate automation upgrades and direct retail contract expansion. Long-term viability hinges on controlled-environment agriculture scale advantages and proprietary genetics access. Monitor divergence between EU REACH and EPA residue thresholds as the critical inflection signal—widening gaps favor low-spray cultivar specialists while convergence benefits commodity-scale operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Genetics Licensing | Driscoll's branded strawberry lines command retail premium through exclusive varietal access. |
| Protected Agriculture Expansion | Mexico's Baja California greenhouse clusters enable continuous harvest cycles for North American supply. |
| Modified Atmosphere Packaging Deployment | Dutch sealing machinery extends retail display life and reduces mechanical damage premiums. |
| Direct Retail Contracting | German Aldi and Lidl volume commitments eliminate wholesale intermediaries and secure shelf placement. |
| Cold Chain Infrastructure Buildout | India's reefer network investments create first-mover positioning in underdeveloped domestic consumption. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, EU phytosanitary certification records, and supermarket procurement disclosures. Primary interviews engaged greenhouse operations managers, retail category buyers, cold chain logistics providers, and regulatory compliance officers across Mexico, Spain, Morocco, and the United States. Secondary validation drew from SADER and SENASICA export filings, FDA import refusal data, and Dutch equipment provider order backlogs. Bottom-up cultivation area estimates and top-down retail value flows were triangulated to anchor volume and price assumptions.
Forecast inputs incorporate protected agriculture investment pipelines, varietal breeding timelines, and regulatory threshold divergence trajectories across the projection horizon. Segmentation modeling spans product type, distribution channel, packaging format, and end-use consumption context with regional production cluster overlays. CAGRs derive from historical volume elasticity against income growth in Asia-Pacific markets and food service penetration rates in North America and Europe. Climate automation adoption curves and residue standard tightening schedules feed scenario-weighted outputs.
Sensitivities concentrate around labor cost volatility in California and Morocco, euro-dollar exchange rate swings affecting Dutch equipment pricing, and abrupt phytosanitary barrier implementation by China SAMR or India FSSAI. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Saudi Arabia Fruit Concentrate Market
Fruits and Vegetables
Boysenberry Market
Fruits and Vegetables
IQF Fruits and Vegetables Market
Fruits and Vegetables
Global Hass Avocado Market
Fruits and Vegetables
Organic Bananas Market
Fruits and Vegetables
Aegle Marmelos Market
Fruits and Vegetables
North America Organic Fruits Market
Fruits and Vegetables
Europe Stone Fruits Market
Fruits and Vegetables
Mango Puree Market
Fruits and Vegetables
Fruit and Vegetable Pulp Market
Fruits and Vegetables
North Africa Fruits and Vegetables Processing Market
Fruits and Vegetables
Starchy Roots Market
Fruits and Vegetables
Lemon Juice Concentrate Market
Fruits and Vegetables
Pineapple Market
Fruits and Vegetables
Global Pickle Market
Fruits and Vegetables
Fruit and Vegetable Pieces and Powders Market