
 Asia-Pacific Cosmeceutical Market | 2026-2036
Asia-Pacific Cosmeceutical Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Cosmeceutical Market Outlook
Younger male consumers is reorganizing demand patterns across the Asia-Pacific cosmeceutical landscape, pulling brands away from legacy anti-aging positioning toward preventive and gender-neutral skincare. Shiseido Group leverages its century-long R&D heritage in Tokyo to sustain premium pricing across multiple Asian markets. Amorepacific Corporation anchors its competitive stance through Seoul-based innovation labs that specialize in fermented botanical actives. Kao Corporation dominates the Japanese mass-market tier with manufacturing scale that controls regional supply chains for ceramide-based formulations.
Cosmeceuticals occupy the regulatory intersection between cosmetics and pharmaceuticals, combining biologically active ingredients such as retinoids, peptides, hydroxy acids, and niacinamide at concentrations sufficient to deliver measurable dermatological effects without requiring full drug approval. Skin care commands the largest revenue pool within product type segmentation, though serums within formulation categories are capturing disproportionate margin expansion due to higher active-ingredient loading and premium positioning. Online retail channels are displacing traditional drugstore dominance fastest in China and Southeast Asia, while specialty stores sustain higher conversion rates for premium lines in Japan and South Korea.
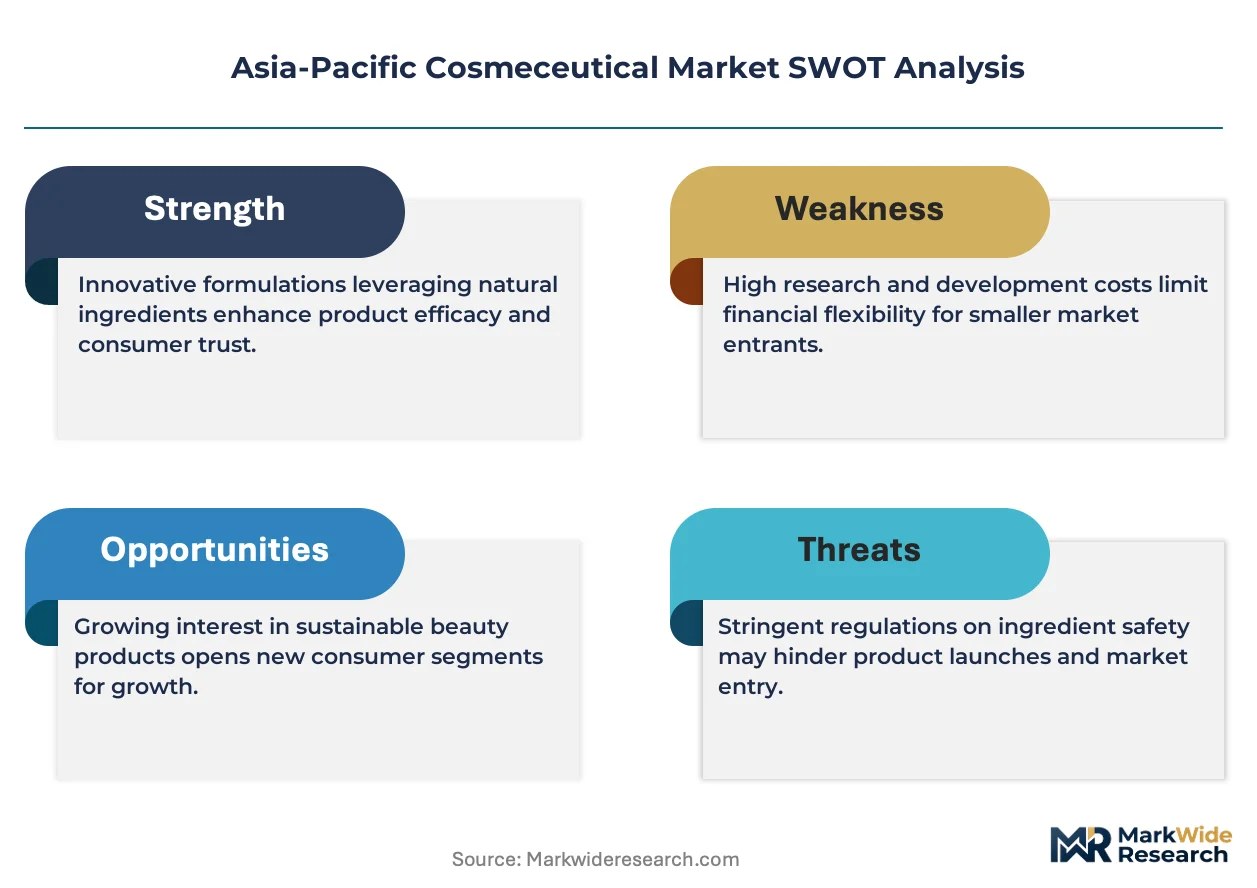
Japan's MHLW quasi-drug framework and South Korea's MFDS functional cosmetics designation create divergent compliance pathways that shape regional product development timelines and market access costs. China's NMPA cosmetic registration requirements for imported cosmeceuticals impose additional testing protocols that delay entry for brands lacking local manufacturing partnerships. Stakeholders must monitor evolving cross-border e-commerce regulations and ingredient ban lists, as these policy instruments increasingly determine which formulations can circulate profitably across Asia-Pacific's fragmented compliance environment.
Market Dynamics
The Asia-Pacific cosmeceutical sector is restructuring around divergent national compliance pathways, where Japan's MHLW quasi-drug standards and South Korea's MFDS functional cosmetics designations impose incompatible testing protocols that fragment regional product development.
Growth Catalysts
- K-beauty innovation clusters:Seoul-Incheon corridor R&D facilities are accelerating fermented botanical active development and cross-border licensing to Southeast Asian markets.
- MHLW quasi-drug framework:Japan's concentration limits on retinoids and hydroxy acids create predictable efficacy thresholds that premium brands leverage for clinical credibility.
- Dermatology clinic expansion:Medical spas across Thailand, Singapore, and Vietnam are professionalizing skincare protocols and pulling pharmaceutical-grade formulations into outpatient settings.
Market Restraints
- Ceramide supply concentration:Japanese mass-market manufacturers control regional feedstock for barrier-repair formulations, constraining independent brand cost structures.
- NMPA registration timelines:China's cosmetic registration requirements for imported cosmeceuticals impose extended animal-alternative testing protocols that delay market entry by 18-24 months.
- Active ingredient volatility:Peptide synthesis capacity concentrates in South Korean and Japanese contract manufacturers, exposing mid-tier brands to input price swings.
Strategic Opportunities
- Vietnam and Indonesia penetration:Underdeveloped professional skincare channels in Ho Chi Minh City and Jakarta offer first-mover positioning before domestic quasi-drug frameworks mature.
- Cross-border e-commerce regulatory arbitrage:China's evolving cross-border e-commerce pilot zones create temporary compliance windows for brands lacking local manufacturing partnerships.
- Biotechnology-convergence:CRISPR-derived peptide engineering and AI-formulation screening are collapsing development cycles for personalized cosmeceutical lines.
Industry Challenges
- Formulation chemist scarcity:Asia-Pacific universities produce insufficient graduates trained at the cosmetics-pharmaceutical interface, forcing brands to recruit from European contract research organizations.
- Dual-registration complexity:Brands seeking simultaneous Japan and China market access must maintain parallel stability studies under incompatible MHLW and NMPA protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Cosmeceutical Market |
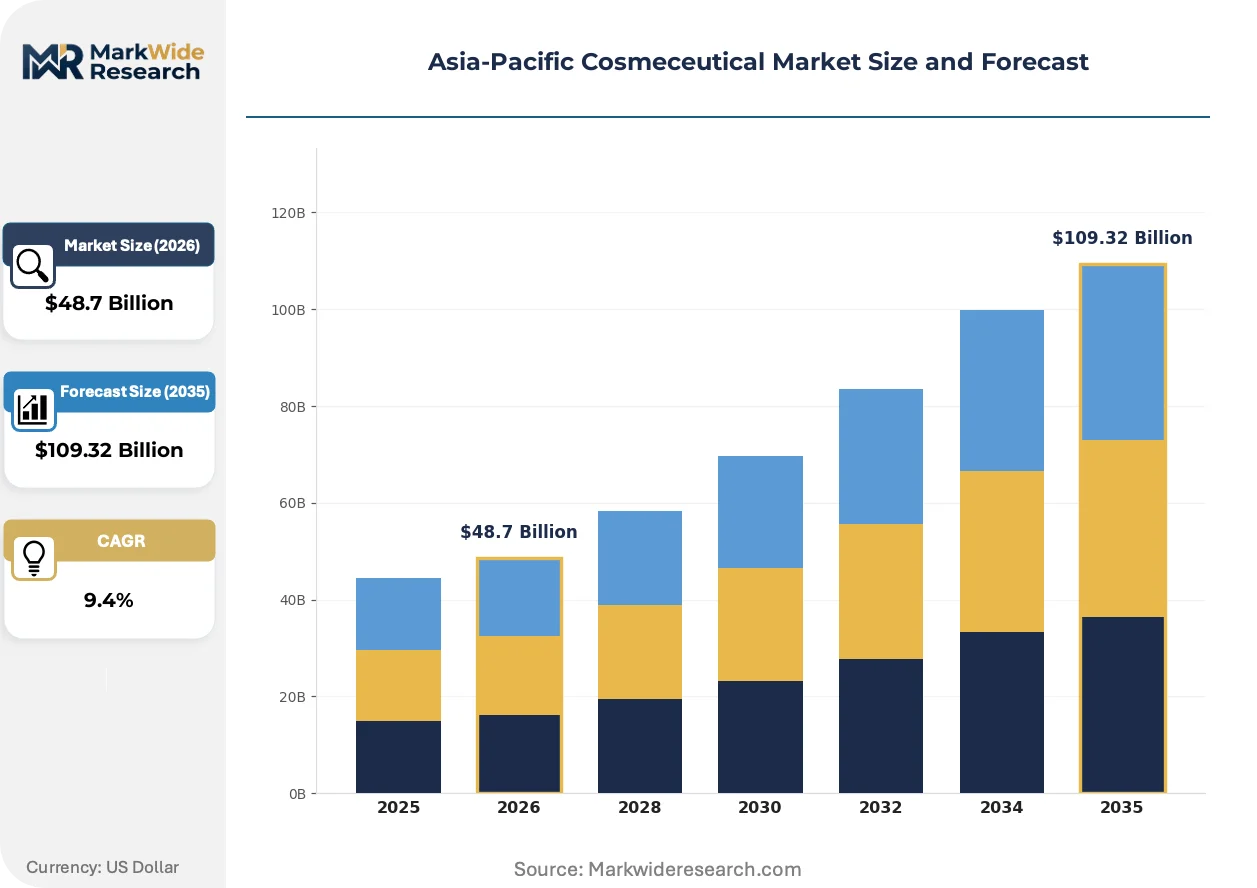
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $109.32 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skin Care, Hair Care, Makeup, Oral Care Formulation: Creams, Serums, Gels, Masks Distribution Channel: Online Retail, Drugstores, Supermarkets, Specialty Stores End User: Women, Men, Teens, Mature Adults |
| Companies Covered | L'Oréal SA, Procter & Gamble Co, Shiseido Group, Unilever PLC, Johnson & Johnson, Estée Lauder Companies, Kao Corporation, Beiersdorf AG, Amorepacific Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Cosmeceutical Market Strategic Shifts
Active ingredient delivery systems are fragmenting traditional formulation hierarchies, as biotechnology-derived carriers and precision encapsulation technologies compress the gap between cosmetic elegance and pharmaceutical efficacy.
Microbiome-targeted skincare is decomposing the legacy clean-beauty positioning that dominated Asia-Pacific marketing through 2020. Seoul-based innovation labs are engineering postbiotic lysates and phage-derived antimicrobials for atopic dermatitis adjacency claims. Dermatology clinics in Singapore and Bangkok are adopting these formats faster than mass retail channels, compressing the traditional 36-month trend cycle into 18-month clinical validation windows.
China's NMPA is tightening cosmetic efficacy claim substantiation requirements, forcing brands to commission domestic clinical trials or abandon functional promises on packaging. This regulatory friction most affects anti-pigmentation and anti-acne categories, where brands previously relied on ingredient association rather than measured outcomes. Japanese and South Korean exporters are responding by establishing captive testing facilities in Shanghai and Guangzhou to compress registration timelines.
Younger male consumers across the Asia-Pacific region are collapsing gendered skincare segmentation that structured brand portfolios for three decades. Seoul-Incheon corridor retailers report men's serum and sunscreen velocities approaching parity with women's in the 18-29 cohort. This behavioral pivot is most visible in China's tier-one cities and Tokyo's Shibuya district, where unisex positioning now commands shelf-space premiums over legacy men's lines.
Asia-Pacific Cosmeceutical Market Segmentation
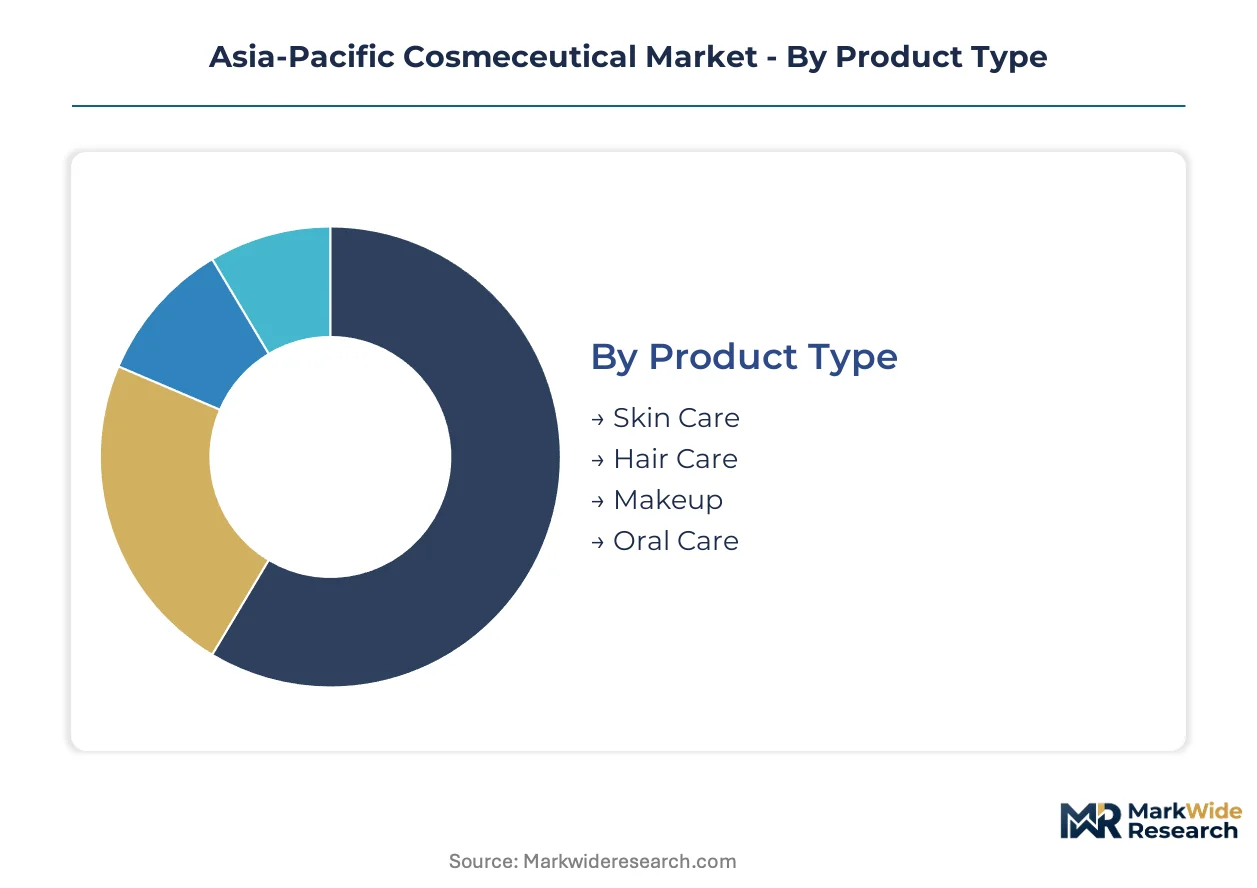
Cosmeceutical segmentation in Asia-Pacific reflects divergent regulatory pathways and channel economics. Product type and formulation hierarchies determine margin capture, while distribution channel choices dictate compliance burden and customer acquisition cost.
Product Type:
Margin pools concentrate in dermatological-grade skin treatments where clinical substantiation commands pricing premiums.
- Skin Care:Formulations containing retinoids, peptides, hydroxy acids, and niacinamide at therapeutic concentrations dominate revenue. Seoul-Incheon corridor innovation clusters and Tokyo dermatology clinics pull pharmaceutical-grade serums and barrier-repair creams into professional protocols. Japan's MHLW quasi-drug framework creates predictable efficacy thresholds that premium brands leverage.
- Hair Care:Scalp microbiome-targeted treatments and peptide-based growth serums are gaining traction in South Korea's functional cosmetics channel. MFDS registration requirements for anti-hair-loss claims force brands toward clinical trial investment or restricted marketing language.
- Makeup:Hybrid color-cosmetic formulations with SPF and antioxidant loading address sun-damage prevention demand in Southeast Asian markets.
- Oral Care:Enzyme-based whitening and probiotic formulations occupy niche positioning under dental professional recommendation channels.
The dominant share belongs to Skin Care, while Hair Care is closing the gap fastest.
Formulation:
Active-ingredient delivery mechanisms determine bioavailability claims and registration complexity across national regulators.
- Serums:High-concentration aqueous or lipid-based carriers with minimal filler content allow maximal active loading. South Korean contract manufacturers specialize in fermented botanical serum bases that compress development cycles for regional brands. China's NMPA requires enhanced stability documentation for serum formulations with unstable actives.
- Creams:Emulsion-based vehicles with ceramide and lipid matrices dominate Japan's mass-market tier. Kao Corporation's regional supply chain control constrains independent brand cost structures for barrier-repair formulations.
- Gels:Water-based systems with rapid absorption profiles target humid climate preferences in Southeast Asia.
- Masks:Sheet and wash-off formats serve as entry-point products for cross-border e-commerce customer acquisition in China.
Serums capture the steepest margin expansion, though Creams retain volume leadership in Japanese drugstore channels.
Distribution Channel:
Channel selection determines regulatory exposure, with direct-to-consumer routes bypassing import registration requirements.
- Online Retail:Cross-border e-commerce pilot zones in China create temporary compliance windows for brands lacking NMPA registration. Southeast Asian platforms are displacing traditional drugstore dominance fastest in tier-two and tier-three Chinese cities.
- Specialty Stores:Premium conversion rates sustain in Tokyo's Shibuya district and Seoul's Gangnam corridor, where trained staff substantiate clinical claims. Amorepacific and Shiseido flagship locations anchor this channel.
- Drugstores:Japanese mass-market penetration relies on Kao Corporation's manufacturing scale controlling regional ceramide supply chains.
- Supermarkets:Basic SPF and moisturizer segments dominate, with limited active-ingredient concentrations avoiding quasi-drug classification.
Online Retail is expanding most quickly, while Specialty Stores defend margin position through experiential service.
End User:
Demographic targeting is collapsing as gender-neutral positioning reorganizes brand portfolios.
- Women:Traditional anti-aging and pigmentation-correction segments retain volume concentration. Legacy brand positioning around age-reversal faces disruption from preventive skincare adoption in younger cohorts.
- Men:Serum and sunscreen velocities approach parity with women's in the 18-29 cohort across Seoul-Incheon retailers and Shanghai tier-one channels. Unisex positioning commands shelf-space premiums over legacy men's lines.
- Teens:Acne-adjacent and barrier-protection formulations drive first cosmeceutical purchase occasions.
- Mature Adults:Dermatology clinic protocols pull pharmaceutical-grade formulations into outpatient settings across Thailand, Singapore, and Vietnam.
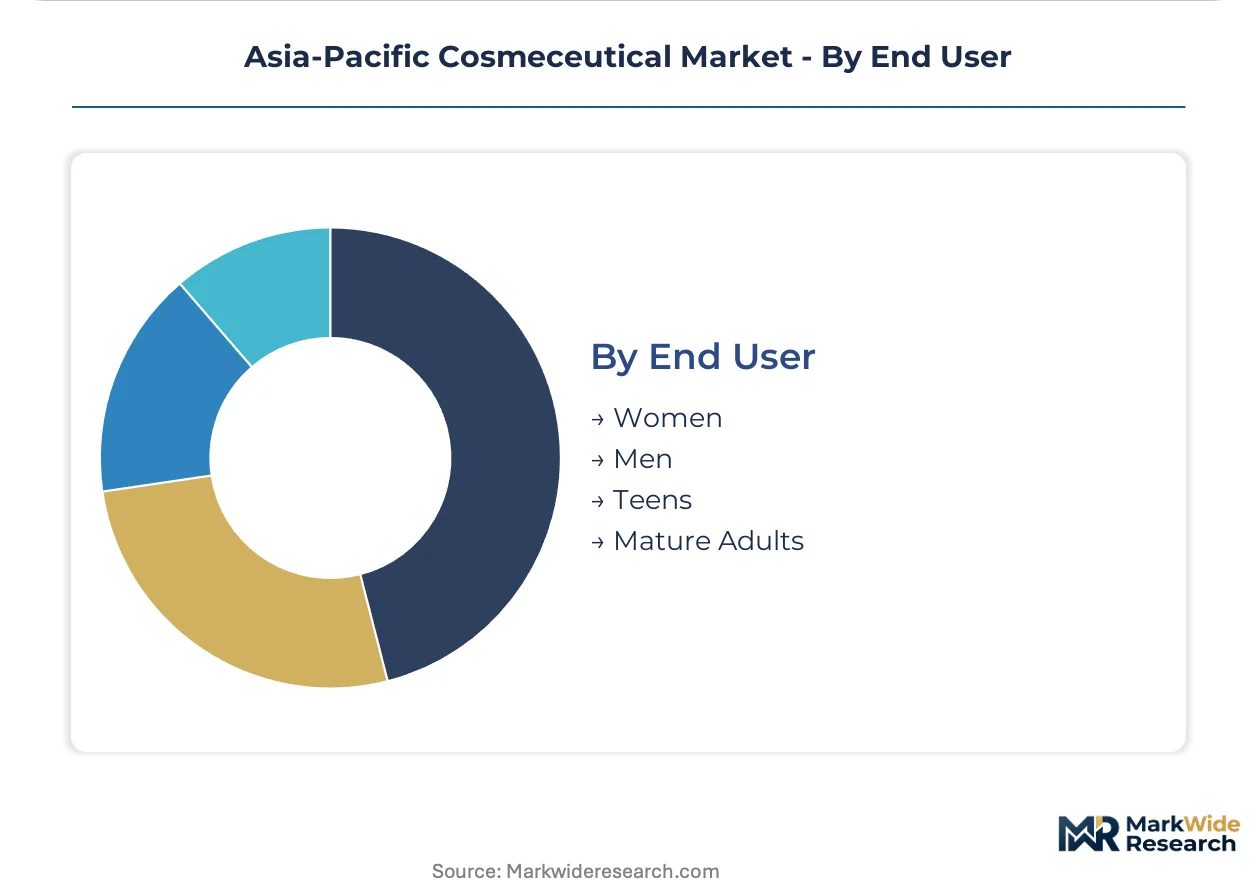
Women retain the dominant share, though Men represent the fastest-closing gap as gendered segmentation dissolves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese and South Korean manufacturers command the dominant share of active ingredient synthesis capacity, with Seoul-Incheon corridor labs and Tokyo dermatology clinics pulling pharmaceutical-grade formulations into professional protocols across Southeast Asia.
Japan
Barrier-repair demand concentrates in Tokyo's Shibuya district and Osaka's drugstore channels, where ceramide-based formulations dominate mass-market tiers. The MHLW quasi-drug framework imposes concentration limits on retinoids and hydroxy acids that premium brands leverage for clinical credibility. Kao Corporation's regional supply chain control constrains independent brand cost structures for emulsion-based vehicles.
South Korea
Fermented botanical actives drive Seoul-Incheon corridor innovation clusters, with Gangnam retailers reporting men's serum velocities approaching parity with women's in the 18-29 cohort. The MFDS functional cosmetics designation requires clinical trial investment for anti-hair-loss claims, forcing brands toward restricted marketing language or substantiation spending. Amorepacific Corporation anchors premium positioning through captive innovation labs specializing in postbiotic lysates.
China
Tier-one cities Shanghai and Beijing compress trend cycles as cross-border e-commerce pilot zones create temporary compliance windows for brands lacking NMPA registration. The NMPA cosmetic registration requirements impose extended animal-alternative testing protocols that delay imported cosmeceutical entry by 18-24 months. Domestic clinical trials for efficacy claim substantiation concentrate in Shanghai and Guangzhou testing facilities.
Vietnam
Ho Chi Minh City dermatology clinics professionalize skincare protocols faster than mass retail channels, pulling pharmaceutical-grade formulations into outpatient settings before domestic quasi-drug frameworks mature. Regulatory arbitrage windows attract first-mover positioning from regional brands seeking penetration ahead of compliance formalization. Bangkok-based medical spa chains extend protocols into Hanoi and Da Nang corridor markets.
Indonesia
Jakarta's underdeveloped professional skincare channels offer positioning opportunities for brands establishing dermatology clinic relationships ahead of domestic regulatory maturation. Humid climate preferences drive water-based gel absorption profiles that differ from Northeast Asian emulsion dominance. Cross-border e-commerce platforms from Singapore and Malaysia displace traditional drugstore channels fastest in Surabaya and Bandung tier-two markets.
Asia-Pacific Cosmeceutical Market Competitive Environment
Concentration sits with diversified beauty conglomerates and specialized fermentation houses, creating a tiered structure where heritage R&D investment separates premium positioning from mass-market scale plays. Three archetypes dominate: century-old Japanese houses leveraging quasi-drug credibility, Seoul-based innovation labs commercializing fermented botanicals, and European multinationals arbitraging cross-border e-commerce regulatory windows. Competitive moves center on captive testing facility establishment in Shanghai and Guangzhou to compress NMPA timelines, plus backward integration into peptide synthesis capacity to reduce exposure to South Korean contract manufacturer pricing volatility.
Among heritage Japanese houses, Shiseido Group and Kao Corporation exemplify divergent strategic postures. Shiseido leverages Tokyo-based R&D heritage to sustain premium pricing across multiple Asian markets, while Kao dominates mass-market tiers through manufacturing scale controlling regional ceramide supply chains. Seoul-based Amorepacific Corporation anchors the fermentation-specialist archetype, occupying a position where postbiotic lysate development collapses traditional trend cycles into compressed clinical validation windows.
| Leading Market Players |
|---|
| L'Oréal SA |
| Procter & Gamble Co |
| Shiseido Group |
| Unilever PLC |
| Johnson & Johnson |
| Estée Lauder Companies |
| Kao Corporation |
| Beiersdorf AG |
| Amorepacific Corporation |
| Others |
Value Chain & Pricing Dynamics
Capacity reservation agreements with South Korean peptide synthesis houses lock in both active ingredient access and cost visibility for premium serum formulations navigating Japan's MHLW quasi-drug compliance timelines. These contractual structures insulate mid-tier brands from spot-market volatility in fermented botanical feedstocks while compressing registration-to-launch intervals.
Pricing Analysis
Volume-discount tiering separates pharmaceutical-grade dermatology clinic lines from mass-market drugstore SKUs and cross-border e-commerce entry products. Price differentiation hinges on clinical trial substantiation investment and MFDS functional cosmetics registration status. Pricing pressure stems from ceramide supply concentration in Japanese manufacturers controlling regional emulsion feedstocks. Mass-market buyers in Southeast Asian drugstores exhibit highest price sensitivity; premium clinic protocols in Tokyo and Seoul show lowest elasticity.
Supply Chain Analysis
Inbound logistics costs through Shanghai and Busan port corridors fluctuate with container availability on Northeast Asian trade lanes, compressing margin buffers for NMPA-registered imports. Active ingredient synthesis concentrates in South Korea, Japan, and select Chinese contract manufacturers. Formulation chemistry rests on retinoid stability compounds, fermented lysate bases, and precision encapsulation polymers. Single-source vulnerability runs through peptide production clusters in Seoul-Incheon. Distribution feeds from captive innovation labs through dermatology clinic networks and cross-border pilot zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific cosmeceutical sector is cycling through a recovery phase as post-pandemic clinic protocol professionalization restocks professional-grade inventory pipelines. This cyclical upswing is anchored by Thailand and Vietnam medical spa expansion pulling pharmaceutical-grade formulations into outpatient settings.
For Market Incumbents: Fortify backward integration into peptide synthesis capacity to reduce exposure to South Korean contract manufacturer pricing swings. Deepen captive testing facility footprints in Shanghai and Guangzhou to compress NMPA registration timelines against emerging European multinationals arbitraging cross-border e-commerce windows. For New Entrants and Emerging Players: MFDS fast-track pathways for functional cosmetics designation offer regulatory credibility without full pharmaceutical trials. White-space concentrates in Ho Chi Minh City and Jakarta dermatology channels before domestic quasi-drug frameworks mature. Launch through clinic-direct sampling programs to bypass mass retail slotting fees. For Investors and Strategic Acquirers: Fermentation-specialist labs with postbiotic lysate IP portfolios represent the most defensible acquisition archetype as microbiome claims compress trend cycles. Long-term viability hinges on CRISPR-derived peptide engineering capabilities displacing traditional synthesis. Watch for NMPA efficacy claim tightening enforcement as the inflection signal for domestic clinical trial infrastructure plays.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Testing Facility Establishment | Shanghai and Guangzhou laboratories compress NMPA animal-alternative testing timelines for imported serums. |
| Backward Integration into Peptide Synthesis | In-house production of active ingredients insulates margin structures from Seoul-based contract manufacturer pricing volatility. |
| Clinic-Direct Distribution Expansion | Bangkok and Ho Chi Minh City medical spa protocols pull pharmaceutical-grade formulations ahead of retail channel maturation. |
| Postbiotic Lysate IP Development | Seoul-based innovation labs engineering microbiome-targeted claims collapse traditional trend cycles into compressed validation windows. |
| Cross-Border E-Commerce Regulatory Arbitrage | China's pilot zones create temporary compliance windows for brands lacking local manufacturing partnerships or full NMPA registration. |
Study Parameters
Cross-validation between regulatory filing databases and trade flow records anchors the qualitative findings on compliance pathway fragmentation. Primary interviews with dermatology clinic procurement directors, formulation chemists at contract research organizations, MFDS registration consultants, and cross-border e-commerce platform category managers combined with secondary analysis of NMPA cosmetic registration disclosures, Japan MHLW quasi-drug approval logs, and South Korean customs export data. Bottom-up brand revenue estimates and top-down regional consumption patterns were triangulated.
Sensitivity analysis around regulatory timeline assumptions and active ingredient cost trajectories informed the projection framework across the analysis window. Segmentation dimensions modeled include product type, formulation vehicle, distribution channel, and national regulatory cluster. CAGRs were derived from fitted growth curves against historical penetration rates. Forecast inputs incorporated MHLW concentration limit enforcement patterns and NMPA efficacy claim substantiation tightening.
Decision-makers should treat outputs as directional under base assumptions of stable quasi-drug framework enforcement and continued cross-border e-commerce pilot zone operation; material deviation in regulatory arbitrage windows or peptide supply disruptions would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Anti-Aging Services Market
Skincare
Global Eczema Skin-Care Products Market
Skincare
Hidradenitis Suppurativa Market
Skincare
Natural Skin Care Products Market
Skincare
Skin Care Emulsion Market
Skincare
Moisturizing Cream Market
Skincare
Skin Resurfacing Market
Skincare
Organic Skincare Products Market
Skincare
Tinted Sunscreen Market
Skincare
Dermocosmetics Skin Care Products Market
Skincare
Dermocosmetics Market
Skincare
DNA-Based Skin Care Products Market
Skincare
Global Skin Rejuvenation Market
Skincare
Ultrasound Skin Cleaners Market
Skincare
Allantoin Extract for Skincare Products Market
Skincare
Skin Boosters Market