
 Asia-Pacific AI in Fintech Market | 2026-2036
Asia-Pacific AI in Fintech Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific AI in Fintech Market Analytics
Chinese cloud infrastructure providers is consolidating AI compute capacity for financial services across the Asia-Pacific region. Ant Financial leverages proprietary risk engines to anchor its dominance in digital lending platforms. Tencent Holdings sustains competitive pressure through its WeChat ecosystem integration with wealth management services. Ping An Technology differentiates via its in-house medical-financial data fusion for insurance underwriting.
Asia-Pacific AI in Fintech deploys machine learning algorithms, natural language processing engines, and predictive analytics models to automate credit decisions, detect anomalous transactions, and personalize customer interactions across banking and insurance workflows. The technology stack spans supervised learning for default prediction, transformer architectures for multilingual chatbot deployment, and real-time graph analytics for anti-money-laundering surveillance. Fraud Detection applications lead current deployment intensity as banks face escalating synthetic identity schemes across Indonesia and Vietnam. Cloud-Based deployment is accelerating fastest among neobanks in the Philippines and Thailand that lack legacy mainframe infrastructure. Machine Learning occupies the deepest margin pools where proprietary training data on regional borrower behavior creates defensible model performance gaps.
India's RBI mandates algorithmic transparency in digital lending, China's SAMR enforces data localization for financial AI training sets, and Australia's ASIC supervises robo-advisory disclosure standards. These frameworks compel vendors to architect explainable model pipelines and jurisdictional data segregation from initial product design. Stakeholders must monitor divergence between China's GB standards and ASEAN model risk guidelines as cross-border platform expansion faces escalating compliance fragmentation.
Market Dynamics
Regulatory fragmentation across Asia-Pacific jurisdictions is forcing AI fintech vendors to architect multi-layered compliance architectures from initial product design, diverting engineering resources from core algorithmic development toward explainability and data localization mandates.
Growth Catalysts
- India's RBI Digital Lending Guidelines:Mandatory algorithmic transparency requirements create first-mover advantages for domestic vendors with compliant model pipelines. Neobanks accelerate procurement of explainable AI credit engines.
- Synthetic Identity Fraud Surge:Indonesian and Vietnamese banking regulators escalate supervisory scrutiny of transaction monitoring systems. Real-time graph analytics deployment intensifies across retail payment networks.
- Cloud-Native Neobank Expansion:Philippine and Thai digital banks bypass legacy mainframe constraints entirely. Greenfield infrastructure enables native AI integration without technical debt remediation.
Market Restraints
- GPU Compute Cost Volatility:NVIDIA H100 cluster pricing fluctuates with US export control adjustments. Chinese cloud providers face supply uncertainty for training large language models.
- Data Localization Mandates:China's SAMR requires financial AI training sets to reside within national borders. Cross-border model deployment incurs redundant infrastructure expenditure.
- Multilingual NLP Performance Gaps:Transformer architectures trained on English corpora underperform on Thai, Vietnamese, and Bahasa Indonesia financial terminology. Regional vendors lack proprietary training data scale.
Strategic Opportunities
- ASEAN Model Risk Harmonization:Singapore's MAS consults on cross-border AI governance standards. Early alignment positions vendors for streamlined multi-jurisdiction licensing.
- Medical-Financial Data Fusion:InsurTech platforms integrate health records with underwriting algorithms. Japan's METI encourages sector convergence through sandbox exemptions.
- Embedded Finance Distribution:Super-app ecosystems in Indonesia and Vietnam embed lending and insurance APIs. Non-bank platforms become primary customer acquisition channels.
Industry Challenges
- Quantitative Risk Modeler Shortage:Asia-Pacific universities produce insufficient graduates combining stochastic calculus with machine learning engineering. Salaries for dual-competency talent inflate 40% above pure software roles.
- Legacy Core Banking Integration:Tier-one Chinese and Indian banks operate 1990s-era COBOL systems. API middleware layers introduce latency that degrades real-time AI decision performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific AI in Fintech Market |
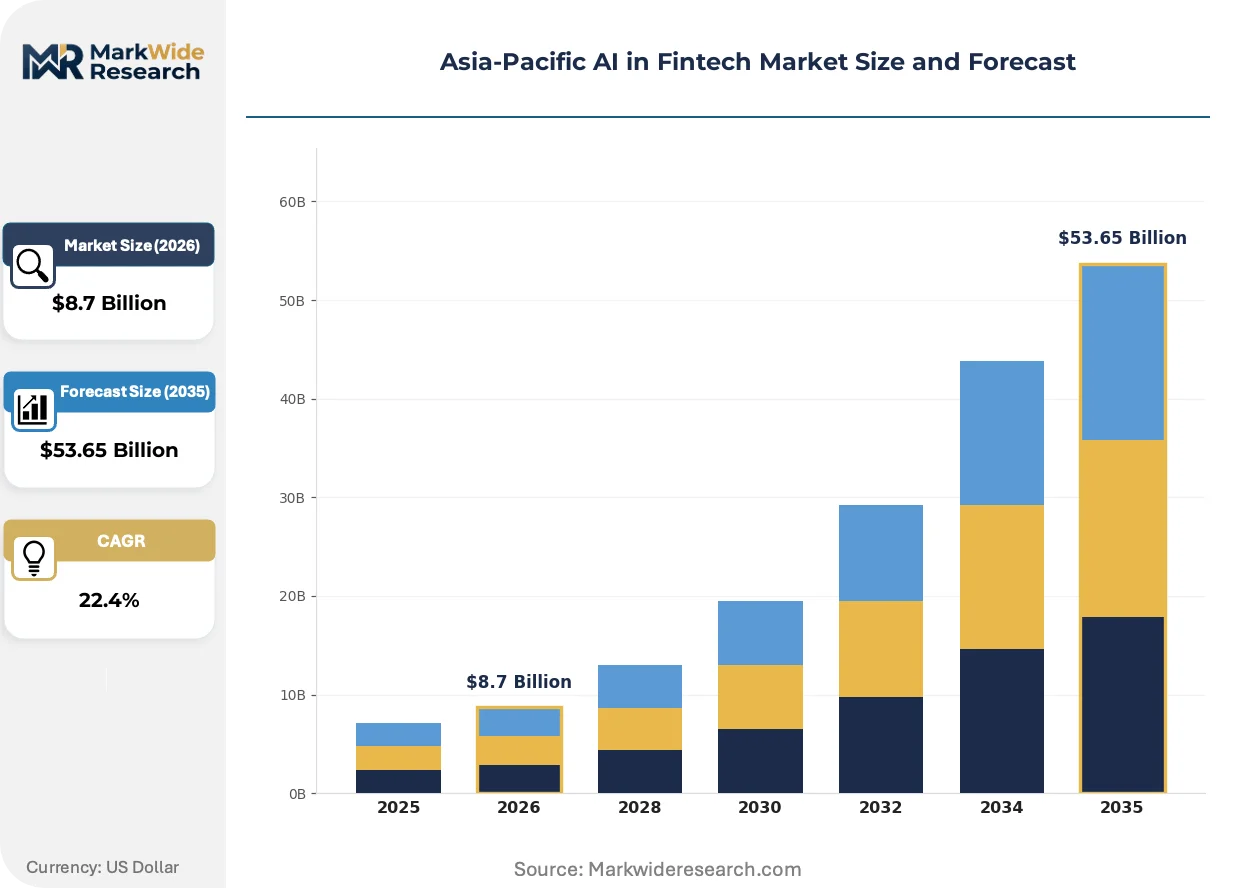
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $53.65 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Fraud Detection, Risk Management, Loan Underwriting, Customer Service Technology: Machine Learning, Natural Language Processing, Computer Vision, Predictive Analytics End User: Banks, Insurance Companies, Investment Firms, Payment Processors Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Ant Financial, Kakao Pay, Paytm, Grab Financial Group, Tencent Holdings, Baidu, OneConnect, JDDJ, Ping An Technology, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific AI in Fintech Market Evolving Landscape
Foundation model architectures trained on regional financial corpora are compressing development timelines for credit scoring and fraud detection applications, while regulatory technology vendors race to embed compliance automation directly into model training pipelines.
Federated learning frameworks for cross-institutional credit risk modeling is overtaking centralized data pooling approaches in privacy-sensitive markets. Korean KakaoBank and Singaporean DBS pilot collaborative default prediction without raw data exchange. This architecture compresses model development costs while satisfying data protection constraints that block traditional consortium approaches.
Australia's ASIC robo-advisory disclosure standards now mandate algorithmic performance benchmarking against human advisor equivalents. Wealth management platforms restructure client communication interfaces to present model confidence intervals alongside return projections. The regulatory pressure most acutely affects hybrid robo-human advisory services targeting high-net-worth segments in Sydney and Melbourne.
Corporate treasury departments at Asia-Pacific multinationals now demand outcome-based pricing for AI-powered FX hedging and liquidity forecasting tools. Vendors abandon seat-based SaaS models in favor of basis-point spreads on executed trades. This procurement evolution concentrates among Singapore-domiciled commodity traders and Hong Kong-listed manufacturers with volatile cross-border receivables exposure.
Asia-Pacific AI in Fintech Market Segmentation
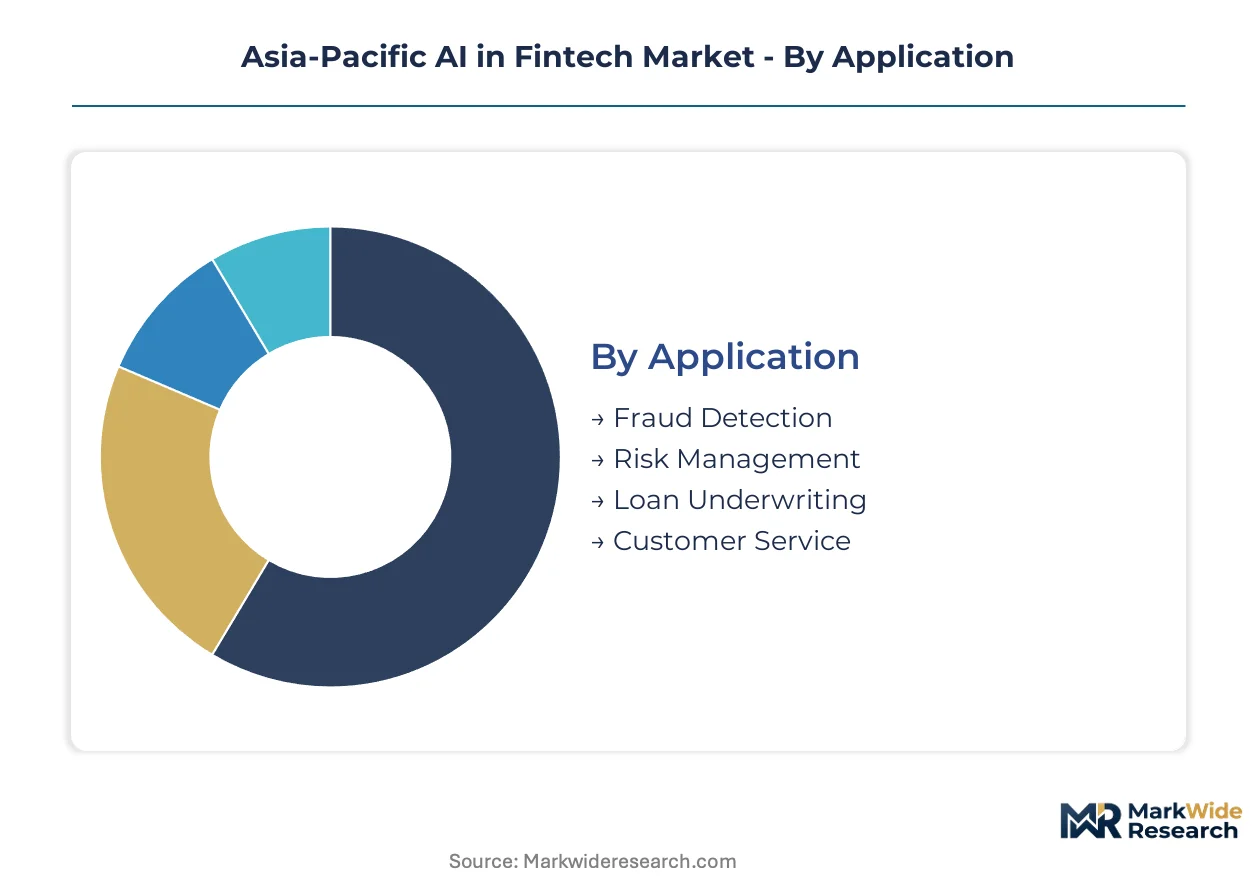
AI fintech segmentation in Asia-Pacific reflects divergent technology maturity across banking infrastructure layers. Deployment choices and application priorities vary sharply between legacy institutions in Shanghai and greenfield neobanks in Manila.
Application:
Volume concentrates in defensive compliance use cases, while premium expansion targets revenue-generating customer interfaces.
- Fraud Detection:Real-time graph analytics identify synthetic identity schemes across Indonesian and Vietnamese payment networks. Banks in Jakarta and Ho Chi Minh City prioritize transaction monitoring upgrades ahead of regulatory deadlines.
- Risk Management:Supervised learning models predict borrower default using alternative data from mobile wallet histories. Demand clusters among Indian digital lenders navigating RBI algorithmic transparency mandates.
- Loan Underwriting:Automated credit decisions reduce origination costs for microfinance platforms serving underbanked populations in the Philippines.
- Customer Service:Multilingual chatbots handle wealth management queries across Singapore's private banking sector.
Today's leader: Fraud Detection. Tomorrow's challenger: Customer Service.
Technology:
Proprietary training data scale separates margin leaders from commodity algorithm providers.
- Machine Learning:Gradient-boosted decision trees and neural networks power credit scoring engines with region-specific feature engineering. Ant Financial and Tencent leverage proprietary borrower behavior datasets to maintain model performance gaps.
- Natural Language Processing:Transformer architectures process financial terminology in Thai, Vietnamese, and Bahasa Indonesia. Performance lags behind English-trained models due to limited regional corpus availability.
- Computer Vision:Document verification systems authenticate identity papers for digital onboarding workflows.
- Predictive Analytics:Time-series forecasting supports treasury liquidity management at Hong Kong-listed manufacturers.
Machine Learning commands the deepest margin pools. Natural Language Processing faces the steepest capability climb.
End User:
Procurement authority shifts from centralized IT to line-of-business units seeking autonomous AI deployment.
- Banks:Tier-one Chinese institutions retrofit COBOL core systems with API middleware for real-time AI integration. Latency constraints persist in legacy environments.
- Insurance Companies:Health record fusion with underwriting algorithms accelerates in Japan following METI sandbox exemptions. Ping An Technology anchors medical-financial data convergence.
- Investment Firms:Robo-advisory platforms restructure client interfaces to present model confidence intervals per ASIC disclosure standards.
- Payment Processors:Real-time fraud scoring protects cross-border remittance corridors linking ASEAN labor markets.
Banks drive current procurement volume. Insurance Companies are gaining share fastest through health data integration.
Deployment:
Technical debt remediation costs dominate infrastructure decisions for incumbent institutions.
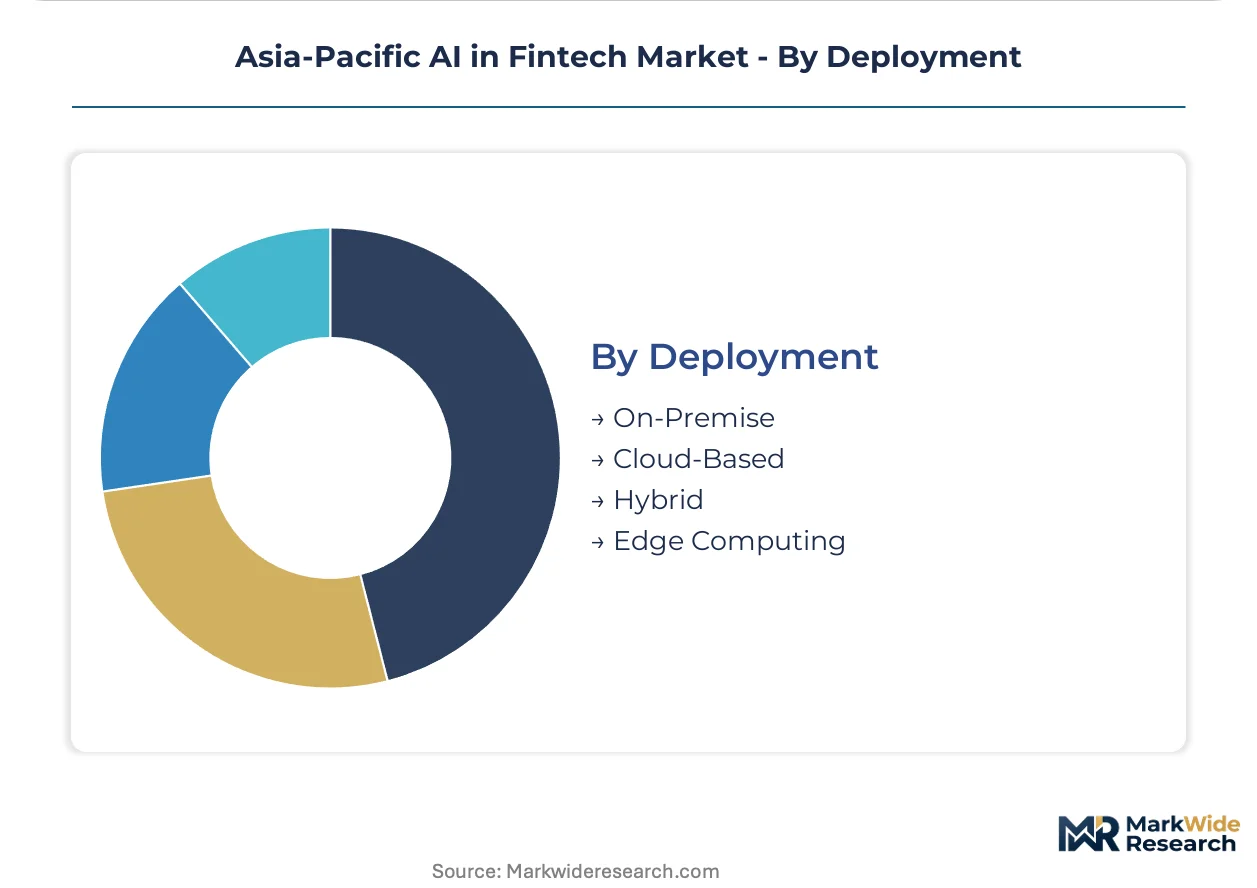
- Cloud-Based:Native AI integration without legacy constraints attracts Philippine and Thai neobanks. Greenfield infrastructure eliminates mainframe migration expenses entirely.
- Hybrid:Sensitive model training occurs on-premise while inference scales through public cloud. China's SAMR data localization mandates enforce this architecture.
- On-Premise:State-owned banks in Beijing and Shanghai retain captive compute for sovereign data control.
- Edge Computing:Low-latency transaction scoring deploys at payment terminal networks across Indonesian retail chains.
Cloud-Based deployment is expanding most quickly. Hybrid architectures satisfy compliance fragmentation across jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping vendor deployment strategies across the Asia-Pacific region, with compliance-cost differentials driving AI fintech infrastructure toward jurisdictions offering clearer algorithmic governance frameworks. Singapore and Australia attract regional headquarters functions, while India and Indonesia concentrate operational scale.
China
Ant Financial and Tencent Holdings anchor domestic demand through super-app ecosystems integrating wealth management and digital lending. SAMR enforces strict data localization mandates requiring financial AI training sets to reside within national borders. Shanghai and Beijing host captive compute clusters serving state-owned banks seeking sovereign data control.
India
RBI algorithmic transparency requirements accelerate procurement of explainable AI credit engines among neobanks and digital lenders. The Mumbai-Bangalore corridor concentrates technical talent and venture deployment for fintech AI development. Domestic vendors gain first-mover advantages through compliant model pipelines.
Singapore
MAS consultations on cross-border AI governance standards position the city-state as a regulatory harmonization hub for ASEAN expansion. Wealth management platforms restructure client interfaces to present model confidence intervals. The financial district anchors regional headquarters for vendors seeking streamlined multi-jurisdiction licensing.
Australia
ASIC robo-advisory disclosure standards mandate algorithmic performance benchmarking against human advisor equivalents. Sydney and Melbourne concentrate hybrid robo-human advisory services targeting high-net-worth segments. Corporate treasury departments at Asia-Pacific multinationals demand outcome-based pricing for AI-powered FX hedging tools.
Indonesia
Synthetic identity fraud surges across retail payment networks, intensifying real-time graph analytics deployment. Banking regulators escalate supervisory scrutiny of transaction monitoring systems. Jakarta anchors transaction monitoring upgrades as banks prioritize fraud detection ahead of regulatory deadlines.
Asia-Pacific AI in Fintech Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue embedded finance distribution through super-app ecosystems. The vendor base clusters around three maturity tiers: cloud-native neobank specialists, legacy bank retrofitters, and super-app platform operators. Strategic archetypes include proprietary data aggregators, regulatory technology integrators, and vertical insurance underwriters. Dominant competitive moves center on federated learning partnerships for cross-institutional credit risk modeling and medical-financial data fusion for insurance product differentiation.
Within the proprietary data tier, Ant Financial and Tencent Holdings exemplify ecosystem-anchored competitive positioning. Ping An Technology occupies a distinct archetype bridging medical and financial data convergence for insurance underwriting. These three entities represent divergent strategic paths: super-app financial integration, cloud infrastructure consolidation, and sector-specific data fusion.
| Leading Market Players |
|---|
| Ant Financial |
| Kakao Pay |
| Paytm |
| Grab Financial Group |
| Tencent Holdings |
| Baidu |
| OneConnect |
| JDDJ |
| Ping An Technology |
| Others |
Value Network & Pricing Analysis
Neobanks in the Philippines and Thailand anchor procurement volume for cloud-native AI fintech infrastructure, locking in subscription-based SaaS pricing with outcome-based overlays for fraud detection modules. Their greenfield status eliminates legacy technical debt remediation costs, compressing total cost of ownership relative to incumbent banks retrofitting COBOL systems.
Pricing Analysis
Direct-to-neobank SaaS subscriptions bypass distributor margins entirely, with vendors capturing value through tiered deployment scales. Price differentiation rests on explainable AI certification tiers and proprietary training data scale for regional borrower behavior. Cost compression in GPU compute tiers intensifies as NVIDIA H100 cluster availability fluctuates with US export control adjustments. Tier-one Chinese banks show least price sensitivity due to captive sovereign data control requirements, while Philippine digital lenders negotiate aggressively on per-transaction inference costs.
Supply Chain Analysis
Regional distribution centers in Singapore and Hong Kong anchor AI model deployment logistics for ASEAN expansion, with hub-and-spoke patterns radiating to Jakarta and Ho Chi Minh City. GPU hardware concentrates in Taiwan and South Korea, while cloud infrastructure draws from domestic Chinese providers facing SAMR data localization mandates. Single-source vulnerability in advanced semiconductor fabrication threatens training capacity for large language models. Distribution runs through hyperscaler marketplaces and direct vendor relationships with tier-one financial institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between Singapore's MAS harmonization consultations and China's SAMR data localization mandates creates geographic cost differentials for AI fintech infrastructure deployment. Vendors optimizing compliance architecture across both jurisdictions capture structural margin advantages.
For Market Incumbents: Anticipate federated learning partnerships as the primary defensive response to synthetic identity fraud escalation across Indonesian payment networks. Consolidate proprietary borrower behavior datasets to maintain model performance gaps against cloud-native challengers. Invest in API middleware latency reduction for COBOL core banking integration, as real-time AI decision degradation threatens customer retention in digital lending workflows.
For New Entrants and Emerging Players: Capture embedded finance distribution channels through super-app ecosystem integration in Indonesia and Vietnam, where non-bank platforms dominate customer acquisition. Target medical-financial data fusion for insurance underwriting following Japan's METI sandbox exemptions, as this segment shows fastest share gain. Deploy multilingual NLP solutions for Thai and Vietnamese financial terminology, addressing the steepest capability climb in regional natural language processing.
For Investors and Strategic Acquirers: Cloud infrastructure providers with financial services verticalization are the most active acquirer in this space, seeking explainable AI credit engine capabilities for neobank procurement cycles. Long-term viability hinges on jurisdictional data segregation architecture that satisfies RBI algorithmic transparency mandates and ASEAN model risk guidelines simultaneously. Monitor divergence between China's GB standards and Singapore's cross-border AI governance consultations as the critical inflection indicator for platform scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Federated Learning Partnership | KakaoBank and DBS pilot collaborative default prediction without raw data exchange, compressing development costs. |
| Medical-Financial Data Fusion | Ping An Technology anchors health record integration with underwriting algorithms following Japan's METI sandbox exemptions. |
| Explainable AI Certification Investment | RBI algorithmic transparency mandates create first-mover advantages for domestic vendors with compliant model pipelines. |
| Super-App Ecosystem Integration | Grab Financial Group embeds lending APIs across Indonesian and Vietnamese non-bank customer acquisition channels. |
| Cloud-Native Infrastructure Buildout | Philippine and Thai neobanks bypass legacy mainframe constraints entirely through greenfield AI-native deployment. |
Research Methodology
Bottom-up neobank procurement modeling reconciled against top-down cloud infrastructure capacity tracking forms the analytical core of this study. Primary interviews with chief technology officers at digital lenders, AI platform engineers at hyperscalers, regulatory compliance leads at MAS and RBI, and procurement officers at tier-one banks combined with secondary validation from SEC filings, hyperscaler capex disclosures, and central bank guideline publications. Triangulation across these sources ensures segmentation integrity for deployment models, application categories, and end-user verticals.
Historical trendline analysis of AI fintech adoption intensity across banking and insurance workflows established baseline penetration rates. The analytical framework projects expansion across the analysis window by modeling technology segmentation dimensions including machine learning, natural language processing, and predictive analytics alongside end-user categories of banks, insurance companies, and payment processors. CAGRs derive from regression analysis of regulatory catalyst timing, GPU compute cost trajectories, and synthetic identity fraud incident rates as industry-specific forecast inputs.
Regulatory divergence, GPU supply disruption, and multilingual NLP performance gaps are the dominant revision risks to the forecast framework. Outputs reflect documented assumptions regarding RBI guideline enforcement timelines and SAMR data localization implementation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Asia-Pacific Fintech Market
FinTech
Fintech Lending Market
FinTech
Financial App Market
FinTech
Singapore AI in Fintech Market
FinTech
Asia-Pacific Fintech Cloud Market
FinTech
Middle East AI in Fintech Market
FinTech
Generative AI in Fintech Market
FinTech
Europe Fintech Market
FinTech
Micro-Investing Platform Market
FinTech
United Kingdom AI in Fintech Market
FinTech
India AI in Fintech Market
FinTech
Canada AI in Fintech Market
FinTech
AI-Powered Wealth Management Solution Market
FinTech
UAE Fintech Market
FinTech
Robo-Advisory Services Market
FinTech
Multichannel Digital Banking Integration Software Market