
 Tax Automation Software Market | 2026-2036
Tax Automation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Tax Automation Software Market Intelligence
ISO 27001 certification for financial data security is collapsing the competitive field, disqualifying smaller vendors from enterprise procurement cycles. Avalara leverages its cloud-native architecture to sustain dominance in sales tax automation across North American e-commerce channels. Thomson Reuters Corporation anchors its position through deep integration with legal and accounting workflows, while Sovos Compliance specializes in regulatory reporting for complex indirect tax regimes.
Tax automation software comprises algorithmic engines that calculate liabilities, populate returns, and maintain audit trails across sales, income, and payroll tax categories, typically processing millions of jurisdictional rate combinations in sub-second response windows. Its primary commercial purpose is to eliminate manual reconciliation errors and accelerate filing velocity for organizations operating across fragmented tax authorities. Cloud-based deployments now capture the fastest expansion as multi-tenant architectures drive per-seat economics below on-premise total cost of ownership, while enterprise solutions concentrate margin pools through customized rule-engine implementations for Fortune 500 tax departments. CPA firms represent a maturing segment where automation penetration already exceeds threshold levels, whereas freelancer adoption remains nascent due to price sensitivity and simplified filing obligations.
The US IRS mandates e-filing thresholds and digital record-keeping standards that compel software upgrades among mid-market filers, while the EU's VAT in the Digital Age framework requires real-time invoice reporting that reshapes product roadmaps for vendors serving European accounts. State-level revenue agencies in India enforce GST reconciliation protocols that drive implementation service demand. Stakeholders must monitor how rapidly evolving e-invoicing mandates fragment compliance requirements across jurisdictions and whether platform consolidation or specialized point solutions better address this complexity.
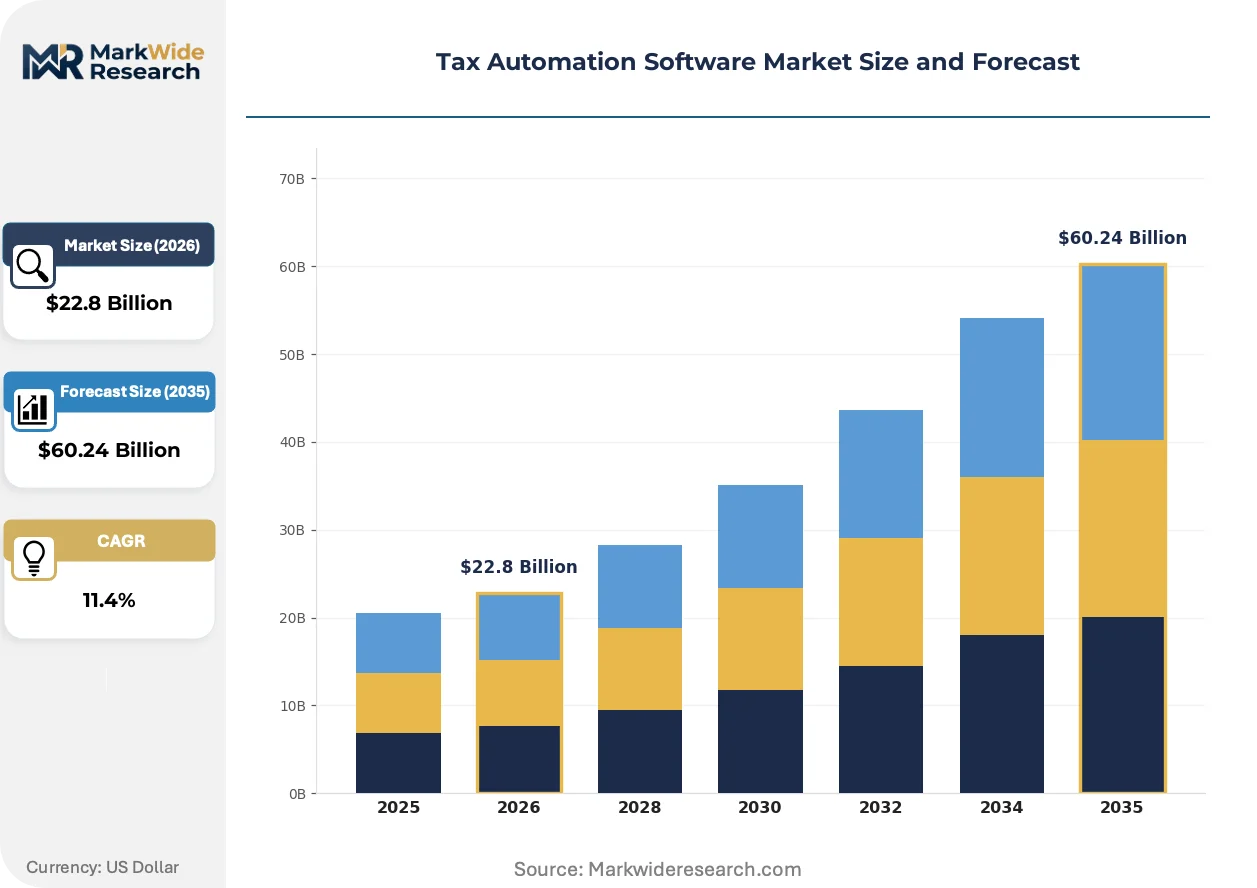
Market Dynamics
Real-time compliance mandates from the US IRS and EU ViDA framework are compressing filing windows and forcing wholesale replacement of batch-oriented tax engines with continuous calculation architectures.
Growth Catalysts
- E-invoicing mandates:Brazil's Nota Fiscal Eletrônica and Italy's SDI requirements force enterprises to adopt automated tax engines that validate transactions at the point of issuance rather than during periodic reconciliation.
- Cloud migration:Mid-market corporations are abandoning on-premise ERP tax modules for API-native SaaS platforms that reduce implementation timelines from quarters to weeks.
- Indirect tax complexity:India's GST reconciliation protocols and Saudi Arabia's ZATCA e-invoicing phases create sustained implementation demand for rule-engine customization services.
Market Restraints
- ISO 27001 certification costs:The $50,000-$150,000 annual compliance burden for financial data security standards excludes regional vendors from enterprise procurement cycles.
- Rate table volatility:US state and local jurisdictions issue over 10,000 annual sales tax rate changes, forcing perpetual subscription upgrades to maintain calculation accuracy.
- Legacy ERP entrenchment:SAP and Oracle on-premise installations with customized tax tables create switching friction that extends replacement cycles beyond typical software refresh timelines.
Strategic Opportunities
- Freelancer segment penetration:Sole proprietors and gig economy workers in the United States remain underserved by current pricing models designed for corporate volume tiers.
- AI-powered audit defense:Machine learning classification of transaction patterns for IRS correspondence automation represents an unoccupied product category between basic filing and full-service representation.
- ViDA preparation services:EU member states' staggered implementation timelines create multi-year advisory and integration revenue windows for vendors with established continental presence.
Industry Challenges
- Specialized tax technologist scarcity:Professionals combining jurisdictional expertise with API architecture skills command compensation premiums that compress implementation margins.
- Multi-tenant data residency conflicts:German and French data localization requirements clash with cloud-native platform economics, forcing expensive regional infrastructure duplication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tax Automation Software Market |
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $60.24 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premise, Hybrid, Enterprise Solutions End User: Corporations, Small Businesses, CPA Firms, Freelancers Service Type: Consulting, Implementation, Support, Maintenance Deployment Model: Single-Tenant, Multi-Tenant, Private Cloud, Public Cloud |
| Companies Covered | Avalara, Vertex Inc., Wolters Kluwer, Intuit Inc., Thomson Reuters Corporation, H&R Block Inc., Sovos Compliance, TaxJar, Drake Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tax Automation Software Market Strategic Shifts & Innovations
Continuous transaction monitoring is replacing periodic reconciliation as the dominant operational paradigm, with vendors racing to embed tax determination directly into procurement and sales workflows rather than treating compliance as a downstream accounting function.
Embedded tax calculation APIs are bifurcating the competitive landscape between lightweight rate-lookup services and full-lifecycle compliance platforms. E-commerce marketplaces and payment processors are adopting the former for immediate checkout accuracy, while Fortune 500 tax departments demand the latter for audit trail completeness and jurisdictional penalty protection. This divergence is compressing mid-market vendor margins as they struggle to serve both simplicity-seeking developers and complexity-tolerant enterprises.
The EU's ViDA framework mandates real-time invoice reporting across all member states by decade's end, forcing product roadmap pivots toward continuous data streaming architectures. Vendors serving European accounts must rebuild batch-oriented engines for sub-second validation against national tax authority servers. German and Italian enterprises face the earliest compliance deadlines and are currently driving pilot program demand.
Subscription unbundling is fragmenting buyer relationships as CPA firms separate tax preparation software from advisory services. Regional accounting partnerships now procure calculation engines through direct vendor relationships while reserving high-margin consulting for internal delivery. This pattern is most visible in the United States, where the largest firms have established captive technology procurement functions independent of traditional software reseller channels.
Tax Automation Software Market Segmentation
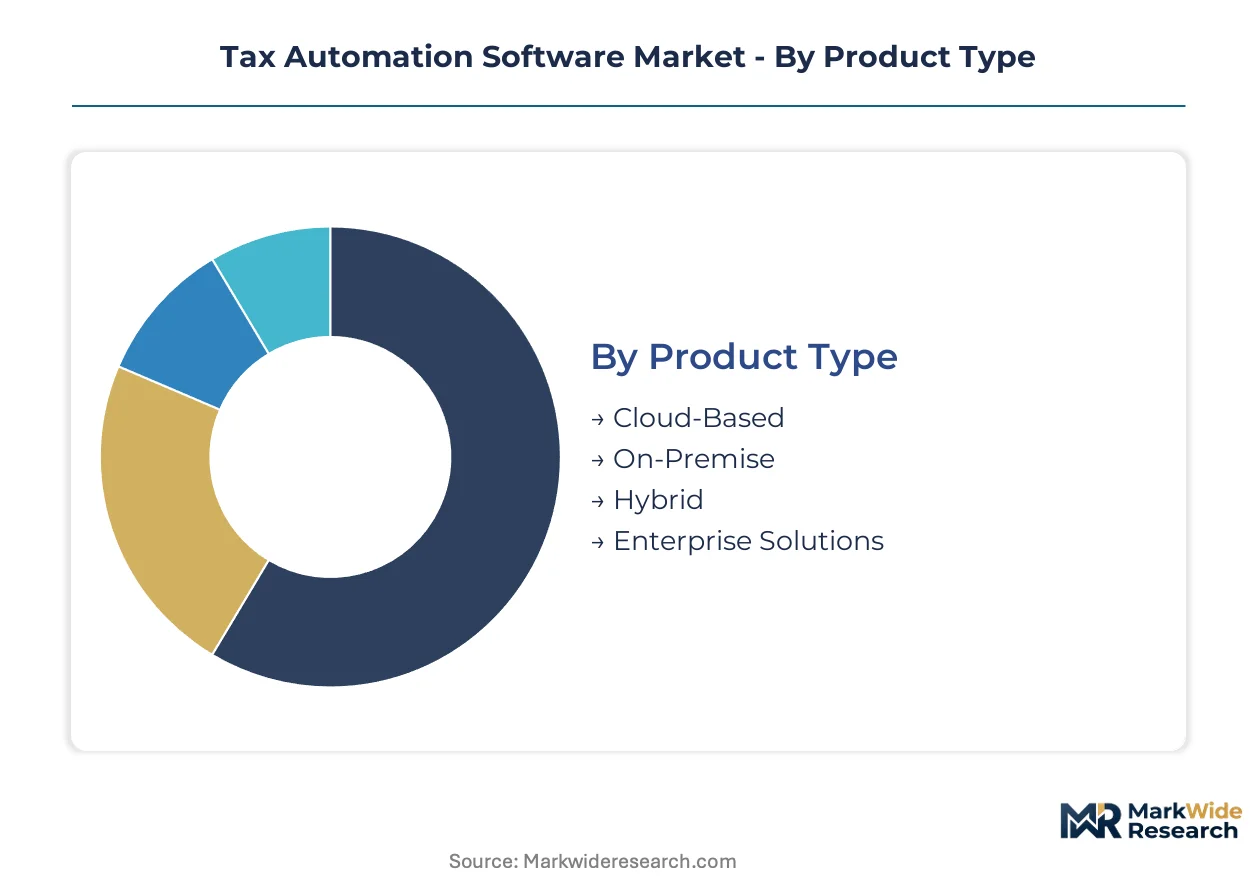
Tax automation software segments by deployment architecture, user scale, and service intensity, with each category mapping to distinct procurement channels and margin structures. Channel strategy varies sharply between volume-driven SaaS platforms and high-touch enterprise implementations.
Product Type:
Cloud-based solutions flow through direct vendor sales and API marketplaces, while enterprise solutions route through systems integrators and advisory partnerships.
- Cloud-Based:Multi-tenant SaaS architectures process millions of jurisdictional rate combinations through REST APIs with sub-second latency. Mid-market corporations in the United States are migrating from on-premise ERP modules to these platforms, compressing implementation timelines from quarters to weeks.
- On-Premise:Legacy installations run customized rule engines within corporate data centers, often entangled with SAP or Oracle ERP customizations that extend replacement cycles beyond typical refresh timelines. German and French data localization requirements sustain residual demand despite cloud migration pressure.
- Hybrid:Split architectures maintain sensitive calculation engines on-premise while leveraging cloud rate tables and update services.
- Enterprise Solutions:Customized implementations for Fortune 500 tax departments command premium pricing through specialized rule-engine configurations and dedicated account management.
On-premise solutions dominate installed base. Cloud-based deployments are where expansion concentrates.
End User:
User scale determines pricing tier and service model, with corporations purchasing through enterprise procurement and freelancers accessing self-serve channels.
- Corporations:Multi-jurisdictional filers require continuous transaction monitoring and audit trail completeness across sales, income, and payroll tax categories. EU ViDA preparation is driving advisory and integration revenue among enterprises with continental operations.
- CPA Firms:Automation penetration already exceeds threshold levels in this maturing segment, with firms unbundling software procurement from high-margin consulting services. The largest United States practices have established captive technology procurement functions independent of traditional reseller channels.
- Small Businesses:Price-sensitive adopters favor lightweight rate-lookup services over full-lifecycle compliance platforms.
- Freelancers:Sole proprietors and gig economy workers remain underserved by pricing models designed for corporate volume tiers.
Corporations command the highest revenue per seat. Freelancers represent the most underpenetrated expansion opportunity.
Service Type:
Margin concentration shifts from implementation toward recurring maintenance as markets mature.
- Consulting:Jurisdictional expertise combined with API architecture skills commands compensation premiums that compress margins, yet remains essential for complex indirect tax regimes like India's GST reconciliation protocols.
- Implementation:Rule-engine customization for Saudi Arabia's ZATCA e-invoicing phases and Brazil's Nota Fiscal Eletrônica creates sustained project demand. This segment is climbing the fastest as real-time compliance mandates force wholesale system replacements.
- Support:Tiered response commitments differentiate vendor positioning in enterprise procurement cycles.
- Maintenance:Perpetual subscription upgrades address US state and local jurisdictions' annual rate table volatility.
Implementation services dominate near-term revenue. Maintenance subscriptions anchor long-term vendor relationships.
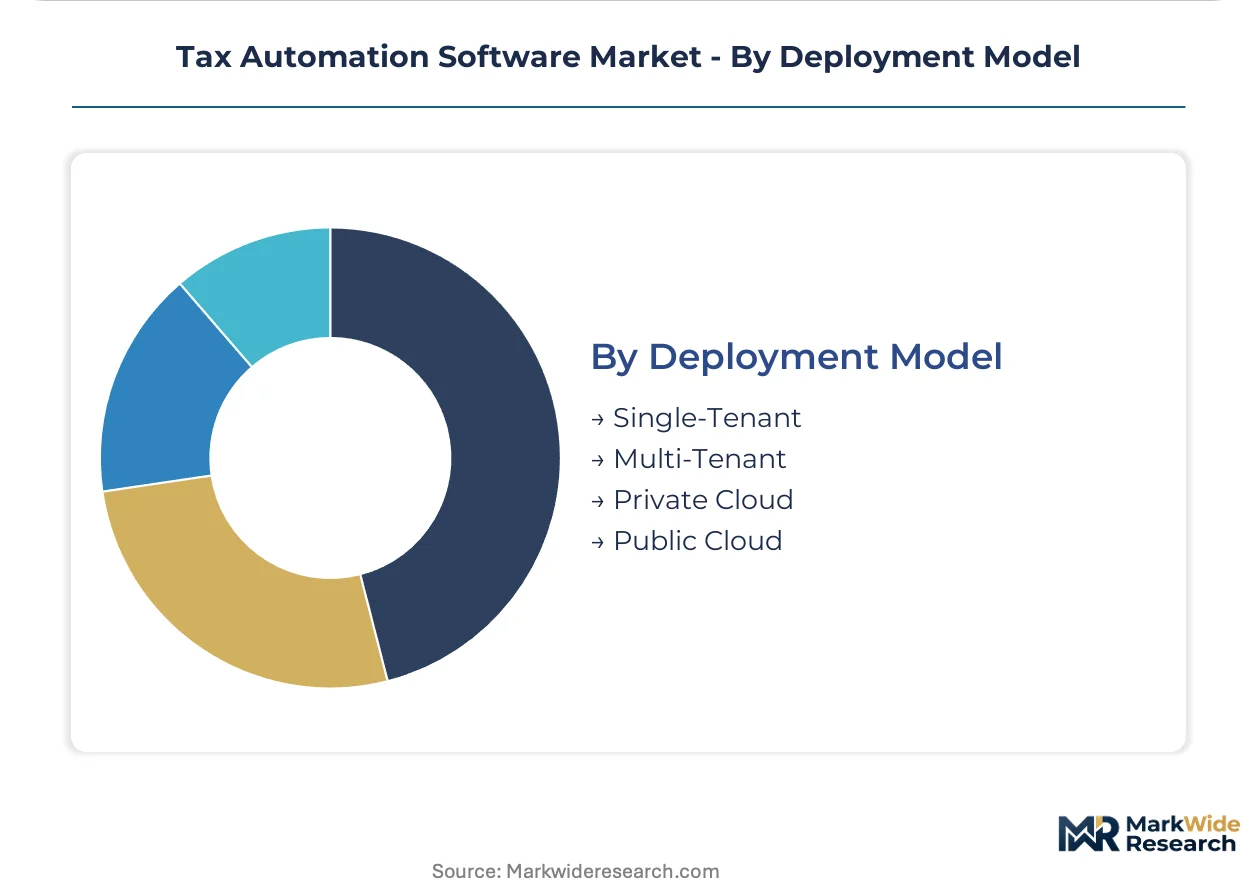
Deployment Model:
Infrastructure configuration directly determines data residency compliance and platform economics.
- Multi-Tenant:Shared architectures drive per-seat economics below on-premise total cost of ownership, though German and French data localization requirements clash with these platform economics and force expensive regional infrastructure duplication.
- Private Cloud:Dedicated instances satisfy financial services data security requirements without full on-premise capital expenditure. ISO 27001 certification costs of $50,000-$150,000 annually disqualify smaller vendors from enterprise procurement cycles.
- Single-Tenant:Isolated environments persist in highly regulated industries with bespoke compliance requirements.
- Public Cloud:Standardized instances serve volume segments through API-native consumption models.
Multi-tenant configurations dominate new bookings. Private cloud is gaining share fastest among regulated industries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Digital-first enforcement postures and real-time compliance mandates are concentrating tax automation demand across jurisdictions with the most aggressive regulatory timelines. Enterprises prioritize vendors with proven architectures for continuous calculation and sub-second validation against national tax authority servers.
United States
Mid-market corporations are accelerating replacement of on-premise ERP tax modules with API-native SaaS platforms. The IRS mandates e-filing thresholds and digital record-keeping standards that compel software upgrades among filers with revenues above specified thresholds. CPA firms in New York and California have established captive technology procurement functions independent of traditional reseller channels.
Germany
Enterprises face the earliest EU ViDA compliance deadlines and are currently driving pilot program demand for continuous data streaming architectures. German data localization requirements clash with multi-tenant cloud economics and force expensive regional infrastructure duplication. Industrial manufacturers in Bavaria and Baden-Württemberg are rebuilding batch-oriented engines for real-time invoice validation.
United Kingdom
Post-Brexit regulatory divergence is creating bespoke implementation demand for hybrid UK-EU compliance workflows. HMRC's Making Tax Digital program compels quarterly digital reporting that reshapes product roadmaps for vendors serving British accounts. London-based financial services firms are procuring private cloud instances to satisfy data security requirements.
Brazil
The Nota Fiscal Eletrônica mandate forces enterprises to adopt automated tax engines that validate transactions at the point of issuance. State-level revenue agencies enforce reconciliation protocols that drive sustained demand for rule-engine customization services. São Paulo-based conglomerates are deploying continuous calculation architectures across procurement and sales workflows.
India
GST reconciliation protocols enforced by state revenue agencies create implementation service demand for complex indirect tax regimes. Mid-market corporations are migrating from manual reconciliation to automated engines that process millions of jurisdictional rate combinations. Technology services clusters in Karnataka and Maharashtra are building specialized tax technologist capabilities.
Tax Automation Software Market Key Industry Players
Player mix skews toward cloud-native SaaS specialists and legacy workflow-integrated conglomerates, with ISO 27001 certification costs collapsing the competitive field below the enterprise tier. The vendor base separates into three strategic archetypes: API-first rate engines serving e-commerce marketplaces, full-lifecycle compliance platforms for Fortune 500 tax departments, and unbundled calculation tools for CPA firm procurement functions. Dominant competitive moves include strategic partnerships with systems integrators and geographic expansion through regional advisory partnerships.
Within the cloud-native tier, Avalara and TaxJar exemplify the API-first archetype serving volume-driven e-commerce channels. Thomson Reuters Corporation anchors the workflow-integrated conglomerate position through deep legal and accounting system entanglements. Sovos Compliance occupies a specialized regulatory reporting niche for complex indirect tax regimes. These three entities collectively represent the competitive positioning spectrum from lightweight rate-lookup services through full-lifecycle enterprise platforms.
| Leading Market Players |
|---|
| Avalara |
| Vertex Inc. |
| Wolters Kluwer |
| Intuit Inc. |
| Thomson Reuters Corporation |
| H&R Block Inc. |
| Sovos Compliance |
| TaxJar |
| Drake Software |
| Others |
Cost & Logistics Intelligence
Multi-tenant cloud architectures in tax automation software achieve sub-second latency at marginal cost near zero, compressing price floors for volume-tier subscriptions while elevating premiums for single-tenant and private-cloud deployments. This scale asymmetry concentrates supply-side power among SaaS-native vendors with established API marketplaces, forcing regional competitors toward specialized implementation services or exit.
Pricing Analysis
Certification level creates the primary spread between vendor tiers, with ISO 27001-compliant platforms commanding enterprise procurement access while uncertified alternatives compete solely on price in the mid-market. Subscription SaaS models dominate, stratifying across premium private-cloud instances, standard multi-tenant seats, and economy-tier rate-lookup APIs. Price erosion runs through the mid-market as Avalara and TaxJar compress per-seat economics below legacy on-premise total cost of ownership. Freelancers and sole proprietors exhibit highest price sensitivity, whereas Fortune 500 tax departments prioritize audit-trail completeness over cost.
Supply Chain Analysis
Just-in-time rate table updates characterize vendor inventory strategy, with cloud-native platforms pushing jurisdictional changes to production environments within hours rather than batch quarterly releases. Software development concentrates in the United States, Ireland, and India, with implementation services anchored in regional hubs serving EU ViDA preparation and Saudi ZATCA compliance. The supply chain draws from specialized tax technologists combining jurisdictional expertise with API architecture skills, creating single-source vulnerability for complex rule-engine customization. Distribution runs through direct vendor sales, API marketplaces, and systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tax automation software functions as a service-attach business where implementation and maintenance subscriptions expand faster than core calculation engine licenses. Recurring-revenue depth separates sustainable vendors from transactional competitors.
For Market Incumbents: Fortify cloud-native architecture advantages through deeper embedding into procurement and sales workflows, displacing batch-oriented ERP modules before legacy vendors complete roadmap pivots. Prioritize ISO 27001 certification maintenance to preserve enterprise procurement access against emerging API-first challengers. Defensive consolidation around specialized tax technologist talent pools protects implementation margin compression.
For New Entrants and Emerging Players: ISO 27001 fast-track programs offer the swiftest path to enterprise procurement qualification, bypassing the certification cost barrier that excludes regional competitors. Freelancers and gig economy workers in the United States represent the most penetrable white-space segment, currently underserved by volume-tier pricing models. API-native self-serve onboarding with transparent per-transaction economics captures price-sensitive adopters abandoned by incumbent complexity.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native SaaS specialists with established multi-tenant platforms and API marketplace distribution. Long-term viability across the projection horizon favors vendors with proven continuous-calculation architectures for real-time compliance mandates. Acquisition target archetypes include specialized regulatory reporting firms with entrenched indirect tax expertise and emerging AI-powered audit defense capabilities. Watch EU member state ViDA implementation timelines as inflection indicator for continental expansion returns.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding tax determination into SAP and Oracle workflows captures ERP-dependent enterprises. |
| Geographic Expansion | Regional infrastructure duplication in Germany and France satisfies data localization requirements. |
| Strategic Partnership | Systems integrator alliances accelerate enterprise implementation timelines from quarters to weeks. |
| Product Launch | AI-powered audit defense tools occupy unoccupied space between basic filing and full-service representation. |
| Acquisition of Specialist Firm | Regulatory reporting expertise for India's GST protocols builds indirect tax complexity moats. |
Research Approach
Findings reconcile primary fieldwork against secondary review of SEC filings, IRS enforcement guidance, EU ViDA framework documents, and national tax authority e-invoicing mandates. Primary interviews engaged CTOs at mid-market corporations, IT procurement officers at CPA firms, platform engineers at SaaS vendors, and integration specialists at systems integrators. Secondary validation drew from customs data on software imports, hyperscaler capex disclosures, and regulatory filing databases. Bottom-up sizing of vendor bookings triangulates against top-down estimates of corporate tax department spending across deployment models.
Segmentation dimensions modeled include deployment architecture, organization size, vertical industry, integration complexity with existing ERP systems, and regional regulatory adoption pattern. CAGRs derive from trend extrapolation of e-filing mandate expansion, cloud migration velocity, and real-time compliance requirement penetration. Industry-specific forecast inputs incorporate IRS digital-first enforcement posture timelines and EU member state ViDA staggered implementation schedules across the analysis window.
Underlying assumptions cover sustained regulatory pressure toward continuous transaction monitoring, with deviation risk concentrated in legacy ERP entrenchment extending replacement cycles beyond typical refresh timelines. Forecasts reflect these conditions without claiming predictive certainty. Revision becomes warranted when cloud migration velocity among mid-market filers crosses thresholds that accelerate or decelerate platform consolidation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accounting and Taxation Services
UAE Accounting Software Market
Accounting and Taxation Services
Tax Management Software Market
Accounting and Taxation Services
Global Fund Accounting Software Market
Accounting and Taxation Services
Finance and Accounting Outsourcing (FAO) Market
Accounting and Taxation Services
Europe Accounting Software Market
Accounting and Taxation Services
Crypto Tax Software Market
Accounting and Taxation Services
Construction Accounting Software Market
Accounting and Taxation Services
Australia Accounting Software Market
Accounting and Taxation Services
Bookkeeping Services Market
Accounting and Taxation Services
Integrated Accounting Software Market
Accounting and Taxation Services
Europe Auditing Services Market
Accounting and Taxation Services
Accounting and Budgeting Software Market
Accounting and Taxation Services
Argentina Accounting Software Market
Accounting and Taxation Services
South Africa Forensic Accounting Market
Accounting and Taxation Services
Small Business Accounting Software Market
Accounting and Taxation Services
Global Accounting Finance Market