
 Honey Spread Market | 2026-2036
Honey Spread Market Size, Share, and Industry Trends Forecast 2026-2036
Honey Spread Market Analysis
The bakery and confectionery sector is pivoting toward honey-based formulations as clean-label mandates intensify. Dabur Ltd. leverages its Ayurvedic heritage to anchor premium positioning in South Asian export markets. Sioux Honey Association Co-op sustains cooperative-scale procurement across North American clover and wildflower territories. Comvita Limited specializes in manuka-derived spreads, commanding differentiated shelf presence through UMF certification.
Honey spread denotes a viscous, pumpable or spreadable preparation of crystallized or emulsified honey, often blended with butter, fruit concentrates, or stabilizers to achieve a creamy, non-drip consistency at ambient temperatures; manufacturers control moisture content below 18 percent and manage glucose-fructose ratios to inhibit re-liquefaction, serving both direct consumption and industrial recipe integration. Organic honey and creamed honey categories attract margin concentration as certification premiums offset volatile apiary input costs. Breakfast spreads and baking ingredients applications dominate volume throughput, though snack additives show accelerated channel placement in grab-and-go retail formats.
The FDA enforces identity standards for honey and honey products under 21 CFR 101.80, while the EU Green Deal and REACH frameworks pressure importers on carbon footprint disclosure and pesticide residue thresholds. Health Canada and Australia's TGA maintain parallel purity benchmarks that shape export eligibility for non-domestic suppliers. Stakeholders must monitor evolving pollinator health regulations and origin verification protocols to secure long-term supply agreements and retail listings.
Market Dynamics
The EU Green Deal's carbon footprint disclosure mandates are forcing honey spread manufacturers to restructure procurement networks and invest in traceable apiary partnerships. REACH pesticide residue thresholds and evolving origin verification protocols now determine which suppliers retain shelf access in European retail channels.
Growth Catalysts
- Clean-label bakery reformulation:Industrial bakers in Germany and France are replacing invert syrups with honey-based binders to meet EU-wide front-of-pack labeling requirements. This substitution pulls volume through foodservice distribution.
- REACH framework compliance:The EU's chemical safety regulations are screening out adulterated honey inputs, creating protected market space for certified pure suppliers who can document residue testing.
- Manuka UMF certification premiums:New Zealand and Australian apiary cooperatives are capturing margin concentration through medical-grade honey spreads positioned in pharmacy and wellness retail channels.
Market Restraints
- Apiary input cost volatility:Colony collapse disorder and varroa mite infestations in North American clover territories are compressing raw honey yields and inflating contract prices for processors.
- Substitution by date and agave syrups:Vegan bakery formulations and plant-based breakfast spreads are displacing honey in price-sensitive private-label SKUs across German discount retail.
- Moisture control technical barriers:Maintaining sub-18% moisture content without thermal degradation requires capital-intensive vacuum evaporation systems that exclude smaller regional blenders.
Strategic Opportunities
- Grab-and-go snack channel expansion:Single-serve honey spread sachets are penetrating convenience retail in Australian metropolitan corridors, displacing jam portions in airline and hotel foodservice contracts.
- Ayurvedic export positioning:South Asian diaspora populations in the United Kingdom and Canada are creating demand for turmeric- and ashwagandha-infused honey spreads through ethnic grocery networks.
- EU Green Deal carbon labeling:Early adopters of blockchain-tracked apiary sourcing are securing preferential listings in Carrefour and REWE sustainability-tier planograms.
Industry Challenges
- Pollinator health compliance timelines:Germany's national pollinator strategy and parallel state-level apiary registration requirements are extending supplier qualification cycles by 8-14 months.
- Crystallization control R&D gaps:Managing glucose-fructose ratios for ambient-stable creamed honey requires food science expertise that concentrates in legacy European and Australian processing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Honey Spread Market |
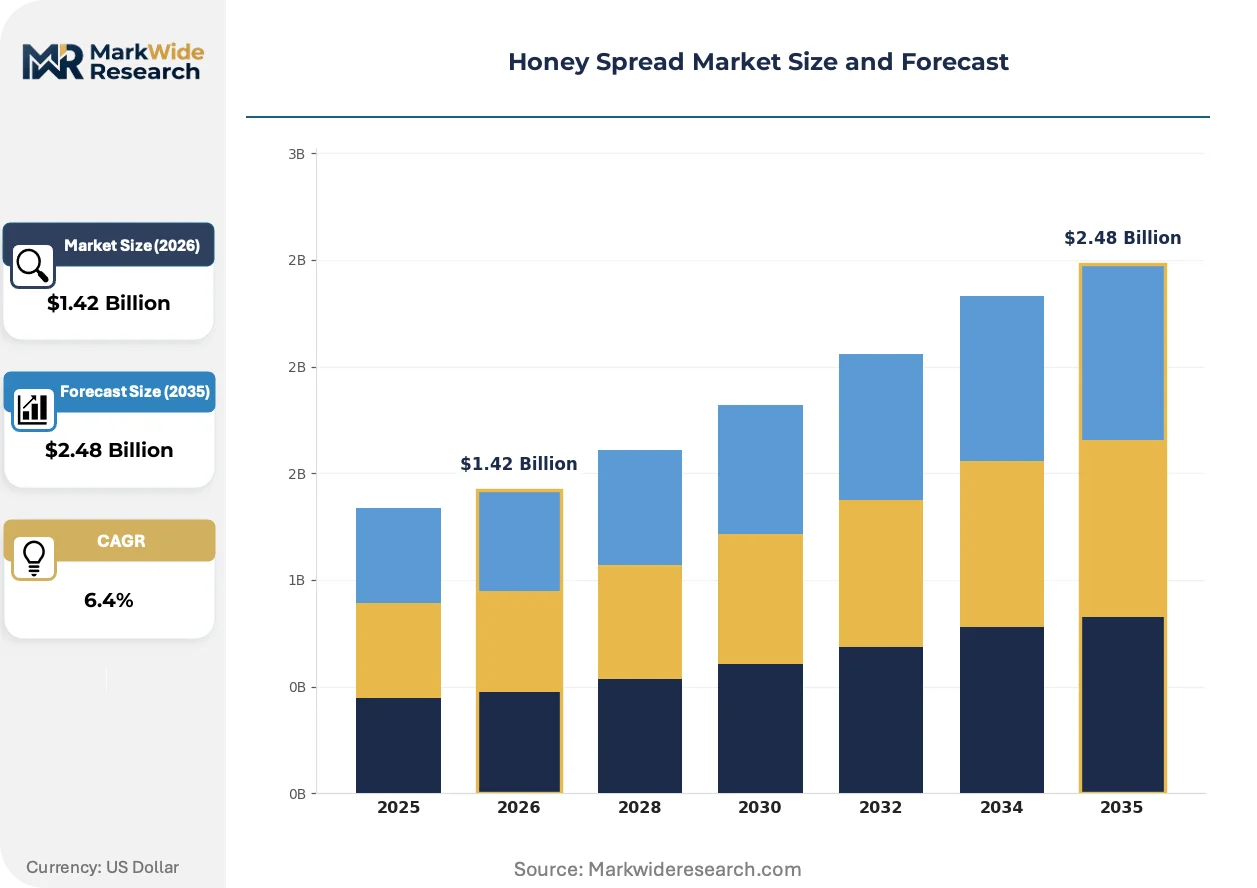
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Honey, Flavored Honey, Raw Honey, Creamed Honey Application: Breakfast Spreads, Snack Additives, Baking Ingredients, Sauces Packaging Type: Glass Jars, Plastic Containers, Squeeze Bottles, Sachets Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Shops |
| Companies Covered | Dabur Ltd., Dutch Gold Honey Inc., Sioux Honey Association Co-op, Bee Maid Honey Limited, Nature Nate’s Honey Co., Comvita Limited, Honey-Butter Products Co Inc., Capilano Honey Ltd., Hive and Wellness Australia Pty Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Honey Spread Market Emerging Trajectories
Reformulation chemistry and packaging engineering are converging to extend honey spread shelf stability without refrigeration. These technical advances are unlocking placement in ambient retail formats previously reserved for synthetic preserves.
Crystallization seeding technology using controlled glucose nucleation is expanding into industrial-scale production lines. North American co-manufacturers serving private-label breakfast brands are retrofitting existing jam facilities with temperature-cycled conditioning tanks. This equipment migration is compressing capital barriers for mid-tier processors seeking clean-label positioning.
REACH authorization requirements for food-contact substances are tightening specifications on stabilizers and emulsifiers permitted in EU-bound honey spreads. Manufacturers are reformulating with fruit pectin and native honey proteins to maintain pumpable viscosity without synthetic additives. German and Dutch importers are now requiring full substance inventory disclosure from Asian contract manufacturers.
Health food channel buyers are consolidating supplier relationships around multi-certification holders who can deliver organic, kosher, and non-GMO verification in single SKUs. This preference compression is marginalizing single-certification regional apiaries in United States natural retail. Australian manuka specialists with integrated UMF-ISO 17025 laboratory capacity are capturing expanded shelf sets in Sprouts and Whole Foods Market.
Honey Spread Market Segmentation
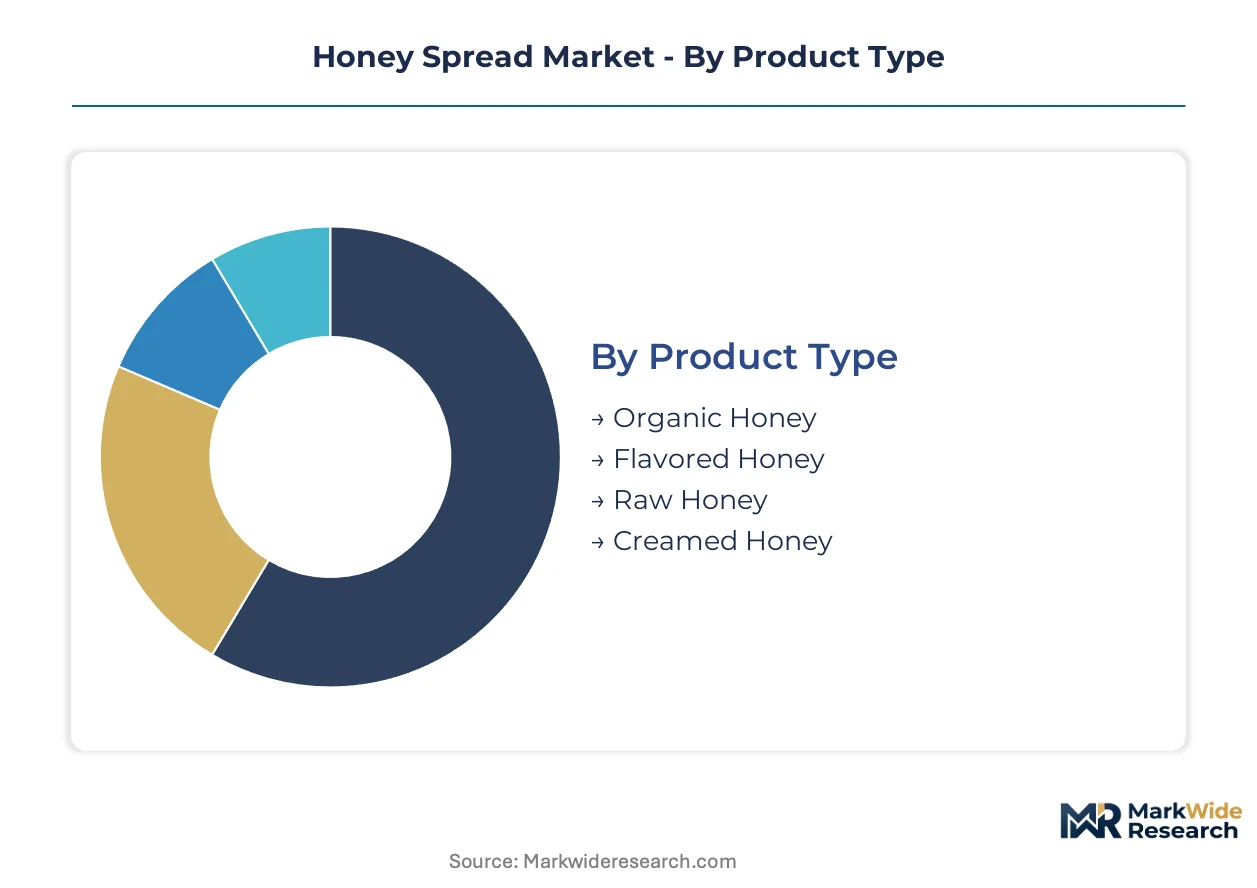
Honey spread manufacturers configure product portfolios across four intersecting dimensions. Specification chemistry, packaging engineering, and channel access determine margin capture and shelf placement viability.
Product Type:
Composition standards and certification premiums define the technology axis for honey spread differentiation.
- Organic Honey:Sourced from apiaries meeting USDA Organic or EU organic standards, with prohibition of synthetic pesticides within forage zones. German and Australian health food channels concentrate demand as EFSA tightens residue testing protocols.
- Flavored Honey:Infused with fruit concentrates, spices, or botanical extracts to achieve differentiated taste profiles. Breakfast spread applications in US natural retail are displacing conventional jams through turmeric-ginger and cinnamon formulations.
- Raw Honey:Unpasteurized preparation retaining native enzyme activity and pollen content. Wellness-positioned SKUs in Canadian specialty shops command certification premiums despite shorter shelf stability windows.
- Creamed Honey:Controlled crystallization produces pumpable, non-drip consistency at ambient temperatures. Industrial bakers in France specify this grade for clean-label binding applications.
Organic honey leads on scale; flavored honey leads on momentum.
Application:
End-use specifications determine viscosity requirements, moisture thresholds, and packaging formats.
- Breakfast Spreads:Tabletop consumption drives single-serve portion demand and premium jar positioning. Australian metropolitan retail and UK ethnic grocery networks concentrate volume for Ayurvedic-infused variants.
- Snack Additives:Sachet and portion-pack formats penetrate convenience retail, airline catering, and hotel foodservice contracts. Grab-and-go placement in Sydney and Melbourne corridors is displacing synthetic preserves.
- Baking Ingredients:Industrial-scale supply to German and French commercial bakeries requires bulk pail or drum packaging with documented glucose-fructose ratios for crystallization control.
- Sauces:Viscous honey-based glazes and marinades serve foodservice and CPG manufacturing. REACH-compliant stabilizer formulations are mandatory for EU-bound industrial shipments.
Baking ingredients lead on scale; snack additives expand most quickly.
Packaging Type:
Material selection and format engineering shape shelf stability, shipping economics, and retail channel access.
- Glass Jars:Premium positioning in specialty retail and gift segments leverages perceived purity and recyclability. German REWE and Carrefour sustainability-tier planograms prioritize this format.
- Plastic Containers:Lightweight, shatter-resistant packaging dominates mass retail and foodservice bulk applications. Cost efficiency supports private-label SKUs in US supermarket channels.
- Squeeze Bottles:Controlled-dispense engineering reduces drip waste in household and foodservice settings. North American co-manufacturers are retrofitting jam lines for this format.
- Sachets:Single-serve portions penetrate convenience retail, travel hospitality, and institutional catering. Australian grab-and-go corridors show steepest placement expansion.
Glass jars lead on scale; sachets lead on momentum.
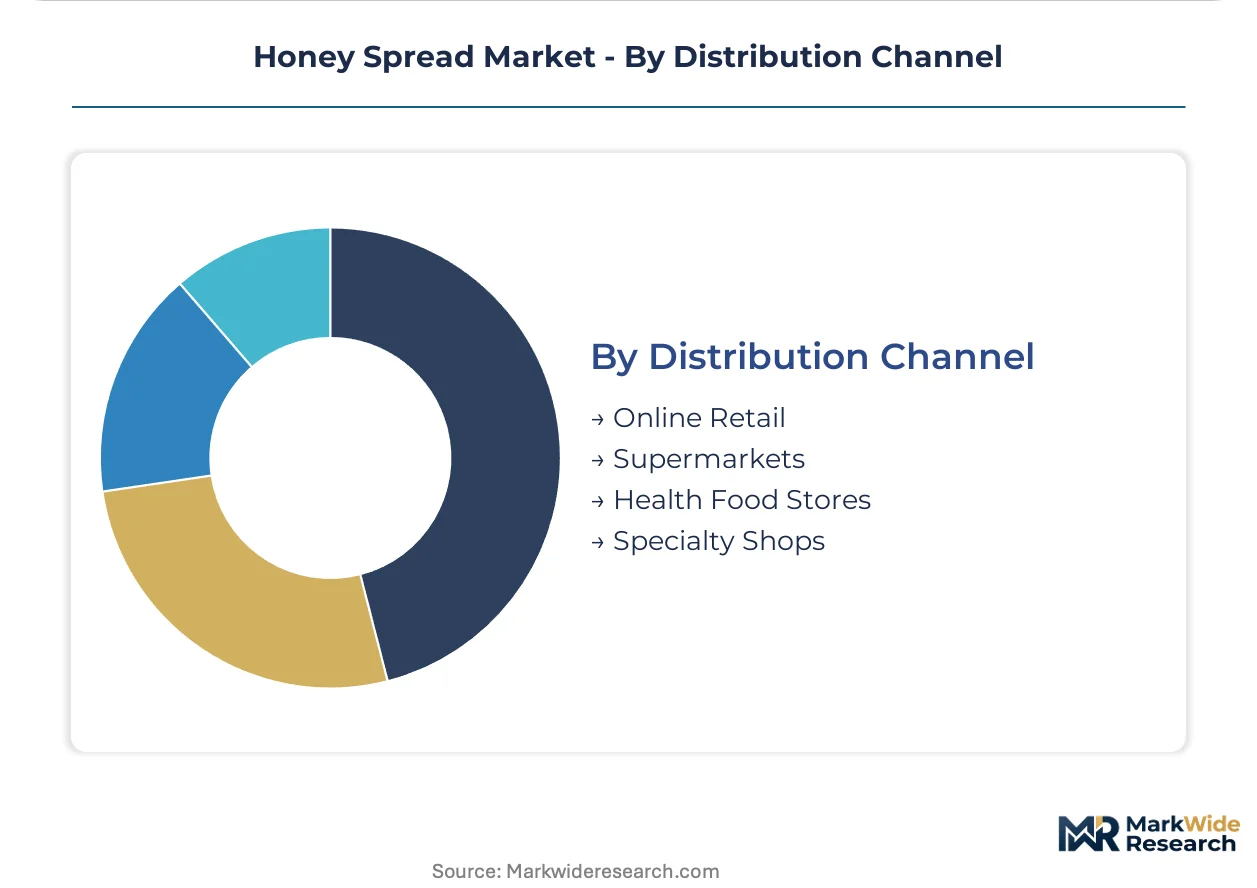
Distribution Channel:
Channel configuration determines certification requirements, margin structure, and supplier qualification timelines.
- Online Retail:Direct-to-consumer platforms enable subscription models and SKU proliferation for specialty variants. US and UK wellness demographics concentrate purchase behavior.
- Supermarkets:Mass retail placement requires scale capacity, promotional funding, and front-of-pack labeling compliance. German discount retail is consolidating around multi-certification suppliers.
- Health Food Stores:Sprouts and Whole Foods Market in the US, plus independent natural retailers, demand organic, non-GMO, and kosher verification bundles.
- Specialty Shops:Ethnic grocery networks in Canada and the UK serve South Asian diaspora demand for Ayurvedic-infused spreads. Smaller format supports premium pricing.
Supermarkets lead on scale; online retail leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping honey spread production geography as REACH compliance costs in Europe push processing investment toward jurisdictions with lower residue-testing burdens. Manufacturers are relocating crystallization-control operations to Australia and North America while maintaining EU market access through certified export facilities.
Germany
Clean-label bakery reformulation drives industrial honey spread demand as commercial bakers replace invert syrups to meet front-of-pack labeling requirements. The EU Green Deal's carbon footprint disclosure mandates force importers to document apiary sourcing through blockchain-tracked partnerships. Processing clusters concentrate in North Rhine-Westphalia where vacuum evaporation facilities serve pan-European distribution.
United States
Health food channel consolidation around multi-certification suppliers concentrates procurement power in Sprouts and Whole Foods Market networks. FDA identity standards under 21 CFR 101.80 shape formulation protocols for domestic and export-bound production. Clover and wildflower apiary territories across the Dakotas and Montana supply cooperative-scale processors with raw inputs.
Australia
Manuka UMF certification commands pharmacy and wellness retail premiums as medical-grade honey spreads penetrate export channels. TGA purity benchmarks align with Health Canada requirements to secure North American market eligibility. Metropolitan Sydney and Melbourne corridors show steepest grab-and-go sachet placement expansion in convenience retail.
United Kingdom
South Asian diaspora populations create demand for Ayurvedic-infused spreads through ethnic grocery networks in London and Birmingham. Post-Brexit origin verification protocols extend supplier qualification timelines for EU-sourced honey inputs. REWE sustainability-tier planogram access requires German-export-compliant certification bundles.
Canada
Wellness-positioned raw honey SKUs command certification premiums in Toronto and Vancouver specialty shops despite shorter shelf stability windows. Health Canada parallel purity benchmarks shape export eligibility for domestic processors serving US natural retail. Prairie province apiaries supply Bee Maid Honey cooperative processing infrastructure.
Honey Spread Market Vendor Landscape
Portfolio diversification dominates the current landscape as manufacturers hedge against apiary input volatility through multi-origin sourcing contracts and certification stacking. The vendor base stratifies across three tiers: legacy cooperative-scale processors with captive apiary networks, mid-tier private-label co-manufacturers retrofitting jam facilities, and premium manuka specialists with integrated laboratory capacity. Strategic archetypes include Ayurvedic heritage anchors, UMF-certified medical-grade positioning, and clean-label industrial ingredient suppliers. M&A activity concentrates on crystallization-control technology acquisition, while geographic expansion targets South Asian diaspora corridors in Canada and the UK.
Within the cooperative-scale tier, Sioux Honey Association Co-op exemplifies North American clover territory aggregation, while Bee Maid Honey Limited anchors Canadian prairie province supply security. Comvita Limited occupies the premium medical-grade position through manuka specialization. These three represent distinct competitive vectors: cooperative procurement scale, national supply security, and certification-driven margin capture.
| Leading Market Players |
|---|
| Dabur Ltd. |
| Dutch Gold Honey Inc. |
| Sioux Honey Association Co-op |
| Bee Maid Honey Limited |
| Nature Nate's Honey Co. |
| Comvita Limited |
| Honey-Butter Products Co Inc. |
| Capilano Honey Ltd. |
| Hive and Wellness Australia Pty Ltd. |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between UMF-certified manuka and commodity clover honey manifests in parallel supply chain configurations: premium tiers anchor to New Zealand and Australian apiary partnerships with integrated laboratory capacity, while standard grades source through North American cooperative networks serving German discount retail under REACH residue thresholds.
Pricing Analysis
Retailer markup layers compress margins most severely in German mass retail, where REWE and Carrefour sustainability-tier placement demands blockchain-tracked provenance documentation. Three-tier pricing structure across premium, standard, and economy levels separates UMF-certified pharmacy-channel SKUs from private-label breakfast spreads and foodservice bulk pails. Cost compression in commodity clover honey intensifies because colony collapse disorder in Dakotas and Montana territories inflates contract prices. Price-sensitive private-label buyers in German discount channels drive substitution toward date and agave syrups, while wellness-positioned consumers in Australian health food stores absorb certification premiums without volume elasticity.
Supply Chain Analysis
Regional distribution centers in North Rhine-Westphalia serve as the primary hub-and-spoke pattern for EU-bound crystallized honey, with satellite facilities in Sydney and Toronto managing Asia-Pacific and North American fulfillment. Geographic supply concentrates in New Zealand, Australia, and the United States, with raw inputs drawing from prairie province apiaries, manuka territories, and clover-rich Dakotas-Montana zones. Supply chain risk hinges on single-source vulnerability for UMF-certified manuka, where TGA laboratory capacity constraints limit qualified processor expansion. Distribution runs through cooperative-scale aggregation for standard grades and direct-apiary contracting for premium tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Honey spread functions as a stable compounder anchored by clean-label bakery reformulation mandates that permanently embed honey-based binders in EU commercial baking specifications.
For Market Incumbents: Hedge against apiary input volatility through multi-origin sourcing contracts spanning Australian manuka, North American clover, and South Asian floral territories. Backward integration into captive apiary networks in varroa-mite-resistant geographies defends margin position against yield compression. Certification stacking—combining organic, kosher, and non-GMO verification—secures shelf access as Sprouts and Whole Foods Market consolidate supplier relationships. For New Entrants and Emerging Players: Crystallization-seeding technology retrofit offers entry into mid-tier private-label manufacturing without capital-intensive vacuum evaporation buildout. White-space targets concentrate in Ayurvedic-infused spreads for UK and Canadian South Asian diaspora corridors, plus single-serve sachet formats for Australian grab-and-go convenience retail. Go-to-market execution should anchor to ethnic grocery network penetration with turmeric-ginger and ashwagandha formulations. For Investors and Strategic Acquirers: Consolidation pressure builds where crystallization-control R&D expertise concentrates in legacy European and Australian processing facilities with limited replication capacity. Long-term viability frames honey spread as a defensive consumer staple with pricing power in wellness-positioned channels. Acquisition targets should screen for integrated UMF-ISO 17025 laboratory infrastructure. Signal to monitor: German pollinator health compliance timeline extensions that extend incumbent supplier lock-in.| Strategic Initiative | Industry Significance |
|---|---|
| Crystallization Technology Acquisition | Retrofit legacy jam facilities with temperature-cycled conditioning tanks to capture clean-label bakery demand. |
| Blockchain-Tracked Apiary Partnership | Secure REWE and Carrefour sustainability-tier listings under EU Green Deal carbon disclosure mandates. |
| Ayurvedic Product Line Extension | Penetrate UK and Canadian ethnic grocery networks serving South Asian diaspora wellness preferences. |
| Single-Serve Sachet Format Launch | Displace synthetic preserves in Sydney and Melbourne convenience retail and airline catering contracts. |
| Multi-Certification Bundle Investment | Consolidate organic, kosher, and non-GMO verification to meet Sprouts and Whole Foods Market procurement standards. |
Methodological Framework
Multiple input streams — structured interviews with apiary cooperative managers and honey spread processors, regulatory filings from EFSA and FDA, and trade flow data from customs authorities — were reconciled to construct supply-side and demand-side estimates. Primary engagement encompassed plant managers at crystallization facilities, procurement leads at German commercial bakeries, category buyers at Australian health food retailers, and regulatory affairs specialists navigating REACH authorization. Secondary validation drew from EFSA residue testing protocols, FDA 21 CFR 101.80 identity standards, TGA purity benchmarks, and Health Canada parallel requirements. Bottom-up volume modeling triangulated against top-down category spend analysis.
Data-stream reconciliation anchored forecast construction across product type, application, packaging format, and distribution channel dimensions, with additional granularity on certification tier and geographic origin. CAGRs emerged from segmented growth trajectory analysis rather than single-point extrapolation. Industry-specific forecast inputs incorporated pollinator health compliance timeline projections, crystallization-seeding technology adoption curves, and clean-label bakery reformulation penetration rates across the projection horizon.
The model holds under stable regulatory enforcement of REACH residue thresholds and continued EU Green Deal carbon disclosure implementation; deviation in pollinator health crisis severity or synthetic stabilizer authorization reversals would shift volume and value trajectories. Forecasts reflect documented assumptions around apiary yield recovery patterns and certification premium sustainability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Middle East and Africa Yerba Mate Market
Specialty Foods
Vegetarian Taquitos Market
Specialty Foods
Global Freeze-Dried Pet Food Market
Specialty Foods
Luxury Cigar Market
Specialty Foods
Low Calorie Oatmeal Market
Specialty Foods
North America Hummus Market
Specialty Foods
Global Hispanic Foods Market
Specialty Foods
Low Calorie Hummus Market
Specialty Foods
Moringa Products Market
Specialty Foods
Fruit Dessert Market
Specialty Foods
Global Cordyceps Militaris Market
Specialty Foods
Chamomile Market
Specialty Foods
United States Tofu Market
Specialty Foods
Low Fat Hummus Market
Specialty Foods
Kelp Noodles Market
Specialty Foods
Low Calorie Desserts Market