
 Hadoop Market | 2026-2036
Hadoop Market Size, Share, and Industry Trends Forecast 2026-2036
Hadoop Market Intelligence
North America is fragmenting as enterprises rebalance on-premise Hadoop estates against cloud-native alternatives. Cloudera sustains relevance through its hybrid platform strategy spanning data centers and multiple public clouds. IBM Corporation leverages mainframe integration to anchor Hadoop workloads in regulated industries. Amazon Web Services competes aggressively with managed EMR services that reduce operational overhead for batch analytics pipelines.
Hadoop is an open-source distributed computing framework that processes petabyte-scale datasets across commodity server clusters using the Hadoop Distributed File System and MapReduce programming model for fault-tolerant parallel computation. Its primary commercial purpose centers on cost-effective storage and batch processing of unstructured data for enterprise analytics, machine learning feature engineering, and regulatory reporting workflows. The Deployment Model dimension shows Public Cloud and Hybrid Cloud configurations capturing the fastest expansion as organizations exit capital-intensive data center commitments, while On-Premise retains margin concentration in sectors with strict data residency requirements. Application Type segmentation reveals Analytics and Data Management commanding premium pricing due to integration complexity with business intelligence tools and governance frameworks.
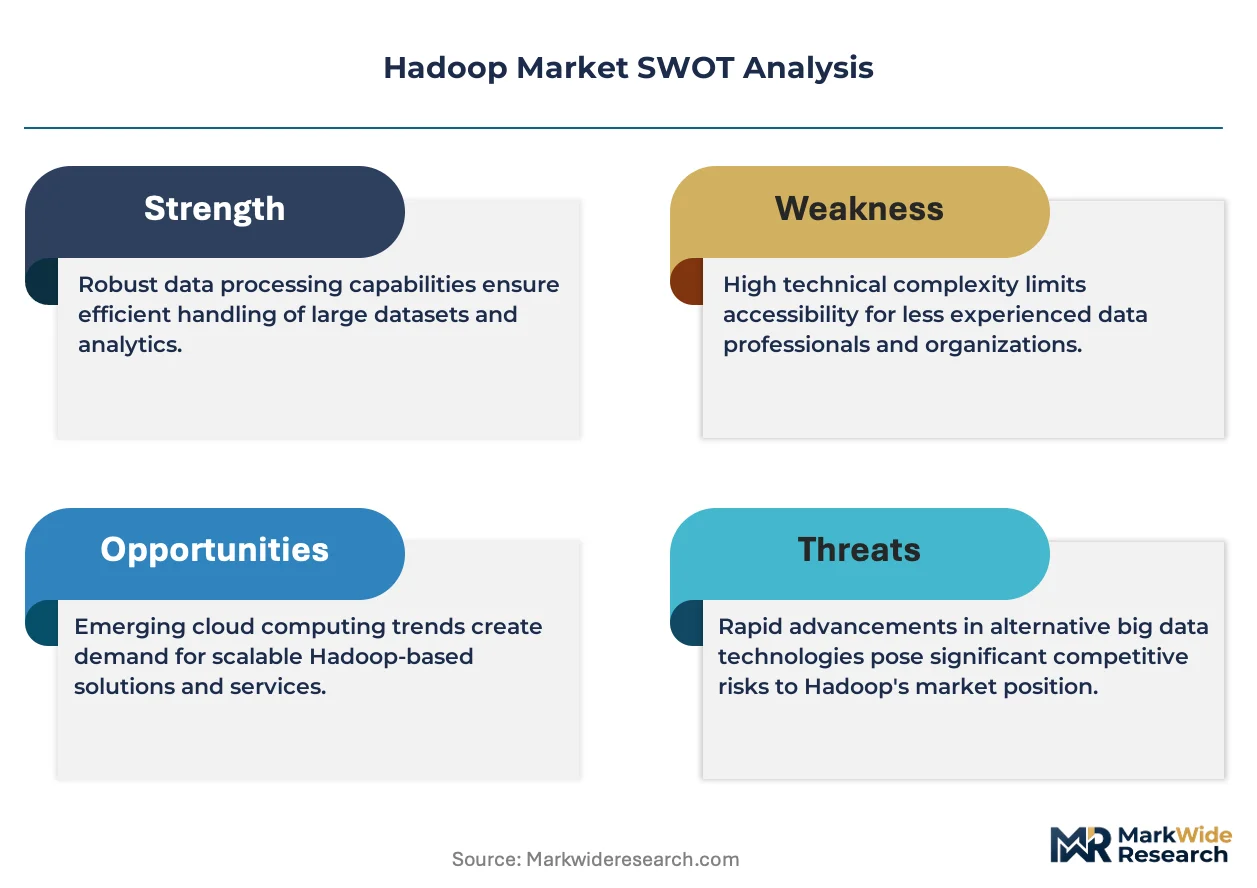
The EU AI Act and GDPR impose algorithmic transparency and data lineage requirements that reshape Hadoop deployments toward governed metadata layers and access audit trails. In the United States, HIPAA and SEC record-keeping rules drive healthcare and financial services firms toward HCatalog and Hive integrations that enforce column-level security and retention policies. Stakeholders must weigh cloud migration timelines against the sunk costs of existing MapReduce codebases and specialized operational expertise.
Market Dynamics
Cloud-native object storage architectures are fragmenting traditional Hadoop deployments as enterprises renegotiate data gravity trade-offs between latency and elasticity. This structural tension between sunk on-premise infrastructure and managed service alternatives defines current vendor positioning.
Growth Catalysts
- EU AI Act compliance mandates:Financial services firms in Germany and France are deploying governed Hadoop lakes to satisfy algorithmic auditability requirements. The regulation forces metadata lineage investments that reinforce ecosystem stickiness.
- Healthcare analytics pipelines:HIPAA-covered entities in the United States are expanding HCatalog implementations for patient record retention and de-identification workflows. Batch processing of clinical imaging archives drives cluster expansion.
- Feature engineering for machine learning:Technology firms are repurposing existing MapReduce clusters for structured data preparation feeding TensorFlow and PyTorch pipelines. This reuse defers cloud migration costs.
Market Restraints
- Specialized talent scarcity:MapReduce optimization expertise concentrates among aging practitioner cohorts with limited pipeline replenishment. Universities have shifted curricula toward Spark and cloud-native alternatives.
- Object storage substitution:Amazon S3, Azure Data Lake Storage, and Google Cloud Storage are capturing net-new unstructured data workloads. These services eliminate HDFS maintenance overhead.
- Data center cost structures:Power, cooling, and server refresh cycles impose fixed cost burdens that cloud variable pricing undercuts. CFOs are applying hurdle rates that favor operating expense treatment.
Strategic Opportunities
- India's data localization requirements:The RBI and CERT-In directives are forcing multinational banks to maintain in-country Hadoop estates. Domestic systems integrators are capturing deployment and managed services contracts.
- Convergence with Kubernetes orchestration:Containerized Hadoop distributions are enabling elastic scaling patterns previously exclusive to cloud-native architectures. This hybrid posture extends on-premise asset lifecycles.
- SEC climate disclosure rules:Asset managers are building Hadoop-based data lakes for portfolio carbon footprint calculations. Alternative data ingestion from satellite imagery and supply chain sensors creates new workload categories.
Industry Challenges
- Version fragmentation across distributions:Cloudera CDP, Hortonworks HDP, and Apache trunk divergence complicates patch management and security compliance. Operations teams maintain parallel skill sets.
- Spark migration execution risk:Rewriting production MapReduce jobs demands scarce Scala and Python data engineering capacity. Business-critical batch windows tolerate minimal regression.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hadoop Market |
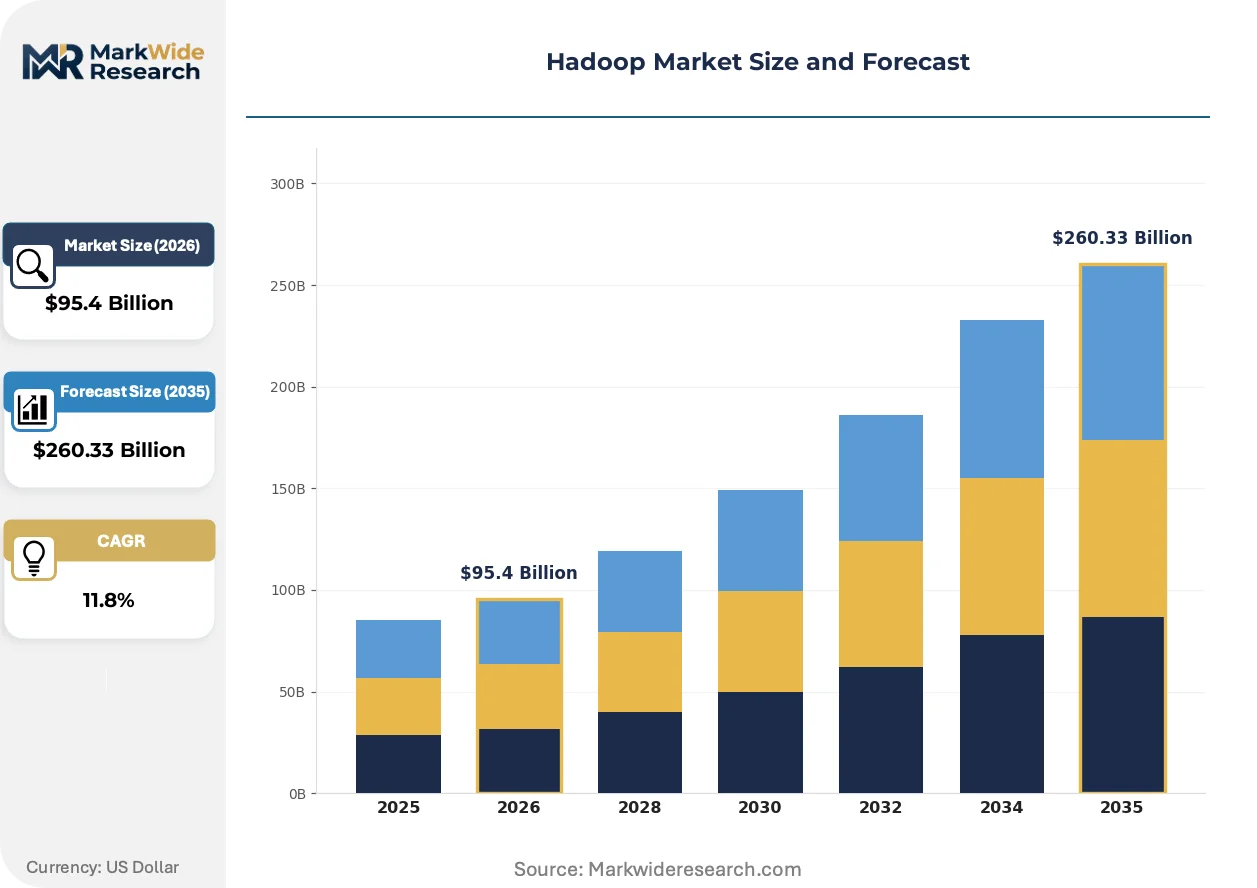
| Market Size in 2026 | $95.4 Billion |
| Market Size in 2035 | $260.33 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premise, Public Cloud, Private Cloud, Hybrid Cloud Application Type: Data Processing, Data Storage, Analytics, Data Management End User: Banking, Telecommunications, Retail, Healthcare Component: Hadoop Distributed File System, MapReduce, HCatalog, Hive |
| Companies Covered | IBM Corporation, Hortonworks, Cloudera, SAS Institute Inc., Oracle Corporation, Amazon Web Services (AWS), Microsoft Corporation, Databricks, MapR Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hadoop Market Strategic Shifts & Innovations
Query engine unification is collapsing the architectural separation between Hadoop batch processing and interactive analytics. Vendors are racing to deliver converged platforms that eliminate ETL latency between storage layers.
Apache Iceberg table formats are rendering obsolete the Hive metastore dependency for schema evolution and time-travel queries. Cloud-native data platform teams at technology firms are adopting Iceberg as the default lakehouse abstraction. This migration is compressing vendor differentiation around proprietary catalog implementations.
The EU AI Act's risk classification framework is mandating documentation standards for training data provenance. Enterprises deploying machine learning on Hadoop clusters must implement automated lineage capture through Apache Atlas or commercial alternatives. Healthcare and financial services verticals in France and Germany are front-loading compliance investments ahead of enforcement deadlines.
Consumption-based pricing for managed Hadoop services is displacing perpetual license models among mid-market buyers. Procurement functions are negotiating committed use discounts against autoscaling elasticity guarantees. This shift is most visible among software-as-a-service vendors in the United States optimizing unit economics for multi-tenant analytics products.
Hadoop Market Segmentation
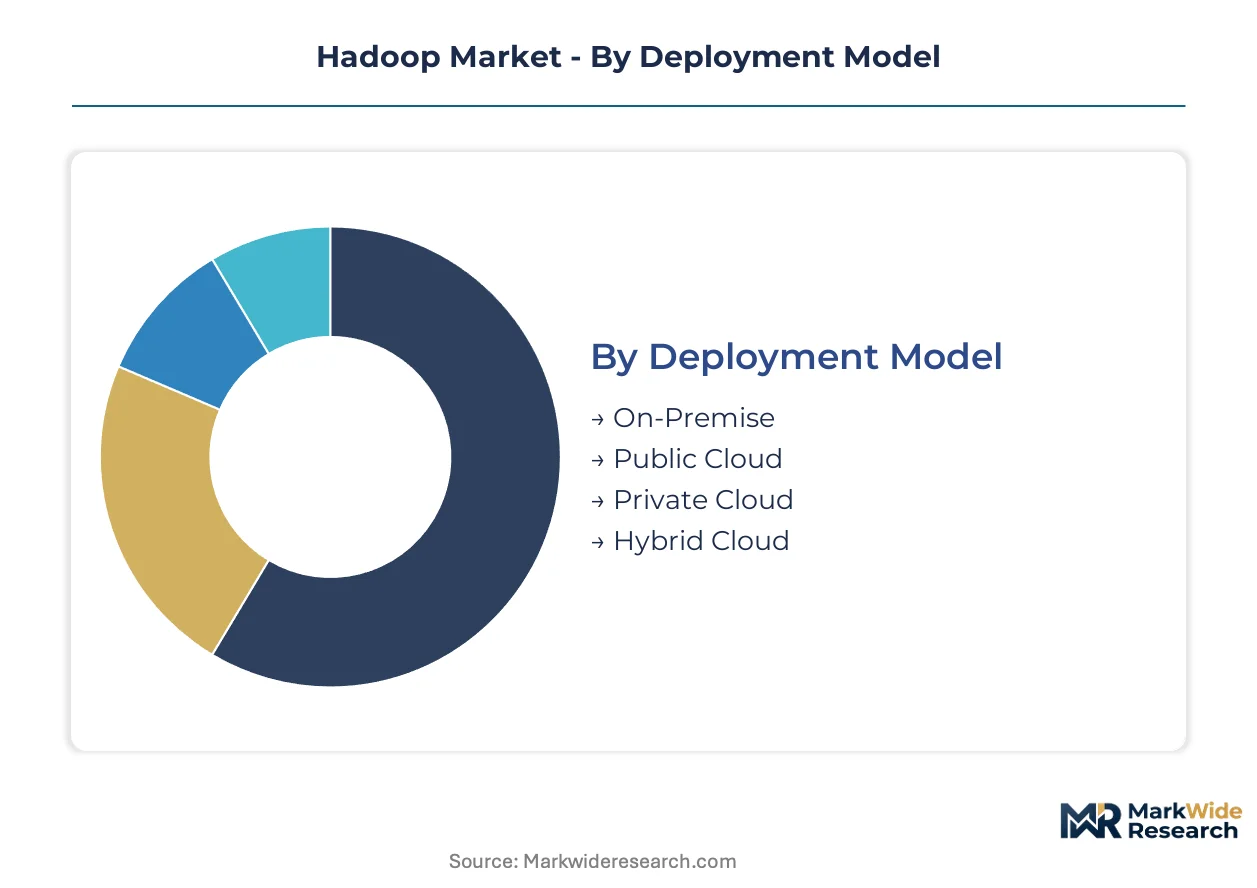
Hadoop deployments fragment across infrastructure choices, workload patterns, and governance requirements. Understanding these divisions reveals where capital concentrates and where operational complexity creates vendor stickiness.
Deployment Model:
Organizations weight data gravity against elasticity needs across four infrastructure postures.
- On-Premise:Dedicated server clusters within enterprise data centers deliver sub-millisecond HDFS access for latency-sensitive fraud detection pipelines. German automotive manufacturers and US defense contractors maintain these estates to satisfy ITAR and EU data sovereignty rules. Established volume favors On-Premise; emerging adoption favors Hybrid Cloud.
- Public Cloud:Amazon EMR, Azure HDInsight, and Google Dataproc eliminate hardware procurement cycles and shift Hadoop operations to variable cost structures. US SaaS vendors expanding multi-tenant analytics products drive demand concentration here.
- Private Cloud:Single-tenant virtualized environments hosted in third-party facilities address data residency without capital expenditure. Indian banks responding to RBI localization mandates deploy this model.
- Hybrid Cloud:Unified control planes span on-premise clusters and burst capacity to public cloud for seasonal workloads. French insurers use this posture for Solvency II reporting peaks.
Established volume favors On-Premise; emerging adoption favors Hybrid Cloud.
Application Type:
Workload characteristics determine integration complexity and pricing premiums across four functional domains.
- Analytics:Business intelligence integration through Hive and Impala enables SQL-based exploration of petabyte-scale datasets. US healthcare systems deploy these layers for population health stratification. Analytics commands premium pricing due to governance framework embedding.
- Data Management:Metadata cataloging, lineage tracking, and retention policy enforcement through Apache Atlas and Ranger satisfy EU AI Act documentation requirements. French asset managers front-load compliance investments here.
- Data Processing:MapReduce and Spark batch jobs transform raw telemetry into structured features for machine learning pipelines. Telcos in India process CDR archives through these workloads.
- Data Storage:HDFS and S3-compatible object layers provide cost-effective archival for regulatory retention periods. US SEC-registered advisors maintain decade-long email and trade record repositories.
Margin concentration sits with Data Management; steepest expansion trajectory belongs to Analytics.
End User:
Vertical-specific compliance and data velocity requirements shape deployment architectures across four sectors.
- Banking:Real-time transaction monitoring and AML pattern detection demand low-latency cluster configurations. German Landesbanken combine Hadoop with mainframe connectivity for core banking integration.
- Healthcare:HIPAA-covered entities deploy HCatalog for patient de-identification and imaging archive batch processing. US hospital networks expand clusters for clinical research data lakes.
- Telecommunications:CDR and network telemetry ingestion at terabyte-per-day scale drives hardware-intensive on-premise estates. Indian operators face RBI and CERT-In localization pressures.
- Retail:Clickstream analysis and supply chain optimization favor cloud-native deployments for elasticity around promotional events. US e-commerce platforms lead this migration.
Compliance intensity favors Banking; cloud migration velocity favors Retail.
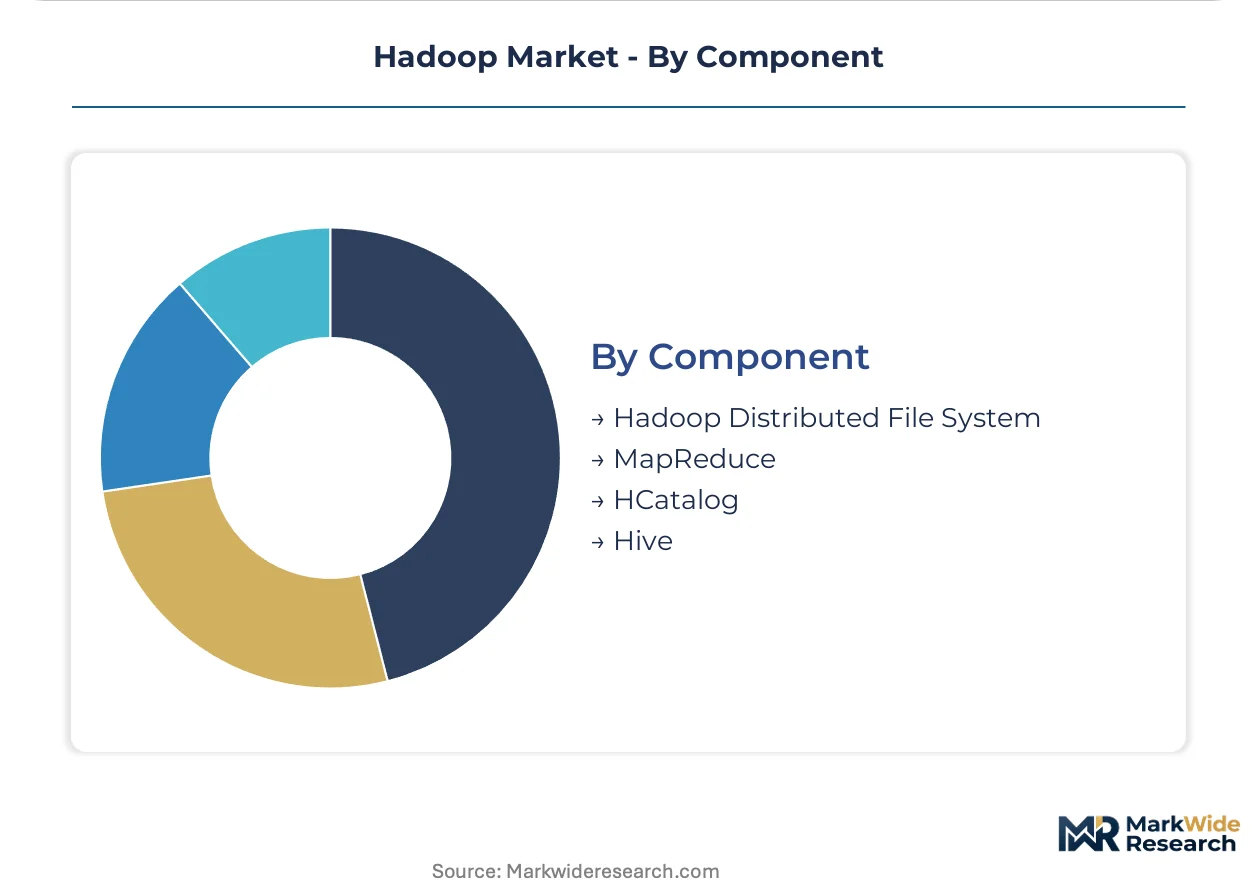
Component:
Core architectural layers differentiate by operational maturity and talent availability.
- Hadoop Distributed File System:The foundational storage layer replicates data blocks across commodity nodes for fault tolerance. Financial services firms in France maintain HDFS estates for algorithmic auditability under EU AI Act.
- MapReduce:The original batch processing paradigm persists in legacy production jobs despite Spark displacement. Scala and Python engineering scarcity complicates migration timelines.
- Hive:SQL abstraction over HDFS enables analyst access without Java expertise. US healthcare BI teams standardize on this interface.
- HCatalog:Metadata and schema management bridge Hadoop with enterprise data governance tools. German manufacturers use this for Industry 4.0 data lake federation.
Maintenance burden concentrates in MapReduce; modernization investment flows to Hive.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform integrators concentrate engineering talent and enterprise sales capacity in three primary markets. The United States, Germany, and India absorb the majority of Hadoop deployment expenditure, while compliance mandates in France and Japan sustain specialized on-premise estates.
United States
Cloud-native enterprises in Seattle and San Francisco are migrating batch analytics workloads to managed services. SEC climate disclosure rules are forcing asset managers in New York to build Hadoop-based data lakes for portfolio carbon footprint tracking. Healthcare networks in Boston expand HCatalog implementations for HIPAA-compliant patient de-identification.
Germany
Landesbanken and automotive manufacturers in Stuttgart maintain on-premise clusters for real-time fraud detection. EU AI Act algorithmic auditability requirements are driving metadata lineage investments through Apache Atlas. Industrial data lakes in Munich integrate Hadoop with mainframe connectivity for Industry 4.0 telemetry processing.
India
RBI data localization mandates are compelling multinational banks to maintain in-country Hadoop estates in Mumbai. Domestic systems integrators in Bangalore are capturing deployment contracts for telco CDR processing at terabyte-per-day scale. CERT-In directives reinforce data residency requirements for cloud burst configurations.
France
French insurers in Paris deploy hybrid cloud postures for Solvency II reporting peaks. CNIL enforcement of GDPR data lineage standards is accelerating Apache Ranger implementations for column-level security. Asset managers front-load EU AI Act compliance investments ahead of enforcement deadlines.
Japan
Tokyo-based financial institutions maintain low-latency clusters for transaction monitoring and AML pattern detection. METI industrial data policies encourage Hadoop integration with manufacturing execution systems. Osaka healthcare networks process clinical imaging archives through batch pipelines.
Hadoop Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the value chain. The vendor landscape consolidates around three functional layers: distribution packagers, managed service operators, and query engine optimizers. Incumbents defend position through hybrid deployment contracts spanning data centers and multiple public clouds. New entrants compete on consumption-based pricing and Kubernetes-native orchestration.
Among distribution packagers, Cloudera and Hortonworks occupy positions as archetypal platform consolidators, while MapR Technologies exemplifies the specialized file-system tier. IBM Corporation anchors the mainframe-integrated segment for regulated industries. These three names represent the primary competitive vectors: hybrid portability, legacy system connectivity, and performance-optimized storage engines.
| Leading Market Players |
|---|
| IBM Corporation |
| Hortonworks |
| Cloudera |
| SAS Institute Inc. |
| Oracle Corporation |
| Amazon Web Services (AWS) |
| Microsoft Corporation |
| Databricks |
| MapR Technologies |
| Others |
Cost & Logistics Intelligence
Bangalore's systems integrator cluster concentrates Hadoop deployment capacity for multinational banks responding to RBI localization mandates. This geographic concentration of implementation expertise translates directly into pricing power for hybrid cloud configurations across the Asia-Pacific corridor.
Pricing Analysis
EU AI Act dictates the pricing tier structure for governed Hadoop deployments across financial services verticals. Three-tier pricing structure across premium, standard, and economy levels segments by compliance automation depth and metadata lineage sophistication. Cost compression in the economy tier is intensifying because cloud-native object storage eliminates HDFS maintenance overhead. Mid-market SaaS vendors exhibit the highest price sensitivity, while German automotive manufacturers and US defense contractors absorbing ITAR compliance costs demonstrate the lowest.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for commodity server hardware feeding Hadoop clusters. Server assembly concentrates in Taiwan, China, and Mexico, with memory components drawing from South Korean and Japanese foundries. Single-source vulnerability in specialized network interface cards for low-latency fraud detection pipelines creates procurement exposure. Distribution runs through systems integrators in India and Germany for regulated industry deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hadoop demand cycles track enterprise data center refresh waves and cloud migration pause points. The current recovery phase reflects deferred on-premise investments reactivating as CFOs reassess long-term operating expense trajectories.
For Market Incumbents: Harden hybrid platform positioning through Kubernetes-native orchestration layers that extend on-premise asset lifecycles. Incumbents must anchor mainframe connectivity capabilities for German banking and automotive verticals facing EU AI Act enforcement. Deepen backward integration into metadata catalog software to capture Apache Atlas and Ranger deployment premiums.
For New Entrants and Emerging Players: Mid-market healthcare networks in the United States represent the most penetrable entry point for HIPAA-compliant HCatalog implementations with consumption-based pricing. Indian telco CDR processing at terabyte-per-day scale offers a second white-space target for containerized Hadoop distributions. A direct sales model through domestic systems integrators bypasses entrenched vendor procurement relationships.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational technology conglomerates divesting non-core data infrastructure assets. The five-to-ten year viability window hinges on hybrid cloud workload persistence against full cloud-native displacement. Watch for Spark migration execution failures as the inflection signal indicating extended MapReduce cluster relevance.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Platform Integration | Unified control planes spanning on-premise and burst capacity address Solvency II reporting peaks for French insurers. |
| Apache Iceberg Table Format Adoption | Cloud-native technology firms adopting Iceberg as default lakehouse abstraction compress vendor differentiation around proprietary catalogs. |
| EU AI Act Compliance Automation | Automated lineage capture through Apache Atlas satisfies algorithmic auditability requirements for German financial services. |
| Kubernetes-Native Orchestration | Containerized distributions enable elastic scaling patterns previously exclusive to cloud-native architectures. |
| Consumption-Based Pricing Transition | Committed use discounts against autoscaling elasticity guarantees displace perpetual license models among mid-market buyers. |
Research Approach
Cross-validation between primary interviews with Hadoop operations directors and secondary validation through hyperscaler capex disclosures anchors the qualitative findings. The research combined discussions with CTOs, platform engineers, channel partners, and integration specialists at financial services and healthcare enterprises. Secondary sources included SEC filings, cloud provider infrastructure investment reports, and regulatory compliance documentation from EU AI Act implementation guidance. Bottom-up cluster deployment estimates and top-down vendor revenue analysis provided triangulation discipline.
Calibration against historical migration velocity patterns and cloud adoption curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment model, organization size, vertical compliance intensity, and regional regulatory cluster. CAGRs were derived from slope analysis of infrastructure spending trajectories. Forecast inputs incorporated MapReduce job persistence rates and Spark migration completion timelines.
Practitioners should monitor cloud-native object storage substitution rates and EU AI Act enforcement intensity for early signals of forecast revision. Forecasts reflect assumptions about enterprise data gravity preferences and regulatory data residency requirements. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Offshore Software Development Market
Software & Services
Application Server Market
Software & Services
Global Political Campaign Software Market
Software & Services
Runtime Software Market
Software & Services
IT Service Management Tools Market
Software & Services
Commissioning Software Market
Software & Services
Dental Practice Management Software Market
Software & Services
HACCP Software Market
Software & Services
Time and Attendance Software Market
Software & Services
Camera Tracking Software Market
Software & Services
Quote Management Software Market
Software & Services
Global Referral Software Market
Software & Services
Global Translation Software Market
Software & Services
Saas-Based Expense Management Market
Software & Services
Servicenow Tech Services Market
Software & Services
Global Restaurant POS Software Market