
 Custom Binders Market | 2026-2036
Custom Binders Market Size, Share, and Industry Trends Forecast 2026-2036
Custom Binders Market Outlook
Corporate professional presentations is shifting toward higher-margin customized formats as enterprises prioritize branded collateral over commodity office supplies. Avery Dennison Corporation leverages its materials science heritage to dominate premium substrate segments. Samsill Corporation anchors its position through manufacturing scale in North American distribution channels. 3M competes on adhesive and coating technology leadership for specialized binding applications.
Custom binders are rigid document enclosures manufactured from plastic, cardboard, leather, or vinyl substrates, typically incorporating metal ring mechanisms, clamp assemblies, or lever-arch hardware to secure perforated or loose-leaf materials for organized storage and presentation. Ring binders sustain the largest volume position due to universal compatibility with standard hole-punch formats across education and office environments. Presentation binders represent the fastest-expanding category as material innovations in recycled cardboard and bio-based vinyl respond to corporate sustainability mandates. Leather and premium vinyl segments concentrate margin pools in executive gifting and legal archiving applications.
The EPA regulates volatile organic compound emissions from adhesive formulations used in vinyl binder assembly, while the EU REACH framework restricts phthalate plasticizers in PVC-based products destined for European office channels. California's Proposition 65 labeling requirements create compliance friction for imported plastic binders containing specified chemical constituents. Stakeholders must monitor evolving extended producer responsibility frameworks that will reshape material specifications and recycling infrastructure obligations across major demand centers.
Market Dynamics
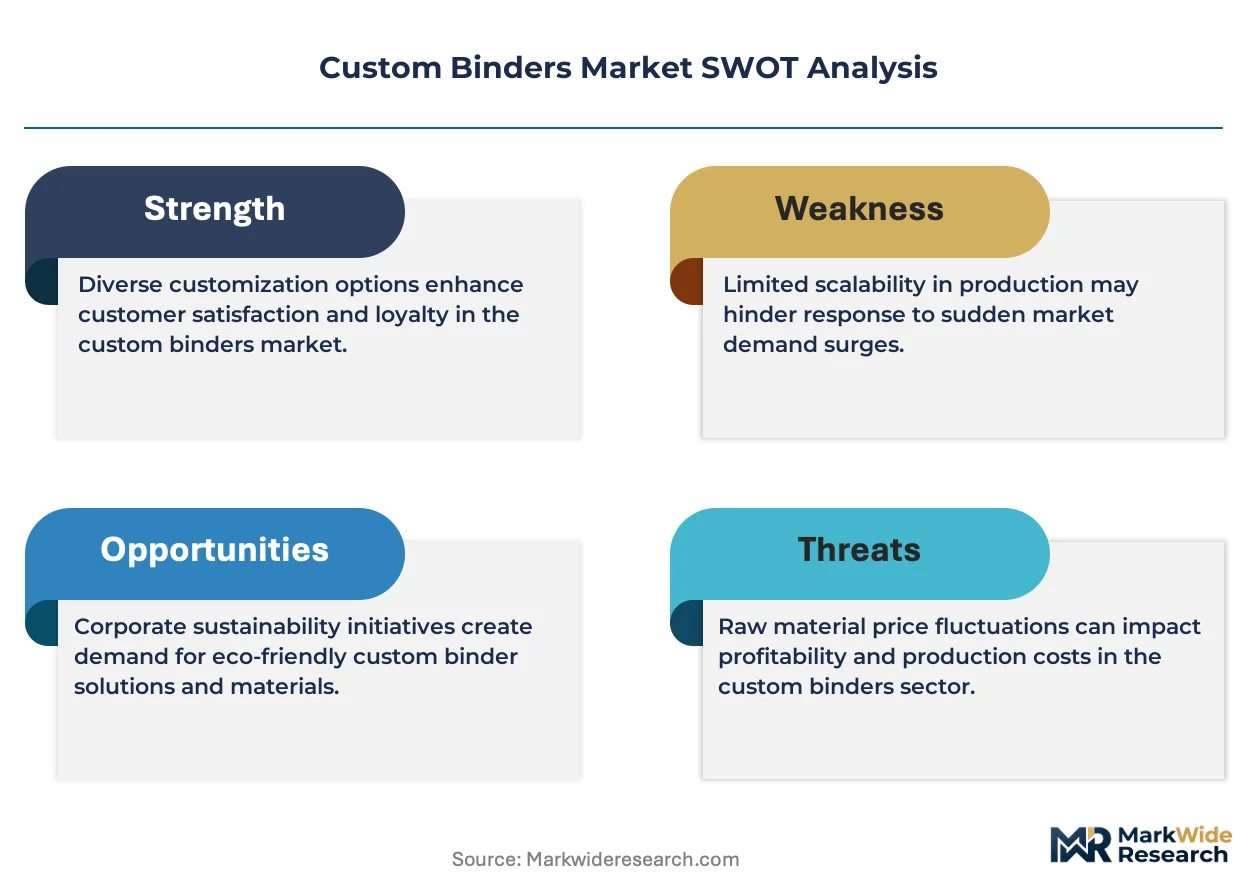
Corporate sustainability mandates are compressing demand for virgin plastic binders while accelerating specification of recycled cardboard and bio-based vinyl alternatives across procurement departments. The EU Green Deal's tightening virgin plastic restrictions are forcing substrate substitutions throughout European office supply channels.
Growth Catalysts
- EU Green Deal plastic restrictions:Binding mandates on virgin plastic content in office supplies are redirecting procurement budgets toward certified recycled and bio-based alternatives across German corporate channels.
- Corporate branded collateral programs:Enterprise marketing departments are expanding budgets for premium presentation materials that reinforce visual identity during client engagements and investor roadshows.
- Leather and premium vinyl archiving:Legal firms and executive offices in Frankfurt and Munich are sustaining demand for high-margin specialty enclosures with extended durability specifications.
Market Restraints
- Petrochemical input volatility:PVC resin and synthetic leather feedstock prices fluctuate with crude oil indices, compressing margin predictability for vinyl-dominant product lines.
- REACH compliance friction:Phthalate plasticizer restrictions in EU-bound products require reformulation investments and extended certification timelines for Asian contract manufacturers.
- Digital document substitution:Cloud-based contract management and tablet-based presentation platforms are displacing physical binder volumes in technology-forward enterprise segments.
Strategic Opportunities
- Extended producer responsibility frameworks:Emerging take-back and recycling infrastructure obligations in Germany and France will favor domestic manufacturers with closed-loop material capabilities.
- Recycled cardboard innovation:Structural advances in molded fiber and post-consumer paperboard are enabling premium aesthetic finishes previously exclusive to plastic substrates.
- Direct-to-enterprise digital channels:Procurement platform integration allows custom binder specialists to bypass traditional wholesale distributors and capture margin from corporate accounts.
Industry Challenges
- Adhesive formulation expertise:Low-VOC and bio-based bonding agents require specialized chemistry knowledge that concentrates among a limited supplier base in Germany and the Netherlands.
- Multi-material assembly complexity:Ring mechanisms, substrate panels, and cover materials sourced from disparate geographies create quality control friction and inventory coordination costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Custom Binders Market |
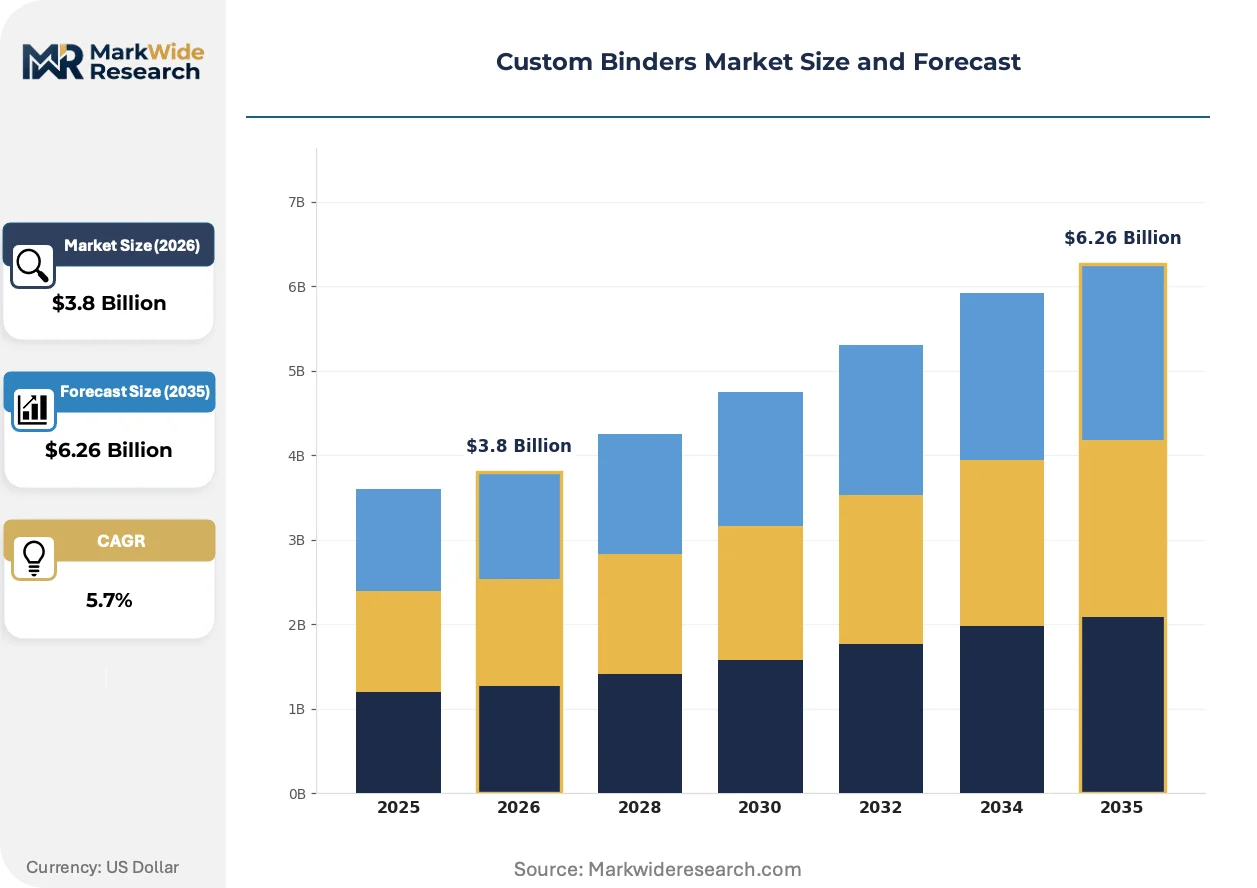
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ring Binders, Presentation Binders, Clip Binders, Lever Arch Binders Material: Plastic, Cardboard, Leather, Vinyl Size: A4, A5, Letter, Custom Sizes Usage: Office, Education, Personal Use, Professional Presentations |
| Companies Covered | Norwood Systems, Avery Dennison Corporation, Samsill Corporation, 3M, Huntsman International LLC, Henkel AG & Co. KGaA, Evonik Industries AG, Dow, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Custom Binders Market Strategic Shifts
Material science advances are dissolving traditional trade-offs between sustainability credentials and structural performance in document enclosure manufacturing. Three interconnected developments are redefining competitive positioning across substrate, hardware, and distribution layers.
Bio-based vinyl formulations derived from castor oil and other renewable feedstocks are converging with conventional petroleum-derived PVC in durability and printability metrics. German automotive and industrial marketing departments are piloting these materials for high-visibility presentation kits. The convergence is compressing price premiums for sustainable alternatives and forcing legacy petrochemical suppliers to accelerate their own biopolymer roadmaps.
REACH Annex XVII restrictions on phthalate plasticizers are compelling PVC binder manufacturers to migrate toward citrate-based or polymeric plasticizer systems. The industrial consequence is elevated R&D expenditure and reformulation validation cycles before products can re-enter European distribution channels. Small and mid-sized converters without in-house polymer science capabilities are outsourcing compliance testing to specialized laboratories in Belgium and the Netherlands, extending time-to-market by six to twelve months.
Enterprise procurement departments are consolidating vendor relationships and demanding consolidated reporting on carbon footprint, recycled content percentage, and end-of-life recyclability. The distributor and wholesaler tier is being compressed as direct manufacturer relationships deliver transparency documentation that intermediaries cannot match. This pattern is most pronounced in Germany's DAX-listed corporations, where sustainability procurement scorecards now weight supplier ESG data at fifteen to twenty percent of total evaluation criteria.
Custom Binders Market Segmentation
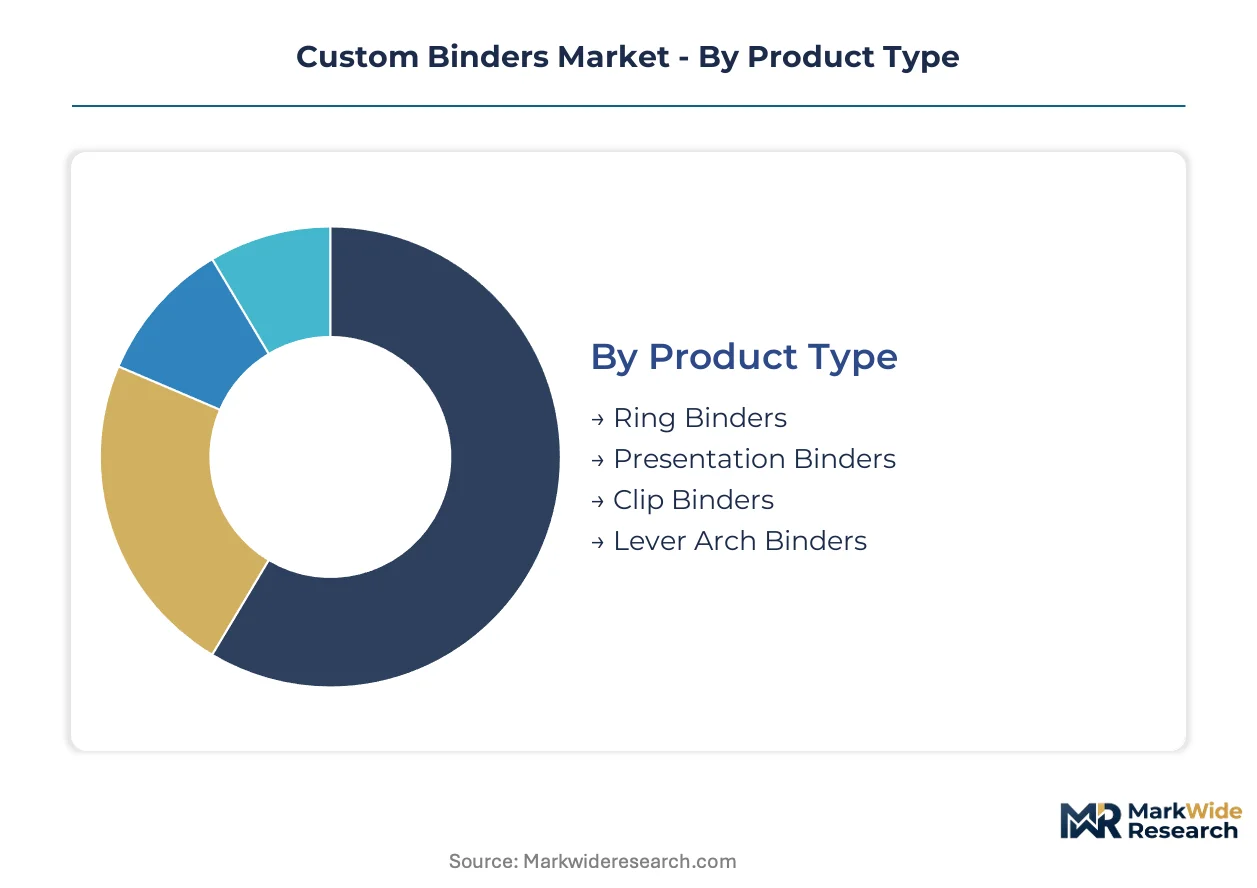
Custom binder specifications diverge sharply between procurement-driven standardization and marketing-led differentiation. Understanding where customization premium justifies cost elevation versus where commodity formats dominate purchasing decisions enables precise portfolio positioning across substrate, hardware, and format dimensions.
Product Type:
Customization intensity varies from standardized hardware mechanisms to fully bespoke enclosure designs, with implications for tooling investment and margin structure.
- Ring Binders:Metal ring mechanisms in 2-ring, 3-ring, and 4-ring configurations accommodate universal hole-punch standards across North American and European office environments. Procurement departments in Germany's automotive sector specify these for technical documentation libraries where interchangeability reduces replacement costs.
- Presentation Binders:Rigid front and back panels with clear overlay pockets enable full-bleed branded graphics and corporate identity integration. Frankfurt marketing departments and Munich investor relations teams drive specification of recycled cardboard and bio-based vinyl variants to satisfy EU Green Deal procurement mandates.
- Clip Binders:Spring-loaded clamp mechanisms secure unpunched materials for legal and archival applications requiring document integrity without perforation.
- Lever Arch Binders:German-engineered lever mechanisms deliver higher sheet capacity for engineering drawings and regulatory compliance documentation in industrial settings.
Leading the category by volume: Ring Binders. Growing fastest: Presentation Binders.
Material:
Cost tier stratification separates commodity substrates from premium alternatives, with sustainability credentials now penetrating mid-market specifications.
- Plastic:PVC and polypropylene formulations dominate high-volume office supply channels through durability and moisture resistance. REACH Annex XVII phthalate restrictions are forcing reformulation toward citrate-based plasticizer systems for EU-bound products, elevating compliance costs for Asian contract manufacturers.
- Cardboard:Post-consumer recycled paperboard and molded fiber substrates are displacing virgin plastic in German corporate procurement scorecards. Structural advances enable premium aesthetic finishes previously exclusive to synthetic materials, with DAX-listed enterprises weighting recycled content at fifteen to twenty percent of supplier evaluation criteria.
- Leather:Full-grain and bonded leather enclosures command executive gifting and legal archiving premiums in Frankfurt and Munich.
- Vinyl:Bio-based formulations derived from castor oil are converging with petroleum-derived PVC in performance metrics, compressing price premiums for sustainable alternatives.
Highest volume position: Plastic. Steepest expansion trajectory: Cardboard.
Size:
Geographic standardization creates regional volume concentrations, with custom formats capturing niche professional applications.
- A4:ISO 216 standard dimensions dominate European office and education procurement, with German public sector tenders specifying this format exclusively.
- A5:Compact portable format concentrates in field documentation and mobile professional use cases.
- Letter:US-standard dimensions anchor North American corporate procurement and federal government supply contracts.
- Custom Sizes:Non-standard dimensions accommodate architectural drawings, pharmaceutical batch records, and specialized industrial documentation.
Dominant specification by region: A4 in Europe, Letter in North America. Fastest-growing specification: Custom Sizes for branded presentation kits.
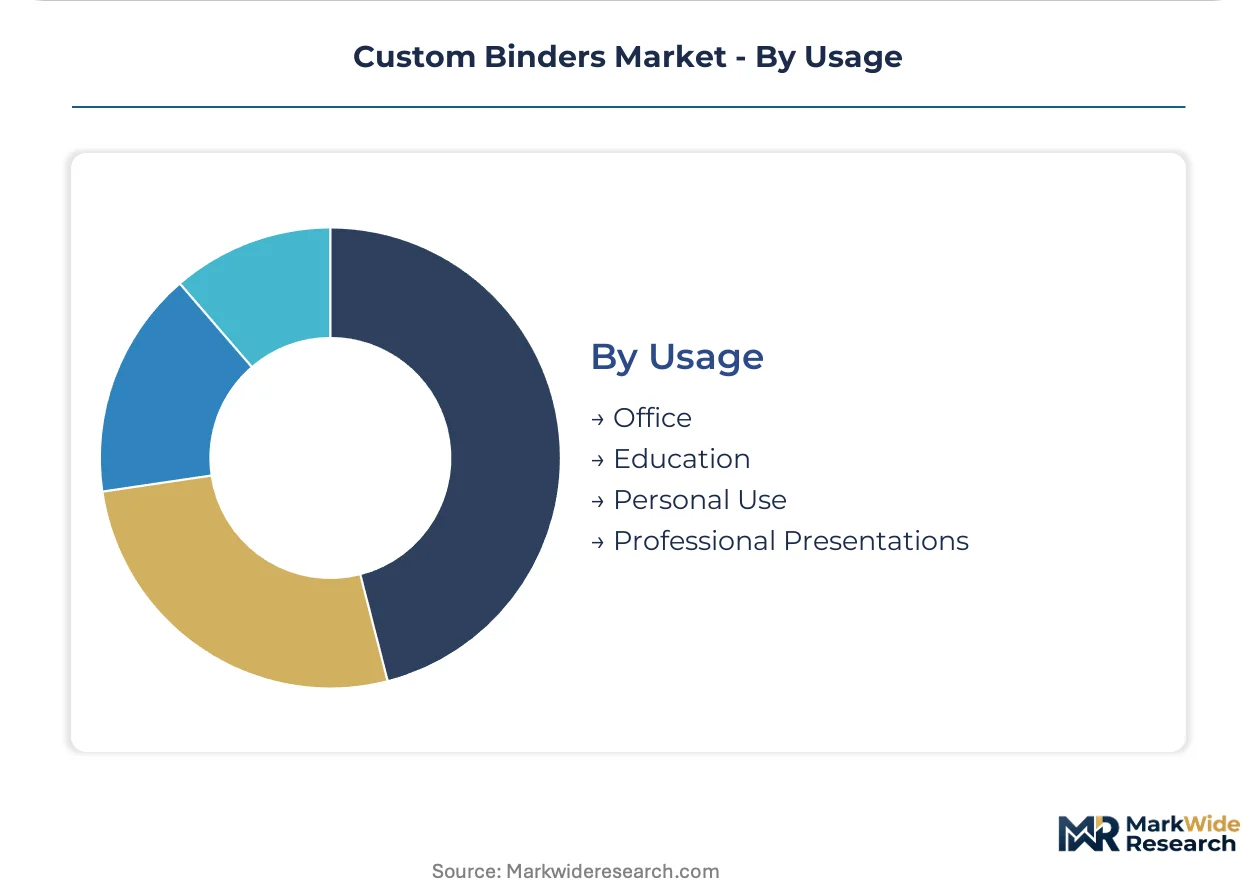
Usage:
End-use application determines durability requirements, aesthetic specifications, and price elasticity across customer segments.
- Office:High-volume administrative storage prioritizes cost efficiency and standardization, with procurement departments consolidating vendor relationships.
- Education:Student and institutional demand concentrates in ring binders compatible with standardized hole-punch formats across K-12 and university environments.
- Personal Use:Individual consumers select on price and basic functionality, with limited customization uptake.
- Professional Presentations:Enterprise marketing departments and investor relations teams specify premium substrates with full branding integration, sustaining margin pools despite digital substitution pressures from tablet-based platforms.
Largest volume base: Office. Gaining share fastest: Professional Presentations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Bavaria and Baden-Württemberg concentrate European binder manufacturing capacity, with automotive marketing procurement driving specification of bio-based vinyl substrates.
Germany
Frankfurt investor relations departments and Munich legal firms sustain premium leather and archival-grade vinyl demand. REACH Annex XVII phthalate restrictions force reformulation of PVC-based products bound for German distribution channels. Stuttgart automotive clusters specify recycled cardboard presentation kits for technical documentation libraries.
United States
Corporate procurement departments in Chicago and Dallas expand branded collateral programs for client presentations and roadshows. EPA volatile organic compound regulations govern adhesive formulations in vinyl binder assembly. California's Proposition 65 labeling requirements create compliance friction for imported plastic binders entering West Coast distribution.
France
Paris-based luxury goods marketing teams drive specification of premium substrates for executive gifting applications. EU Green Deal procurement mandates redirect public sector budgets toward certified recycled alternatives. Lyon industrial documentation clusters sustain demand for high-capacity lever-arch formats in engineering environments.
United Kingdom
London financial services marketing departments prioritize sustainability credentials in supplier scorecards for investor presentation materials. Extended producer responsibility frameworks reshape material specifications and recycling infrastructure obligations. Manchester corporate procurement hubs consolidate vendor relationships to capture transparency documentation on carbon footprint metrics.
China
Contract manufacturers in Guangdong and Zhejiang provinces supply ring mechanism hardware and substrate panels to European and North American brands. Dual carbon goals and tightening environmental inspections elevate compliance costs for petrochemical-derived PVC production. Shenzhen industrial design clusters develop molded fiber innovations for export-bound premium presentation formats.
Custom Binders Market Competitive Environment
Top-tier vendors anchor premium substrate and adhesive technology segments, while mid-scale converters occupy standardized ring binder and cardboard format production. The vendor base distributes across materials science conglomerates, specialized office supply manufacturers, and regional fabrication specialists. Strategic archetypes include petrochemical-integrated substrate suppliers, hardware-focused mechanism specialists, and sustainability-certified converters. Dominant competitive moves encompass bio-based material reformulation partnerships and direct-to-enterprise digital channel integration.
Among materials science conglomerates, Avery Dennison Corporation, 3M, and BASF SE exemplify the technology-licensing archetype, anchoring premium adhesive and coating capabilities that downstream converters license for specialized binding applications. Samsill Corporation occupies a position within the North American manufacturing scale tier. Henkel AG & Co. KGaA and Evonik Industries AG sit within the European chemical formulation specialist segment.
| Leading Market Players |
|---|
| Norwood Systems |
| Avery Dennison Corporation |
| Samsill Corporation |
| 3M |
| Huntsman International LLC |
| Henkel AG & Co. KGaA |
| Evonik Industries AG |
| Dow |
| BASF SE |
| Others |
Value Chain & Pricing Dynamics
Specialized adhesive formulation chemists in Germany and the Netherlands command wage premiums that compress margin spreads between premium bio-based vinyl binders and economy-grade PVC alternatives. Labor-cost differentials across these technical workforce clusters directly shape three-tier pricing stratification across the European procurement landscape.
Pricing Analysis
Short lead-time premiums for certified recycled cardboard and REACH-compliant bio-based vinyl binders run 15-25 percent above spot inventory pricing for standard PVC formats. Three-tier pricing structure across premium, standard, and economy levels reflects customization intensity, substrate certification grade, and hardware mechanism origin. Price erosion runs through commodity PVC ring binders as Asian contract manufacturers absorb reformulation costs for phthalate-free plasticizer systems. Procurement departments in Germany's automotive sector exhibit lowest price sensitivity, prioritizing ESG documentation and supply chain transparency over unit cost minimization.
Supply Chain Analysis
Regional distribution centers in Bavaria and Baden-Württemberg operate hub-and-spoke patterns feeding German corporate channels, with secondary nodes in France and the United Kingdom serving pan-European accounts. Manufacturing concentration centers on China for ring mechanism hardware and substrate panels, Germany for adhesive formulation and final assembly, and Vietnam for emerging molded fiber capacity. Raw material dependencies include PVC resin from petrochemical complexes, post-consumer paperboard from Nordic pulp mills, and citrate-based plasticizers from Belgian specialty chemical producers. Single-source vulnerability concentrates in German adhesive formulation expertise, where REACH-compliant bonding agent knowledge rests with a limited supplier base. Distribution runs through direct-to-enterprise digital channels that bypass traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market constitutes a vertical-integration race where backward control over bio-based substrate supply and captive adhesive formulation capabilities determine margin sustainability. Players are pursuing upstream integration into castor oil-derived vinyl feedstocks and downstream direct procurement platform relationships.
For Market Incumbents: Deepen captive supply of citrate-based plasticizer systems to insulate margin structures from REACH reformulation cost spikes. Acquire specialized laboratories in Belgium or the Netherlands to compress six-to-twelve-month compliance validation cycles for bio-based vinyl alternatives. Channel control through direct-to-enterprise digital procurement platforms defends position against distributor-tier compression. For New Entrants and Emerging Players: The mid-market price-point gap between Frankfurt premium leather archiving formats and economy PVC office supplies offers white-space entry. Target recycled cardboard presentation binders for DAX-listed corporate sustainability scorecards where incumbent petrochemical players lag substrate innovation. Deploy molded fiber structural engineering capabilities from Shenzhen design clusters as differentiated go-to-market positioning. For Investors and Strategic Acquirers: Re-rating potential sits with sustainability-certified converters given EU Green Deal procurement mandate acceleration. Long-term viability favors manufacturers with closed-loop material capabilities and ESG documentation infrastructure. Watch German extended producer responsibility framework implementation timelines as inflection indicators for domestic manufacturing asset valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Feedstocks | Castor oil-derived vinyl supply secures margin insulation from petrochemical volatility. |
| REACH Compliance Laboratory Acquisition | Belgian testing capabilities compress reformulation validation cycles for EU-bound products. |
| Direct-to-Enterprise Digital Channel Launch | Procurement platform integration captures margin from distributor-tier compression. |
| Recycled Cardboard Structural Innovation | Molded fiber advances enable premium aesthetics previously exclusive to plastic substrates. |
| Extended Producer Responsibility Infrastructure | German take-back capabilities align with emerging recycling obligation frameworks. |
Study Parameters
Multi-period observation of substrate substitution rates, REACH compliance timelines, and corporate procurement scorecard evolution anchored the trend analysis, supplemented by interviews with plant managers at German converter facilities, procurement leads at DAX-listed automotive OEMs, distribution channel partners in French office supply networks, and technical R&D directors at adhesive formulation specialists. Secondary validation drew from ECHA substance restriction databases, EU Green Deal procurement mandate documentation, customs trade data for ring mechanism hardware flows, and SEC 10-K disclosures from materials science conglomerates. Bottom-up volume modeling across substrate and hardware segments triangulated against top-down procurement budget allocation estimates.
Input-output matrices mapped petrochemical feedstock costs, labor differentials across formulation chemistry clusters, and sustainability certification premiums to volume and value outputs across the projection horizon. Segmentation dimensions included product type, material substrate, size format, and end-use application intensity. CAGRs were derived from elasticity-adjusted demand curves incorporating digital substitution rates and regulatory compliance cost pass-through assumptions. Industry-specific forecast inputs encompassed REACH Annex XVII amendment timelines and EU Green Deal virgin plastic restriction phase-in schedules.
Inputs from ECHA regulatory filings and German federal procurement databases were available through the study window; gaps in real-time corporate sustainability scorecard weighting introduce uncertainty bands around bio-based vinyl adoption velocity. Forecasts reflect documented assumptions on petrochemical price trajectories and regulatory enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Supplies
Global Stationery and Supplies Market
Office Supplies
Europe School Stationery Supplies Market
Office Supplies
Writing Instruments Market
Office Supplies
Business Card Holder Market
Office Supplies
Stamp Pad Market
Office Supplies
Cutter Staplers Market
Office Supplies
Mechanical Pencil Leads Market
Office Supplies
United States School Stationery Supplies Market
Office Supplies
Latin America School Stationery Supplies Market
Office Supplies
Letter Opener Market
Office Supplies
Global Office Peripherals and Products Market
Office Supplies
GCC School Stationery Supplies Market
Office Supplies
School Stationery Supplies Market
Office Supplies
Stationery Products Market
Office Supplies
Marker Pens Market
Office Supplies
Dictionary Pen Market