
 Carthamus Yellow Market | 2026-2036
Carthamus Yellow Market Size, Share, and Industry Trends Forecast 2026-2036
Carthamus Yellow Market Outlook
Modular concentrate-to-powder formulation is repositioning buyer choice across the Carthamus Yellow supply chain. Hansen Holding A/S leverages its fermentation expertise to anchor premium natural colorant portfolios. Guixi Huakang Natural Pigment Factory dominates regional extraction capacity in Jiangxi province. Zhejiang Binmei Biotechnology Co. Ltd. specializes in spray-dried powder grades for multinational food clients.
Carthamus Yellow is a natural hydroxysafflor yellow A pigment extracted from Carthamus tinctorius L. florets, typically standardized to color values between E50 and E150 and water-soluble for direct incorporation into aqueous food matrices. The pigment serves primarily as a replacement for synthetic azo dyes in acidic to neutral pH applications. Powder formats lead volume due to stability in ambient storage and ease of dry blending, while liquid concentrates capture margin pools in beverage and confectionery lines where dosing precision matters. Pharmaceutical applications represent the fastest-expanding segment as excipient-grade natural colorants gain traction in tablet film coatings.
China's SAMR enforces GB 2760 food additive standards that restrict synthetic dye usage in infant and school food categories, directly expanding qualified natural pigment demand. The EU EFSA maintains positive safety opinions for carthamus-derived colorants under Regulation 1333/2008, enabling cross-border ingredient trade into European processed food channels. India's FSSAI notification on natural colorant purity specifications creates compliance thresholds that favor established extractors with analytical capabilities. Stakeholders must monitor evolving pharmacopeial monographs for natural pigments, as compendial recognition determines access to pharmaceutical formulation pipelines.
Market Dynamics
China's SAMR enforcement of GB 2760 infant food additive restrictions is forcing domestic and multinational food manufacturers toward certified natural pigment sourcing, compressing synthetic dye procurement windows and elevating extractor qualification requirements.
Growth Catalysts
- Clean-label infant food mandates:China's SAMR restrictions on synthetic dyes in infant and school food categories directly expand qualified natural pigment demand among domestic processors.
- EFSA cross-border recognition:Positive safety opinions under EU Regulation 1333/2008 enable Chinese extractors to access European processed food channels without redundant toxicology testing.
- Pharmaceutical excipient pivot:Tablet film coating applications for natural colorants are accelerating as drug manufacturers replace synthetic lake pigments ahead of pharmacopeial monograph updates.
Market Restraints
- Safflower crop concentration:Raw material sourcing clusters in China's Shandong and Xinjiang provinces, exposing processors to regional weather volatility and single-origin supply risk.
- Hydroxysafflor yellow A stability limits:The pigment's pH sensitivity below 4.0 and light degradation above 25°C restricts formulation in acidic beverage applications and transparent packaging.
- FSSAI purity compliance costs:India's notification on natural colorant analytical thresholds favors established extractors with HPLC capabilities, raising barriers for new market entrants.
Strategic Opportunities
- Pharmaceutical compendial recognition:USP and EP monograph inclusion for Carthamus Yellow would unlock direct supply to generic drug manufacturers in North America and Europe.
- Spray-dried powder standardization:Multinational food clients are consolidating suppliers around ISO 22000-certified facilities with documented color value consistency between E50 and E150 batches.
- Modular concentrate-to-powder systems:Fermentation-derived pigment platforms are converging with botanical extraction to create hybrid supply models with reduced agricultural land dependency.
Industry Challenges
- Analytical chemist scarcity:Hydroxysafflor yellow A quantification requires HPLC-DAD expertise that remains concentrated in Jiangsu and Zhejiang university pipelines, constraining quality control scaling.
- Dual certification timelines:Simultaneous FSSC 22000 and excipient-grade GMP qualification extends facility commissioning by 14-18 months, delaying revenue recognition for capacity expansions.
- Legacy dye switching friction:Food manufacturers with entrenched synthetic azo dye formulations face reformulation stability testing costs and sensory panel revalidation before natural pigment adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carthamus Yellow Market |
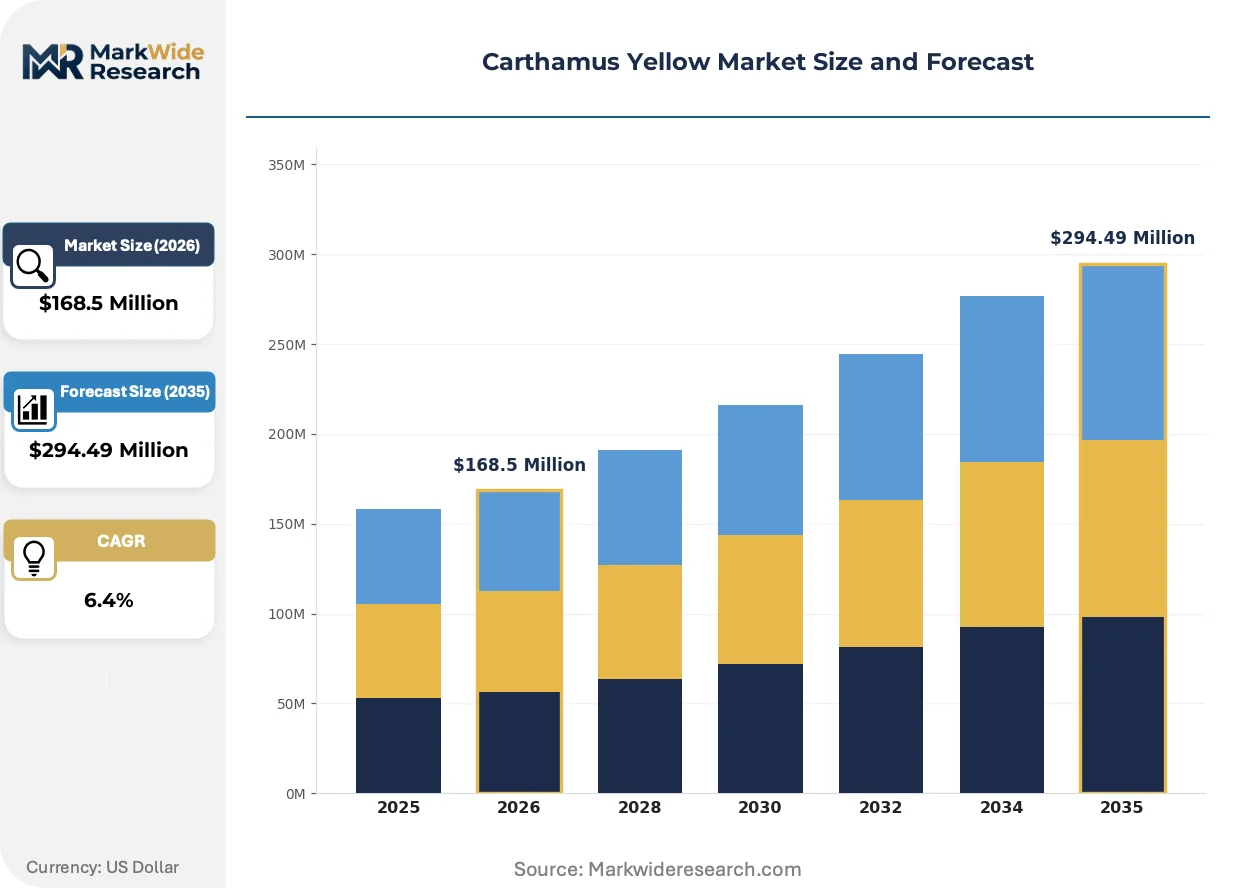
| Market Size in 2026 | $168.5 Million |
| Market Size in 2035 | $294.49 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granule, Liquid, Concentrate Application: Food Coloring, Cosmetics, Textiles, Pharmaceuticals End User: Food Industry, Personal Care, Textile Manufacturers, Chemical Industry Distribution Channel: Online Retail, Wholesale, Direct Sales, Distributors |
| Companies Covered | Hansen Holding A/S, Guixi Huakang Natural Pigment Factory, Qingdao Pengyuan Kanghua Natural Source Co. Ltd., Zhejiang Binmei Biotechnology Co. Ltd., Yunnan Tonghai Yang Natural Products Co. Ltd., Shaanxi Fuheng Biotechnology Co. Ltd., Glico Nutrition, Kanegrade Ltd., Avantor Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carthamus Yellow Market Strategic Shifts
Extraction technology and regulatory compliance frameworks are actively compressing supplier qualification cycles while expanding addressable application categories beyond traditional food coloring.
Modular concentrate-to-powder formulation systems are modularizing production economics across the Carthamus Yellow supply chain. Mid-scale extractors in Jiangxi and Shandong provinces are adopting standardized drying skids that reduce batch-to-batch color variance. This modularity is enabling toll manufacturing arrangements where food brands retain formulation IP while outsourcing pigment production to certified third parties.
REACH Annex XIV authorization requirements for certain synthetic azo dyes are accelerating natural pigment substitution in EU confectionery and beverage applications. The industrial consequence is a qualification backlog at EFSA-notified bodies for novel food additive safety dossiers. German and Dutch processed food manufacturers are responding by pre-qualifying Chinese extractors with existing USP or JP compliance histories to bypass lengthy toxicology reviews.
Buyer concentration among multinational food conglomerates is compressing supplier negotiation leverage and extending payment terms from 60 to 90 days. Regional extractors in China's Jiangxi province are responding by forming supply cooperatives that aggregate volume commitments and share analytical testing infrastructure. This consolidation pattern is most visible in the dairy and confectionery verticals where three global buyers account for the majority of certified natural pigment procurement.
Carthamus Yellow Market Segmentation
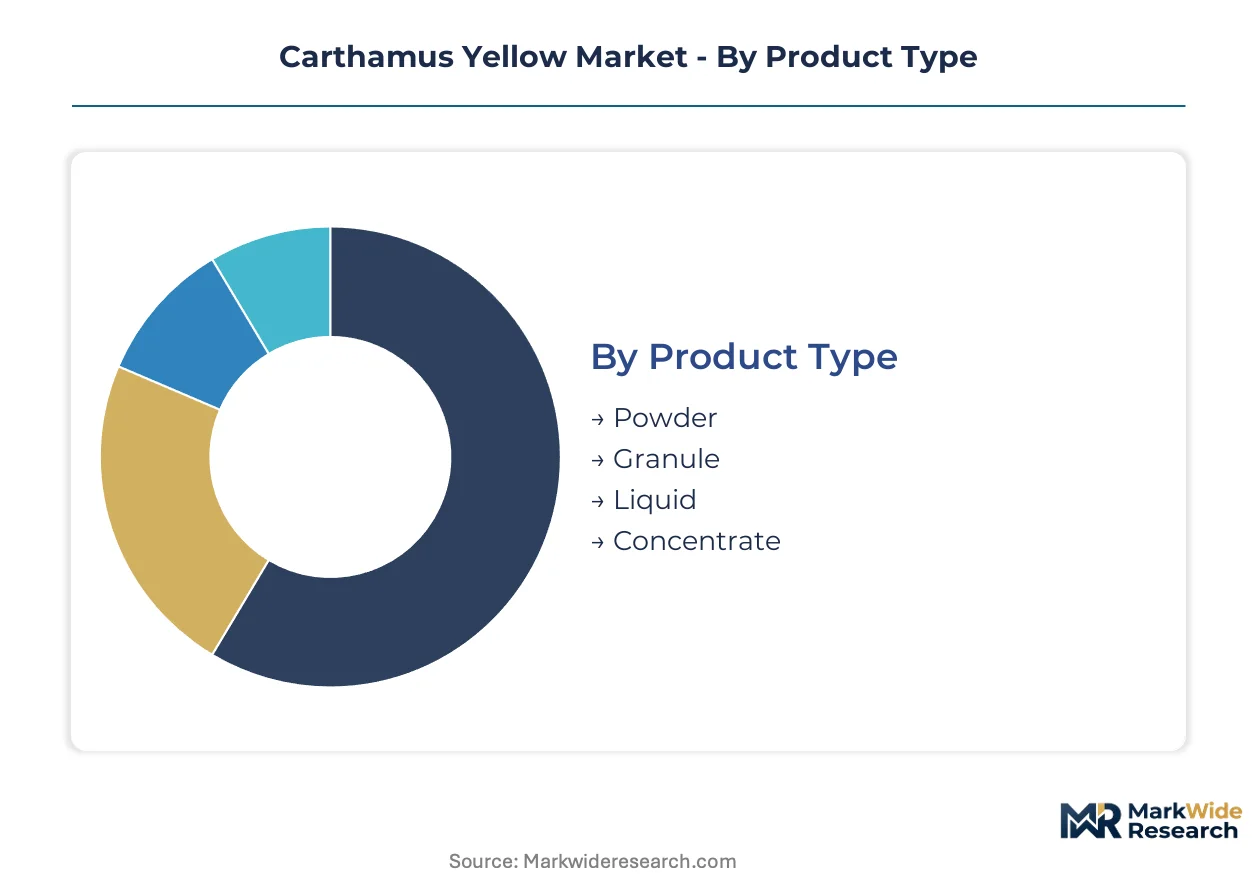
Carthamus Yellow procurement patterns diverge sharply between standalone pigment sales and embedded formulation systems. Powder formats dominate dry-blend food manufacturing, while liquid concentrates integrate directly into continuous beverage processing lines. Understanding these integration pathways clarifies why extraction technology investments cluster around specific end-use specifications rather than generic color value outputs.
Product Type:
Integration depth varies dramatically across physical formats, with standalone powders requiring downstream processing versus concentrates designed for immediate dosing.
- Powder:Spray-dried particles standardized to E50-E150 color values enable ambient storage stability and seamless dry-blending into flour mixes, seasonings, and powdered beverages. Food manufacturers in China's Shandong province specify powder grades for infant formula applications where GB 2760 synthetic dye restrictions apply.
- Liquid:Aqueous solutions with controlled viscosity allow direct injection into beverage pasteurization lines and confectionery syrup cookers. Dairy processors in Zhejiang province favor liquid formats for yogurt fruit preparations where batch-to-batch color consistency determines shelf appeal.
- Granule:Agglomerated particles bridge powder flowability and liquid dispersibility for intermediate processing stages. Tablet coating operations in pharmaceutical applications specify granule grades for uniform film distribution.
- Concentrate:High-potency extracts requiring dilution prior to use, typically supplied to toll manufacturers with proprietary formulation IP. Concentrate procurement concentrates among multinational food conglomerates with captive blending facilities.
Volume placements concentrate in Powder; the faster expansion belongs to Liquid.
Application:
Cost tier differentiation separates commodity food coloring from premium pharmaceutical and cosmetic grades with stringent purity documentation.
- Food Coloring:Acidic to neutral pH applications in confectionery, dairy, and beverages drive baseline demand. EFSA Regulation 1333/2008 compliance enables Chinese extractors to supply European processed food channels without redundant safety dossiers.
- Pharmaceuticals:Excipient-grade natural colorants for tablet film coatings and capsule shells command analytical documentation exceeding food-grade requirements. USP monograph inclusion would unlock direct supply to North American generic drug manufacturers.
- Cosmetics:Colorant applications in skincare and personal care products require additional heavy metal and microbial testing protocols. Formulators specify Carthamus Yellow for lip and eye products where synthetic dye substitution aligns with clean-label positioning.
- Textiles:Traditional dyeing applications for natural fiber coloration persist in artisanal and heritage production segments. Textile demand remains constrained by synthetic dye cost advantages in bulk apparel manufacturing.
Food Coloring captures the largest volume footprint; Pharmaceuticals is climbing the fastest on compendial recognition prospects.
End User:
Customer type fragmentation creates distinct procurement patterns between multinational volume buyers and specialized niche processors.
- Food Industry:Infant formula, dairy, confectionery, and beverage manufacturers constitute the primary demand base. SAMR enforcement of synthetic dye restrictions in school food categories directly expands qualified natural pigment procurement among domestic Chinese processors.
- Personal Care:Cosmetic formulators and contract manufacturers specify Carthamus Yellow for color cosmetics and skincare applications. Clean-label positioning in premium beauty segments drives specification above commodity food-grade pricing.
- Textile Manufacturers:Natural fiber processors and heritage craft producers maintain steady demand for traditional safflower-derived colorants. Volume remains limited by competition from petrochemical dyes in mass-market apparel.
- Chemical Industry:Reagent and analytical standard producers require high-purity hydroxysafflor yellow A for reference material production. This segment demands HPLC-certified batches with documented chromatographic purity.
The Food Industry anchors current volume; Personal Care is gaining share fastest on premium positioning.
Distribution Channel:
Supply concentration in extraction clusters shapes channel selection, with proximity to Jiangxi and Shandong facilities favoring direct procurement over intermediated flows.
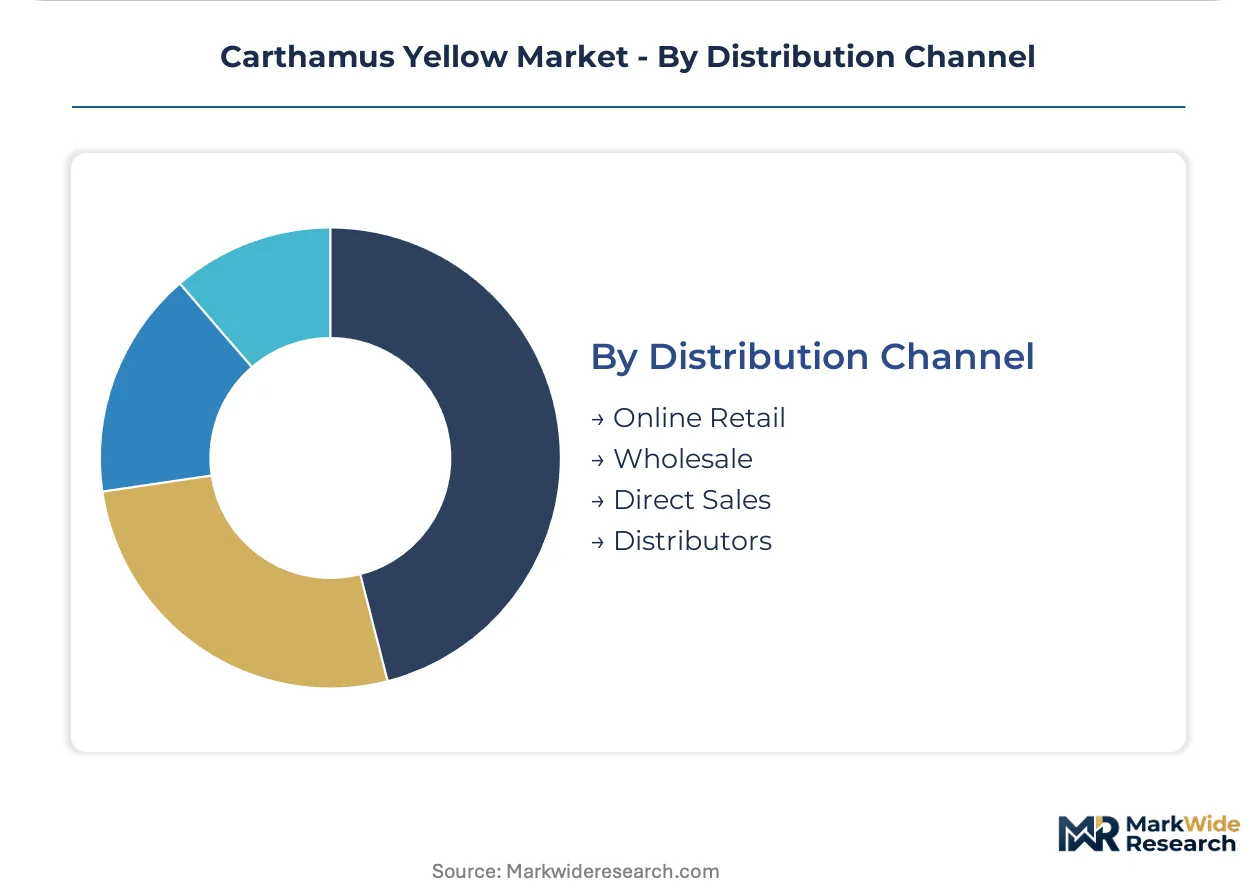
- Direct Sales:Multinational food conglomerates negotiate long-term supply agreements with certified extractors, extending payment terms to 90 days. Direct relationships enable custom color value specification and joint stability testing protocols.
- Distributors:Regional chemical and ingredient distributors aggregate smaller volume orders from mid-scale food processors. Inventory holding at distributor warehouses reduces lead times for buyers lacking just-in-time logistics capabilities.
- Wholesale:Bulk commodity traders handle standardized powder grades for buyers with flexible specification requirements. Wholesale channels dominate textile and traditional food applications with less stringent certification needs.
- Online Retail:E-commerce platforms serve artisanal food producers, small cosmetic formulators, and research laboratories requiring sample quantities. Online channels remain marginal for industrial-scale procurement.
Direct Sales commands the dominant volume position; Distributors show the steepest expansion trajectory among mid-scale processor segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China dominates Carthamus Yellow extraction capacity while consumption spreads across Asia-Pacific food processing hubs and European pharmaceutical channels. The production-consumption divide shapes procurement logistics and regulatory compliance pathways.
China
Shandong and Zhejiang provinces concentrate safflower cultivation and extraction facilities serving domestic infant formula and dairy processors. SAMR enforcement of GB 2760 synthetic dye restrictions in school food categories directly expands qualified natural pigment procurement. Jiangxi province hosts toll manufacturing arrangements where regional extractors aggregate volume commitments for multinational buyers.
India
Domestic dairy and confectionery manufacturers drive natural colorant specification as clean-label positioning penetrates mass-market brands. FSSAI notification on natural colorant purity specifications creates compliance thresholds favoring established extractors with HPLC analytical capabilities. Maharashtra and Gujarat food processing corridors concentrate demand from mid-scale processors upgrading from synthetic dyes.
Germany
REACH Annex XIV authorization requirements for synthetic azo dyes accelerate natural pigment substitution in confectionery and beverage applications. EFSA Regulation 1333/2008 enables Chinese extractors to supply European processed food channels without redundant toxicology testing. North Rhine-Westphalia chemical distributors pre-qualify Asian suppliers with existing pharmacopeial compliance histories.
United States
Pharmaceutical excipient demand for tablet film coatings outpaces food-grade growth as drug manufacturers replace synthetic lake pigments. FDA guidance on natural colorant specifications in dietary supplements creates documentation requirements that favor suppliers with USP reference standards. New Jersey and California formulation hubs source certified extracts for generic drug manufacturing pipelines.
Japan
Cosmetic and personal care formulators specify Carthamus Yellow for color cosmetics where synthetic dye substitution aligns with premium clean-label positioning. METI standards on natural ingredient labeling in functional foods expand addressable applications beyond traditional coloring. Osaka and Tokyo metropolitan areas concentrate demand from skincare brands targeting export markets.
Carthamus Yellow Market Competitive Environment
The competitive structure tilts toward regional extraction specialists with certified analytical capabilities rather than diversified multinational ingredient portfolios. Mid-scale Chinese facilities dominate botanical extraction capacity while European and Japanese players anchor premium pharmaceutical-grade positioning. Two archetypes define the field: province-clustered extractors with toll manufacturing flexibility, and fermentation-technology holders with hybrid pigment platforms. Capacity expansion and dual certification timelines constitute the dominant competitive moves, with FSSC 22000 and excipient-grade GMP qualification extending facility commissioning by 14-18 months.
Among China-based extraction specialists, Guixi Huakang Natural Pigment Factory and Zhejiang Binmei Biotechnology Co. Ltd. occupy positions within the Jiangxi and Zhejiang provincial clusters where safflower processing infrastructure concentrates. Hansen Holding A/S represents the fermentation-technology archetype, anchoring premium natural colorant portfolios through microbial pigment platforms that reduce agricultural land dependency. These three companies exemplify the geographic and technological bifurcation shaping supplier qualification dynamics across food and pharmaceutical end-use channels.
| Leading Market Players |
|---|
| Hansen Holding A/S |
| Guixi Huakang Natural Pigment Factory |
| Qingdao Pengyuan Kanghua Natural Source Co. Ltd. |
| Zhejiang Binmei Biotechnology Co. Ltd. |
| Yunnan Tonghai Yang Natural Products Co. Ltd. |
| Shaanxi Fuheng Biotechnology Co. Ltd. |
| Glico Nutrition |
| Kanegrade Ltd. |
| Avantor Inc. |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between excipient-grade GMP and food-grade FSSC 22000 facilities manifests in both procurement premiums and supply chain consolidation patterns across China's Jiangxi and Shandong extraction clusters. Buyers with dual qualification requirements face extended commissioning timelines that compress supplier pools and elevate contract pricing power for certified incumbents.
Pricing Analysis
Cost-down pressure on pharmaceutical-grade batches accelerates because generic drug manufacturers demand USP-compliant documentation ahead of compendial monograph inclusion. Three-tier pricing structure across excipient-grade, food-grade, and technical-grade levels separates buyers by analytical stringency, with infant formula processors in Shandong showing least price sensitivity due to SAMR enforcement mandates and wholesale textile buyers exhibiting maximum elasticity.
Supply Chain Analysis
Regional distribution centers in Zhejiang and Jiangxi provinces anchor hub-and-spoke patterns that aggregate safflower floret intake from Shandong and Xinjiang cultivation zones. Raw material supply draws from seasonal agricultural harvests, HPLC-certified reference standards, and fermentation-derived pigment platforms. Single-origin crop concentration in China's northern provinces exposes processors to weather volatility. Distribution runs through toll manufacturing arrangements where multinational buyers retain formulation IP.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
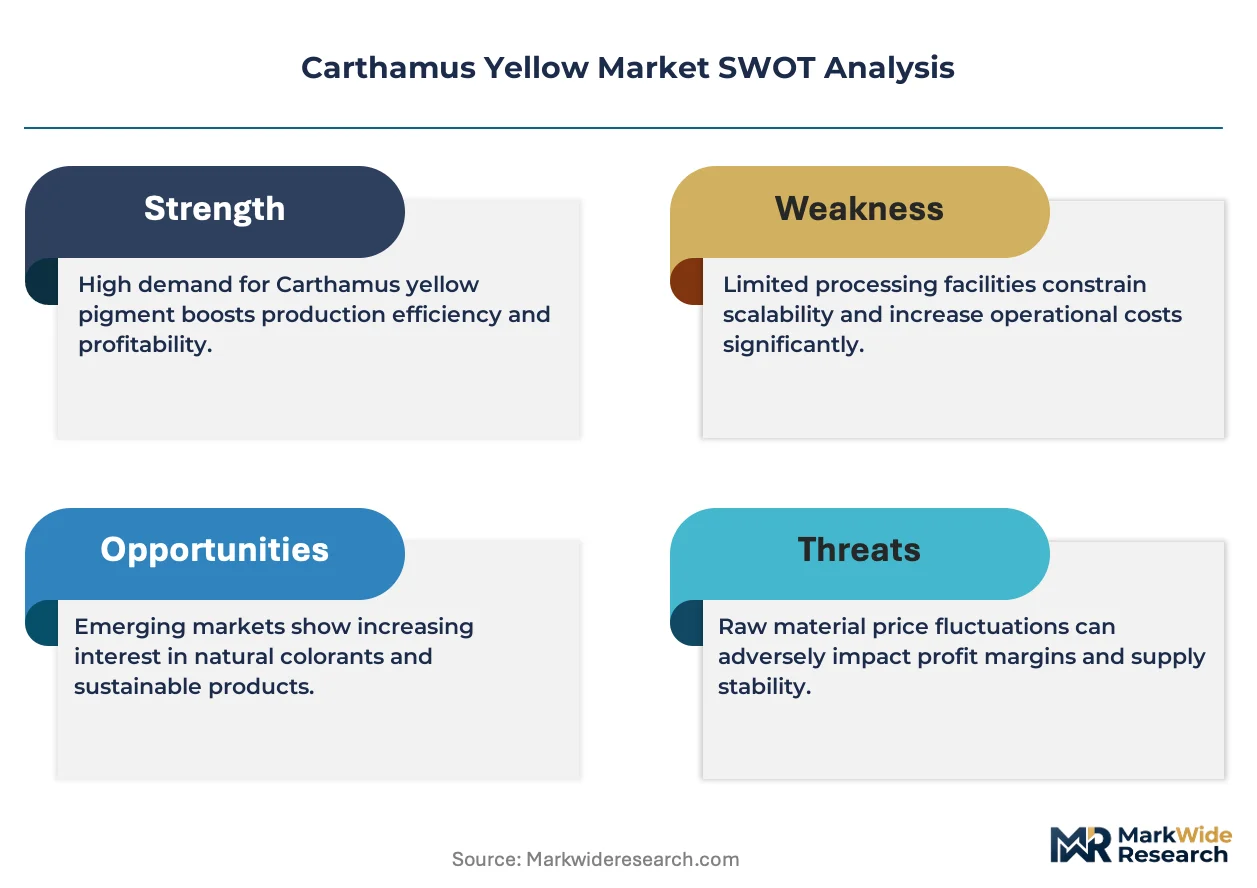
This market functions as a cost-of-compliance story where China's SAMR GB 2760 infant food restrictions erect analytical capability barriers that protect qualified extractors with existing HPLC-DAD infrastructure.
For Market Incumbents: To counter analytical chemist scarcity concentrated in Jiangsu and Zhejiang university pipelines, expand captive training partnerships with regional technical institutes and deepen backward integration into safflower seed breeding programs in Xinjiang. Dual FSSC 22000 and excipient-grade GMP certification investments extend facility commissioning timelines but lock in multinational buyer relationships with 90-day payment terms. For New Entrants and Emerging Players: Toll manufacturing partnerships with established Jiangxi extractors offer the most penetrable entry vector for food-grade powder production without dual certification capital burdens. Target mid-scale dairy processors in India's Maharashtra and Gujarat corridors upgrading from synthetic dyes under FSSAI purity notifications. Lead with ISO 22000-certified spray-dried powder grades and documented E50-E150 color value consistency. For Investors and Strategic Acquirers: Re-rating potential sits with fermentation-technology holders given hybrid pigment platforms reduce agricultural land dependency and decouple production from safflower crop cycles. Long-term viability favors extractors with existing pharmacopeial compliance histories that bypass EFSA dossier backlogs. Monitor USP and EP monograph inclusion timelines as the critical inflection signal for pharmaceutical excipient market access.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | FSSC 22000 and excipient-grade GMP qualification extends commissioning by 14-18 months but secures multinational buyer lock-in. |
| Backward Integration into Seed Breeding | Xinjiang safflower cultivation control reduces single-origin supply risk from Shandong weather volatility. |
| Toll Manufacturing Partnership | Food brands retain formulation IP while outsourcing pigment production to certified third parties in Jiangxi. |
| HPLC-DAD Capability Expansion | Analytical infrastructure investments address FSSAI purity thresholds that favor established extractors in India. |
| Pharmacopeial Monograph Pursuit | USP and EP inclusion unlocks direct supply to North American and European generic drug manufacturers. |
Study Parameters
Trade databases, customs records, and pharmacopeial submission filings formed the secondary backbone, supplemented by primary interviews with extraction facility technical directors, infant formula procurement managers, pharmaceutical excipient quality leads, and natural colorant distributors across China and India. Bottom-up and top-down triangulation validated volume estimates against safflower cultivation data and pigment production capacity disclosures.
Bottom-up modeling anchored demand-side estimates across powder, liquid, granule, and concentrate formats while top-down cross-checks applied end-use industry consumption patterns. Segmentation dimensions included physical format, application category, end-user type, and distribution channel. CAGRs derived from regression analysis against regulatory enforcement timelines and substitution elasticity parameters for synthetic dye displacement.
Several conditions sit outside the modeled scope, including unforeseen pharmacopeial monograph rejection, extreme weather events affecting Xinjiang safflower yields, and abrupt tariff adjustments on natural extract imports. Forecasts reflect documented assumptions around SAMR enforcement continuity and EFSA recognition stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Dried Herbs Market
Spices and Seasonings
Plastic Spice Jars Market
Spices and Seasonings
White Pepper Market
Spices and Seasonings
Spice Oils and Oleoresins Market
Spices and Seasonings
North America Seasonings Market
Spices and Seasonings
US Spice and Seasonings Market
Spices and Seasonings
Spices and Seasonings Market
Spices and Seasonings
Cardamom Market
Spices and Seasonings
Boutique Salt Market
Spices and Seasonings
Paprika Color Market
Spices and Seasonings
Tamarind Extract Market
Spices and Seasonings
Dried Spices Market
Spices and Seasonings
Onion Salt Market
Spices and Seasonings
Sriracha Market
Spices and Seasonings
Spices Market
Spices and Seasonings
Thyme Extract Market