
 Low Sodium Sea Salt Market | 2026-2036
Low Sodium Sea Salt Market Size, Share, and Industry Trends Forecast 2026-2036
Low Sodium Sea Salt Market Foresight
Supermarket private-label consolidation is rebalancing procurement leverage toward large retail banners. Cargill leverages its integrated salt-evaporation infrastructure to secure cost advantages across North American supply contracts. Morton Salt anchors shelf presence through established broker networks in conventional grocery. Himalayan Chef differentiates via mineral-content storytelling aimed at premium household segments.
Low sodium sea salt denotes evaporated marine salt with reduced sodium content, typically achieved through potassium chloride blending or crystal-structure modification, yielding formulations with 25% to 50% less sodium than standard sea salt while maintaining salinity perception for food preservation and flavor enhancement. The product serves industrial food processors seeking reformulation compliance alongside health-positioned consumer brands. Table salt and cooking salt categories dominate volume throughput due to universal kitchen penetration, while gourmet salt commands disproportionate margin pools through artisan positioning and limited-batch scarcity. Food processing end users represent the structurally fastest-growing demand node as multinational manufacturers reformulate legacy recipes ahead of tightening sodium thresholds.
FDA sodium reduction targets and WHO global sodium benchmarks are forcing reformulation timelines across packaged food portfolios. EFSA nutrition claims regulation shapes permissible front-of-pack labeling across European export destinations, conditioning market access criteria. Stakeholders must monitor evolving potassium chloride supply constraints and regional evaporative yield volatility as dual determinants of formulation cost stability.
Market Dynamics
Reformulation mandates from FDA and WHO are compressing sodium thresholds across packaged food portfolios, forcing ingredient suppliers to reengineer crystal structures and potassium chloride blends at industrial scale.
Growth Catalysts
- Regulatory Compression:FDA sodium reduction targets and WHO global benchmarks are accelerating procurement timelines for reduced-sodium inputs among multinational food processors.
- Food Processing Demand:Industrial reformulation of legacy recipes in ready meals, snacks, and bakery categories is pulling bulk volumes of modified sea salt formulations.
- Potassium Chloride Infrastructure:Dedicated evaporation facilities in coastal regions are securing captive supply chains for mineral-blended salt production.
Market Restraints
- Input Cost Volatility:Potassium chloride spot pricing fluctuates with fertilizer market cycles, destabilizing formulation cost structures for mid-tier suppliers.
- Technical Limitations:Crystal-structure modification techniques struggle to replicate exact salinity perception above 50% sodium reduction thresholds without metallic off-notes.
- Regulatory Friction:EFSA nutrition claims regulation imposes strict front-of-pack labeling conditions that limit health-positioning flexibility in European export markets.
Strategic Opportunities
- Underpenetrated Channels:Direct-to-foodservice distribution bypasses retail margin stacking for institutional buyers in healthcare and education catering segments.
- Technology Convergence:Precision fermentation-derived salt enhancers are pairing with modified crystal structures to amplify perceived salinity at lower sodium loads.
- Certification-Driven Positioning:Organic and marine-stewardship certifications are opening premium shelf placement in European and North American natural grocery channels.
Industry Challenges
- Specialized Talent Scarcity:Food formulation chemists with dual expertise in sensory science and mineral chemistry command premium compensation, constraining R&D expansion.
- Capex Intensity:Solar evaporation pond construction and potassium chloride storage infrastructure require substantial upfront investment with 7-10 year payback horizons.
- Integration Complexity:Reformulated salt crystals often require line-speed adjustments and recalibration of automated seasoning equipment in legacy processing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Sodium Sea Salt Market |
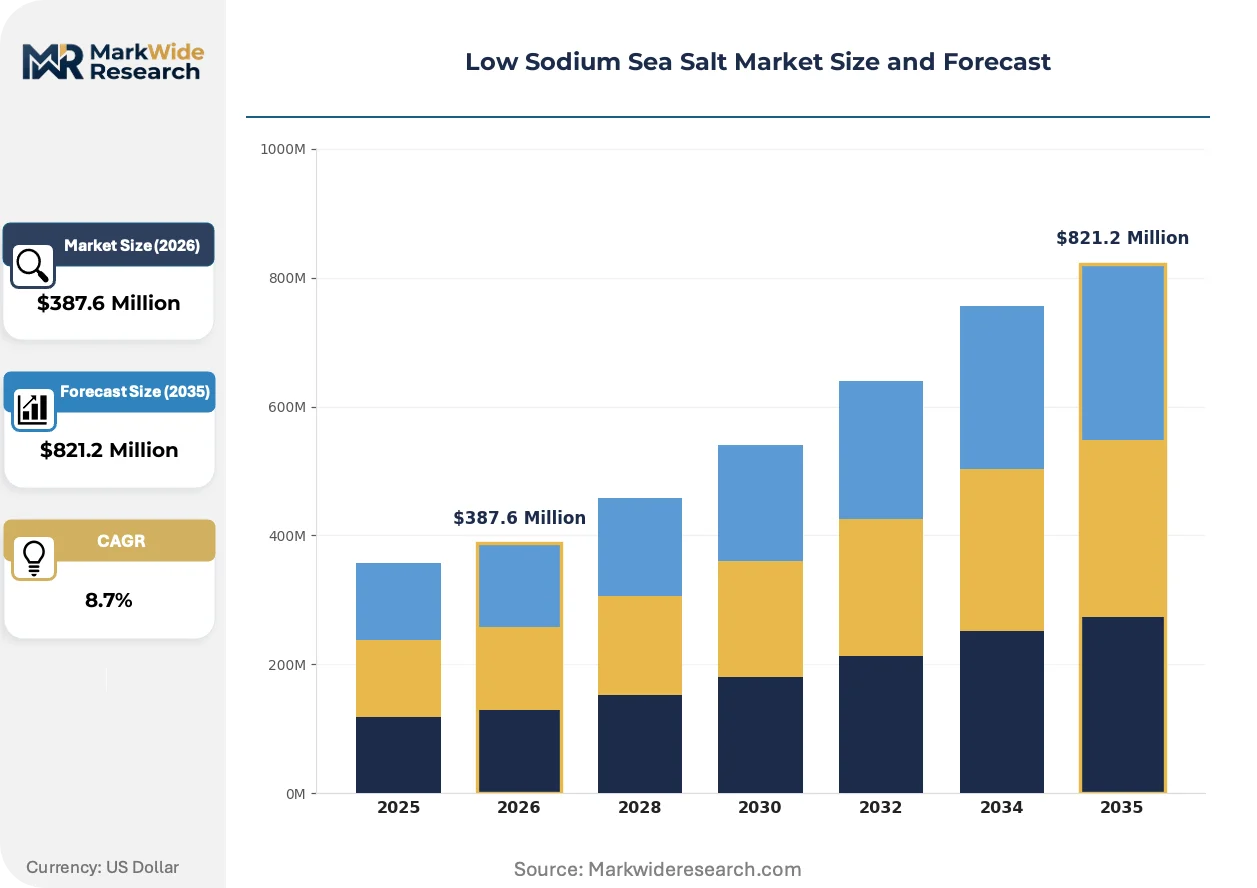
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Table Salt, Cooking Salt, Gourmet Salt, Seasoning Salt Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Wholesale Distributors End User: Households, Restaurants, Food Processing, Healthcare Facilities Packaging Type: Bags, Boxes, Shakers, Bulk Containers |
| Companies Covered | Sodium Solutions, Himalayan Chef, Cargill, K+S Aktiengesellschaft, Maldon Salt, Kraft Heinz, Tate & Lyle, Nippon Shokubai, Morton Salt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Sodium Sea Salt Market Shifts & Advancements
Active reformulation across packaged food categories is driving parallel innovation in salt crystal engineering, mineral blending protocols, and sensory masking technologies to maintain consumer acceptance under reduced sodium loads.
Microencapsulation technology is converging with potassium chloride delivery systems to time-release mineral ions and suppress bitter metallic aftertastes in reduced-sodium formulations. Snack manufacturers are piloting these structures in seasoned chip and cracker applications. The technology is converging with clean-label positioning requirements to enable front-of-pack sodium claims without artificial additive disclosures.
EFSA nutrition claims regulation is tightening permissible health messaging on reduced-sodium products sold into European Union member states. Front-of-pack labeling restrictions now require precise sodium-per-serving thresholds before "reduced salt" claims appear. Bakery and ready-meal exporters to Germany, France, and Italy are reformulating recipes to secure compliant positioning ahead of enforcement phase-ins.
Foodservice procurement teams are consolidating supplier relationships and demanding volume-tiered pricing with embedded reformulation technical support. Broadline distributors are displacing fragmented broker networks for mid-scale restaurant chains seeking consistent sodium-reduction specifications. This consolidation is most visible in United States healthcare foodservice contracts where dietary sodium compliance carries regulatory audit weight.
Low Sodium Sea Salt Market Segmentation
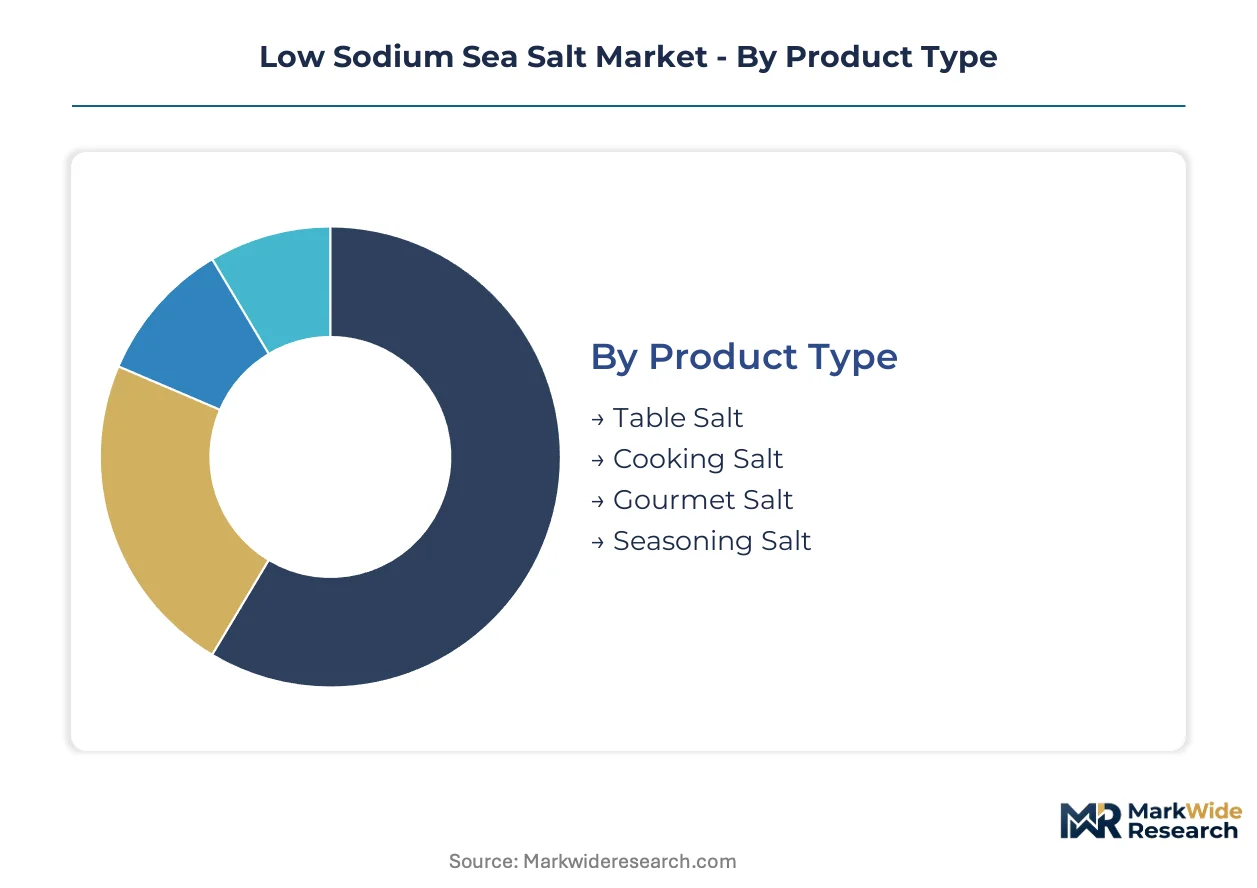
Low sodium sea salt manufacturers must align formulation specifications with distinct usage contexts across kitchen, industrial, and institutional environments. Segment-specific packaging, mineral profiles, and distribution pathways determine margin capture and compliance positioning.
Product Type:
Reformulation cycles in packaged food are driving upgrade demand from standard sodium-reduced grades toward engineered crystal structures with enhanced salinity perception.
- Table Salt:Fine-grain potassium chloride blends dominate household tabletop use, with 25% to 50% sodium reduction achieved through mineral substitution. United States retail shelves concentrate volume placements as FDA labeling mandates push consumers toward reformulated options. The segment absorbs cost volatility through high-turnover private-label contracts with supermarket banners.
- Cooking Salt:Coarse crystal formulations dissolve at controlled rates for stovetop applications, requiring modified evaporative processes to maintain flake integrity. Food processing facilities in the United States pull bulk volumes for recipe reformulation ahead of sodium threshold enforcements. Crystal size distribution directly impacts line-speed compatibility in automated seasoning systems.
- Gourmet Salt:Artisan positioning leverages trace mineral content and geographic origin claims for premium household segments.
- Seasoning Salt:Pre-blended herb and spice combinations target convenience-oriented cooking applications with integrated sodium reduction.
Volume placements concentrate in Table Salt; the faster expansion belongs to Cooking Salt as industrial reformulation accelerates.
Distribution Channel:
Procurement leverage is shifting toward consolidated retail banners and direct institutional contracts, compressing margins for fragmented broker networks.
- Supermarkets:Private-label consolidation at Walmart, Kroger, and Albertsons banners concentrates procurement power, forcing suppliers into volume-tiered pricing with embedded technical support. Shelf placement demands compliant nutrition labeling aligned with FDA sodium disclosure rules. The channel captures the majority of household volume through conventional grocery penetration.
- Online Retailers:Amazon and Thrive Market enable direct-to-consumer mineral-content storytelling for premium-positioned brands. Subscription models lock in recurring revenue for health-positioned households seeking consistent sodium-reduction specifications. The channel bypasses traditional slotting fees while demanding fulfillment infrastructure investments.
- Specialty Stores:Natural grocery banners like Whole Foods and Sprouts command organic and marine-stewardship certifications for shelf access.
- Wholesale Distributors:Broadline operators including Sysco and US Foods consolidate foodservice procurement with embedded reformulation consulting.
Supermarkets anchor current volume; Online Retailers are climbing the fastest as direct-to-consumer health positioning gains traction.
End User:
Application requirements diverge sharply between sensory-perception priorities in household cooking and compliance-driven specifications in institutional settings.
- Households:Health-conscious consumers drive demand for front-of-pack sodium claims, accepting potassium chloride blends despite subtle metallic notes. United States residential kitchens concentrate volume through retail replenishment cycles. Taste acceptance thresholds limit achievable sodium reduction without sensory masking technologies.
- Food Processing:Multinational manufacturers reformulate legacy recipes in ready meals, snacks, and bakery categories to meet FDA sodium reduction targets. Bulk procurement contracts specify crystal-size distribution and dissolution rates for automated line compatibility. The segment commands technical support resources for recipe reformulation and equipment recalibration.
- Restaurants:Foodservice operators seek consistent seasoning performance across menu items with simplified inventory management.
- Healthcare Facilities:Hospital and long-term care dietary departments face regulatory audit pressure for sodium compliance in patient meals.
Households retain the largest volume footprint; Food Processing shows the steepest expansion trajectory as reformulation mandates compress timelines.
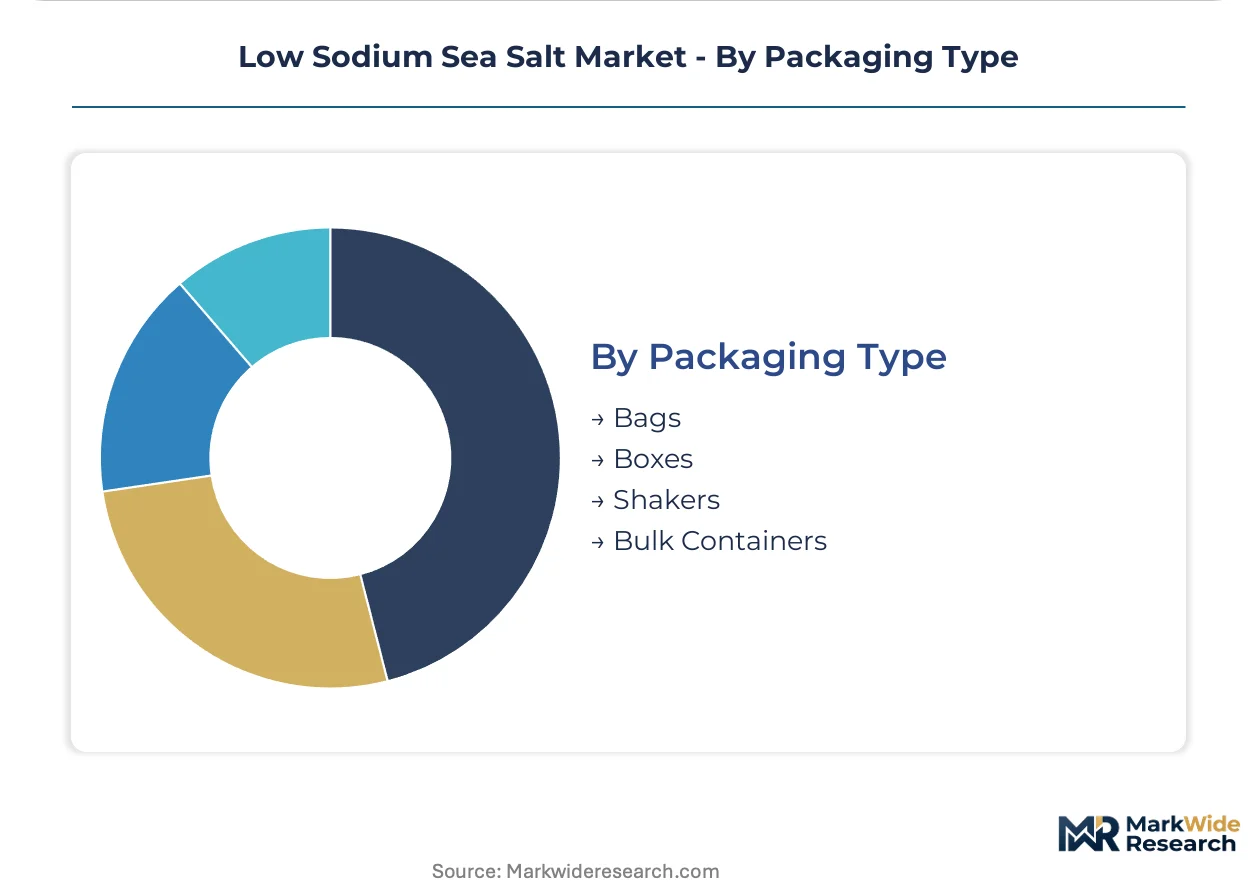
Packaging Type:
Cost-to-serve economics and handling requirements shape format selection across retail, industrial, and institutional procurement pathways.
- Bulk Containers:Industrial totes and supersacks serve food processing facilities with high-volume, low-frequency replenishment cycles. Palletized logistics minimize per-unit handling costs for manufacturers operating dedicated evaporation infrastructure. The format dominates total volume throughput through direct mill-to-plant supply arrangements.
- Shakers:Tabletop dispensing formats with moisture-resistant closures target household convenience and foodservice table settings. United States retail shelves standardize on 26-ounce polyethylene containers with flip-top dispensing. The format commands premium pricing per ounce against bulk alternatives.
- Bags:Flexible pouches serve cooking salt applications with resealable closures for kitchen pantry storage.
- Boxes:Paperboard cartons enable premium gift positioning and sampler assortments for gourmet salt collections.
Bulk Containers capture industrial volume; Shakers are gaining share fastest as retail health positioning drives household conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States food processing facilities concentrate bulk procurement volumes as FDA sodium reduction targets compress reformulation timelines for packaged food manufacturers.
United States
Multinational snack and ready-meal manufacturers drive industrial demand for potassium chloride blended sea salt formulations. FDA sodium labeling mandates and voluntary reduction targets force ingredient procurement shifts across legacy recipes. Midwest processing corridors in Illinois and Ohio anchor bulk supply contracts with dedicated evaporation infrastructure.
Germany
Bakery and ready-meal exporters prioritize EFSA-compliant sodium claims for EU market access. EFSA nutrition claims regulation imposes strict front-of-pack thresholds that condition permissible health messaging. North Rhine-Westphalia food clusters around Cologne and Düsseldorf concentrate reformulation technical service providers.
Japan
Aging demographics and hypertension prevalence accelerate household conversion to reduced-sodium seasonings. METI dietary guidelines and FOSHU functional food labeling shape permissible health-positioning frameworks. Kanto region Tokyo-Osaka corridor dominates premium mineral-salt distribution through established retail pharmacy networks.
United Kingdom
Supermarket private-label consolidation at Tesco, Sainsbury's, and Morrisons compresses supplier margins while demanding reformulation support. FSA salt reduction targets and front-of-pack traffic light labeling drive consumer-facing sodium claims. Midlands manufacturing belt around Birmingham anchors industrial salt blending facilities for processed food exporters.
Australia
Health-conscious households and foodservice operators seek marine-stewardship certified reduced-sodium options. FSANZ nutrition labeling standards and Health Star Rating system condition front-of-pack positioning requirements. Victoria and New South Wales coastal evaporation sites supply domestic processors with modified crystal-structure formulations.
Low Sodium Sea Salt Market Competitive Landscape
North American integrated producers anchor one tier; European specialty salt refiners hold premium positioning through mineral-content differentiation. The vendor base organizes around three strategic archetypes: diversified agribusiness conglomerates with captive evaporation infrastructure, regional salt refiners with broker-network shelf presence, and premium-positioned specialty brands leveraging origin storytelling. Competitive moves concentrate on backward integration into potassium chloride supply chains and direct-to-foodservice distribution bypassing retail margin stacking.
Within the integrated agribusiness tier, Cargill and Morton Salt occupy positions defined by scale-driven supply contract security across North American food processing corridors. Himalayan Chef exemplifies the premium specialty archetype, anchoring mineral-content narratives for health-positioned household segments. K+S Aktiengesellschaft represents European refiner positioning with industrial-grade formulation capabilities serving export compliance requirements.
| Leading Market Players |
|---|
| Sodium Solutions |
| Himalayan Chef |
| Cargill |
| K+S Aktiengesellschaft |
| Maldon Salt |
| Kraft Heinz |
| Tate & Lyle |
| Nippon Shokubai |
| Morton Salt |
| Others |
Supply & Pricing Matrix
Potassium chloride blending technology and modified crystal-structure engineering are simultaneously compressing per-unit production costs and concentrating supply leverage among integrated evaporation facility operators with captive mineral sourcing.
Pricing Analysis
Volume-mass-market tiers absorb commodity potassium chloride spot volatility through long-term offtake contracts, while premium gourmet segments command mineral-content premiums. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and geographic origin claims. Pricing pressure stems from fertilizer market cycle swings destabilizing potassium chloride input costs. Food processing facilities exhibit highest price sensitivity due to bulk procurement scale, whereas health-positioned households accept premium positioning for front-of-pack sodium claims.
Supply Chain Analysis
Regional distribution centers in coastal evaporation zones operate hub-and-spoke patterns feeding Midwest food processing corridors. Supply concentrates in the United States, Germany, and Australia where dedicated solar evaporation infrastructure anchors production. Raw material flows draw from potassium chloride mining operations, marine evaporative yields, and mineral-blending additives. Single-source vulnerability around potassium chloride supply creates structural exposure to fertilizer market disruptions. Distribution runs through direct mill-to-plant bulk arrangements for industrial buyers alongside broker-network retail placement for household segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Evaporation pond construction timelines and potassium chloride storage infrastructure represent binding capacity constraints that prop pricing power for existing facility operators.
For Market Incumbents: To counter potassium chloride spot price volatility, secure captive supply through backward integration into fertilizer-adjacent mineral sourcing and expand dedicated storage infrastructure in coastal evaporation zones. Anchor food processing contracts with embedded reformulation technical support to deepen switching costs. For New Entrants and Emerging Players: Healthcare foodservice procurement teams represent an underserved buyer archetype with regulatory audit-driven sodium compliance requirements and consolidated distributor relationships. Penetrate through direct institutional contracts bypassing retail margin stacking, targeting hospital and long-term care dietary departments with volume-tiered pricing and technical consulting bundles. For Investors and Strategic Acquirers: Exit pathways concentrate in agribusiness conglomerate acquisition of regional salt refiners with broker-network shelf presence and established FDA-compliant formulation capabilities. Long-term viability hinges on potassium chloride supply security and evaporative yield stability. Watch potassium chloride fertilizer market correlation as inflection indicator for input cost compression cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Potassium Chloride Supply | Cargill and integrated operators secure captive mineral sourcing insulated from fertilizer spot volatility. |
| Direct-to-Foodservice Distribution Expansion | Sysco and US Foods consolidate healthcare and education procurement with embedded reformulation consulting. |
| Microencapsulation Technology Licensing | Snack manufacturers pilot time-release mineral delivery suppressing metallic aftertastes in reduced-sodium formulations. |
| Marine-Stewardship Certification Program | Whole Foods and Sprouts demand certified shelf access opening premium natural grocery placement. |
| Precision Fermentation Salt Enhancer Partnership | Technology convergence amplifies perceived salinity at lower sodium loads pairing with modified crystal structures. |
Research Methodology
Trade publications, customs export records, and food formulation patent filings formed the secondary backbone, cross-referenced against primary interviews with salt evaporation facility operators, food processing procurement directors, and supermarket category buyers. Bottom-up and top-down triangulation validated volume estimates across product type, distribution channel, and end-user segments.
Bottom-up modeling built from facility-level evaporation capacity and potassium chloride blending throughput, while top-down analysis tracked FDA sodium reduction target compliance timelines across packaged food portfolios. Segmentation dimensions spanned crystal-structure grade, packaging format, and institutional versus household procurement pathways. CAGRs derived from regression analysis of historical reformulation mandate adoption curves and mineral-substitution technology diffusion rates.
Revisions become necessary when potassium chloride supply disruptions, evaporative yield volatility from climate patterns, or accelerated FDA enforcement timelines materialize outside baseline assumptions. Forecasts reflect documented parameters around regulatory phase-in schedules and mineral-blending technology adoption. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Paprika Color Market
Spices and Seasonings
Gourmet Seaweed Seasoning Market
Spices and Seasonings
Frankincense Extract Market
Spices and Seasonings
Onion Salt Market
Spices and Seasonings
Onion Essential Oil Market
Spices and Seasonings
Sichuan Peppercorn Market
Spices and Seasonings
Wild Cherry Powder Market
Spices and Seasonings
Global Spices and Stimulants Market
Spices and Seasonings
Vanilla Salt Market
Spices and Seasonings
Celery Seed Extract Powder Market
Spices and Seasonings
All-Purpose Seasoning Market
Spices and Seasonings
Ginger Market
Spices and Seasonings
Thyme Extract Market
Spices and Seasonings
Global Clove Market
Spices and Seasonings
Green Pepper Market
Spices and Seasonings
BBQ Seasoning Market