
 Asia-Pacific Operational Risk Management Consulting Services in Manufacturing Market | 2026-2036
Asia-Pacific Operational Risk Management Consulting Services in Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Operational Risk Management Consulting Services in Manufacturing Market Analytics
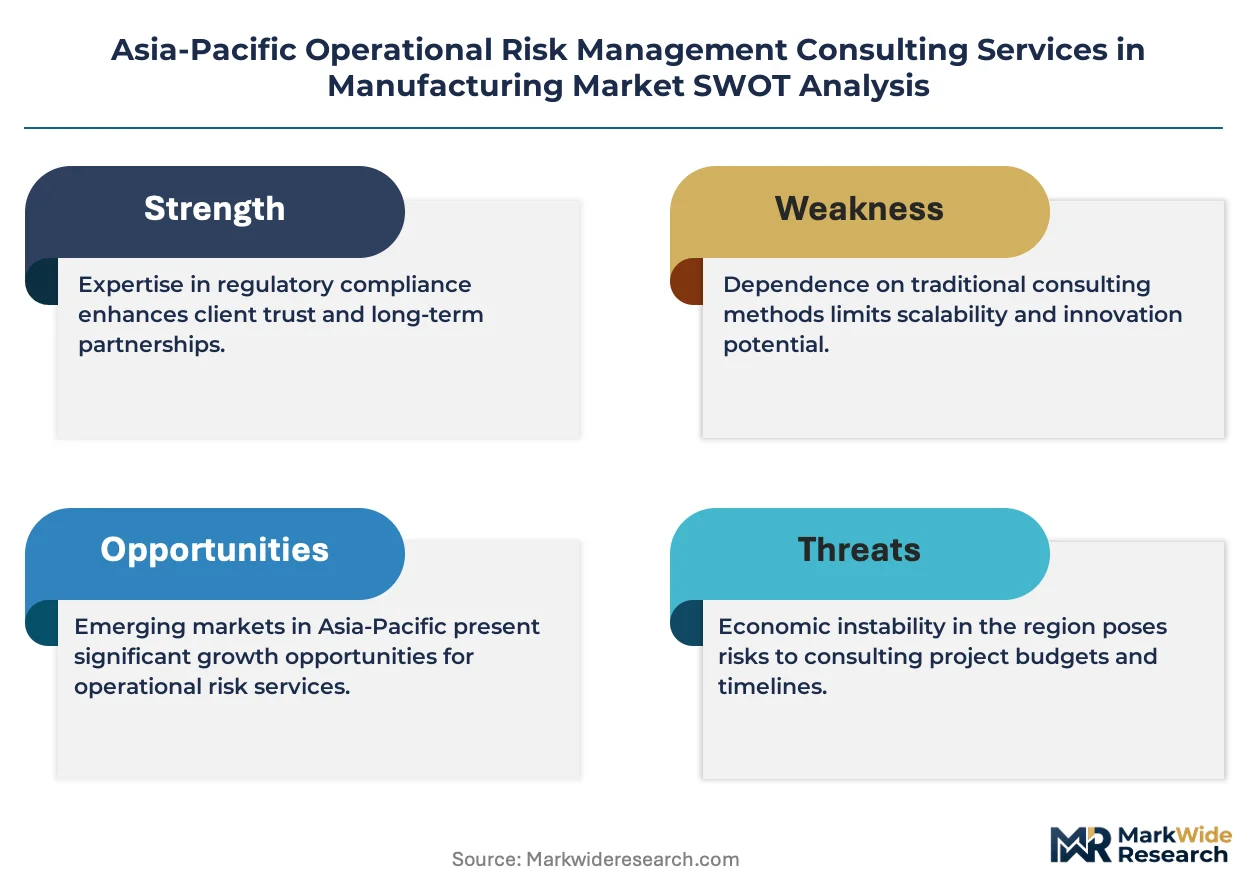
The capability gap between capital-heavy integrated consultancies and boutique risk specialists is bifurcating the competitive landscape. KPMG leverages its regulatory relationships across ASEAN manufacturing hubs to anchor large-scale compliance mandates. Deloitte sustains dominance in crisis management consulting through deep bench strength in Shanghai and Singapore. Oliver Wyman competes narrowly by positioning advanced scenario analytics for semiconductor supply chain disruptions.
Asia-Pacific operational risk management consulting services in manufacturing encompass systematic identification, quantification, and mitigation of production hazards, supply chain failures, and regulatory non-compliance across industrial facilities. These services deploy probabilistic risk models, ISO 31000-aligned frameworks, and real-time monitoring protocols to prevent operational downtime and liability exposure. Risk assessment services command the largest revenue pool as manufacturers face escalating ESG disclosure requirements under Australia's Work Health and Safety Act and Japan's METI guidelines. Compliance consulting represents the fastest-expanding segment as pharmaceutical firms and electronics manufacturers navigate divergent national safety standards. Crisis management retains premium pricing power due to scarcity of consultants with cross-border incident response credentials.
Japan's METI, Australia's Work Health and Safety Act, and China's SAMR collectively shape market access through mandatory safety audits and escalating penalty structures for industrial accidents. These frameworks compel manufacturers to externalize risk expertise rather than build captive capabilities. Stakeholders must monitor regulatory harmonization progress between ASEAN member states to anticipate consolidation or fragmentation of consulting procurement models.
Market Dynamics
Regulatory divergence across ASEAN member states is compelling manufacturers to externalize risk expertise rather than build captive capabilities, creating sustained demand for consulting mandates that bridge compliance gaps.
Growth Catalysts
- Thailand's automotive OEM expansion:Vehicle manufacturers in Rayong and Chonburi industrial zones are mandating ISO 31000-aligned operational risk frameworks for tier-one suppliers.
- Australia's Work Health and Safety Act:Escalating penalty structures for industrial accidents are forcing pharmaceutical and electronics manufacturers to retain external compliance auditors.
- Semiconductor supply chain analytics:Real-time probabilistic risk models for chip fabrication disruptions are driving consulting engagement from foundries in Hsinchu and Singapore.
Market Restraints
- Consultant talent scarcity:Cross-border incident response credentials command premium pricing, limiting boutique firm scalability across Vietnam and Indonesia.
- Regulatory fragmentation:Divergent national safety standards between Japan's METI guidelines and China's SAMR audit requirements increase compliance complexity for regional manufacturers.
- Captive capability temptation:Large integrated manufacturers in Shanghai and Shenzhen are building in-house risk teams, threatening external consulting retention.
Strategic Opportunities
- Philippines electronics manufacturing:Underpenetrated operational risk consulting presence in Cavite and Laguna industrial corridors offers first-mover positioning for scenario analytics specialists.
- ESG disclosure convergence:Australia's mandatory climate risk reporting and Japan's METI safety transparency mandates are creating integrated ESG-operational risk service bundles.
- Digital twin integration:Convergence of IoT sensor networks with predictive risk modeling enables real-time operational monitoring for petrochemical facilities in Singapore's Jurong Island cluster.
Industry Challenges
- Cross-border credential recognition:Consultants certified under Japan's JIS standards face re-certification barriers when deploying to ASEAN manufacturing hubs.
- Legacy system interoperability:Risk monitoring protocols must integrate with decades-old MES and SCADA infrastructure prevalent in Thailand's automotive supplier base.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Operational Risk Management Consulting Services in Manufacturing Market |
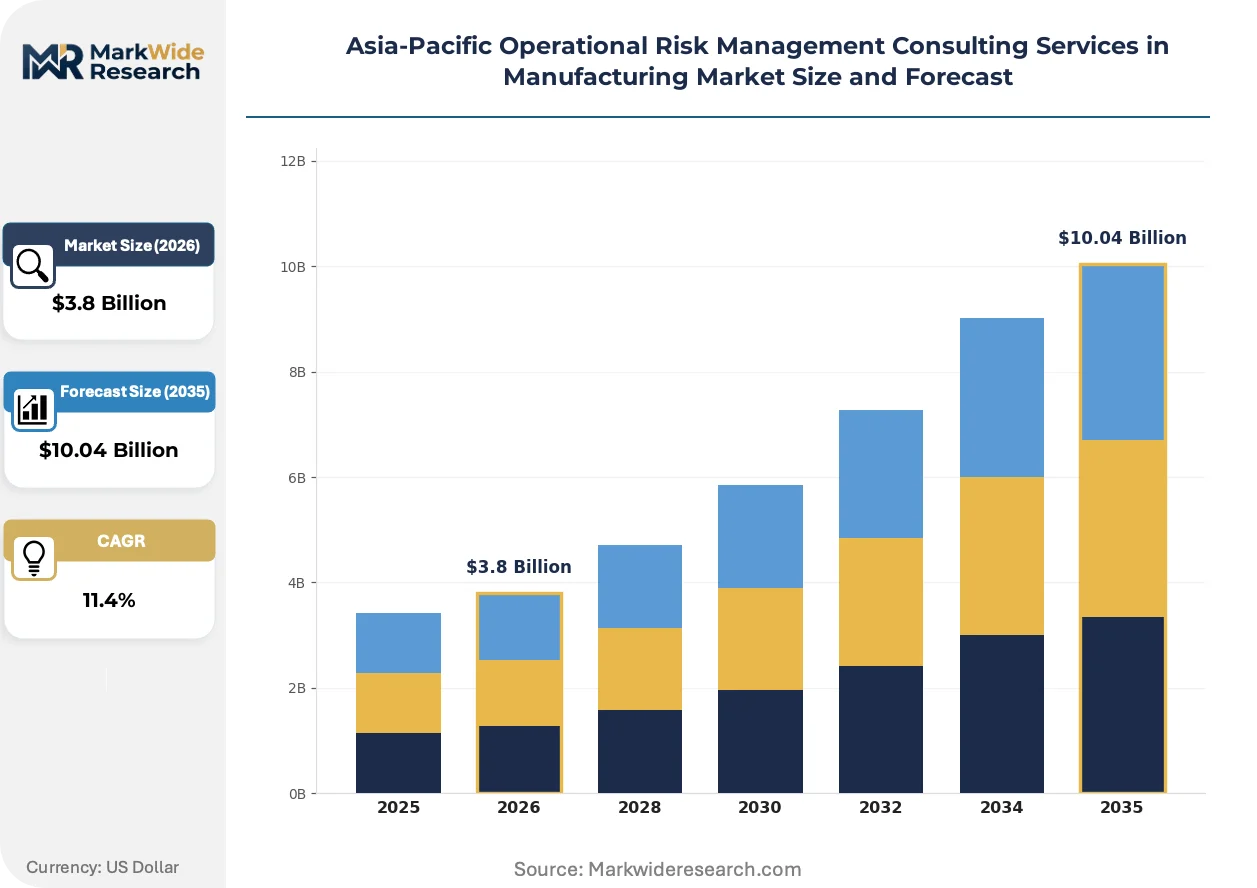
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Risk Assessment, Compliance Consulting, Crisis Management, Business Continuity End User: Automotive OEMs, Food Processing, Electronics Manufacturers, Pharmaceutical Firms Solution Type: Software Solutions, Training Programs, Strategy Development, Audit Services Industry Vertical: Manufacturing, Energy, Aerospace, Consumer Goods |
| Companies Covered | KPMG, Deloitte, PwC, Accenture, EY, McKinsey & Company, Boston Consulting Group, Bain & Company, Oliver Wyman, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Operational Risk Management Consulting Services in Manufacturing Market Evolving Landscape
Artificial intelligence is compressing risk identification cycles from months to days, while regulatory technology mandates are redefining service delivery architectures across Asia-Pacific manufacturing consulting.
Probabilistic risk modeling software is fragmenting traditional consulting value chains by automating scenario generation that previously required senior analyst teams. Semiconductor manufacturers in Taiwan and South Korea are deploying these tools for supply chain disruption simulation. The technology is fragmenting fee structures as automated outputs commoditize baseline risk assessments.
Japan's METI safety guidelines now mandate documented operational risk governance for chemical and heavy machinery producers, compelling external audit trails. Manufacturers must demonstrate continuous monitoring protocols or face production suspension. Electronics OEMs in Osaka and Nagoya industrial belts are consolidating consulting procurement to meet these documentation burdens.
Subscription-based risk monitoring services are displacing project-based consulting engagements among mid-tier automotive suppliers. Tier-two manufacturers in Vietnam's Vinh Phuc and Hai Phong corridors prefer monthly retainers over discrete compliance mandates. This model concentrates revenue visibility for consultancies willing to embed permanent staff in client facilities.
Asia-Pacific Operational Risk Management Consulting Services in Manufacturing Market Segmentation
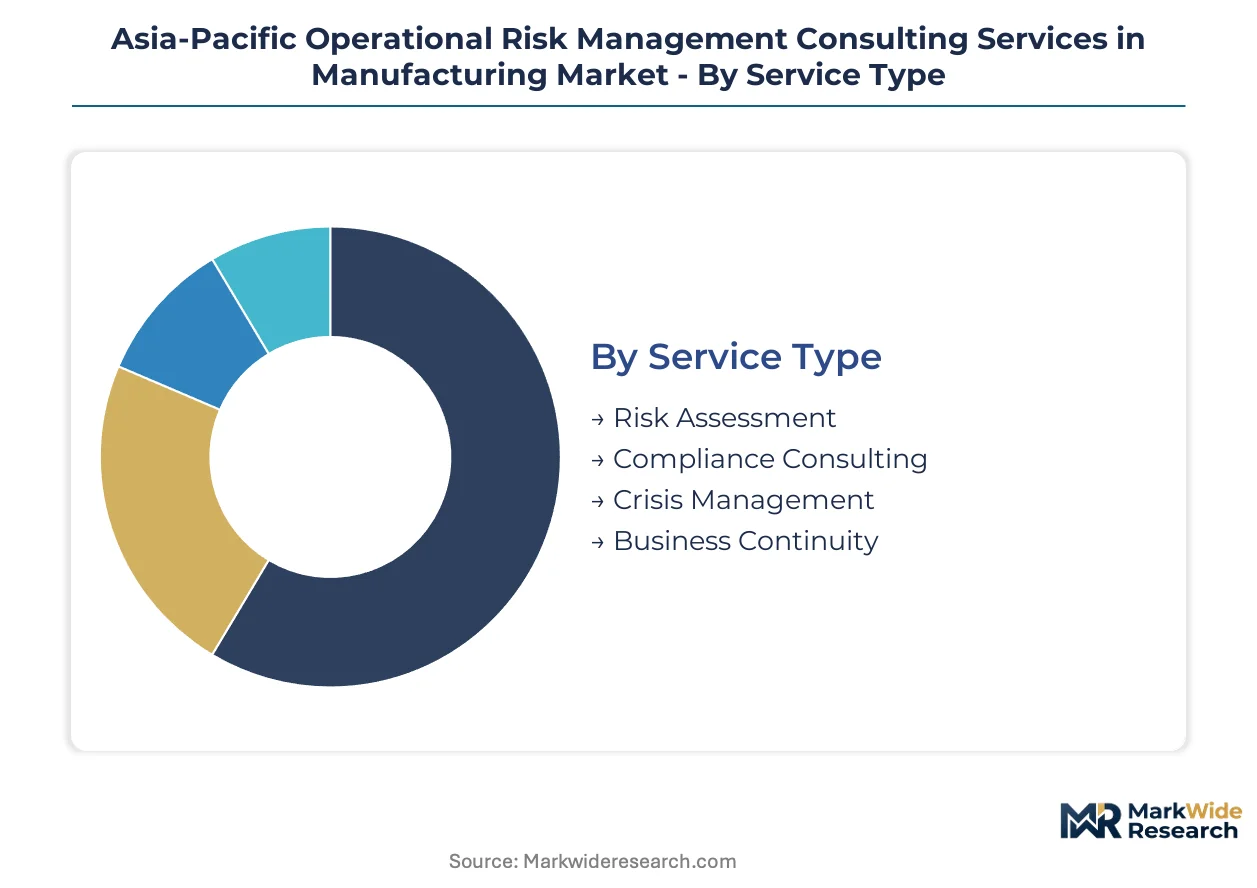
Operational risk consulting in Asia-Pacific manufacturing fragments across service delivery models, end-user sophistication, and technology integration depth. Consulting procurement patterns diverge sharply between integrated global mandates and localized compliance engagements.
Service Type:
Substitution pressure from automated risk platforms threatens baseline assessment services most severely, while high-touch advisory retains pricing power.
- Risk Assessment:Systematic identification and quantification of production hazards, supply chain vulnerabilities, and facility safety gaps using probabilistic models and ISO 31000 frameworks. Demand concentrates in China's Shanghai and Shenzhen industrial clusters, where supply chain complexity drives recurring engagement from electronics and automotive manufacturers facing METI documentation requirements.
- Compliance Consulting:External audit and regulatory alignment services bridging divergent national safety standards across ASEAN manufacturing hubs. Australia's Work Health and Safety Act penalty escalations are forcing pharmaceutical and electronics manufacturers in Victoria and New South Wales to retain continuous compliance oversight rather than discrete project mandates.
- Crisis Management:Cross-border incident response and business interruption recovery planning for operational disruptions.
- Business Continuity:Operational resilience frameworks ensuring production persistence through supply chain failures or facility outages.
Risk Assessment anchors the volume base while Compliance Consulting gains share at the steepest rate.
End User:
Cost tier stratification separates capital-intensive OEMs with captive risk teams from mid-tier suppliers dependent on external expertise.
- Automotive OEMs:Vehicle manufacturers in Thailand's Rayong and Chonburi zones mandating tier-one supplier risk frameworks. Thailand's Board of Investment incentives are accelerating Japanese and Korean OEM facility expansion, embedding operational risk requirements into procurement contracts.
- Electronics Manufacturers:Semiconductor foundries and contract manufacturers deploying real-time probabilistic models for fabrication disruption scenarios. Taiwan's Hsinchu Science Park and Singapore's wafer facilities are driving consulting engagement for supply chain analytics and chip shortage mitigation protocols.
- Pharmaceutical Firms:Drug manufacturers navigating Australia's TGA inspection regimes and multi-jurisdictional quality standards.
- Food Processing:Agribusiness and packaged goods producers managing contamination risk and cold chain integrity across dispersed sourcing networks.
Automotive OEMs dominate current procurement volumes while Electronics Manufacturers are expanding most quickly.
Solution Type:
Technology maturity curves separate software-enabled monitoring from labor-intensive training and strategy engagements.
- Software Solutions:IoT-integrated risk monitoring platforms and predictive analytics dashboards for real-time operational visibility. Singapore's Jurong Island petrochemical cluster is piloting digital twin integration with risk modeling, creating subscription-based revenue streams that displace project-based consulting.
- Strategy Development:Enterprise risk governance design and board-level operational resilience frameworks. Japan's METI safety guidelines are compelling chemical and heavy machinery producers in Osaka and Nagoya to consolidate consulting procurement for documented governance structures.
- Training Programs:Workforce certification and competency development for risk identification and escalation protocols.
- Audit Services:Independent verification of internal controls and regulatory compliance documentation.
Strategy Development commands premium pricing while Software Solutions are climbing the fastest.
Industry Vertical:
Geographic concentration of production assets determines consulting procurement density and service mix preferences.
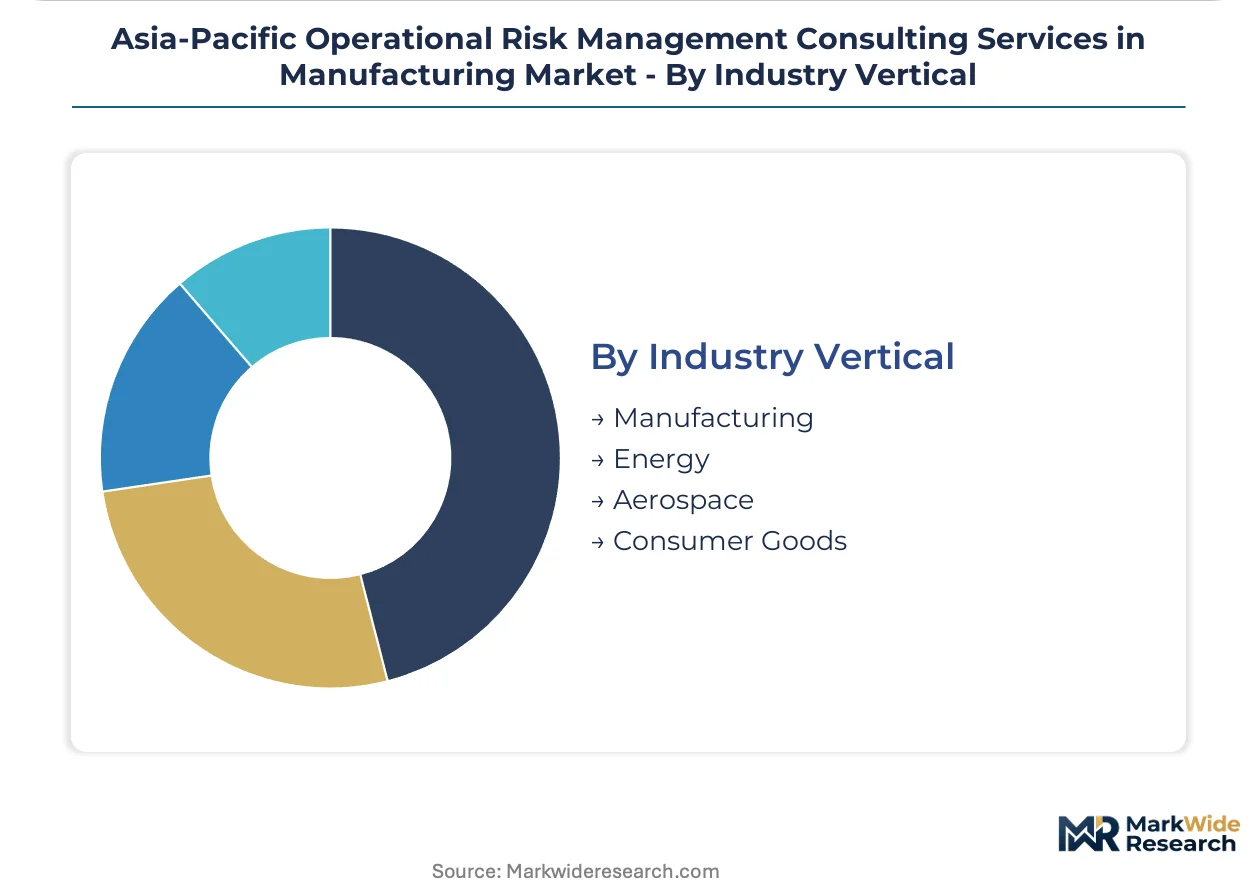
- Manufacturing:Discrete and process manufacturing encompassing automotive, electronics, and industrial machinery production. China's SAMR audit requirements and Japan's METI guidelines are externalizing risk expertise across chemical and heavy machinery segments previously reliant on captive capabilities.
- Energy:Power generation, oil and gas, and renewable asset operators managing catastrophic failure scenarios and grid integration risks.
- Aerospace:Aviation component manufacturers and maintenance facilities subject to stringent quality and safety certification regimes.
- Consumer Goods:Durable and non-durable goods producers balancing cost efficiency with supply chain resilience.
Manufacturing retains the deepest consulting penetration while Energy is expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Asia-Pacific diverge sharply by industrial maturity. Japanese manufacturers prioritize documented governance frameworks under METI mandates, while Southeast Asian automotive hubs emphasize supplier-tier risk propagation. Australian pharmaceutical and electronics producers concentrate compliance spending around penalty-avoidance.
China
Electronics and automotive OEMs in Shanghai and Shenzhen industrial clusters drive recurring consulting engagement for supply chain complexity management. SAMR audit requirements for chemical and heavy machinery segments are externalizing risk expertise previously held in-house. Yangtze River Delta manufacturers are consolidating procurement to meet escalating documentation burdens.
Japan
Chemical and heavy machinery producers in Osaka and Nagoya industrial belts are consolidating consulting procurement for METI-mandated governance structures. Safety guidelines now require continuous monitoring protocols with external audit trails. Electronics OEMs face production suspension risks without demonstrated compliance documentation.
Thailand
Japanese and Korean automotive OEMs in Rayong and Chonburi zones are embedding ISO 31000-aligned risk requirements into tier-one supplier contracts. Board of Investment incentives are accelerating facility expansion with operational risk procurement mandates. Tier-two suppliers struggle with legacy MES and SCADA interoperability for risk monitoring protocols.
Australia
Pharmaceutical and electronics manufacturers in Victoria and New South Wales are shifting from discrete project mandates to continuous compliance oversight. Work Health and Safety Act penalty escalations are forcing external auditor retention. TGA inspection regimes for drug manufacturers are intensifying quality standard navigation requirements.
Singapore
Semiconductor foundries and petrochemical facilities on Jurong Island are piloting digital twin integration with predictive risk modeling. Wafer fabrication disruption scenarios are driving real-time probabilistic model deployment. Subscription-based monitoring services are displacing project-based engagements among mid-tier suppliers.
Asia-Pacific Operational Risk Management Consulting Services in Manufacturing Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-speed competitive structure. The upper tier commands large-scale compliance mandates through regulatory relationships and crisis management bench strength. Boutique specialists compete on advanced scenario analytics and semiconductor supply chain expertise. Consolidation pressure is mounting as automated risk platforms commoditize baseline assessments, while M&A activity targets niche analytics capabilities.
Among integrated global consultancies, KPMG, Deloitte, and Oliver Wyman occupy distinct positioning vectors. KPMG exemplifies the regulatory-relationship archetype across ASEAN manufacturing hubs. Deloitte represents the crisis management and Shanghai-Singapore bench strength model. Oliver Wyman sits within the advanced scenario analytics specialization tier for semiconductor supply chain disruptions. Each anchors a different competitive response to automated platform substitution pressure.
| Leading Market Players |
|---|
| KPMG |
| Deloitte |
| PwC |
| Accenture |
| EY |
| McKinsey & Company |
| Boston Consulting Group |
| Bain & Company |
| Oliver Wyman |
| Others |
Value Network & Pricing Analysis
Project-based consulting engagements lock in supply access to cross-border incident response teams while anchoring price visibility for automotive OEMs navigating Thailand's tier-one supplier mandates. Subscription-based risk monitoring services are displacing these discrete mandates among mid-tier manufacturers, compressing revenue predictability for consultancies embedding permanent staff in client facilities.
Pricing Analysis
Project-based mandates dominate premium-tier consulting, with crisis management retainers commanding the highest rates due to scarcity of consultants holding Japan's JIS certifications and ASEAN cross-border credentials. Three-tier pricing structure across premium, standard, and economy levels separates multinational compliance mandates from localized audit services and automated platform subscriptions. Cost compression in baseline risk assessment is intensifying because probabilistic modeling software commoditizes scenario generation previously requiring senior analyst teams. Mid-tier automotive suppliers in Vietnam's Vinh Phuc corridor exhibit the greatest price sensitivity, while semiconductor foundries in Singapore's Jurong Island cluster prioritize capability over cost.
Supply Chain Analysis
Just-in-time deployment of risk monitoring personnel prevails among integrated consultancies, though boutique specialists maintain strategic stockpiles of certified analysts for METI-mandated governance documentation. Consultant talent concentrates in Japan, Singapore, and Australia, where regulatory complexity sustains premium credentialing pathways. Raw material dependencies include cross-border certification reciprocity, legacy MES system interoperability expertise, and real-time IoT sensor integration capabilities. Single-source vulnerability runs through Japan's JIS certification pipeline, which faces re-certification barriers when deploying to ASEAN manufacturing hubs. Distribution runs through direct partnership models with industrial zone authorities in Shanghai, Shenzhen, and Rayong.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from cyclical compression in project-based mandates, with regulatory tightening across METI, SAMR, and Australia's Work Health and Safety Act providing the cyclical impetus.
For Market Incumbents: Shield premium pricing power by embedding permanent staff in Thailand's Rayong and Chonburi automotive corridors, where tier-one supplier mandates create captive relationships. Consolidate scenario analytics capabilities through targeted acquisition of semiconductor supply chain specialists before automated platforms commoditize this tier. Vertical integration into digital twin development for Singapore's Jurong Island petrochemical cluster anchors subscription revenue against project-based volatility.
For New Entrants and Emerging Players: Lead with ISO 31000-aligned frameworks targeting underpenetrated electronics manufacturers in the Philippines' Cavite and Laguna industrial corridors, where first-mover positioning remains available. White-space opportunities concentrate in ESG-operational risk service bundles bridging Australia's mandatory climate risk reporting with Japan's METI safety transparency mandates. A channel partnership model with Thailand's Board of Investment accelerates access to Japanese and Korean OEM procurement contracts.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors analytics-specialist acquisition targets with proven semiconductor supply chain expertise. Long-term viability hinges on recurring revenue models displacing project-based engagements across the projection horizon. Boutique firms holding cross-border incident response credentials represent the priority acquisition archetype. The signal to watch is regulatory harmonization progress between ASEAN member states, which would trigger rapid consolidation of fragmented consulting procurement models. Revision becomes warranted when automation penetration in baseline risk assessment crosses thresholds that eliminate human analyst value-add.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment | JIS and ISO 31000 credential expansion secures access to Japan's METI-mandated governance mandates. |
| Geographic Expansion | Permanent staff embedding in Vietnam's Vinh Phuc corridor captures tier-two automotive supplier subscription demand. |
| Technology Licensing | Digital twin integration partnerships with Singapore's Jurong Island petrochemical facilities create recurring revenue streams. |
| Strategic Partnership | Thailand Board of Investment collaboration accelerates Japanese and Korean OEM procurement channel access. |
| Acquisition of Specialist Firm | Semiconductor supply chain analytics capabilities defend against automated platform substitution pressure. |
Research Methodology
The analysis maps operational risk consulting services across risk assessment, compliance consulting, crisis management, and business continuity segments, each validated through managing directors at integrated consultancies, operational risk officers at automotive OEMs, compliance leads at pharmaceutical manufacturers, and procurement heads at electronics contract manufacturers. Primary interview findings triangulated against secondary sources including SAMR audit disclosure filings, METI safety guideline documentation, Australia's Work Health and Safety Act penalty records, and ASEAN industrial zone authority procurement data. Bottom-up service-line revenue estimates reconciled with top-down market sizing across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks including regulatory filing intensity, industrial zone expansion permits, and certification body issuance records. Segmentation modeling incorporated service type, end-user sophistication, solution technology depth, and industry vertical concentration. CAGRs derived from regression analysis of historical procurement patterns and regulatory mandate implementation timelines. Semiconductor fabrication capacity expansion and automotive OEM facility investment schedules served as industry-specific demand inputs.
Forecasts assume regulatory continuity in Japan's METI guidelines, China's SAMR audit requirements, and Australia's Work Health and Safety Act penalty structures; material policy shifts would require re-modeling demand trajectories. Specific risks include accelerated captive capability building by large Shanghai and Shenzhen manufacturers, and faster-than-anticipated automation of baseline risk assessment functions. Revision becomes warranted when consultant talent scarcity thresholds trigger unsustainable wage inflation or when regulatory harmonization materially alters cross-border service delivery economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
North America BFSI Biometrics Market
Risk Management and Compliance
Stress Testing Solutions Market
Risk Management and Compliance
Treasury and Risk Management Application Market
Risk Management and Compliance
Sell-Side Due Diligence Services Market
Risk Management and Compliance
Global Regulatory Reporting and Compliance Market
Risk Management and Compliance
Certificates Market
Risk Management and Compliance
Fraud Detection and Prevention (FDP) Market
Risk Management and Compliance
Global Liquidity Asset Liability Management Solutions Market
Risk Management and Compliance
Asia-Pacific BFSI Biometrics Market
Risk Management and Compliance
Global Financial Crime and Fraud Management Solutions Market
Risk Management and Compliance
Global Compliance Management Software Market
Risk Management and Compliance
Global Asset Integrity Management Market
Risk Management and Compliance
Oil and Gas Risk Management Market
Risk Management and Compliance
Digital Risk Management Market
Risk Management and Compliance
United States Strategic Consulting Services Market
Risk Management and Compliance
Enterprise Governance, Risk, and Compliance (Egrc) Market