
 Oil and Gas Risk Management Market | 2026-2036
Oil and Gas Risk Management Market Size, Share, and Industry Trends Forecast 2026-2036
Oil and Gas Risk Management Market Analysis
The shift from single-source consulting contracts toward multi-vendor risk technology ecosystems is broadening competitive entry points for specialized providers. Honeywell leverages its industrial automation heritage to embed risk sensors within operational hardware. Siemens sustains engineering credibility through digital twin integration for asset integrity monitoring. Baker Hughes differentiates by combining subsurface expertise with predictive analytics platforms.
Oil and gas risk management encompasses the systematic identification, quantification, and mitigation of hazards across exploration, production, transportation, and refining operations, typically employing probabilistic safety assessments, real-time monitoring architectures, and enterprise governance frameworks to reduce incident frequency and financial loss severity. Software solutions anchored in cloud computing and machine learning are capturing margin pools as operators replace static spreadsheet models with dynamic scenario engines. Consulting retains structural importance in upstream and offshore segments where bespoke geological and metocean risks resist full automation. Insurance-linked instruments and compliance services face pricing pressure from standardized regulatory templates in mature basins.
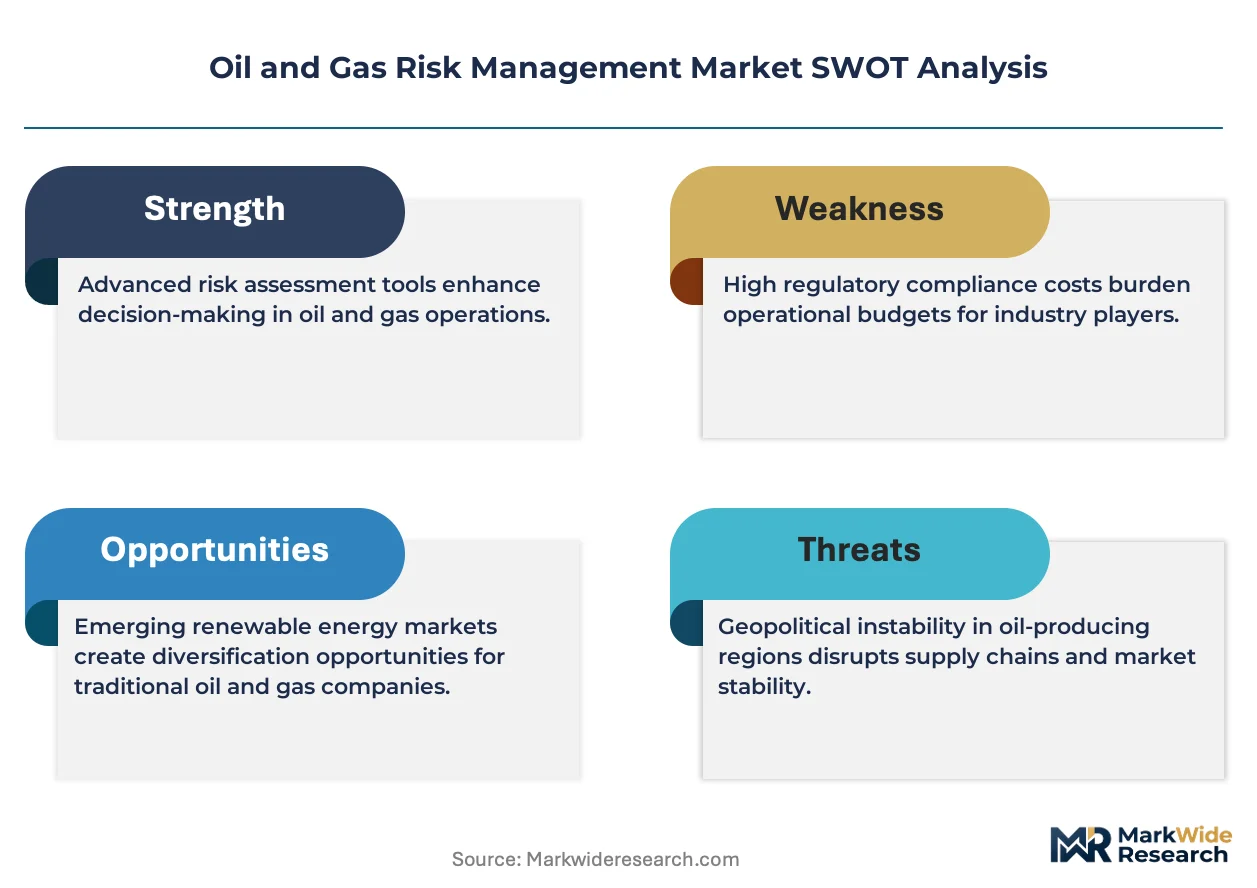
The US Bureau of Safety and Environmental Enforcement mandates SEMS protocols for offshore facilities, while DNV classification rules and ISO 31000 enterprise risk standards shape product certification and market access across international project finance. The EU AI Act and CSRD disclosure requirements are extending liability frameworks to algorithmic risk tools and Scope 3 emissions reporting. Stakeholders must evaluate whether their technology stacks satisfy emerging cross-border auditability demands before committing to multi-year platform contracts.
Market Dynamics
Deepwater project complexity in the United States Gulf Coast corridor is forcing operators to abandon static risk models for dynamic, real-time platforms that integrate subsurface data with predictive analytics.
Growth Catalysts
- EU CSRD disclosure mandates:The Corporate Sustainability Reporting Directive compels Scope 3 emissions transparency across oil and gas value chains. Operators now procure integrated risk platforms to automate emissions quantification and audit trails.
- Offshore digital twin adoption:Asset integrity monitoring through virtual replicas enables continuous stress-testing of subsea infrastructure against metocean hazards. North Sea and Gulf of Mexico operators lead deployment.
- F-Gas Regulation phase-down:The EU's fluorinated gas restrictions accelerate leak detection technology procurement for refrigeration and processing equipment. Compliance deadlines drive replacement cycles.
Market Restraints
- Specialized sensor supply concentration:High-integrity pressure transducers and subsea monitoring hardware depend on a limited supplier base concentrated in Norway and Scotland. Geopolitical friction threatens delivery timelines.
- Legacy system integration costs:Brownfield facilities operate decades-old SCADA architectures. Retrofitting real-time risk feeds requires bespoke middleware development that consumes 40-60% of platform deployment budgets.
- Qualified geoscientist scarcity:Probabilistic safety assessment expertise resides with an aging workforce. Universities produce fewer petroleum risk specialists as energy curricula pivot toward renewables.
Strategic Opportunities
- Brazil pre-salt basin expansion:Petrobras and international partners are sanctioning new floating production units. First-of-a-kind geological risks create demand for specialized consulting and probabilistic modeling services.
- AI Act algorithmic liability:The EU's artificial intelligence regulation creates audit requirements for automated risk decision systems. Compliance service providers can capture recurring revenue from algorithmic impact assessments.
- Drone-based inspection convergence:Unmanned aerial systems combined with methane spectrometry expand coverage of pipeline corridors and remote wellpads. Midstream operators in Texas and Alberta pilot subscription-based monitoring.
Industry Challenges
- SEMS audit preparation burden:The US Bureau of Safety and Environmental Enforcement mandates Safety and Environmental Management System documentation for offshore facilities. Operators struggle to harmonize paper-based legacy records with digital audit platforms.
- Cross-border data residency conflicts:Real-time risk platforms transmit operational data across jurisdictions. Brazil's national content requirements and China's data localization rules fragment cloud architecture design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil and Gas Risk Management Market |
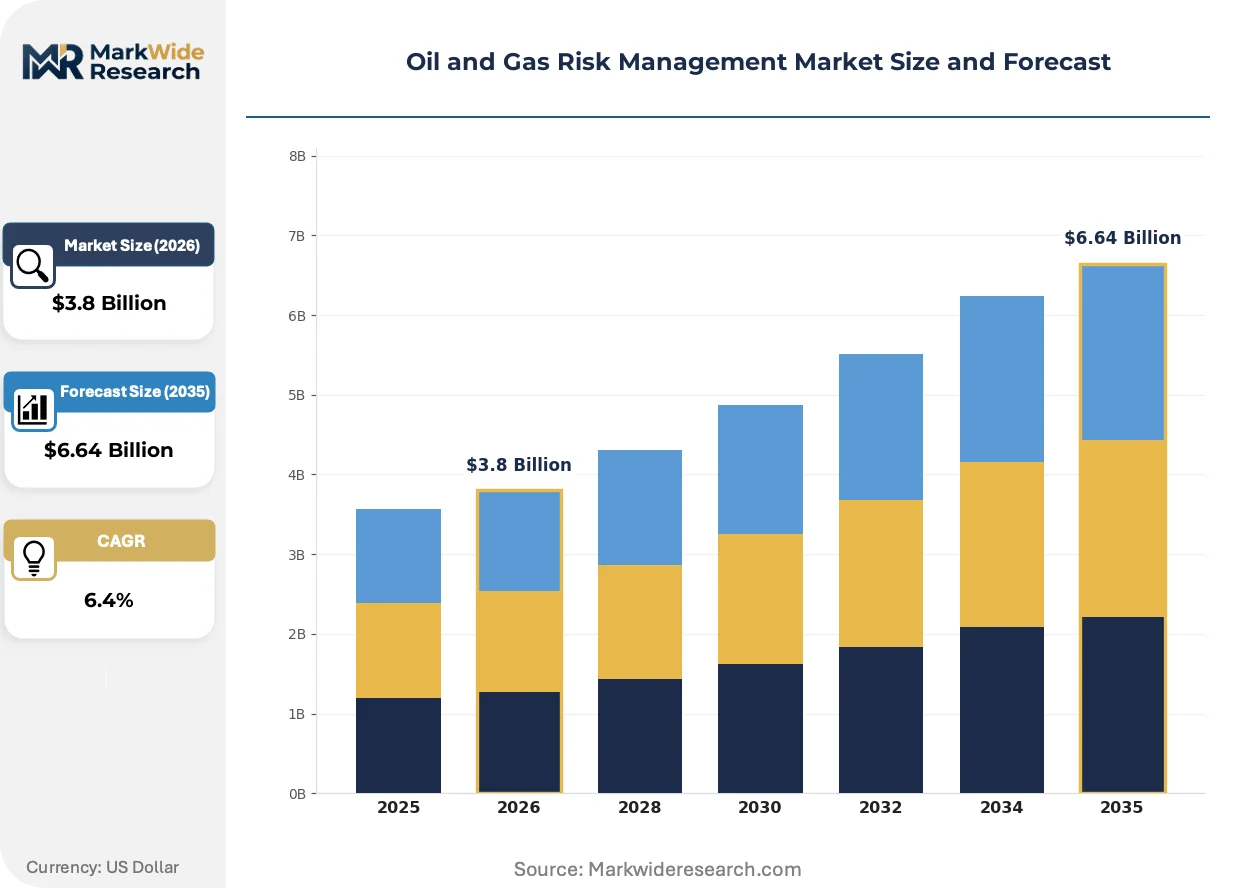
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
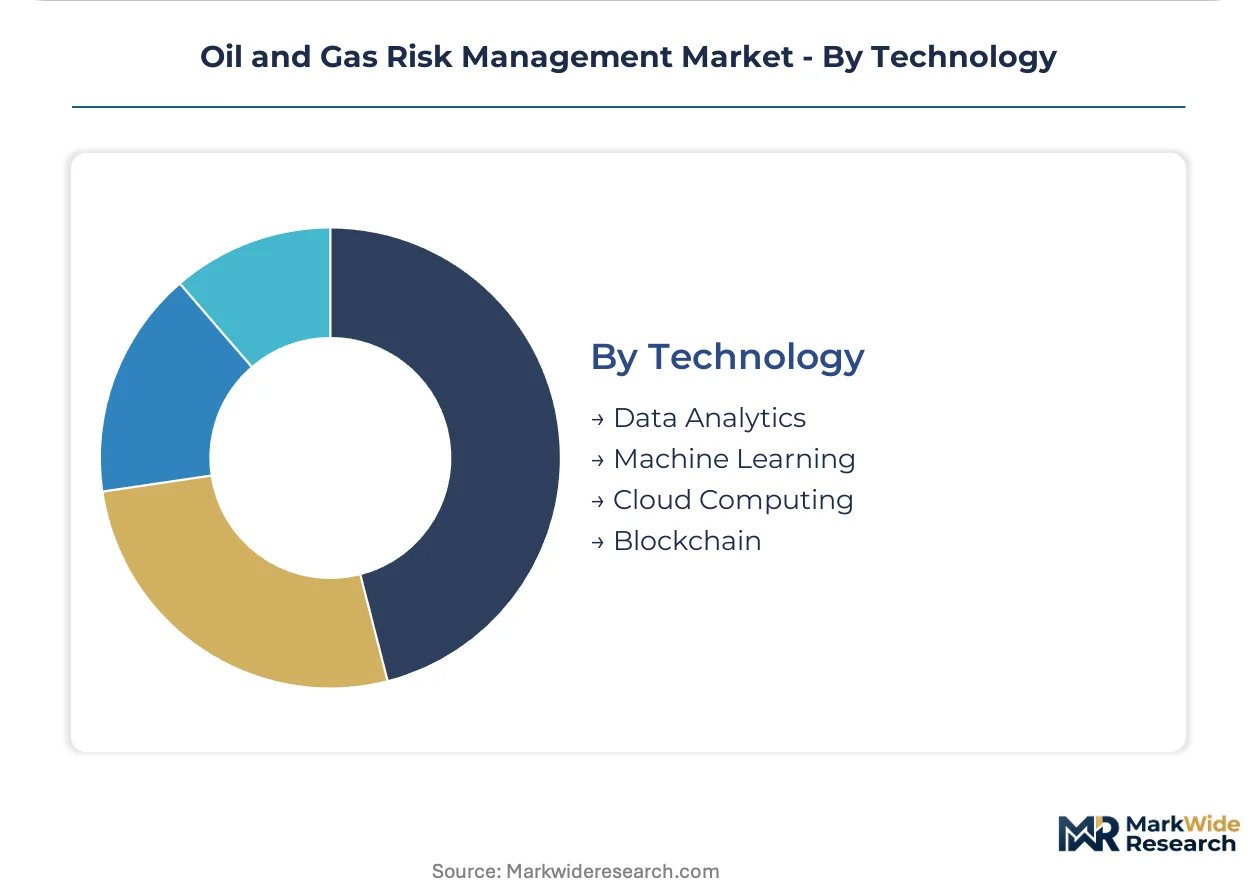
| Segmentation | Service Type: Consulting, Insurance, Software, Training Risk Type: Operational, Financial, Environmental, Compliance Industry Segment: Upstream, Midstream, Downstream, Offshore Technology: Data Analytics, Machine Learning, Cloud Computing, Blockchain |
| Companies Covered | Honeywell, Siemens, Microsoft, Schlumberger, Halliburton, Baker Hughes, Deloitte, DNV, Intertek Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil and Gas Risk Management Market Emerging Trajectories
Cloud-native risk engines are displacing on-premise installations as operators prioritize scalability over capital control. Machine learning inference at the edge enables sub-second anomaly detection on offshore platforms.
Digital twin technology is expanding into subsea production systems, creating virtual replicas of wellheads, manifolds, and flowlines that simulate corrosion rates and fatigue accumulation. Major operators in the Gulf of Mexico and North Sea deploy these models to extend asset life and optimize inspection intervals. The technology compresses traditional calendar-based maintenance schedules into condition-driven interventions.
The EU AI Act imposes conformity assessment requirements on automated risk classification tools used for blowout preventer testing and pressure integrity verification. Vendors must document training data provenance and algorithmic decision boundaries. Offshore engineering consultancies in Norway and the Netherlands are restructuring product liability frameworks to accommodate these audit trails.
Integrated service contracting is displacing discrete software licenses and standalone consulting engagements. Supermajors now procure multi-year risk management subscriptions that bundle predictive analytics, regulatory filing support, and insurance advisory. This consolidation concentrates vendor relationships and raises switching costs. The model is most visible among US independents operating in the Permian and Bakken shale plays.
Oil and Gas Risk Management Market Segmentation
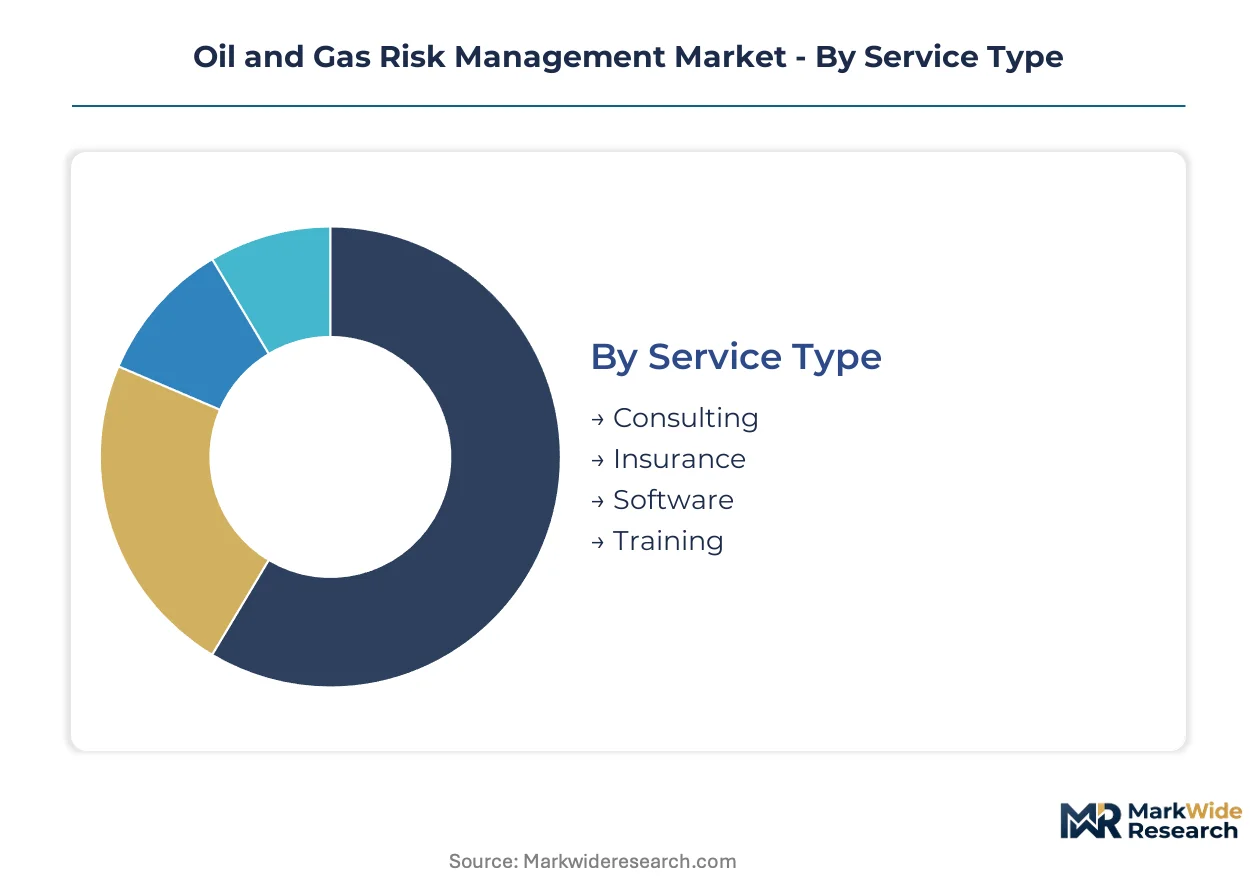
Risk management procurement patterns diverge sharply across service modalities and operational contexts. Technology maturity, regulatory exposure, and asset complexity determine which segments capture operator budgets.
Service Type:
Technology sophistication separates procurement tiers.
- Software:Cloud-native platforms with real-time scenario engines displace spreadsheet-based models. Gulf of Mexico deepwater operators prioritize API-integrated systems that feed directly into SEMS documentation workflows mandated by the US Bureau of Safety and Environmental Enforcement.
- Consulting:Bespoke geological and metocean risk assessments retain structural importance where subsurface uncertainty resists algorithmic standardization. Brazil pre-salt basin developments drive specialized probabilistic safety assessment contracts.
- Insurance:Traditional coverage instruments face margin compression from standardized regulatory templates in mature North American basins. Carriers pivot toward parametric products tied to operational downtime events.
- Training:Simulator-based competency programs address qualified geoscientist scarcity. Virtual reality deployments for blowout preventer certification expand in Norway and Scotland.
Mature deployment sits with Software. Newer deployment is concentrated in Training.
Risk Type:
Regulatory intensity reshapes prioritization hierarchies.
- Environmental:Scope 3 emissions quantification and F-Gas Regulation compliance dominate European procurement. Integrated platforms automate audit trails for CSRD disclosure mandates across value chains.
- Compliance:Cross-border algorithmic liability under the EU AI Act creates audit requirements for automated risk classification tools. Conformity assessment services capture recurring revenue.
- Operational:Real-time anomaly detection for subsea infrastructure leverages edge computing. Digital twin integration enables continuous stress-testing against metocean hazards.
- Financial:Commodity price volatility instruments and project finance risk models support capital allocation decisions. Structured products link to reserve-based lending covenants.
Established frameworks anchor Environmental. Emerging complexity centers on Compliance.
Industry Segment:
Asset vintage and project economics determine technology adoption velocity.
- Offshore:Floating production unit complexity in ultra-deepwater settings demands integrated risk ecosystems. Petrobras pre-salt expansions drive specialized consulting and predictive analytics procurement.
- Upstream:Unconventional shale operators in Texas and North Dakota adopt drone-based methane monitoring subscriptions. Legacy SCADA retrofit costs constrain real-time platform deployment.
- Midstream:Pipeline corridor integrity management combines unmanned aerial systems with spectrometry. Alberta and Texas operators pilot subscription-based inspection models.
- Downstream:Refinery process safety management emphasizes pressure integrity verification. F-Gas phase-down accelerates leak detection replacement cycles for refrigeration equipment.
Capital intensity peaks in Offshore. Margin pressure concentrates in Downstream.
Technology:
Infrastructure architecture choices lock in multi-year vendor relationships.
- Data Analytics:Probabilistic safety assessments integrate subsurface, metocean, and equipment reliability datasets. Cloud-native engines displace on-premise installations for scalability.
- Machine Learning:Edge inference enables sub-second anomaly detection on offshore platforms. Training data provenance documentation satisfies EU AI Act conformity requirements.
- Cloud Computing:Data residency conflicts fragment architecture design. Brazil's national content requirements and China's localization rules complicate cross-border transmission.
- Blockchain:Immutable audit trails for equipment certification and maintenance records. Adoption remains exploratory with limited production deployment.
Proven scale sits with Data Analytics. Experimental traction gathers in Blockchain.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hydrocarbon basins along the United States Gulf Coast and the North Sea continental shelf concentrate specialized risk management procurement. Deepwater project complexity and aging infrastructure drive technology adoption patterns across producing regions.
United States
The Gulf of Mexico ultra-deepwater corridor demands integrated risk platforms for floating production units. The Bureau of Safety and Environmental Enforcement mandates SEMS documentation for all offshore facilities. Houston hosts the primary vendor ecosystem serving Permian shale operators and deepwater independents.
Brazil
Pre-salt basin expansions by Petrobras and international partners create demand for probabilistic safety assessments. ANVISA and environmental licensing requirements shape equipment certification protocols. Rio de Janeiro anchors specialized consulting firms serving first-of-a-kind geological risks.
Norway
North Sea asset integrity monitoring drives digital twin adoption for subsea infrastructure. DNV classification rules and Petroleum Safety Authority regulations enforce continuous risk verification. Stavanger concentrates sensor manufacturers and engineering consultancies developing metocean hazard models.
United Kingdom
Decommissioning liabilities and mature basin complexity sustain consulting demand for operational risk. The Health and Safety Executive maintains offshore safety case requirements for all installations. Aberdeen retains specialized competency in blowout preventer certification and well control training.
China
Deepwater exploration in the South China Sea accelerates procurement of real-time monitoring architectures. The Ministry of Ecology and Environment tightens emissions accountability for offshore production. Tianjin and Shenzhen host domestic platform developers integrating risk sensors with national cloud infrastructure.
Oil and Gas Risk Management Market Vendor Landscape
Global majors compete with regional champions across technology integration depth and regulatory specialization. The market structures around three tiers: diversified industrial conglomerates, pure-play risk technology vendors, and engineering consultancies with certification authority. Consolidation pressures intensify as operators seek bundled subscriptions spanning software, compliance advisory, and insurance placement. Strategic moves center on embedding risk sensors within operational hardware and acquiring boutique data analytics capabilities.
Within the industrial automation tier, Honeywell and Siemens exemplify platform breadth through embedded sensor networks and digital twin architectures. Baker Hughes occupies a specialized position combining subsurface expertise with predictive analytics. These three anchors represent divergent paths to operator wallet share: hardware-integrated risk feeds, engineering-credibility-driven consulting, and subsurface-data-centric platforms.
| Leading Market Players |
|---|
| Honeywell |
| Siemens |
| Microsoft |
| Schlumberger |
| Halliburton |
| Baker Hughes |
| Deloitte |
| DNV |
| Intertek Group |
| Others |
Supply Flow & Price Mechanics
The EU F-Gas Regulation phase-down gates qualified supply of high-integrity leak detection sensors and compresses premium-tier pricing access for operators requiring certified compliance documentation across refrigeration and processing equipment replacement cycles.
Pricing Analysis
Warranty and service-bundling arrangements separate subscription-based predictive analytics platforms from unbundled software licenses requiring separate consulting support. Pricing stratifies across premium, standard, and economy tiers based on API integration depth and SEMS documentation automation capabilities. Cost compression in the standard tier is intensifying because cloud-native entrants are displacing legacy on-premise installations with scalable SaaS alternatives. Independent shale operators in Texas exhibit the highest price sensitivity, while Gulf of Mexico deepwater independents prioritize integration depth over unit cost.
Supply Chain Analysis
Dual-sourcing qualification requirements for high-integrity pressure transducers and subsea monitoring hardware mandate vendor redundancy across Norwegian and Scottish manufacturing bases. Component supply draws from Norway, Scotland, and Germany for specialized sensor fabrication, with raw material dependencies spanning titanium alloys, high-purity ceramics, and fiber-optic cabling. Single-source vulnerability concentrates in subsea connector assemblies subject to geopolitical friction. Distribution runs through engineering-procurement-construction contractors and direct OEM relationships to operator technical procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a technology-transition phase where cloud-native risk engines are displacing static spreadsheet models and on-premise installations across offshore and shale operator portfolios.
For Market Incumbents: Deepen embedded sensor integration within industrial automation hardware to defend against pure-play software entrants. Expand API connectivity with SEMS documentation workflows mandated by the US Bureau of Safety and Environmental Enforcement. Acquire boutique data analytics capabilities in Brazil and Norway to capture pre-salt and North Sea consulting demand. For New Entrants and Emerging Players: Midstream operators in Alberta and Texas represent an underserved buyer archetype seeking subscription-based drone inspection services for pipeline corridor integrity. Target methane spectrometry pilots with unmanned aerial systems before incumbents consolidate integrated service contracting. Position through outcome-based monitoring agreements rather than capital equipment sales. For Investors and Strategic Acquirers: Petrobras pre-salt floating production unit sanctioning is the leading indicator that specialized probabilistic safety assessment demand will concentrate in Rio de Janeiro engineering consultancies. Long-term viability favors targets combining subsurface expertise with predictive analytics platforms over pure compliance software plays. Watch for ANVISA equipment certification backlog as signal of vendor qualification bottlenecks.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Integration | Virtual replicas of subsea infrastructure enable condition-driven maintenance for Gulf of Mexico operators. |
| API-First Platform Development | Direct SEMS workflow integration satisfies Bureau of Safety and Environmental Enforcement documentation mandates. |
| Edge Computing Deployment | Sub-second anomaly detection on offshore platforms reduces reliance on cloud connectivity for critical safety systems. |
| Specialized Consulting Acquisition | First-of-a-kind geological risk expertise in Brazil pre-salt basins resists full algorithmic automation. |
| Parametric Insurance Product Launch | Operational downtime-linked coverage instruments replace traditional policies facing margin compression. |
Methodological Framework
Regulatory filings from the US Bureau of Safety and Environmental Enforcement, EU CSRD disclosure databases, and DNV classification rule updates formed the secondary backbone for compliance requirement mapping. Primary interviews with offshore engineering directors, risk management officers at supermajors, subsea equipment procurement leads, and digital transformation executives at shale operators combined with secondary validation. Bottom-up platform deployment estimates and top-down operator budget allocations were triangulated to anchor market sizing.
Historical trendline analysis of technology procurement patterns across software, consulting, and insurance modalities informed projection frameworks. Segmentation modeling spanned service type, risk category, industry segment, and technology infrastructure choices across the analysis window. CAGR derivation incorporated offshore project sanctioning timelines, F-Gas Regulation compliance deadlines, and qualified geoscientist supply constraints. Scenario testing integrated CSRD disclosure mandate acceleration and AI Act algorithmic liability enforcement timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical friction affecting Norwegian sensor supply and Brazil national content requirement evolution. Forecasts reflect documented assumptions regarding offshore capital expenditure cycles and regulatory enforcement intensity. Deviation in EU AI Act conformity assessment timelines or SEMS audit scope expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
Global Energy Trading and Risk Management (ETRM) Market
Risk Management and Compliance
Anti-Money Laundering (AML) Market
Risk Management and Compliance
Europe Governance, Risk and Compliance Platform Market
Risk Management and Compliance
Global Liquidity Asset Liability Management Solutions Market
Risk Management and Compliance
Europe Strategic Consulting Services Market
Risk Management and Compliance
Enterprise Risk Management Market
Risk Management and Compliance
Sell-Side Due Diligence Services Market
Risk Management and Compliance
Asia-Pacific Sustainable Finance Market
Risk Management and Compliance
Europe Sustainable Finance Market
Risk Management and Compliance
North America BFSI Biometrics Market
Risk Management and Compliance
Revenue Assurance Market
Risk Management and Compliance
Global Risk and Compliance Consulting Services Market
Risk Management and Compliance
Europe Risk Management Market
Risk Management and Compliance
China Enterprise Risk Management Market
Risk Management and Compliance
Europe Strategy Consulting Market
Risk Management and Compliance
Corporate Investigation Services Market