
 Artificial Intelligence and Regtech Market | 2026-2036
Artificial Intelligence and Regtech Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence and Regtech Market Outlook
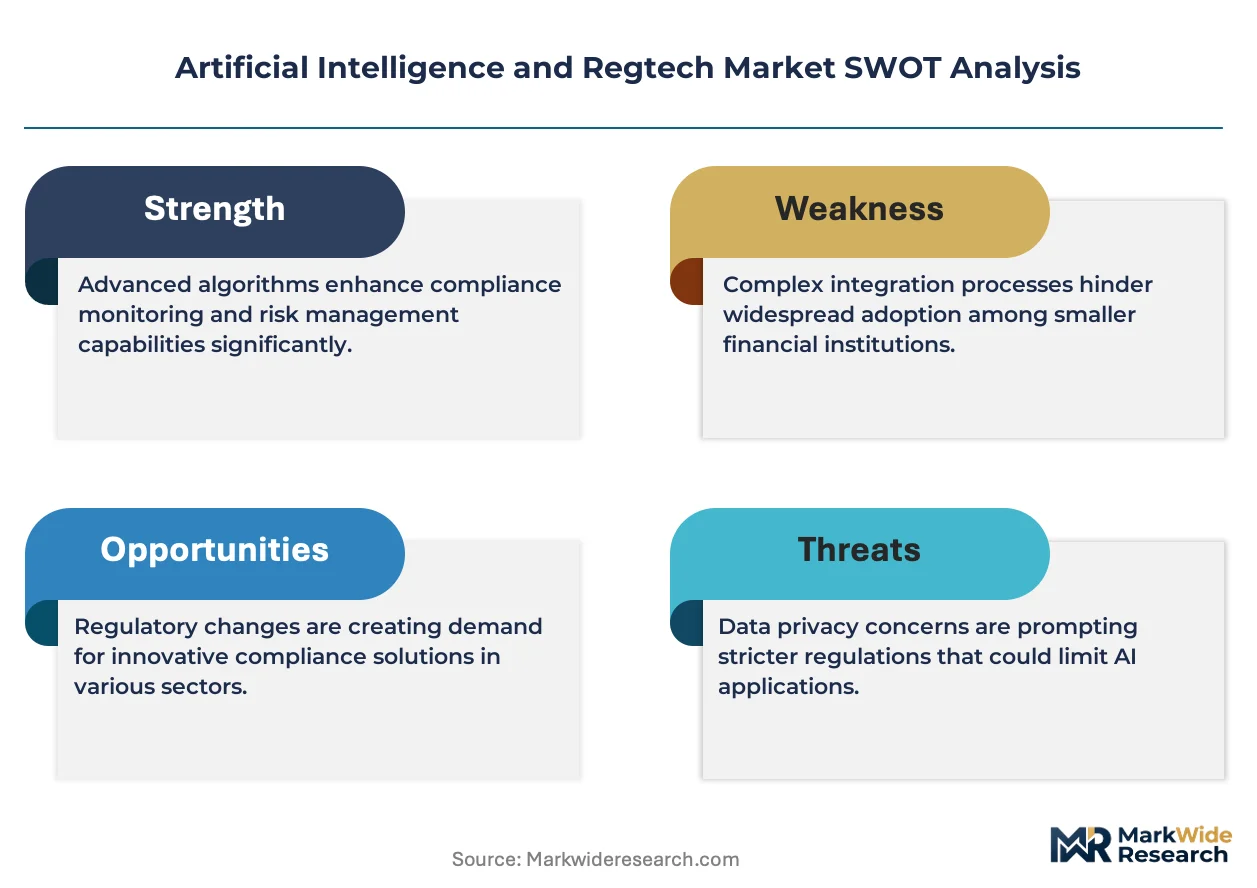
Banking sector compliance is restructuring around real-time transaction monitoring, pulling investment away from periodic batch reporting. ComplyAdvantage leverages machine learning to sustain watchlist screening accuracy across fragmented sanctions regimes. IBM Corporation anchors enterprise-scale deployments with hybrid cloud architectures that integrate legacy core systems.
Artificial intelligence and regtech encompasses algorithmic systems that automate regulatory compliance, risk detection, and supervisory reporting through natural language processing of legal texts and predictive analytics on transactional data. These platforms operate by ingesting structured and unstructured regulatory content, generating executable compliance rules, and flagging anomalies against behavioral baselines for investigation by human analysts. Fraud detection and anti-money laundering applications now dominate procurement budgets as financial institutions face intensified enforcement from multiple jurisdictions. Machine learning competes with rules-based systems for capital allocation, though predictive analytics is gaining share where institutions seek forward-looking risk signals rather than retrospective alerts.
The EU AI Act, GDPR, and SEC disclosure mandates are reshaping product requirements by imposing explainability standards and audit trail obligations on automated decision systems. The Federal Reserve and OCC in the United States are scrutinizing model risk management frameworks, creating procurement headwinds for black-box solutions that lack interpretable outputs. Stakeholders must weigh algorithmic transparency against predictive performance when selecting platforms for cross-border deployment.
Market Dynamics
Financial institutions are dismantling periodic compliance reviews in favor of continuous algorithmic surveillance, forcing vendors to rearchitect platforms for real-time ingestion of transactional streams and regulatory feeds.
Growth Catalysts
- EU AI Act explainability mandates:Banks must deploy interpretable models for automated credit and fraud decisions, creating procurement urgency for platforms with built-in audit trails.
- Sanctions regime fragmentation:OFAC, HMT, and UN lists diverge faster than manual processes can reconcile, pulling investment toward machine learning systems that harmonize watchlist updates.
- Cloud-native core banking migration:Institutions replacing legacy infrastructure embed compliance APIs directly into transactional pipelines, reducing implementation friction for AI surveillance tools.
Market Restraints
- Model risk management scrutiny:The Federal Reserve SR 11-7 guidelines demand extensive documentation and validation cycles that extend sales timelines for black-box solutions.
- Data localization requirements:China's PIPL and Russia's data sovereignty rules fragment training datasets, forcing vendors to maintain jurisdiction-specific model instances.
- Specialized talent scarcity:The intersection of regulatory expertise and machine learning engineering commands compensation premiums that compress vendor margins.
Strategic Opportunities
- Embedded finance compliance:Non-bank fintechs offering banking-as-a-service lack internal compliance infrastructure, creating demand for white-label AI surveillance platforms.
- Environmental disclosure convergence:The EU CSRD mandates granular sustainability reporting that AI systems can automate from unstructured supplier documentation.
- Natural language processing of legal texts:Regulators now issue guidance through informal channels; platforms that parse enforcement speeches and speeches gain predictive advantage.
Industry Challenges
- Explainability-performance tradeoffs:Gradient-boosted models outperform linear alternatives on fraud detection benchmarks but fail regulatory interpretability requirements.
- Cross-border model drift:Training data from US transaction patterns degrades accuracy when deployed against European behavioral baselines without retraining pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence and Regtech Market |
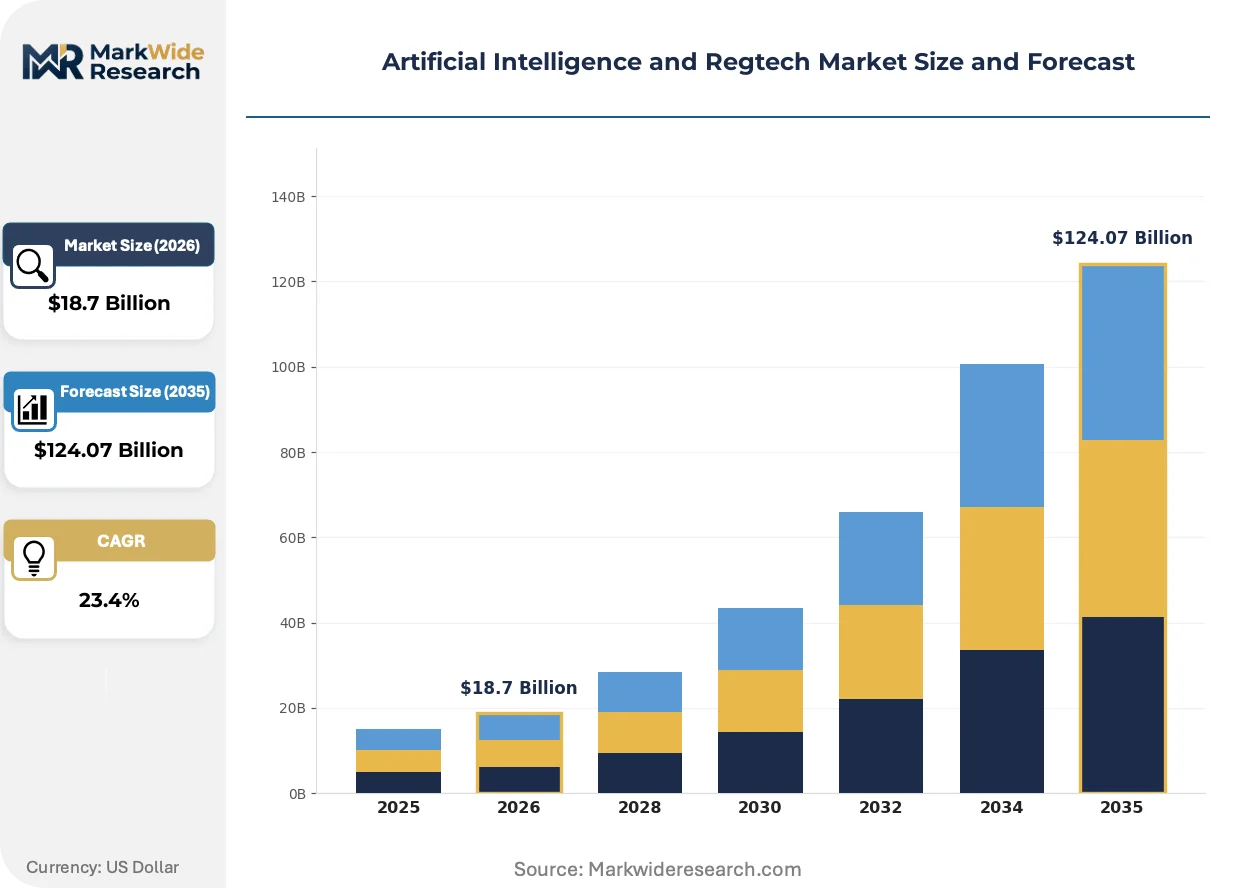
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $124.07 Billion |
| CAGR (2026 – 2036) | 23.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Natural Language Processing, Computer Vision, Predictive Analytics Application: Fraud Detection, Risk Management, Compliance Monitoring, Anti-Money Laundering End User: Financial Institutions, Insurance Companies, Investment Firms, Regulatory Bodies Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | IBM Corporation, ComplyAdvantage, Onfido, Trulioo, Chainalysis, Ascent Technologies, Elliptic, Quantexa, Feedzai, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence and Regtech Market Strategic Shifts
Regulatory technology vendors are racing to embed generative capabilities into compliance workflows while navigating divergent jurisdictional constraints on algorithmic decision-making.
Federated learning architectures are expanding into anti-money laundering applications, enabling institutions to train models on pooled behavioral patterns without centralizing sensitive transaction data. Tier-one banks in Switzerland and Singapore pilot these networks to detect cross-border laundering schemes invisible to single-institution surveillance. The approach compresses detection latency while satisfying data residency constraints that prohibit raw record export.
The SEC's proposed predictive data analytics rule is forcing broker-dealers to document how AI-driven recommendations align with investor best-interest obligations. Compliance officers must now maintain version-controlled records of model updates and override rationales. Vendors serving US wealth management channels are reengineering audit interfaces to capture this evidentiary trail automatically.
Buyers now unbundle implementation services from software licensing, contracting specialized system integrators for core banking integration while negotiating direct platform subscriptions. This bifurcation concentrates pricing power with vendors possessing pre-built connectors to major core systems. European institutions lead this pattern, driven by procurement frameworks that separate IT professional services from software category spend.
Artificial Intelligence and Regtech Market Segmentation
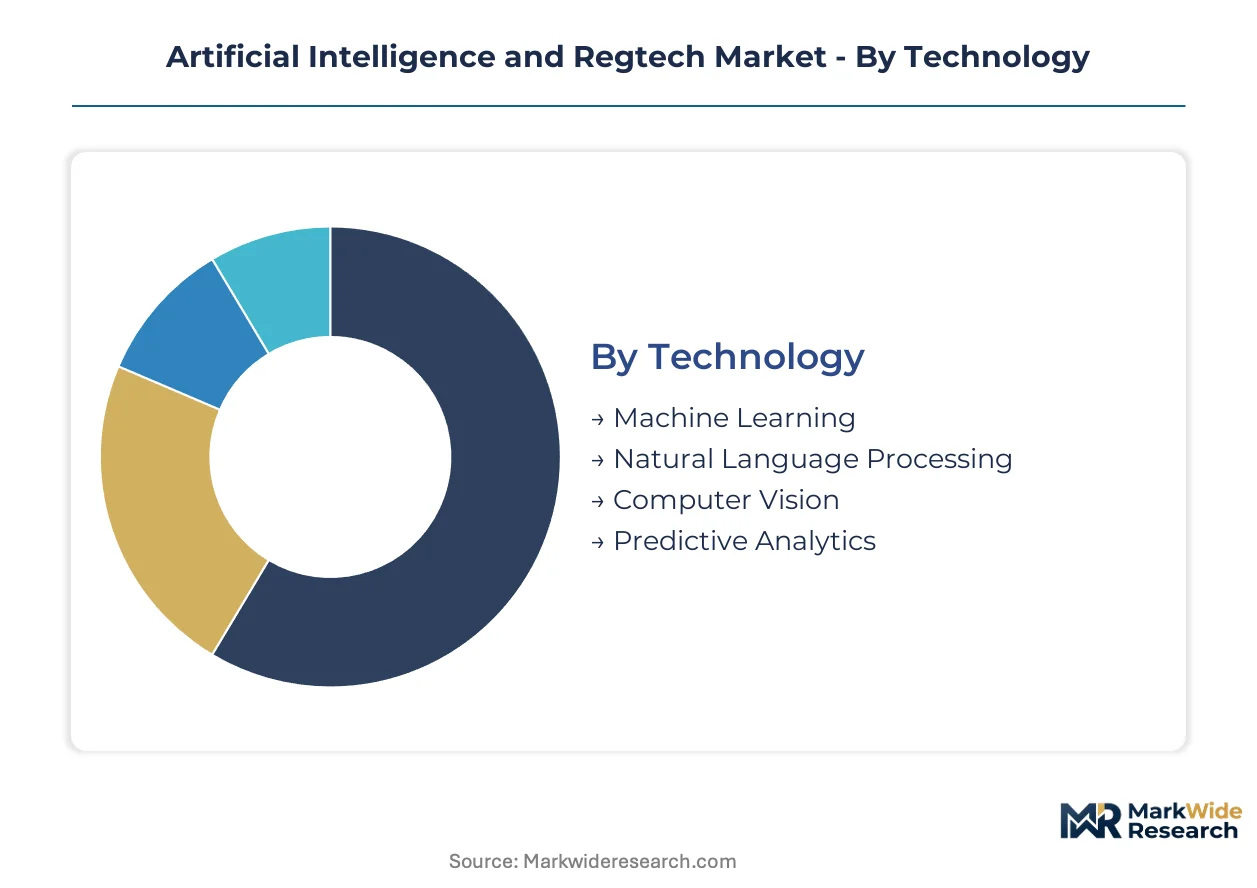
Segmentation in AI and regtech reveals where compliance automation sits as standalone infrastructure versus embedded capability within core banking systems. Procurement patterns diverge sharply between institutions modernizing entire technology stacks and those layering surveillance atop legacy architectures.
Technology:
Integration depth varies dramatically across these four technology families, with some operating as embedded inference engines and others demanding dedicated infrastructure layers.
- Machine Learning:Gradient-boosted and neural architectures detect transaction anomalies against behavioral baselines, requiring substantial training pipelines. Demand clusters in tier-one banks across the United States and Switzerland where model risk management frameworks from the Federal Reserve and FINMA mandate interpretable outputs.
- Natural Language Processing:Systems parse regulatory texts, enforcement speeches, and legal filings to auto-generate compliance rules. Procurement accelerates in the European Union where the EU AI Act requires automated documentation of how algorithmic decisions map to legal obligations.
- Computer Vision:Document verification and identity authentication through image analysis. Financial institutions in Singapore deploy these systems for know-your-customer workflows.
- Predictive Analytics:Forward-looking risk scoring that anticipates compliance breaches before they crystallize. Investment firms in the United Kingdom leverage these tools for regulatory capital forecasting.
Volume placements concentrate in Machine Learning; the faster expansion belongs to Natural Language Processing.
Application:
Cost tiering separates commodity surveillance from premium predictive capabilities, with price-to-value ratios diverging threefold across these four use cases.
- Fraud Detection:Real-time transaction scoring against synthetic identity and authorized push payment schemes. Retail banks in the United States allocate the largest procurement budgets here as the Consumer Financial Protection Bureau intensifies reimbursement obligations.
- Risk Management:Model risk quantification and stress testing automation. Insurance companies in Germany deploy these systems to satisfy BaFin's quantitative reporting requirements.
- Compliance Monitoring:Continuous surveillance of employee communications and trading behaviors. Broker-dealers facing SEC examination priorities drive uptake.
- Anti-Money Laundering:Suspicious activity report generation and watchlist screening. Swiss banks lead deployment as the Swiss Financial Market Supervisory Authority tightens correspondent banking oversight.
Compliance Monitoring commands the highest per-seat pricing; Fraud Detection shows the steepest expansion trajectory.
End User:
Customer sophistication determines whether procurement favors configurable platforms or managed compliance services.
- Financial Institutions:Universal banks with dedicated model risk offices procure enterprise licenses for internal deployment. United States money center banks represent the deepest wallet share.
- Insurance Companies:Solvency II and ORSA reporting automation drives demand in France and Germany.
- Investment Firms:Private equity and hedge funds with lean compliance teams favor SaaS surveillance for Form PF and ADV obligations.
- Regulatory Bodies:Supervisory technology for market surveillance and thematic reviews. The Monetary Authority of Singapore pilots these capabilities for fintech sandbox monitoring.
Financial Institutions anchor current revenue; Regulatory Bodies are climbing the fastest as supervisory technology budgets expand.
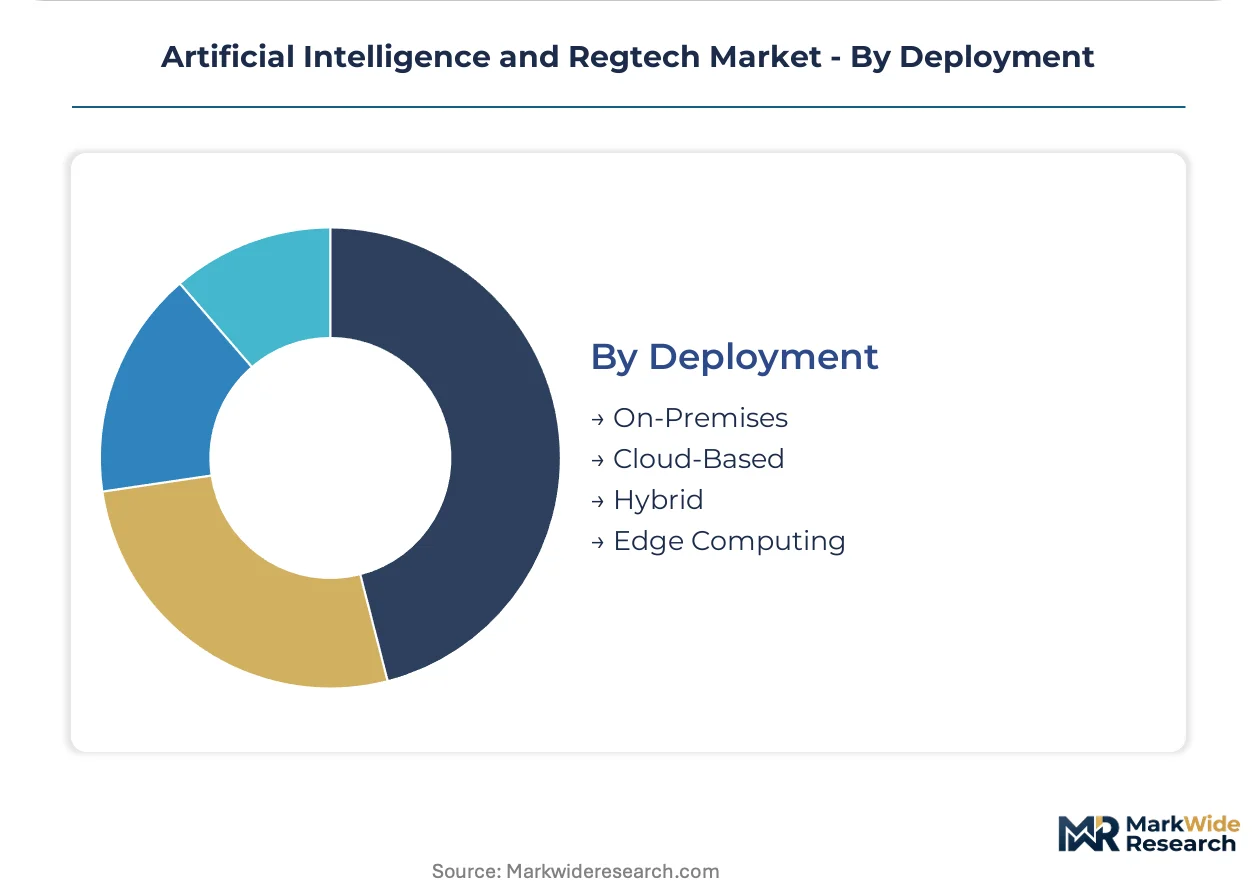
Deployment:
Margin structures favor cloud-native delivery, though data residency constraints preserve substantial on-premises revenue.
- On-Premises:Air-gapped installations for classified or geopolitically sensitive data. Russian banks under data sovereignty mandates maintain these configurations.
- Cloud-Based:Multi-tenant SaaS with API-first integration. Fintechs in Brazil leverage these platforms for rapid market entry without infrastructure capital.
- Hybrid:Sensitive model training on-premises with inference at cloud edge. United Kingdom retail banks favor this architecture for GDPR compliance.
- Edge Computing:Low-latency decisioning at branch or ATM locations. Japanese regional banks deploy these for real-time transaction authorization.
Hybrid deployments dominate new contracts; Edge Computing is gaining share fastest as 5G infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The New York metropolitan area concentrates procurement for AI-driven regulatory surveillance, with federal agencies and money center banks co-locating compliance technology investments. Singapore's fintech sandbox programs attract vendor development centers. London's regulatory technology cluster benefits from proximity to both the FCA and Lloyd's insurance market.
United States
Federal Reserve SR 11-7 guidelines and SEC disclosure mandates drive enterprise procurement for interpretable machine learning platforms. The Consumer Financial Protection Bureau intensifies reimbursement obligations for authorized push payment fraud. Manhattan and Jersey City host the densest concentration of compliance technology vendors serving money center banks.
United Kingdom
Investment firms leverage predictive analytics for regulatory capital forecasting under Prudential Regulation Authority supervision. The Financial Conduct Authority's thematic reviews on algorithmic trading accelerate continuous surveillance adoption. The City of London and Canary Wharf clusters specialize in broker-dealer compliance monitoring for Form PF and ADV obligations.
Germany
Insurance companies deploy automated Solvency II and ORSA reporting systems to satisfy BaFin's quantitative requirements. The EU AI Act explainability mandates create procurement urgency for platforms with built-in audit trails. Frankfurt's financial center anchors model risk management platform development for continental European deployment.
Switzerland
FINMA interpretability requirements concentrate demand for gradient-boosted models with regulatory-compliant outputs. Swiss Financial Market Supervisory Authority tightening of correspondent banking oversight drives anti-money laundering investment. Zurich and Geneva host federated learning pilots for cross-border laundering detection across tier-one private banks.
Singapore
Monetary Authority of Singapore supervisory technology budgets expand for fintech sandbox monitoring and real-time surveillance. Computer vision systems for know-your-customer workflows receive regulatory endorsement through MAS innovation programs. The Marina Bay financial district concentrates vendor R&D centers serving ASEAN market entry strategies.
Artificial Intelligence and Regtech Market Competitive Environment
Top-tier vendors anchor enterprise-scale deployments, while specialized boutiques capture niche surveillance workflows. The vendor base stratifies across three tiers: full-stack platform providers, point-solution specialists, and managed compliance services. Two strategic archetypes dominate: hybrid cloud integrators serving legacy core banking migrations, and API-first vendors embedding surveillance into cloud-native transactional pipelines. Competitive moves concentrate on pre-built connector development for major core systems and federated learning network orchestration.
Among established technology conglomerates, IBM Corporation occupies a position exemplifying hybrid cloud architecture for enterprise compliance. ComplyAdvantage represents the machine learning specialist archetype focused on watchlist screening harmonization. Within the blockchain analytics segment, Chainalysis anchors vendor positioning for cryptocurrency surveillance applications. These three entities illustrate the geographic and technological diversification patterns visible across the competitive set.
| Leading Market Players |
|---|
| IBM Corporation |
| ComplyAdvantage |
| Onfido |
| Trulioo |
| Chainalysis |
| Ascent Technologies |
| Elliptic |
| Quantexa |
| Feedzai |
| Others |
Value Chain & Pricing Dynamics
Cloud compute spot price indices from AWS, Azure, and Google Cloud Platform cascade through AI regtech vendor cost structures, compressing margins for pure-play SaaS providers while hybrid cloud integrators absorb volatility through long-term enterprise contracts. This input cost pressure stratifies pricing tiers between API-first entrants and full-stack platform incumbents.
Pricing Analysis
Short lead-time premiums dominate procurement negotiations, with federal agencies and tier-one banks paying 15-30% markups for sub-90-day implementation against standard 6-12 month enterprise deployments. Three-tier pricing structure across premium, standard, and economy levels separates white-glove managed compliance from self-service API tiers. Pricing pressure stems from open-source machine learning frameworks commoditizing core algorithmic capabilities. Fintech challengers exhibit highest price sensitivity; money center banks with dedicated model risk offices demonstrate lowest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with NVIDIA GPU supply for training infrastructure, concentrated in Taiwan and South Korea fabrication facilities. Raw material dependencies span specialized semiconductors, high-bandwidth memory modules, and rare earth elements for server hardware. Tariff exposure on Chinese-manufactured edge computing devices disrupts cost models for ATM and branch deployment. Distribution runs through direct enterprise sales teams for tier-one accounts, with channel partners serving mid-market financial institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as EU AI Act compliance costs force sub-scale vendors toward acquisition or exit. Interpretability mandates favor incumbents with established model risk documentation infrastructure.
For Market Incumbents: Extend federated learning network coverage into Singapore and Swiss private banking corridors before specialized boutiques capture cross-border AML workflows. Acquire natural language processing specialists to fill regulatory text parsing gaps as EU AI Act documentation requirements tighten. Vertical integration into cloud infrastructure insulates margin compression from hyperscaler pricing volatility. For New Entrants and Emerging Players: Embedded finance compliance APIs represent the most penetrable white-space, targeting Brazilian and Nigerian fintechs lacking internal surveillance infrastructure. White-label KYC computer vision modules for neobanks offer fastest path to recurring revenue. Partner with core banking system integrators rather than building direct sales capacity. For Investors and Strategic Acquirers: Distressed-cycle entries favor machine learning boutiques with FINMA or Federal Reserve model risk pre-qualifications in Switzerland and the United States. Long-term viability hinges on regulatory moat durability rather than algorithmic performance alone. Watch for SEC predictive data analytics rule enforcement intensity as inflection signal for wealth management compliance automation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Federated Learning Network Expansion | Swiss and Singaporean tier-one banks pilot cross-border AML detection without data centralization. |
| Natural Language Processing Acquisition | Regulatory text parsing capabilities satisfy EU AI Act automated documentation mandates. |
| Hybrid Cloud Architecture Development | Legacy core system connectors reduce implementation friction for money center bank procurement. |
| Embedded Finance API Launch | Banking-as-a-service providers in Brazil lack internal compliance infrastructure. |
| Model Risk Documentation Automation | SEC predictive data analytics rule creates evidentiary trail requirements for broker-dealers. |
Study Parameters
Multi-period observation of vendor pricing disclosures, procurement contract structures, and regulatory filing patterns anchored the trend analysis, supplemented by interviews with compliance technology officers, model risk directors, regulatory affairs leads at tier-one banks, and fintech CTOs. Secondary validation drew from SEC disclosure mandates, EU AI Act implementation guidance, Federal Reserve SR 11-7 documentation, and cloud hyperscaler capex reports. Bottom-up segment sizing triangulated against top-down market aggregation.
Segment-weighting across technology families, application use cases, deployment architectures, and end-user sophistication tiers structured the analytical framework across the analysis window. CAGRs derived from slope-intercept modeling of historical placement trajectories and regulatory mandate implementation timelines. Forecast inputs incorporated EU AI Act enforcement phase-ins and cloud-native core banking migration velocities.
Several conditions sit outside the modeled scope, including geopolitical disruptions to semiconductor supply chains and unilateral regulatory reversals by national supervisors. Forecasts reflect documented assumptions about interpretability standard harmonization across jurisdictions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
Global Strategy Consulting Market
Risk Management and Compliance
Vendor Risk Management Market
Risk Management and Compliance
Asset Liability Management (ALM) Solution Market
Risk Management and Compliance
Employee Benefits Strategy and Consulting Market
Risk Management and Compliance
Financial Risk Management Software Market
Risk Management and Compliance
Disclosure Management Market
Risk Management and Compliance
Stress Testing Solutions Market
Risk Management and Compliance
Risk Analytics Market
Risk Management and Compliance
Global Risk and Compliance Consulting Services Market
Risk Management and Compliance
Global Backstop Netting Systems Market
Risk Management and Compliance
Europe Sustainable Finance Market
Risk Management and Compliance
Third Party Risk Management Market
Risk Management and Compliance
NPL Management Market
Risk Management and Compliance
Digital Risk Management Market
Risk Management and Compliance
BFSI Crisis Management Market
Risk Management and Compliance
Risk Assessment Software Market