
 Surety Market | 2026-2036
Surety Market Size, Share, and Industry Trends Forecast 2026-2036
Surety Market Outlook
The EU Green Deal is hardening sustainability-linked contract requirements for public works across member states. Chubb Limited leverages its global underwriting footprint to navigate these evolving European standards. Liberty Mutual Insurance Company anchors its competitive stance through deep specialization in infrastructure and commercial construction bonds. The Travelers Indemnity Company dominates the US contractor segment with granular risk segmentation and long-standing carrier relationships.
Surety denotes a tripartite guarantee instrument where a bonding company assumes obligation for a principal's performance to an obligee, typically backed by rigorous financial underwriting and collateral assessment. Contract surety leads premium generation across the analysis window, reflecting sustained infrastructure investment cycles and mandatory bonding thresholds on public projects. Performance surety is expanding fastest among client segments, driven by developer and subcontractor demand for completion guarantees on complex builds. Court surety occupies a mature niche with stable but lower-margin premium pools tied to judicial system volume.
US federal procurement regulations and state-level contractor licensing boards shape mandatory bond requirements across public works and commercial construction. The EU's CE marking framework and national procurement codes in Germany, France, and Italy influence cross-border surety standards for infrastructure tenders. Stakeholders must monitor how evolving green procurement criteria and digital bond issuance platforms reshape underwriting workflows and obligee expectations.
Market Dynamics
Federal procurement mandates in the United States are tightening performance bond thresholds on infrastructure projects, while the EU Green Deal hardens sustainability-linked contract requirements, creating dual regulatory pressure on surety underwriters to recalibrate risk models and collateral frameworks.
Growth Catalysts
- Transportation Infrastructure:The Infrastructure Investment and Jobs Act drives mandatory bonding volumes on federally funded highway, bridge, and transit projects across the United States.
- EU Green Deal Procurement Standards:Sustainability-linked tender requirements harden contract performance criteria for public works in Germany, France, and Italy, expanding demand for environmental guarantee instruments.
- Utility Sector Privatization:Power grid modernization and renewable energy interconnection projects in Texas, California, and Florida generate premium bond requirements for contractor performance.
Market Restraints
- Treasury Yield Volatility:Collateral backing requirements fluctuate with Federal Reserve rate cycles, compressing underwriting margins on long-duration construction bonds.
- Reinsurance Capacity Concentration:Catastrophe-exposed surety lines face capacity tightening from Bermuda and London market reinsurers following multi-year weather losses.
- Alternative Risk Transfer Instruments:Letters of credit from commercial banks and parent company guarantees displace traditional surety bonds on select private developer projects.
Strategic Opportunities
- Digital Bond Issuance Platforms:Blockchain-verified smart contracts streamline obligee verification and claims processing for mid-market contractors in the United States.
- Subcontractor Default Insurance Convergence:Hybrid products blending surety guarantees with casualty coverage address completion risk on complex vertical construction in New York and Illinois.
- Small Business Administration Surety Programs:Federal guarantee mechanisms reduce collateral barriers for emerging contractors bidding on federal set-aside contracts.
Industry Challenges
- Actuarial Talent Scarcity:Underwriting functions require specialized expertise in construction finance and project risk assessment that outpaces graduate pipeline output.
- Legacy System Integration:Core policy administration platforms from the 1990s resist API connectivity with modern data analytics and obligee portal demands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surety Market |
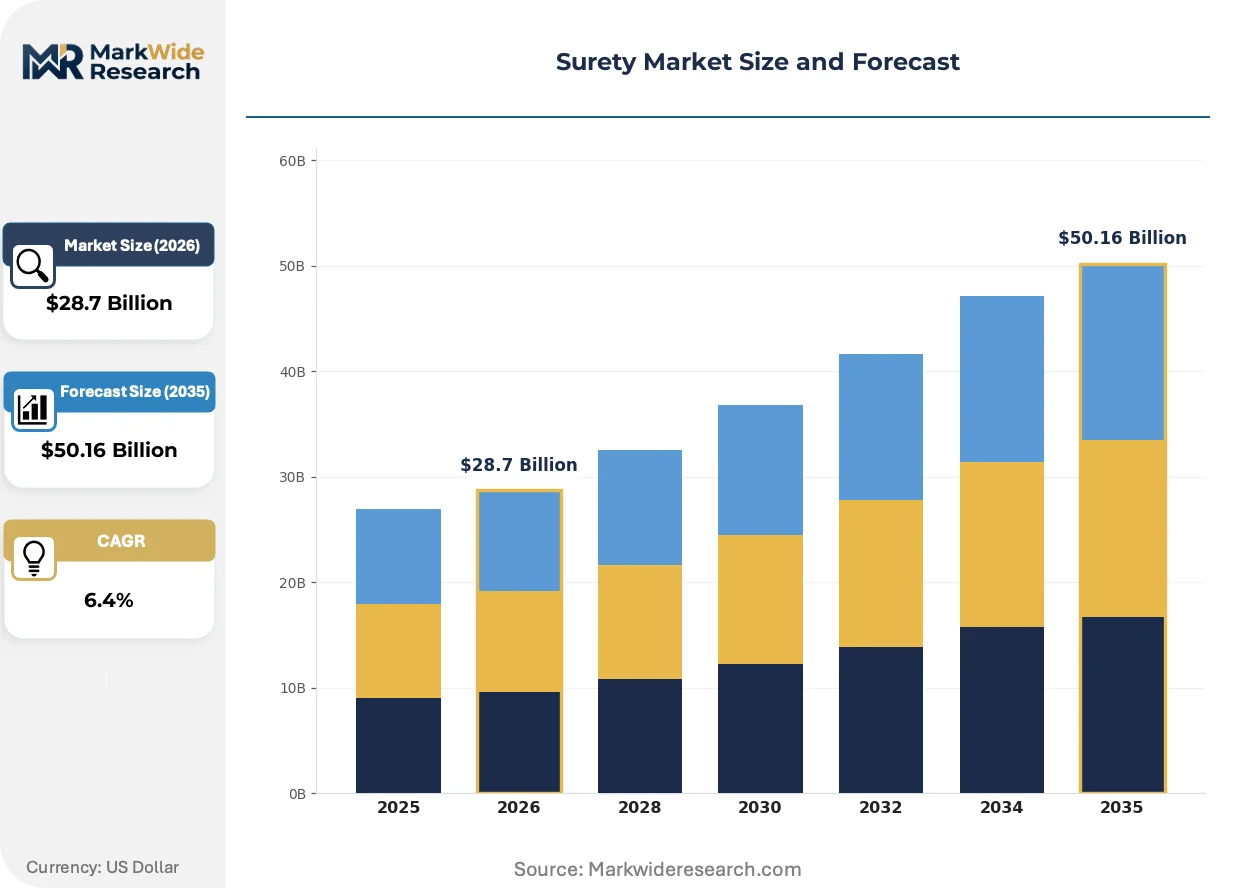
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $50.16 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contract Surety, Court Surety, License Surety, Performance Surety Client Type: General Contractors, Subcontractors, Developers, Service Providers Application: Construction Projects, Legal Proceedings, Licensing Requirements, Public Works Industry Sector: Construction, Transportation, Manufacturing, Retail |
| Companies Covered | The Travelers Indemnity Company, Liberty Mutual Insurance Company, Chubb Limited, CNA Financial Corporation, The Hartford, Crum & Forster, American Financial Group, Zurich Insurance Group, Great American Insurance Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surety Market Strategic Shifts
Digital underwriting workflows and alternative data sources are compressing bond issuance timelines from weeks to days, while sustainability-linked contract structures reshape obligee expectations around environmental performance guarantees.
API-driven risk scoring platforms are overtaking traditional financial statement review for contractor qualification. Mid-sized commercial builders in Texas and Florida adopt real-time cash flow monitoring tools that feed directly into underwriter dashboards. This compression of assessment cycles is enabling same-day bond issuance for repeat contractors with established performance histories.
The EU's Corporate Sustainability Reporting Directive hardens disclosure requirements for environmental and social governance metrics on public works tenders. Contractors bidding on German federal infrastructure must now document supply chain carbon intensity and circular material usage. French obligees are responding by embedding sustainability key performance indicators directly into bond indemnity structures.
Consolidated buying by national homebuilders and utility developers concentrates bond procurement with fewer intermediaries. Regional insurance brokers in the United States face margin compression as direct-to-carrier digital platforms capture standard commercial construction accounts. This channel shift is most visible in Arizona and Colorado, where large-scale master planned community developers self-procure surety capacity through captive arrangements.
Surety Market Segmentation
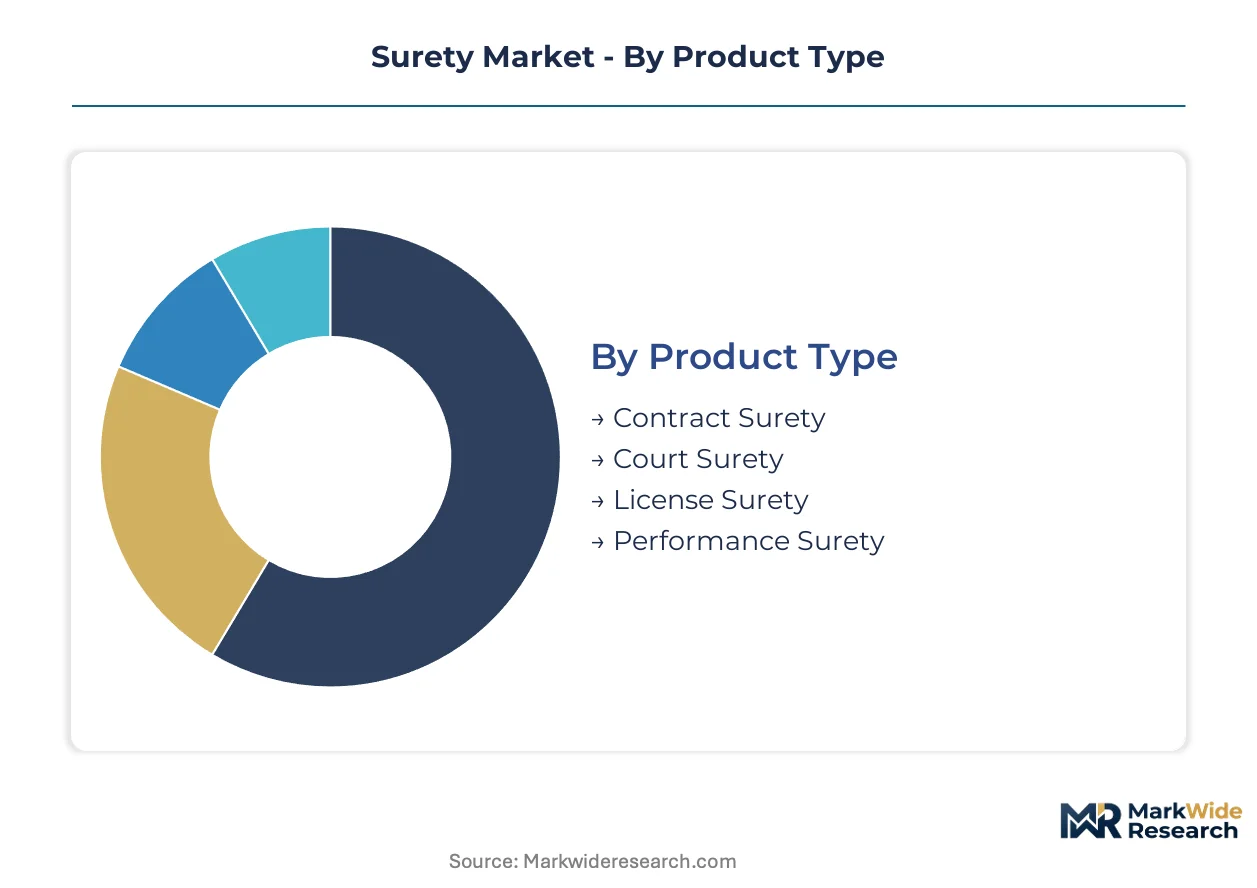
Surety instruments serve distinct obligee-principal relationships across project finance, judicial systems, and regulatory compliance. Segmentation reveals how collateral frameworks, risk assessment protocols, and obligee requirements diverge across product categories and client profiles. Underwriters calibrate pricing and capacity allocation based on these structural differences in exposure duration and default correlation.
Product Type:
Technical specifications vary by guarantee structure, obligee protection mechanism, and collateral backing intensity.
- Contract Surety:Tripartite instruments guaranteeing contractor performance on specified deliverables, typically backed by rigorous financial underwriting and project-specific collateral assessment. Demand concentrates with infrastructure general contractors bidding on federal highway and bridge projects in the United States, where the Infrastructure Investment and Jobs Act mandates bonding thresholds.
- Performance Surety:Completion guarantees covering developer and subcontractor obligations on complex vertical construction, with indemnity structures tied to milestone-based disbursement schedules. Subcontractors in Texas and Florida drive fastest expansion as renewable energy interconnection projects proliferate.
- Court Surety:Judicial system instruments securing fiduciary obligations and appeal bonds, characterized by standardized forms and shorter duration exposure.
- License Surety:Regulatory compliance guarantees required by state contractor licensing boards and professional credentialing authorities.
Mature deployment sits with Contract Surety. Newer deployment is concentrated in Performance Surety.
Client Type:
Customer sophistication and procurement scale determine underwriting resource allocation and relationship management intensity.
- General Contractors:Prime bidders on public works carrying comprehensive bonding programs spanning bid, performance, and payment obligations. Developers in Arizona and Colorado increasingly self-procure through captive arrangements.
- Subcontractors:Tier-2 and tier-3 trades requiring specialized default coverage as prime contractors push risk downstream.
- Developers:Commercial and residential project sponsors seeking completion guarantees and subdivision improvement bonds.
- Service Providers:Non-construction professionals including freight brokers, mortgage originators, and collection agencies requiring license and permit bonds.
Established relationships dominate General Contractor placement. Emerging volume is concentrating with Subcontractors.
Application:
Use-case environments shape obligee verification protocols and claims resolution procedures.
- Construction Projects:Private and commercial builds where developer-financed work competes with public procurement for underwriter attention.
- Public Works:Government-funded infrastructure where federal and state mandates create non-discretionary demand pools.
- Legal Proceedings:Court-ordered fiduciary and appeal instruments with standardized judicial forms and expedited issuance timelines.
- Licensing Requirements:Occupational and business credentialing bonds where state regulatory boards set coverage minimums.
Traditional volume centers on Construction Projects. Regulatory expansion is driving Licensing Requirements.
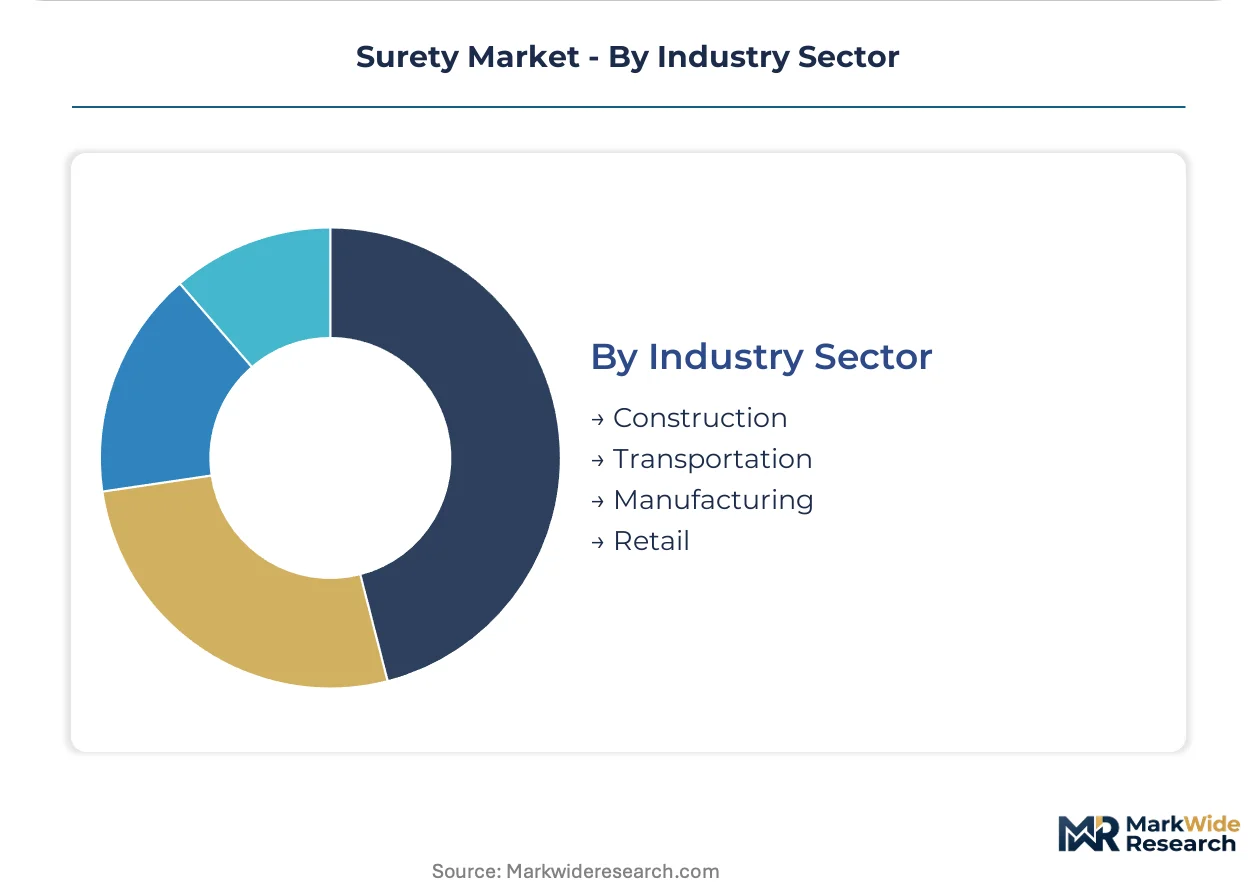
Industry Sector:
End-market cyclicality and capital intensity influence portfolio construction and reinsurance ceding decisions.
- Construction:The core demand vertical spanning residential, commercial, and civil engineering segments with pronounced regional cycle exposure.
- Transportation:Highway, rail, and aviation infrastructure where federal funding authorization drives multi-year bond pipelines.
- Manufacturing:Industrial facility construction and equipment installation contracts requiring specialized performance instruments.
- Retail:Commercial tenant improvement and franchise development programs with standardized bond forms and rapid turnaround requirements.
Long-established concentration resides in Construction. Diversification momentum is building in Transportation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston anchors the North American surety landscape through its concentration of energy infrastructure contractors and utility-scale renewable projects requiring performance guarantees.
United States
Federal highway and bridge mandates under the Infrastructure Investment and Jobs Act drive mandatory bonding volumes across state transportation departments. The Federal Highway Administration enforces Miller Act thresholds on public works exceeding $150,000. Dallas-Fort Worth contractors dominate premium generation through airport expansion and light rail interconnection projects.
Germany
Public procurement for rail modernization and autobahn maintenance sustains contract surety demand among civil engineering consortiums. The EU Green Deal hardens sustainability-linked tender requirements through the Corporate Sustainability Reporting Directive. Munich-based infrastructure specialists navigate expanded environmental guarantee obligations on federal building contracts.
France
Nuclear facility maintenance and offshore wind interconnection projects generate specialized performance bond requirements. French national procurement codes embed circular economy criteria into public works contracts. Lyon construction clusters respond by integrating supply chain carbon disclosure into surety underwriting submissions.
Canada
Provincial crown corporation infrastructure programs and P3 hospital developments sustain contractor bonding pipelines. Health Canada and provincial licensing boards mandate performance guarantees on healthcare facility construction. Toronto-Greater Golden Horseshoe contractors concentrate bid activity on transit expansion and water treatment upgrades.
United Arab Emirates
Mega-project developments including NEOM and Red Sea tourism infrastructure drive international surety capacity deployment. The UAE's federal procurement framework and emirate-level contractor classification systems govern bonding thresholds. Dubai-based developers self-procure surety capacity through captive arrangements on master-planned community builds.
Surety Market Competitive Environment
The competitive structure tilts toward diversified multi-line carriers with construction underwriting specialization. Tier-one players command federal contractor relationships through decades-long obligee trust accumulation. Strategic archetypes include global commercial insurers with dedicated surety divisions, mutual carriers leveraging policyholder capital advantages, and specialty underwriters targeting niche contractor segments. Capacity expansion through reinsurance partnerships and portfolio diversification into environmental guarantee instruments represent dominant competitive vectors.
Among US-based diversified carriers, The Travelers Indemnity Company, Liberty Mutual Insurance Company, and Chubb Limited exemplify the tier-one archetype through their established federal contractor placement networks and granular risk segmentation capabilities. These entities occupy positions defined by obligee relationship depth rather than price competition, with underwriting infrastructure calibrated to mandatory bonding workflows on public infrastructure. Zurich Insurance Group represents the European-headquartered multinational model, leveraging cross-border capacity deployment for international project finance guarantees.
| Leading Market Players |
|---|
| The Travelers Indemnity Company |
| Liberty Mutual Insurance Company |
| Chubb Limited |
| CNA Financial Corporation |
| The Hartford |
| Crum & Forster |
| American Financial Group |
| Zurich Insurance Group |
| Great American Insurance Company |
| Others |
Value Chain & Pricing Dynamics
Federal contractor procurement offices and large infrastructure developers concentrate buying power across the United States, anchoring a value-based pricing model where bond premiums correlate with project completion risk and obligee protection value rather than standardized rate cards.
Pricing Analysis
Outcome-contingent pricing dominates contract surety, with premium rates scaling to project milestone complexity and principal creditworthiness. Price differentiation hinges on contractor experience modifiers and federal certification tier, alongside collateral backing intensity. Pricing pressure stems from alternative guarantee instruments displacing traditional bonds on private developer projects. Emerging contractors in SBA programs exhibit highest price sensitivity, while established federal prime contractors accept premium tiers for obligee relationship continuity.
Supply Chain Analysis
Domestic-content requirements in US federal procurement and EU Green Deal local sourcing mandates reshape reinsurance and capacity sourcing patterns. Underwriting capacity concentrates in the United States, Bermuda, and London, with collateral instruments drawing from Treasury securities, cash deposits, and letters of credit. Single-source vulnerability sits with Bermuda reinsurers following multi-year weather losses. Distribution runs through national brokers, direct carrier platforms, and captive arrangements for large developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
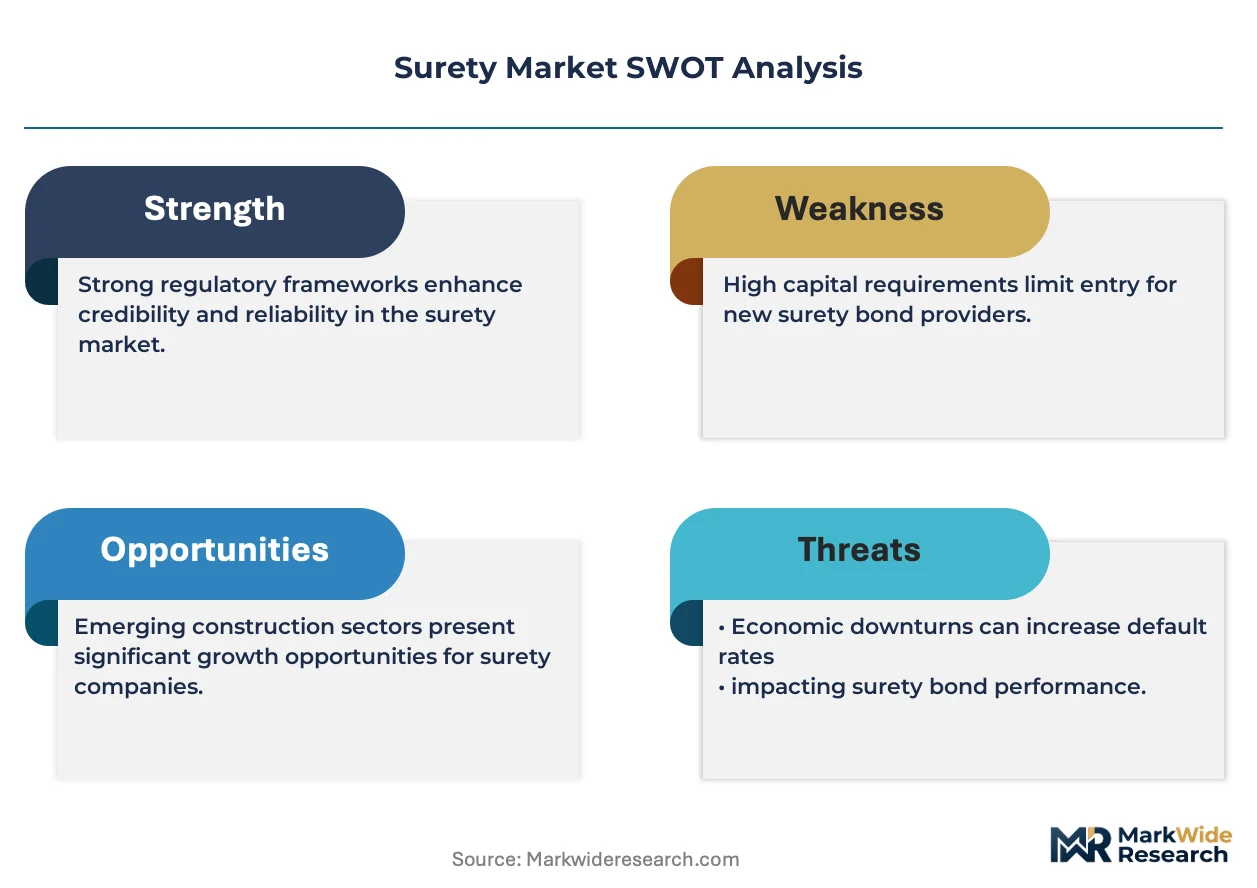
The surety market functions as a cost-of-compliance arena where Miller Act thresholds and EU Green Deal procurement standards erect regulatory moats favoring carriers with established obligee relationships and specialized construction underwriting infrastructure.
For Market Incumbents: Deploy digital bond issuance platforms to compress underwriting cycles and capture mid-market contractor volume. Deepen specialization in environmental guarantee instruments as EU sustainability-linked tender requirements harden. Counter alternative risk transfer instruments by embedding real-time project monitoring into bond indemnity structures. For New Entrants and Emerging Players: Launch via subcontractor default insurance convergence products targeting Texas and Florida renewable energy interconnection projects. White-space concentrates with tier-2 and tier-3 subcontractors lacking established carrier relationships. Penetrate through API-driven risk scoring platforms that bypass legacy financial statement review workflows. For Investors and Strategic Acquirers: The window for entry favors diversified carriers with dormant surety divisions seeking construction underwriting specialization. Long-term viability hinges on federal infrastructure authorization continuity and green procurement standard diffusion. Monitor digital bond platform adoption rates as inflection signal for underwriting margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Bond Platform Deployment | Blockchain-verified smart contracts streamline obligee verification for mid-market US contractors. |
| Environmental Guarantee Expansion | EU Green Deal sustainability-linked tender requirements harden contract performance criteria across member states. |
| Subcontractor Default Insurance Convergence | Hybrid products address completion risk on complex vertical construction in New York and Illinois. |
| Reinsurance Partnership Restructuring | Bermuda and London market capacity tightening following multi-year weather losses reshapes ceding strategies. |
| SBA Surety Program Participation | Federal guarantee mechanisms reduce collateral barriers for emerging contractors bidding on set-aside contracts. |
Study Parameters
Independent corroboration across surety underwriters, federal procurement officers, and construction finance executives underwrites the qualitative findings. Primary fieldwork engaged contract surety specialists, reinsurance brokers, and infrastructure contractor risk managers. Secondary validation drew from SEC 10-K filings of listed carriers, Federal Highway Administration procurement databases, and EU public procurement notices. Bottom-up premium volume estimates triangulated against top-down infrastructure spending authorization data.
Comparable historical periods anchored the projection horizon to established infrastructure investment cycles and regulatory implementation timelines. The analytical framework modeled segmentation across product type, client sophistication tier, application environment, and regional regulatory cluster. CAGRs derived from trend extrapolation of mandatory bonding thresholds and green procurement standard adoption curves. Forecast inputs incorporated Federal Reserve rate cycle assumptions and EU Corporate Sustainability Reporting Directive implementation pace.
The model assumes a particular technology adoption path; alternative pathways for blockchain-verified smart contracts would alter the outlook. Forecasts reflect assumptions regarding federal infrastructure authorization continuity and reinsurance market capacity stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
NPL Management Market
Risk Management and Compliance
United States Governance, Risk and Compliance Platform Market
Risk Management and Compliance
Enterprise Governance, Risk, and Compliance (Egrc) Market
Risk Management and Compliance
Risk-Based Monitoring Software Market
Risk Management and Compliance
Medical Device Cyber Risk Quantification Market
Risk Management and Compliance
Global Energy Trading and Risk Management (ETRM) Market
Risk Management and Compliance
Asia-Pacific Compliance and Traceability Solutions Market
Risk Management and Compliance
Healthcare Fraud Detection Market
Risk Management and Compliance
Fraud Detection and Prevention (FDP) Market
Risk Management and Compliance
Legal Advisory Service Market
Risk Management and Compliance
BFSI Crisis Management Market
Risk Management and Compliance
Financial Services Security Software Market
Risk Management and Compliance
Quality Warranty Management Market
Risk Management and Compliance
Europe BFSI Biometrics Market
Risk Management and Compliance
Europe Strategic Consulting Services Market
Risk Management and Compliance
Global Backstop Netting Systems Market