
 Home Theater Seating Market | 2026-2036
Home Theater Seating Market Size, Share, and Industry Trends Forecast 2026-2036
Home Theater Seating Market Foresight
Aftermarket service revenue for motorized recliner mechanisms is reshaping margin distribution across the Home Theater Seating value chain, pulling profitability away from pure manufacturing toward installation support and extended warranty programs. Valencia Seating leverages its North American assembly footprint to control lead times on custom-configured sectionals. Octane Seating anchors its position through proprietary lumbar support technology integrated across its powered recliner portfolio. La-Z-Boy competes by extending its residential furniture brand recognition into dedicated theater room channels.
Home theater seating comprises engineered furniture systems designed for extended viewing sessions, typically incorporating motorized recline actuators, ambient lighting integration, and acoustic absorption properties within frame construction. Manufacturers employ hardwood ply framing with high-density foam layering to achieve durability ratings exceeding residential sofa standards while maintaining ergonomic positioning for screen sightlines. Leather upholstery commands the dominant material position due to its acoustic dampening characteristics and premium positioning, though fabric alternatives are gaining fastest among price-sensitive residential buyers seeking breathable performance textiles. Single-seat configurations occupy the largest capacity segment by volume, while three-seat row arrangements concentrate margin pools in custom installation projects.
The Consumer Product Safety Commission governs motorized furniture safety standards in the United States, requiring pinch-point guarding and stability testing that elevates engineering costs for powered recliner entrants. California's Proposition 65 compliance obligations for foam flame retardant disclosures create additional labeling complexity for manufacturers distributing across state lines. Stakeholders must monitor evolving residential building energy codes that increasingly specify media room HVAC loads, directly influencing seating density and material thermal specifications in new construction specifications.
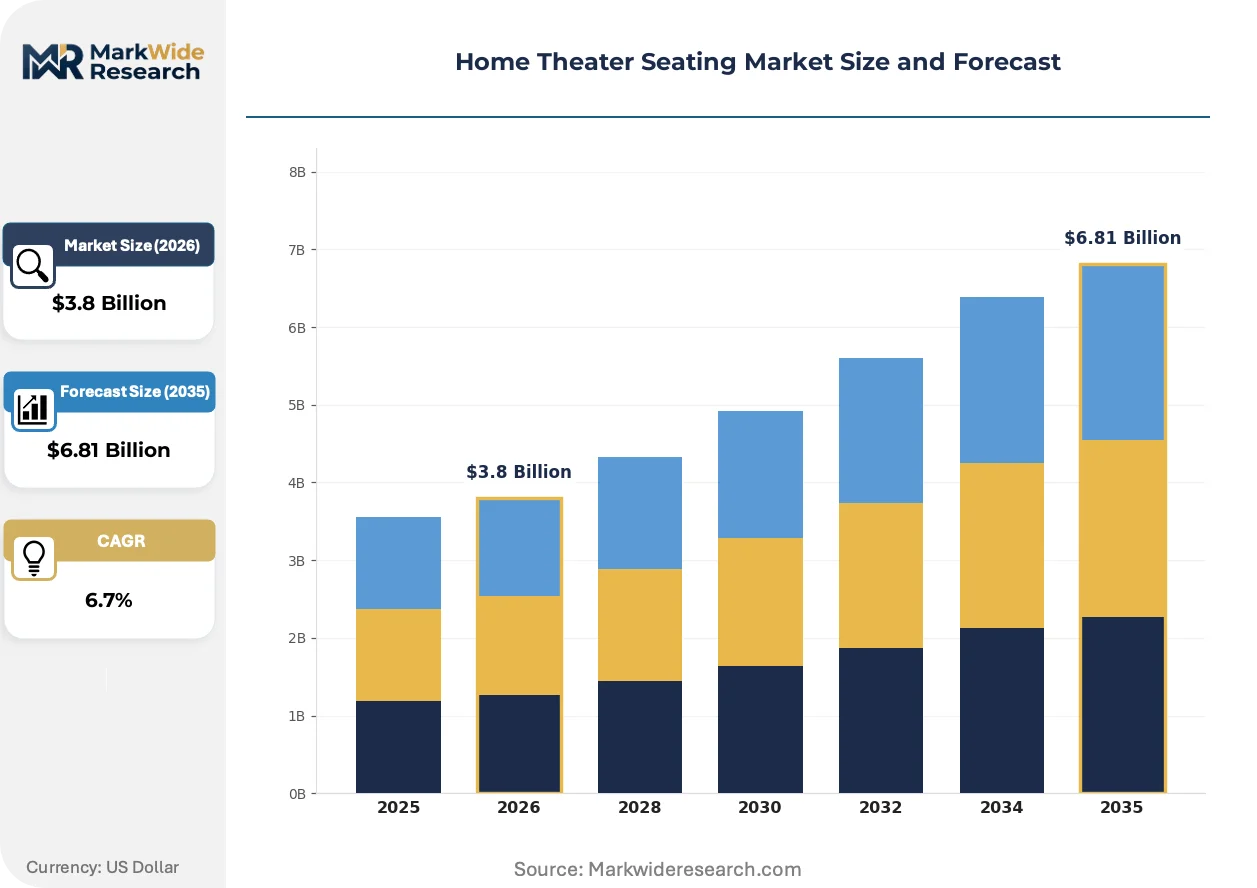
Market Dynamics
Motorized recliner actuators and smart home integration protocols are compressing replacement cycles while elevating engineering complexity for traditional furniture manufacturers.
Growth Catalysts
- Residential media room construction:Suburban new-build properties in the United States are incorporating dedicated theater spaces as standard amenities, pulling demand for powered sectional configurations.
- REACH-compliant flame retardant foams:European regulatory alignment on chemical safety is enabling cross-border distribution without reformulation costs, expanding addressable markets for upholstered seating exporters.
- Performance fabric technology:Stain-resistant synthetic weaves with acoustic dampening properties are capturing leather-averse buyers in humid climates.
Market Restraints
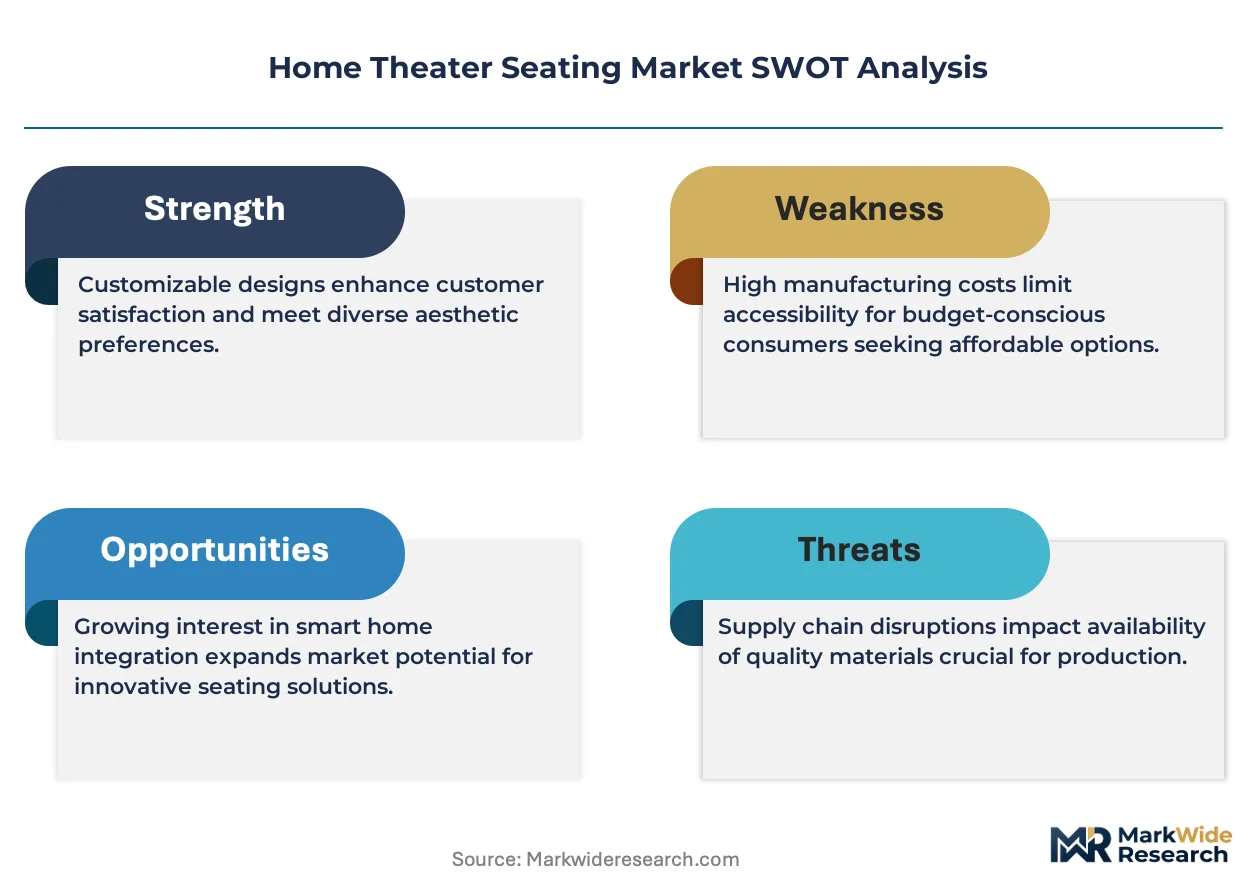
- Steel and aluminum price volatility:Frame construction relies on imported metal stock, exposing margins to commodity swings and tariff uncertainty.
- Actuator supply concentration:Precision motorized mechanisms source primarily from German and Chinese industrial component suppliers, creating single-source vulnerability.
- California Proposition 65 compliance:Foam chemical disclosure requirements impose labeling complexity that elevates administrative costs for multi-state distributors.
Strategic Opportunities
- India luxury residential segment:Mumbai and Delhi high-rise developments are introducing dedicated entertainment rooms, creating first-mover positioning for powered seating configurations.
- Extended warranty and installation services:Recurring revenue models for motorized mechanism maintenance are capturing margin pools previously lost to third-party repair networks.
- Biometric lumbar systems:Pressure-sensing adjustable support technology converging with mobile app control is differentiating premium tier offerings.
Industry Challenges
- Smart home protocol fragmentation:Integration with Crestron, Control4, and proprietary automation systems requires redundant engineering cycles and certification delays.
- Specialized upholstery craftsmanship:Performance fabric installation demands tension-calibration skills that outpace vocational training pipeline output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Theater Seating Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recliners, Sectionals, Sofas, Chairs Material: Leather, Fabric, Microfiber, Vinyl Capacity: Single Seat, Double Seat, Three Seat, Four Seat Feature: Built-in Speaker, Cup Holder, Adjustable Headrest, Massage Function |
| Companies Covered | Valencia Seating, Flash Furniture, Brassex, Octane Seating, Picket House, Coaster, Ideal Home, Acoustic Innovations, La-Z-Boy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Theater Seating Market Shifts & Advancements
Seating intelligence layers and material science advances are redefining durability expectations and service revenue models across residential cinema installations.
Wireless inductive charging modules embedded in armrest consoles are rendering obsolete hardwired USB port configurations that dominated 2018-2023 product cycles. Custom installation firms in Texas and Florida are specifying these systems in 40% of new residential media room projects. The shift is compressing SKU complexity while elevating average unit values for factory-installed electronics packages.
EPA formaldehyde emission standards for composite wood products are tightening substrate sourcing requirements for plywood framing components. Manufacturers are qualifying CARB Phase 2 certified suppliers to preempt enforcement exposure. Upholstered seating with exposed wood trim faces disproportionate compliance verification costs relative to fully upholstered frame designs.
Direct-to-consumer configuration tools are displacing traditional dealer showroom selection for single-seat and loveseat purchases. Online visualization platforms with dimensional accuracy guarantees are capturing buyer preference in the under-$3,000 price band. This channel rotation is most pronounced in secondary US metropolitan markets where dedicated furniture retailers have contracted floor space.
Home Theater Seating Market Segmentation
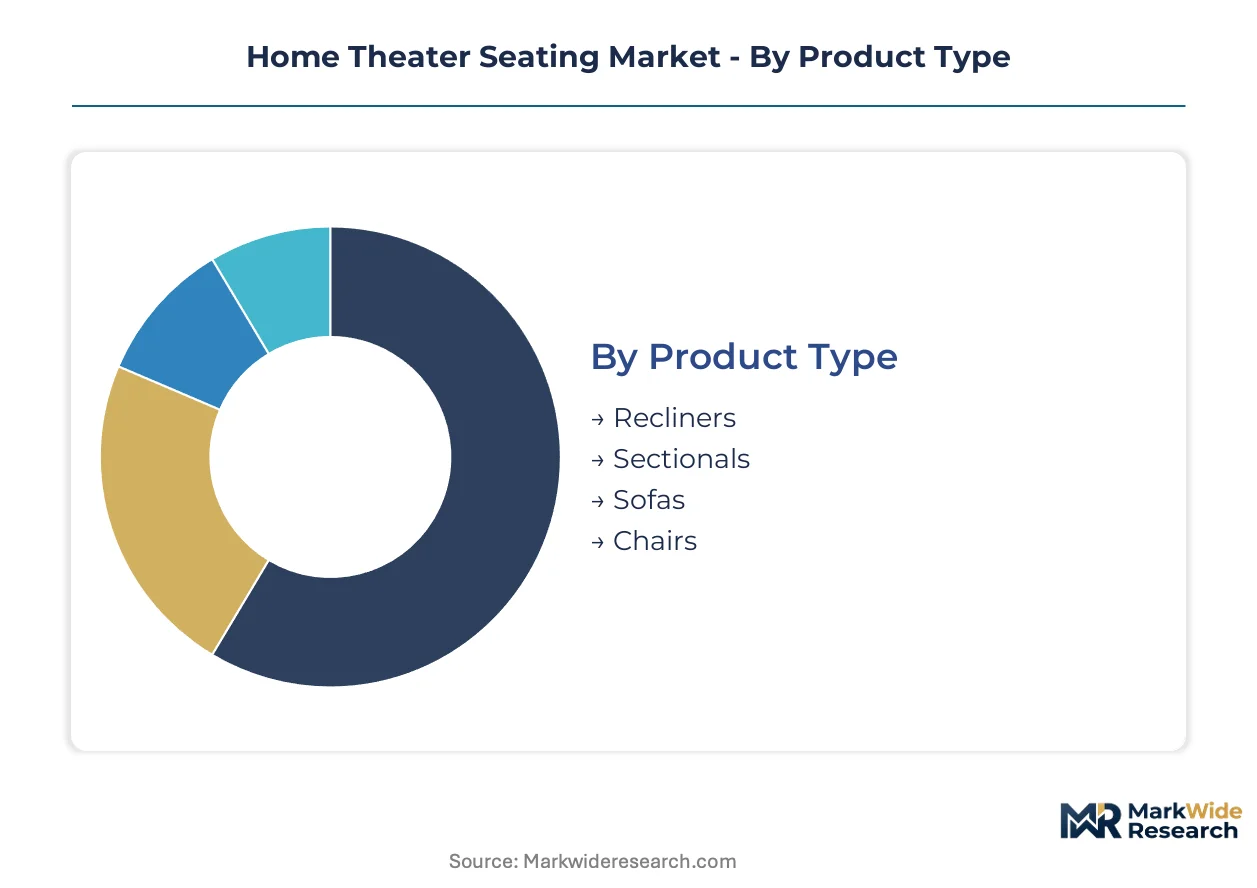
Home theater seating segmentation reveals divergent service intensity profiles across product configurations. Motorized mechanisms in premium tiers generate recurring maintenance revenue streams that reshape manufacturer economics differently than static furniture categories.
Product Type:
After-sales-service intensity varies sharply across seating architectures, with powered configurations demanding specialized technician networks that static frames bypass entirely.
- Recliners:Individual motorized units incorporate actuator assemblies, lumbar motors, and control modules requiring periodic calibration. Residential media rooms in Texas and Florida specify these in dedicated theater spaces where extended viewing sessions demand ergonomic adjustability. Service contracts for mechanism maintenance now constitute material revenue streams for installation firms.
- Sectionals:Modular configurations with integrated power systems span multiple seating positions, multiplying potential failure points across connected units. Custom installation projects in suburban United States new-build properties favor these for flexible room layouts, though field service complexity elevates total cost of ownership.
- Sofas:Traditional three-seat fixed frames dominate entry-level residential procurement with minimal service attachment.
- Chairs:Static accent seating occupies peripheral positions in media room layouts with negligible motorized component exposure.
By volume, Recliners leads. By growth pace, Sectionals is ahead.
Material:
Cost tier stratification in upholstery selection directly determines margin retention through product lifecycle, with premium hides commanding sustained replacement part economics.
- Leather:Full-grain and top-grain hides provide acoustic dampening properties valued in high-end residential installations. Humid climate buyers in Florida and Gulf Coast states increasingly specify these despite climate maintenance requirements. The material's durability sustains premium resale values in secondary furniture markets.
- Fabric:Performance synthetic weaves with stain-resistant coatings are capturing leather-averse segments in price-sensitive buyer pools. REACH-compliant flame retardant formulations enable cross-border distribution without reformulation costs, expanding manufacturer addressable markets.
- Microfiber:Synthetic suede alternatives occupy mid-tier positioning with balanced cleanability and tactile appeal.
- Vinyl:Polyurethane-coated substrates serve budget-conscious commercial and residential installations with minimal maintenance demands.
By volume, Leather leads. By expansion trajectory, Fabric is climbing the fastest.
Capacity:
Volume concentration in single-seat procurement reflects individual purchasing patterns, while row configurations concentrate project-based margin pools.
- Single Seat:Standalone powered units dominate direct-to-consumer channels where online configuration tools displace traditional showroom selection. Secondary United States metropolitan markets with contracted furniture retail floor space favor this format for simplified logistics.
- Three Seat:Row arrangements anchor custom installation projects in dedicated media room construction, where integrated power and lighting systems elevate average unit values. California's Proposition 65 compliance obligations for foam disclosures impose labeling complexity that multi-state distributors absorb across these higher-value transactions.
- Double Seat:Loveseat configurations serve compact residential spaces with coupled seating demand.
- Four Seat:Extended rows target commercial cinema and large residential installations with specialized sightline engineering.
By volume, Single Seat leads. By value concentration, Three Seat is gaining share fastest.
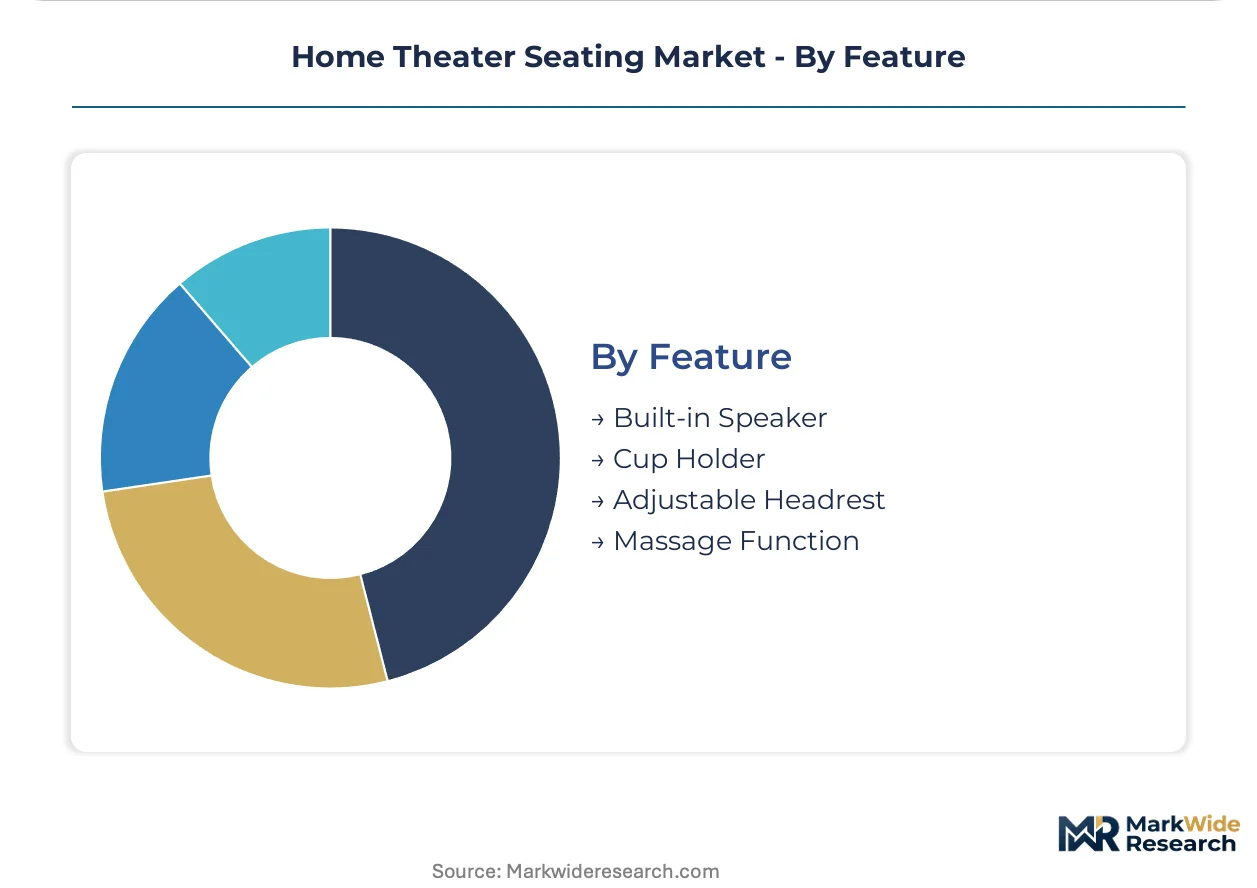
Feature:
Technology integration layers differentiate premium tier offerings while compressing replacement cycles through obsolescence pressure.
- Adjustable Headrest:Motorized positioning systems converge with mobile app control protocols, requiring redundant engineering cycles for Crestron and Control4 certification. Biometric pressure-sensing variants are emerging as differentiation points in luxury residential specifications.
- Built-in Speaker:Wireless inductive charging modules embedded in armrest consoles are displacing hardwired USB configurations that dominated prior product cycles. Texas and Florida installation firms specify these in substantial shares of new residential media room projects.
- Cup Holder:Integrated cooling and lighting features elevate basic convenience functions into premium positioning elements.
- Massage Function:Vibration and heating mechanisms add component complexity with elevated warranty exposure.
By volume, Cup Holder leads. By technology momentum, Adjustable Headrest is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in humid subtropical markets demonstrate the highest price elasticity, while purchasers in arid western climates absorb premium leather configurations with minimal resistance. This demand-elasticity contrast shapes regional procurement patterns across residential cinema installations.
United States
Suburban new-build properties in Texas and Florida specify powered sectional configurations as standard media room amenities. The Consumer Product Safety Commission governs motorized furniture safety standards, requiring pinch-point guarding that elevates engineering costs. Installation firms in Dallas-Fort Worth and Miami-Dade County now generate material revenue from extended warranty programs for motorized mechanism maintenance.
Canada
REACH-compliant flame retardant foams enable cross-border distribution without reformulation costs, expanding manufacturer addressable markets in Ontario and Quebec. Health Canada maintains aligned chemical safety standards with European regulatory frameworks. Toronto and Vancouver residential developers incorporate dedicated entertainment rooms in luxury high-rise specifications, pulling demand for custom-configured seating.
Germany
Precision motorized actuator mechanisms source primarily from German industrial component suppliers, creating supply-side concentration for European seating assemblers. ECHA REACH regulations govern foam chemical safety and labeling obligations. The Stuttgart and Munich metropolitan clusters anchor upholstered furniture manufacturing with integrated electronics packaging capabilities.
China
Performance fabric technology with stain-resistant synthetic weaves captures leather-averse buyer segments in humid southern provinces. GB standards and MIIT regulations shape composite wood product emission requirements for frame construction. The Pearl River Delta manufacturing corridor concentrates upholstered furniture export capacity with integrated smart home electronics integration.
India
Mumbai and Delhi high-rise developments introduce dedicated entertainment rooms, creating first-mover positioning for powered seating configurations in the luxury residential segment. BIS certification requirements for imported furniture components create compliance complexity for multi-state distributors. The Maharashtra and Delhi-NCR construction corridors concentrate premium residential media room installations.
Home Theater Seating Market Competitive Landscape
Capability concentration sits with specialized seating engineers; scale advantage sits with diversified residential furniture conglomerates. The market structures around three tiers: dedicated theater seating specialists, multi-category upholstery manufacturers, and contract furniture suppliers. Strategic archetypes include powered mechanism integrators, performance fabric innovators, and direct-to-consumer configuration platforms. Dominant competitive moves center on extended warranty service models and smart home protocol certification partnerships.
Within the specialized seating tier, Valencia Seating, Octane Seating, and La-Z-Boy occupy distinct positioning vectors. Valencia Seating exemplifies the North American assembly footprint archetype with controlled lead time capabilities. Octane Seating represents proprietary technology integration across powered recliner portfolios. La-Z-Boy anchors the brand extension strategy, leveraging residential furniture recognition into dedicated theater room channels. These three entities collectively illustrate how competitive differentiation converges on service infrastructure, mechanism engineering, and consumer brand equity rather than manufacturing scale alone.
| Leading Market Players |
|---|
| Valencia Seating |
| Flash Furniture |
| Brassex |
| Octane Seating |
| Picket House |
| Coaster |
| Ideal Home |
| Acoustic Innovations |
| La-Z-Boy |
| Others |
Supply & Pricing Matrix
Steel and aluminum price volatility determines both tier spreads and supply chain configuration in home theater seating. Commodity swings compress margins on entry-level vinyl and microfiber configurations while elevating the premium commanded by leather-upholstered powered recliners with captive mechanism sourcing.
Pricing Analysis
Extended warranty and installation service contracts now anchor lifetime value capture for motorized recliner portfolios. Three-tier pricing structure across premium leather, standard fabric, and economy vinyl levels stratifies buyer pools by climate sensitivity and customization demand. Cost compression in entry-tier static seating intensifies as direct-to-consumer channels displace dealer markups. Price-sensitive buyers in humid subtropical markets gravitate toward performance fabric alternatives, while arid western climate purchasers absorb full-grain leather premiums with minimal resistance.
Supply Chain Analysis
Pearl River Delta contract manufacturers concentrate upholstered frame assembly capacity for North American and European brands. Precision motorized actuators draw from German and Chinese industrial component suppliers, creating single-source vulnerability for powered mechanism integrators. Frame construction hinges on CARB Phase 2 certified plywood substrates to satisfy EPA formaldehyde emission standards. Distribution runs through custom installation firms in Texas and Florida for premium sectional configurations, while direct-to-consumer platforms capture single-seat transactions in secondary metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across smart home protocol standards creates niche positioning opportunities for specialized integrators. Direct-to-consumer configuration tools are splitting demand between showroom-dependent and digitally-native buyer archetypes.
For Market Incumbents: Pre-empt margin erosion in static seating by consolidating aftermarket service networks for motorized mechanism maintenance. Incumbents should deepen captive supply of precision actuators to offset German and Chinese supplier concentration. Channel control through exclusive partnerships with Crestron and Control4 certification programs defends premium positioning against direct-to-consumer entrants.
For New Entrants and Emerging Players: India's Maharashtra and Delhi-NCR construction corridors offer underpenetrated white space for powered sectional configurations in luxury high-rise entertainment rooms. New entrants should target price-sensitive fabric buyers in Florida and Gulf Coast humid climates with REACH-compliant flame retardant formulations. A direct-to-consumer visualization platform with dimensional accuracy guarantees captures share in contracted furniture retail markets.
For Investors and Strategic Acquirers: The market sits at a technology-integration phase that favors specialized seating engineers with proprietary lumbar systems over diversified furniture conglomerates. Long-term viability rests on recurring revenue attachment rates for motorized mechanism service contracts. Investors should monitor smart home protocol consolidation as an inflection signal for platform-dependent valuation multiples. Cross-checking against residential construction permit data in Texas and Florida is advised before commitment-grade decisions.
| Strategic Initiative | Industry Significance |
|---|---|
| Extended Warranty Program Launch | Captures recurring revenue pools previously lost to third-party repair networks in motorized recliner portfolios. |
| Smart Home Certification Partnership | Secures Crestron and Control4 integration pathways that compress competitor engineering cycles. |
| Performance Fabric Technology Investment | Enables REACH-compliant cross-border distribution without reformulation costs in European markets. |
| North American Assembly Footprint Expansion | Controls lead times on custom-configured sectionals for suburban new-build media room projects. |
| Biometric Lumbar System Development | Differentiates premium tier offerings through pressure-sensing adjustable support with mobile app control. |
Research Methodology
Initial hypotheses were tested against primary input from custom installation firm owners, motorized mechanism procurement leads, upholstery manufacturing plant managers, and residential media room designers and refined through secondary validation. Sources included customs and trade data on upholstered furniture imports, EPA and CARB regulatory filings on composite wood emissions, Consumer Product Safety Commission motorized furniture safety standards, and SEC 10-K disclosures from diversified residential furniture conglomerates. Bottom-up unit economics triangulated against top-down construction spending projections.
Demand-supply balance modeling across the projection horizon incorporated product type segmentation by motorized versus static configurations, material tiers from full-grain leather to performance synthetics, capacity formats spanning single-seat through four-seat rows, and feature integration levels from basic cup holders to biometric lumbar systems. CAGRs were derived from regression analysis against residential construction permit flows and media room specification rates. Industry-specific inputs included actuator supplier lead time variability and REACH compliance cost differentials across foam formulations.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by diversified furniture conglomerates would shift outcomes substantially. Cross-checking against regional building energy code adoption timelines for media room HVAC specifications is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
Cat Diets Market
Consumer Goods
Cyber-Shoes Market
Consumer Goods
Crystal Bracelets Market
Consumer Goods
Global Bath Salts Market
Consumer Goods
Gardening Pots Market
Consumer Goods
Mexico Washing Machine Market
Consumer Goods
Beauty Salon Market
Consumer Goods
Asia-Pacific Home Appliances Market
Consumer Goods
Biodegradable Diapers Market
Consumer Goods
Smart Jewelry Market
Consumer Goods
Electric Hair Clipper and Trimmer Market
Consumer Goods
Vegan Cat Food Market
Consumer Goods
India Small Home Appliances Market
Consumer Goods
Rooftop Tent Market
Consumer Goods
Baby Nipple/Teat Market
Consumer Goods
Digital Piano Market