
 Malaysia Shampoo Market | 2026-2036
Malaysia Shampoo Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Shampoo Market Outlook
Malaysia's halal certification mandate is rebalancing formulation priorities across the shampoo sector. Unilever leverages its extensive halal-compliant portfolio to sustain shelf dominance in modern trade channels. Procter & Gamble anchors its position through R&D investment in sulfate-free and plant-derived variants tailored to Muslim consumer preferences. L'Oréal competes by controlling premium salon distribution networks that bypass mass-market price erosion.
Shampoo comprises surfactant-based cleansing formulations typically containing 10-20% active detergents, conditioning agents, and functional additives designed for scalp and hair fiber maintenance. The product type dimension spans Anti-Dandruff, Moisturizing, Color Protection, and Volume Boosting formulations, with Moisturizing variants capturing margin pools amid rising concerns over tropical humidity damage. The end user dimension segments into Men, Women, Children, and Salon Professionals, where Salon Professionals represents the fastest-growing channel as Malaysia's beauty services workforce expands beyond 35,000 registered practitioners.
NPRA halal enforcement, BIS-equivalent cosmetic safety standards, and Ministry of Health (MOH) cosmetic notification requirements collectively shape permissible ingredients and labeling protocols. Malaysia's adherence to ASEAN Cosmetic Directive harmonization further tightens import compliance for non-domestic manufacturers. Stakeholders must monitor evolving halal ingredient rulings and state-level enforcement variance between Peninsular Malaysia and East Malaysian territories.
Market Dynamics
NPRA halal certification mandates are restructuring Malaysia's shampoo formulation landscape, forcing manufacturers to reformulate surfactant bases and source alcohol-free preservatives while maintaining cleansing efficacy in tropical humidity conditions.
Growth Catalysts
- Professional Salon Channel Expansion:Malaysia's registered beauty services workforce now exceeds 35,000 practitioners, creating sustained demand for salon-grade formulations that command premium positioning over mass-market alternatives.
- ASEAN Cosmetic Directive Harmonization:Regulatory alignment across Southeast Asian markets is streamlining cross-border product registration for Malaysian manufacturers seeking regional export growth.
- Sulfate-Free Surfactant Innovation:Advanced plant-derived cleansing agents derived from coconut and palm kernel sources are replacing traditional sodium lauryl sulfate in formulations targeting sensitive scalp segments.
Market Restraints
- Palm-Derived Feedstock Volatility:Malaysia's shampoo sector depends on domestic palm oil derivatives for surfactant production, exposing margins to commodity price swings and sustainability certification costs.
- Import Dependency for Specialty Additives:Conditioning polymers and UV filters remain concentrated among European and Japanese specialty chemical suppliers, creating supply vulnerability for local formulators.
- Halal Certification Timeline Friction:NPRA's multi-stage ingredient verification process extends product development cycles by 8-14 months for new formulations seeking compliance.
Strategic Opportunities
- East Malaysia Distribution Gap:Sabah and Sarawak territories show underpenetrated modern trade coverage relative to Peninsular Malaysia, presenting first-mover potential for organized retail expansion.
- Child-Specific Formulation Segment:Pediatric dermatologist-recommended shampoo variants represent an emerging white space as parental concern over synthetic ingredient exposure intensifies among urban households.
- E-Commerce Direct-to-Consumer Channels:Platform-specific subscription models on Shopee and Lazada are bypassing traditional wholesale markups while capturing recurring revenue from convenience-seeking buyers in Greater Kuala Lumpur.
Industry Challenges
- Halal Chemist Talent Scarcity:Qualified formulators capable of navigating NPRA ingredient rulings while maintaining product performance remain limited, constraining R&D throughput for mid-tier manufacturers.
- Legacy Manufacturing Equipment Retrofit Costs:Transitioning production lines to handle alcohol-free processing and segregated halal-compliant workflows demands capital outlays that strain smaller domestic players.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Shampoo Market |
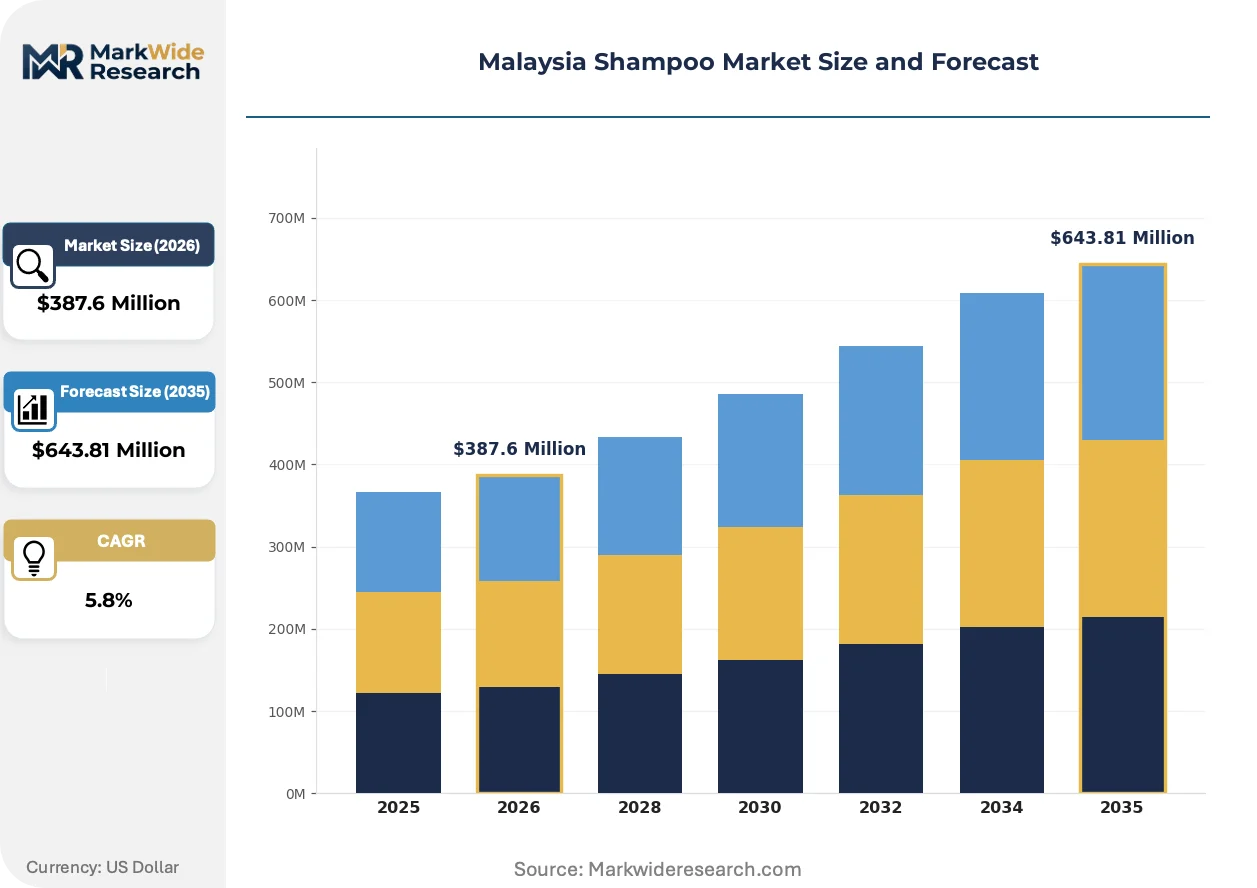
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anti-Dandruff, Moisturizing, Color Protection, Volume Boosting End User: Men, Women, Children, Salon Professionals Packaging Type: Bottles, Sachets, Jars, Pumps Distribution Channel: Supermarkets, Online Retail, Salons, Pharmacies |
| Companies Covered | Unilever, Procter & Gamble, L'Oréal, Henkel, Schwarzkopf, Wella, Kao Corporation, Colgate-Palmolive Company, Coty Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Shampoo Market Strategic Shifts
Malaysia's shampoo sector is experiencing accelerated formulation evolution as halal compliance requirements intersect with tropical climate performance demands and professional salon channel sophistication.
Biodegradable surfactant systems derived from fermented agricultural byproducts are integrating into premium shampoo bases to replace petroleum-derived cleansing agents. Salon professionals in Selangor and Kuala Lumpur are adopting these formulations at twice the rate of mass-market consumers, compressing the performance gap between professional and retail-grade products while elevating ingredient transparency expectations across all price tiers.
NPRA's 2024 tightening of preservative allowance lists is forcing reformulation of existing product lines containing methylisothiazolinone and formaldehyde-releasing compounds. Manufacturers must submit updated safety dossiers for continued market authorization, with moisturizing and anti-dandruff segments facing the highest compliance burden due to their reliance on long-acting preservation systems.
Subscription-based replenishment models through e-commerce platforms are displacing traditional hypermarket bulk purchases among urban millennial households. Shopee's auto-replenishment feature now captures significant recurring orders from dual-income families in Petaling Jaya and Subang Jaya, shifting inventory risk from retailers to manufacturers while compressing brand switching costs through algorithmic recommendation engines.
Malaysia Shampoo Market Segmentation
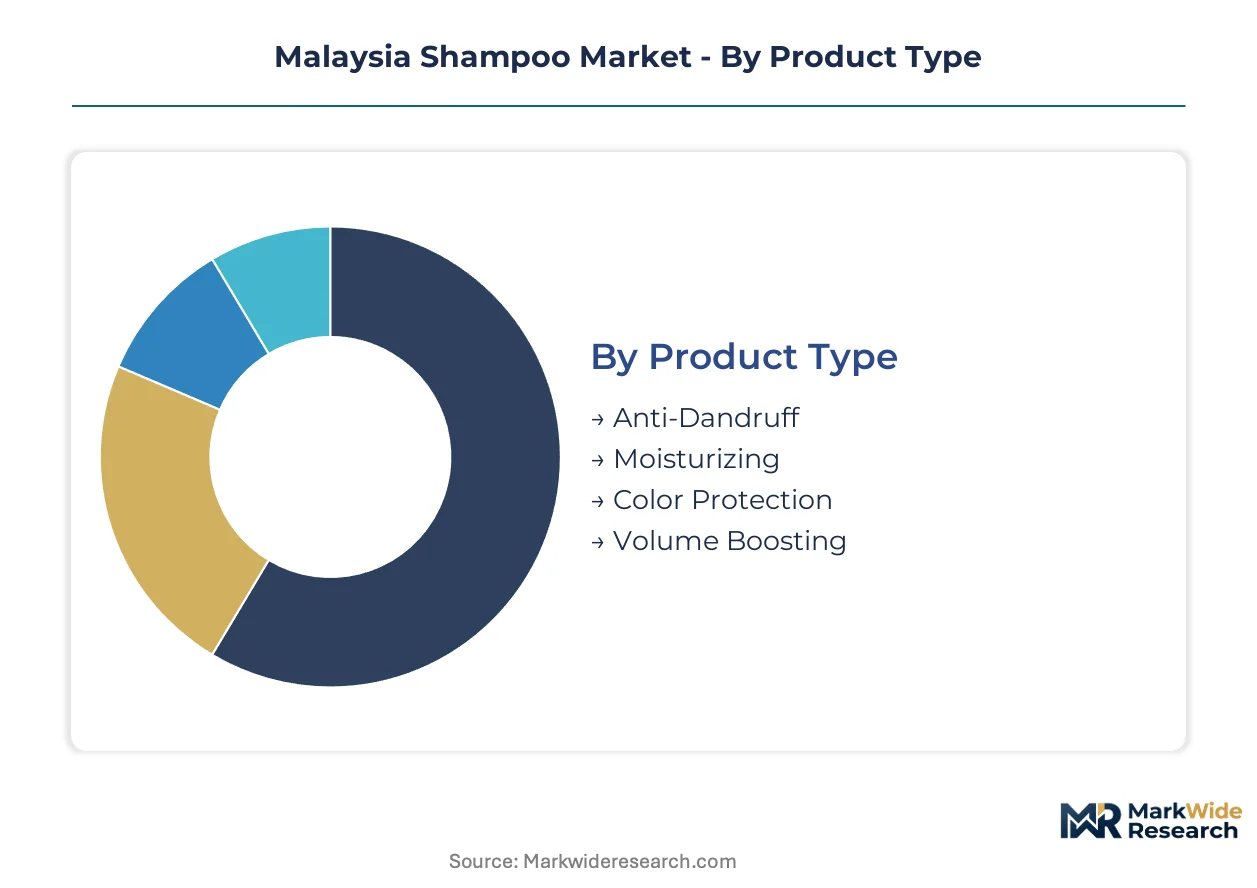
Malaysia's shampoo segmentation reflects the NPRA's halal certification architecture, where formulation chemistry and channel access vary sharply across product types and end-user categories. Manufacturers must align segment-specific R&D investments with divergent compliance timelines and distribution infrastructure requirements.
Product Type:
NPRA halal mandates impose tiered certification burdens: anti-dandruff variants face extended preservative scrutiny, while moisturizing formulations navigate alcohol-free emollient sourcing requirements.
- Moisturizing:Humectant-rich formulations incorporating glycerin and panthenol address tropical humidity-induced cuticle damage. Demand concentrates in Kuala Lumpur and Selangor urban households where dual-income families prioritize scalp barrier maintenance.
- Anti-Dandruff:Zinc pyrithione and selenium sulfide actives require NPRA safety dossier submission for continued authorization. Salon professionals in Petaling Jaya adopt these at premium price points for client treatment protocols.
- Color Protection:UV-filtering chemistries protect oxidative dye degradation in Malaysia's high-UV index climate.
- Volume Boosting:Lightweight polymer systems target fine-hair demographics without residue accumulation in humid conditions.
Leading the category by volume: Moisturizing. Growing fastest: Anti-Dandruff.
End User:
Customer-type segmentation determines channel economics, with salon professionals commanding margin multiples over mass-market consumer tiers through technical service bundling.
- Salon Professionals:Bulk-format, high-concentration formulations designed for back-bar dilution and professional application protocols. Malaysia's 35,000 registered beauty practitioners drive institutional procurement through distributor networks in Klang Valley.
- Women:Multi-step regimen purchasers averaging higher basket values across shampoo-conditioner-treatment combinations. Urban millennials in Subang Jaya demonstrate strongest subscription adoption via Shopee auto-replenishment.
- Men:Simplified, two-in-one cleansing formats targeting convenience-oriented grooming routines.
- Children:Tear-free, mild surfactant systems requiring pediatric dermatologist endorsement for parental trust conversion.
Highest margin capture: Salon Professionals. Steepest expansion trajectory: Children.
Packaging Type:
Format selection intersects with halal supply chain integrity, where pump and bottle systems require segregated production workflows to prevent cross-contamination risks.
- Bottles:Standard polyethylene terephthalate containers dominate modern trade shelf presence. Peninsular Malaysia's organized retail density supports economies of scale in blow-molded packaging procurement.
- Pumps:Metered-dispense systems reduce product waste in professional salon environments. Selangor's salon supply distributors prioritize these for back-bar efficiency.
- Sachets:Single-use formats penetrate East Malaysia's price-sensitive rural markets and trial-size sampling campaigns.
- Jars:Wide-mouth containers serve mask and treatment sub-categories requiring finger-scoop application.
Volume leadership: Bottles. Fastest format growth: Pumps.
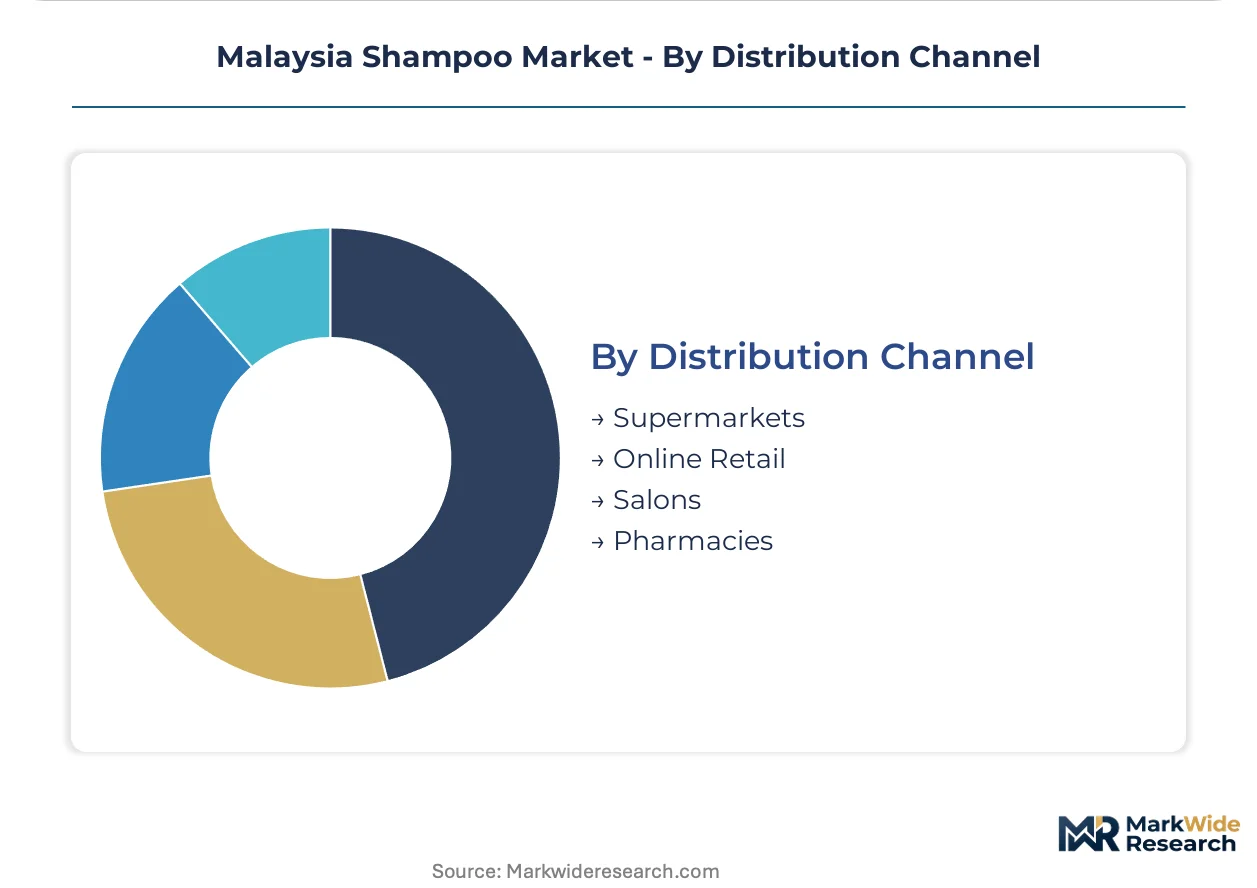
Distribution Channel:
Channel segmentation maps directly to NPRA notification requirements, where pharmacy and salon channels face stricter ingredient disclosure protocols than general retail.
- Supermarkets:Hypermarket and supermarket chains anchor mass-market volume through promotional stacking and private-label placement. Greater Kuala Lumpur's retail density concentrates competitive shelf-space battles.
- Online Retail:Shopee and Lazada platform algorithms compress brand discovery costs while enabling direct-to-consumer halal certification transparency. Petaling Jaya households show highest recurring order frequency.
- Salons:Professional-only distribution networks bypass retail margin structures through exclusive distributor relationships. Technical training requirements limit unauthorized channel diversion.
- Pharmacies:Dermatologist-recommended and medicated variants require pharmacist consultation protocols under Ministry of Health oversight.
Dominant volume channel: Supermarkets. Expanding most quickly: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kuala Lumpur anchors Malaysia's shampoo demand concentration, with the Klang Valley metropolitan corridor generating disproportionate premium product pull through modern trade density and salon network clustering.
Selangor
Urban households in Petaling Jaya and Subang Jaya drive moisturizing variant adoption amid dual-income family expansion. NPRA halal enforcement tightens preservative allowances for products manufactured in Shah Alam industrial zones. Selangor's salon supply distributors concentrate in Damansara, channeling professional-grade formulations to Malaysia's expanding beauty services workforce.
Penang
Georgetown's manufacturing base supports surfactant production from palm-derived feedstock, integrating with Peninsular Malaysia's chemical processing corridor. Ministry of Health cosmetic notification requirements govern export-oriented production from Bayan Lepas industrial parks. Penang's port infrastructure facilitates ASEAN Cosmetic Directive-aligned shipments to regional markets.
Johor
Iskandar Malaysia's logistics hub status attracts distribution center investment for shampoo imports transiting Singapore. The state's proximity to halal certification bodies accelerates product registration timelines for new market entrants. Johor Bahru retail clusters serve cross-border demand from Singaporean consumers seeking price-differentiated formulations.
Sabah
East Malaysia's underpenetrated modern trade coverage creates first-mover expansion potential for organized retail. Sachet formats dominate Kota Kinabalu's price-sensitive rural markets, contrasting with Peninsular Malaysia's bottle-format preference. State-level enforcement variance in halal compliance adds regulatory complexity for manufacturers establishing East Malaysian distribution.
Sarawak
Kuching's emerging urban middle class demonstrates trial-size sampling responsiveness for premium shampoo variants. The territory's distance from NPRA headquarters in Putrajaya extends certification timeline friction for new product launches. Sarawak's independent retail channel density exceeds modern trade penetration, shaping go-to-market cost structures for national brand expansion.
Malaysia Shampoo Market Competitive Environment
The competitive structure tilts toward multinational conglomerates with halal-compliant global portfolios. Shelf dominance in Malaysian modern trade channels concentrates among three to four parent entities controlling multiple brand tiers. Strategic archetypes include: (1) diversified FMCG conglomerates leveraging scale economies in surfactant procurement; (2) professional salon specialists capturing margin multiples through technical service bundling; and (3) regional Asian manufacturers competing on palm-derived ingredient proximity. Dominant competitive moves encompass portfolio diversification across sulfate-free and plant-derived variants, plus strategic partnerships with local distributors to penetrate East Malaysian territories.
Within the diversified conglomerate tier, Unilever and Procter & Gamble exemplify archetypes anchored by global R&D infrastructure adapted to NPRA compliance requirements. L'Oréal occupies a position representing premium salon channel specialization, with distribution networks that bypass mass-market price erosion through professional exclusivity. These three entities collectively demonstrate how multinational scale intersects with localized halal certification capabilities to sustain competitive positioning in Malaysia's reformulation-intensive regulatory environment.
| Leading Market Players |
|---|
| Unilever |
| Procter & Gamble |
| L'Oréal |
| Henkel |
| Schwarzkopf |
| Wella |
| Kao Corporation |
| Colgate-Palmolive Company |
| Coty Inc. |
| Others |
Value Chain & Pricing Dynamics
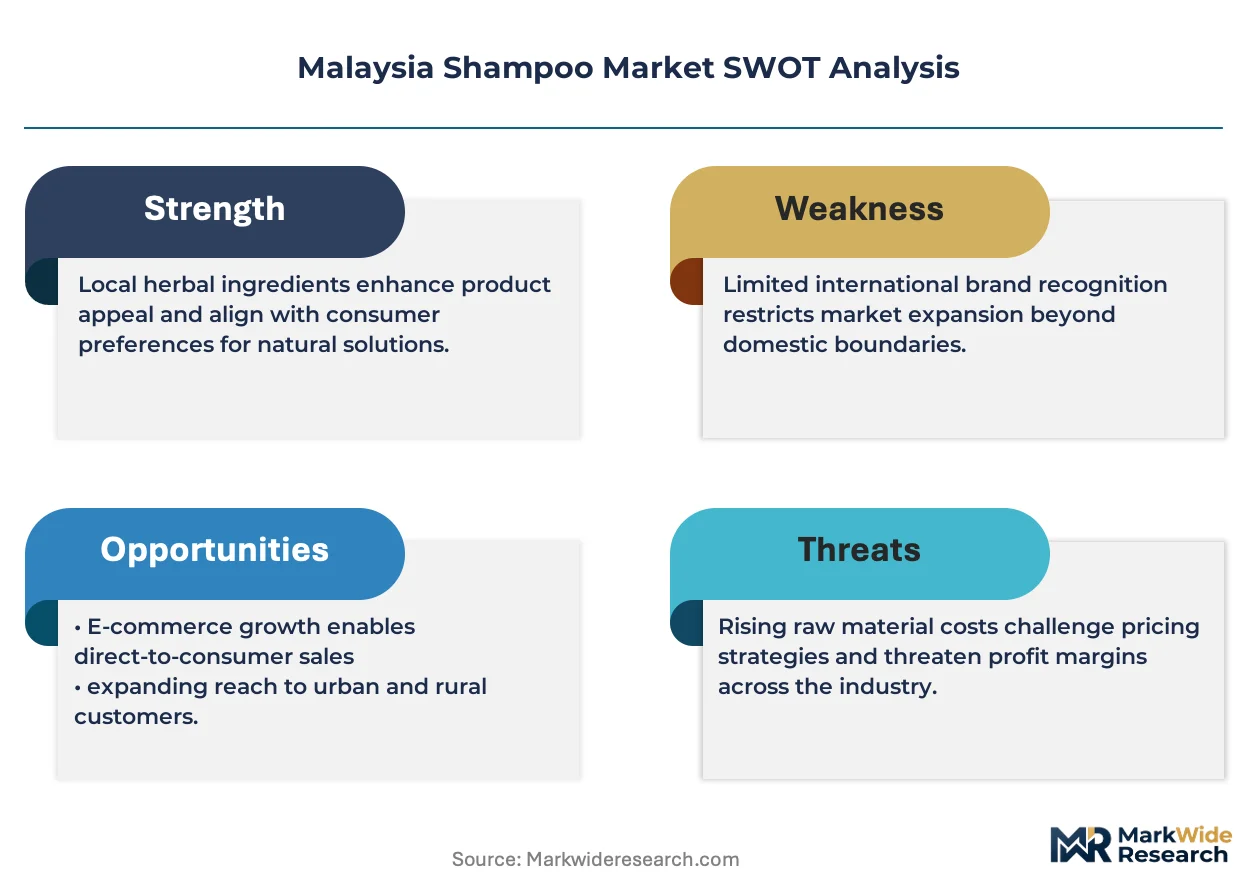
Certification-grade divergence between NPRA halal-compliant formulations and conventional alternatives manifests in both pricing premiums and segregated manufacturing workflows. Salon-grade products commanding value-based positioning source alcohol-free preservatives through dedicated supply channels, while mass-market tiers absorb palm-derived surfactant volatility through volume-scale procurement.
Pricing Analysis
Value-based pricing anchors salon-grade formulations to treatment outcomes and professional throughput metrics. Three-tier pricing structure across premium, standard, and economy levels separates NPRA-certified salon exclusives from mass-market halal variants and sachet-format rural offerings. Price differentiation stems from certification grade and volume scale, with cost compression in the standard tier intensifying due to feedstock volatility. Salon professionals show least price sensitivity; East Malaysian sachet buyers demonstrate highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with European and Japanese specialty chemical suppliers for conditioning polymers and UV filters. Malaysia's shampoo sector draws from domestic palm oil derivatives, European polymer specialists, and ASEAN fragrance houses. Regulatory restriction through NPRA halal enforcement creates supply chain risk for non-compliant imports. Distribution runs through Klang Valley modern trade clusters, professional salon distributor networks, and Shopee-Lazada platform fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around halal certification capabilities that force smaller domestic formulators into acquisition or exit. NPRA compliance timelines and retrofit capital requirements disproportionately burden mid-tier manufacturers lacking multinational R&D infrastructure.
For Market Incumbents: Lock in salon channel exclusivity through technical training partnerships that bind Malaysia's 35,000 registered practitioners to proprietary protocols. Deepen backward integration into palm-derived surfactant production to neutralize feedstock volatility threatening margin stability. Defend against regional Asian manufacturers by accelerating sulfate-free formulation pipelines ahead of NPRA preservative tightening.
For New Entrants and Emerging Players: The mid-tier price-point gap between L'Oréal salon exclusives and Unilever mass-market dominance offers white-space entry for halal-certified specialty brands. East Malaysia's underpenetrated modern trade coverage presents the most penetrable geography, with Kota Kinabalu's sachet-to-bottle upgrade trajectory supporting premium trial. Launch through Shopee subscription models to bypass traditional wholesale markups and capture recurring revenue from Petaling Jaya dual-income households.
For Investors and Strategic Acquirers: Re-rating potential sits with domestic formulators possessing NPRA pre-approved ingredient libraries given accelerating compliance timeline friction. Long-term viability favors targets with captive halal chemist talent and Shah Alam manufacturing assets adaptable to alcohol-free processing. Watch for inflection when NPRA announces expanded preservative prohibition lists forcing industry-wide reformulation cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Acceleration | Pre-approved ingredient dossiers compress NPRA timelines by 8-14 months versus new submissions. |
| Salon Distribution Exclusivity | Damansara distributor partnerships lock out competitors from Malaysia's 35,000-practitioner professional channel. |
| Sulfate-Free Formulation Pivot | Plant-derived surfactant R&D aligns with Muslim consumer preferences and NPRA tightening trajectories. |
| East Malaysia Retail Expansion | Sabah and Sarawak first-mover positioning captures sachet-to-bottle upgrade demand before organized trade saturation. |
| E-Commerce Subscription Models | Shopee auto-replenishment algorithms reduce customer acquisition costs in Greater Kuala Lumpur urban corridors. |
Study Parameters
Document review covered NPRA halal certification databases, Ministry of Health cosmetic notification registries, and ASEAN Cosmetic Directive harmonization protocols, complemented by interviews with brand managers at multinational FMCG conglomerates, category buyers at hypermarket chains, Shah Alam plant operations directors, and Damansara salon supply distributors. Secondary validation drew from customs trade data, retail audit disclosures, and surfactant procurement records. Bottom-up volume builds across product type and end-user segments were triangulated against top-down market sizing.
Segment-level projections across product type, end user, packaging format, and distribution channel dimensions were generated through elasticity-adjusted extrapolation over the projection horizon. CAGRs were derived from regression analysis of historical volume trajectories against NPRA regulatory inflection points and salon workforce expansion rates. Palm oil derivative pricing indices and Shopee platform transaction velocity served as industry-specific forecast inputs.
Inputs from NPRA certification timelines and salon distributor inventory records were available through the study window; gaps in real-time East Malaysian retail scan data introduce uncertainty bands around Sabah and Sarawak penetration assumptions. Forecasts reflect documented assumptions regarding halal chemist talent availability and preservative regulatory trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hair Care
Germany Hair Care Market
Hair Care
Rice Water Shampoo Market
Hair Care
Plant-Based Hair Dye Market
Hair Care
Hair Extension Market
Hair Care
South Africa Cosmetics and Personal Care Products Market
Hair Care
Mexico Hair Care Market
Hair Care
Asia Pacific Hair Care Market
Hair Care
Hair Care Appliances Market
Hair Care
United States Hair Care Market
Hair Care
Latin America Hair Care Market
Hair Care
China Hair Care Products Market
Hair Care
Hair Oil Market
Hair Care
Asia-Pacific Shampoo Market
Hair Care
Hair Edge Tamer Market
Hair Care
Global Professional Hair Care Market
Hair Care
Hair Mask Market