
 Wearable Gaming Technology Market | 2026-2036
Wearable Gaming Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable Gaming Technology Market Outlook
Cloud gaming subscription services is expanding the addressable base beyond hardware buyers toward recurring revenue pools. Sony Corporation leverages its PlayStation ecosystem to anchor software-hardware integration across living-room and portable formats. Samsung Electronics competes through display technology leadership in VR headset panels. Apple Inc. differentiates via proprietary silicon and closed-loop biometric integration in its wearable lineup.
Wearable gaming technology encompasses body-worn electronic devices engineered for interactive entertainment, typically integrating inertial measurement units, haptic feedback actuators, and sub-20ms motion-to-photon latency specifications to eliminate simulator sickness in head-mounted systems. VR headsets command the dominant hardware margin pool due to optical stack complexity and semiconductor intensity, while gesture recognition technology is displacing handheld controllers in fitness-oriented gaming applications. Biometric sensors represent the fastest-growing technology layer as heart-rate variability and galvanic skin response data enable adaptive difficulty algorithms.
The FCC in the United States governs radio-frequency emissions for wireless wearables, while CE marking under the EU Radio Equipment Directive mandates electromagnetic compatibility and safety testing for European market access. China's MIIT enforces GB standards for wireless transmission power that shape hardware design constraints for manufacturers targeting domestic distribution. Stakeholders must monitor evolving electromagnetic exposure limits across jurisdictions to preempt certification delays and inventory lockups.
Market Dynamics
Cloud gaming subscription services are restructuring revenue models away from hardware-centric sales toward recurring software access, while Shenzhen's manufacturing concentration and the EU AI Act's biometric compliance mandates simultaneously reshape supply and regulatory trajectories.
Growth Catalysts
- CE marking under EU Radio Equipment Directive:Standardized electromagnetic compatibility testing reduces fragmentation across European national markets, streamlining multi-country launch timelines for hardware manufacturers.
- Galvanic skin response sensors:Adaptive difficulty algorithms using biometric inputs extend session duration and retention metrics in fitness-oriented gaming verticals.
- Shenzhen hardware ecosystem:Vertical integration of MEMS foundries, optical module suppliers, and assembly houses compresses prototyping cycles and unit economics for VR headset production.
Market Restraints
- Optical stack input concentration:Premium VR displays depend on Korean and Japanese OLED microdisplay suppliers, creating single-source vulnerability for mid-tier manufacturers.
- Sub-20ms motion-to-photon latency requirement:Technical specification demands specialized signal processing silicon and display driver tuning that inflate bill-of-materials costs.
- GB standards wireless power limits:China's MIIT transmission caps constrain antenna design flexibility, forcing hardware variants for domestic versus export markets.
Strategic Opportunities
- Cloud gaming subscription bundling:Microsoft and Sony platform ecosystems enable hardware-agnostic revenue capture beyond initial device sales.
- Gesture recognition controller displacement:Computer vision and inertial fusion eliminate handheld peripherals in location-based entertainment venues.
- EU AI Act biometric data governance:Compliance infrastructure investments create defensive moats for early-adopter manufacturers against late entrants.
Industry Challenges
- Motion-to-photon latency engineering talent:Scarce expertise in real-time rendering pipeline optimization and predictive head tracking constrains product development velocity.
- FCC Part 15 certification timelines:Radio-frequency emission testing queue lengths delay US market entry by 8-14 weeks for wireless wearable launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable Gaming Technology Market |
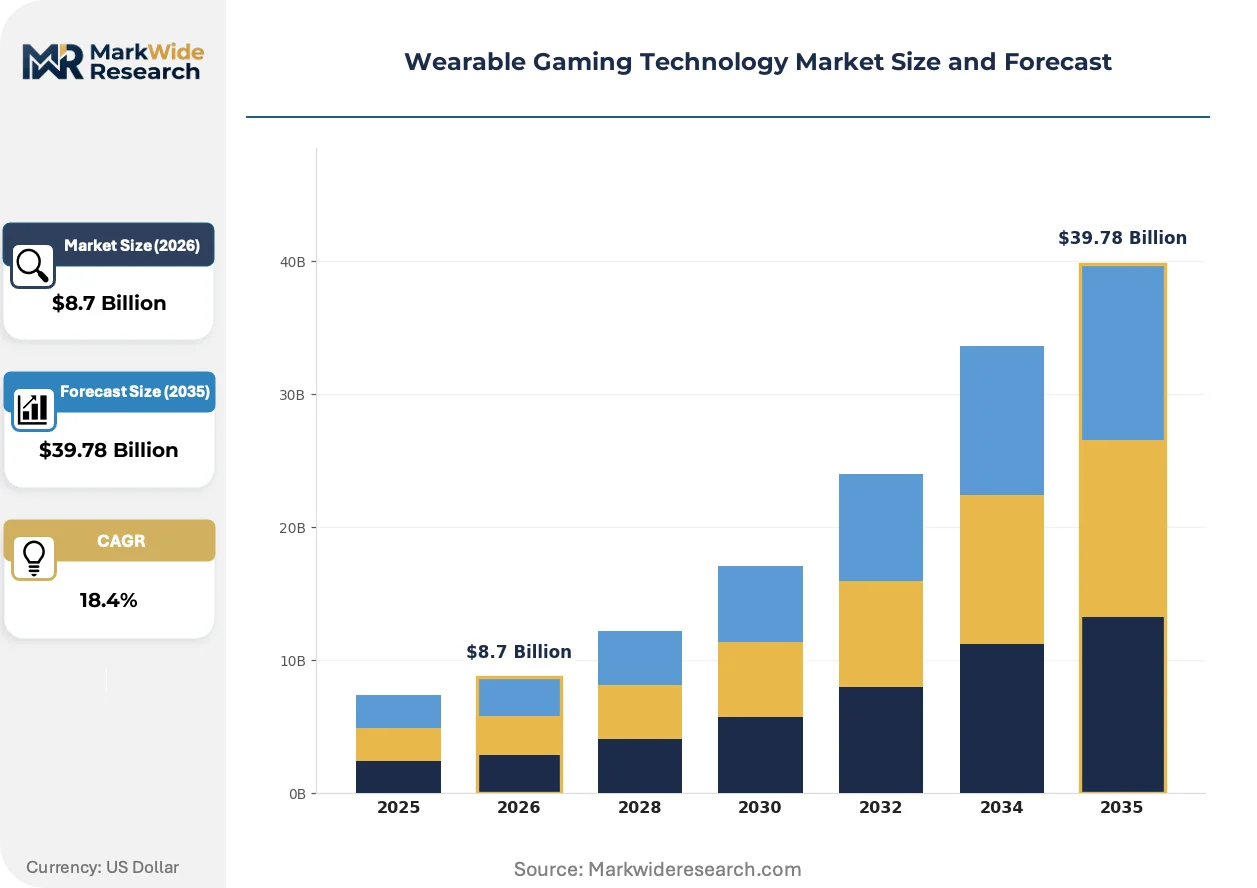
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartwatches, Fitness Trackers, VR Headsets, Gaming Gloves Technology: Augmented Reality, Virtual Reality, Gesture Recognition, Biometric Sensors End User: Casual Gamers, Competitive Gamers, Fitness Enthusiasts, Developers Distribution Channel: Online Retail, Electronics Stores, Specialty Gaming Shops, Direct Sales |
| Companies Covered | Apple Inc., Samsung Electronics, Microsoft Corporation, Sony Corporation, HTC Corporation, Google Inc., Oculus VR, Razer Inc., Garmin Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable Gaming Technology Market Strategic Shifts
Three converging forces—silicon efficiency gains, biometric data governance frameworks, and cloud-native gaming infrastructure—are compressing hardware replacement cycles while elevating software and sensor monetization potential.
Haptic feedback actuators with localized vibration patterning are absorbing rendering pipeline complexity previously handled by visual systems alone. Competitive esports venues and rehabilitation clinics are adopting these interfaces at accelerated procurement cadences. The technology is absorbing portions of the sensory load that optical systems alone cannot address within thermal and power constraints.
The EU AI Act's risk classification framework for biometric inference systems is mandating algorithmic audit trails and human oversight protocols for heart-rate variability applications in gaming. Hardware manufacturers must now embed explainability features and data minimization logic at the firmware layer. European market entrants face 12-18 month compliance runway extensions versus jurisdictions without equivalent biometric governance.
Subscription bundling of cloud gaming libraries with hardware financing is displacing outright purchase patterns among younger demographic cohorts. Retail channel partners are ceding margin to platform operators who control software distribution and payment rails. This behavioral pivot concentrates most visibly in South Korean and US West Coast metropolitan markets where fiber infrastructure supports sub-25ms streaming latency.
Wearable Gaming Technology Market Segmentation
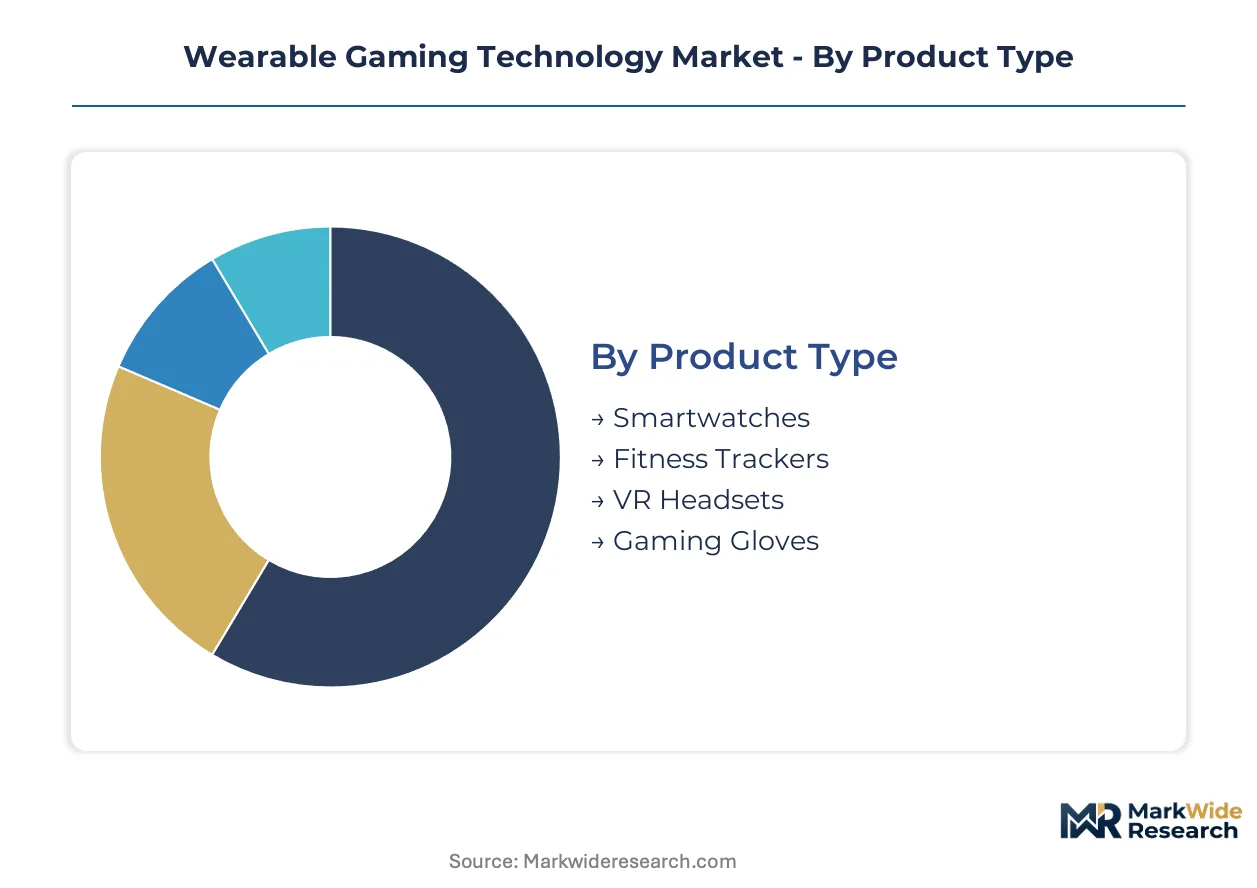
Wearable gaming technology fragments across hardware form factors, sensory modalities, user sophistication levels, and channel economics. Each segmentation axis carries distinct margin profiles and certification burdens that reshape go-to-market sequencing for manufacturers.
Product Type:
Standalone headsets operate as self-contained entertainment systems, while wrist-worn and hand-worn devices embed within broader ecosystem architectures.
- VR Headsets:Optical stack complexity incorporating pancake lenses, micro-OLED panels, and spatial audio drivers creates the highest hardware margin pool. Demand concentrates in South Korean internet cafes and US West Coast metropolitan fiber corridors where sub-25ms streaming latency enables cloud-native session models.
- Smartwatches:Proprietary silicon integration with closed-loop biometric feedback loops distinguishes premium tier offerings. Procurement is shifting toward health-gaming hybrid applications in European rehabilitation clinics subject to EU AI Act biometric governance protocols.
- Fitness Trackers:Galvanic skin response and heart-rate variability sensors enable adaptive difficulty algorithms in exergaming verticals.
- Gaming Gloves:Haptic feedback actuators with localized vibration patterning absorb rendering complexity previously handled by visual systems alone.
Volume placements concentrate in VR Headsets; the faster expansion belongs to Smartwatches.
Technology:
Cost tier stratification separates premium immersive stacks from accessible motion-capture alternatives.
- Biometric Sensors:Heart-rate variability and galvanic skin response data streams feed adaptive difficulty engines. Demand is accelerating in China's Shenzhen hardware ecosystem where MEMS foundry integration compresses unit economics for fitness-gaming hybrids.
- Virtual Reality:Sub-20ms motion-to-photon latency specifications demand specialized signal processing silicon and display driver tuning. FCC Part 15 certification timelines delay US market entry by 8-14 weeks for wireless implementations.
- Augmented Reality:Optical waveguide transparency and field-of-view tradeoffs constrain battery thermal budgets.
- Gesture Recognition:Computer vision and inertial fusion eliminate handheld peripherals in location-based entertainment venues.
Revenue concentration sits with Virtual Reality; Biometric Sensors are climbing the fastest.
End User:
Application intensity varies from casual session patterns to professional-grade performance optimization requirements.
- Competitive Gamers:Low-latency telemetry and predictive head tracking capabilities command premium pricing. Cloud gaming subscription bundling is restructuring procurement away from hardware ownership toward recurring access models in South Korean esports training facilities.
- Fitness Enthusiasts:Biometric feedback integration with session duration metrics drives retention in rehabilitation and wellness verticals. CE marking under EU Radio Equipment Directive streamlines multi-country launch timelines for European market access.
- Casual Gamers:Price sensitivity favors all-in-one headsets with simplified setup protocols.
- Developers:SDK access and debug telemetry requirements shape procurement toward open-platform hardware.
Installed base dominance rests with Casual Gamers; Competitive Gamers show the steepest expansion trajectory.
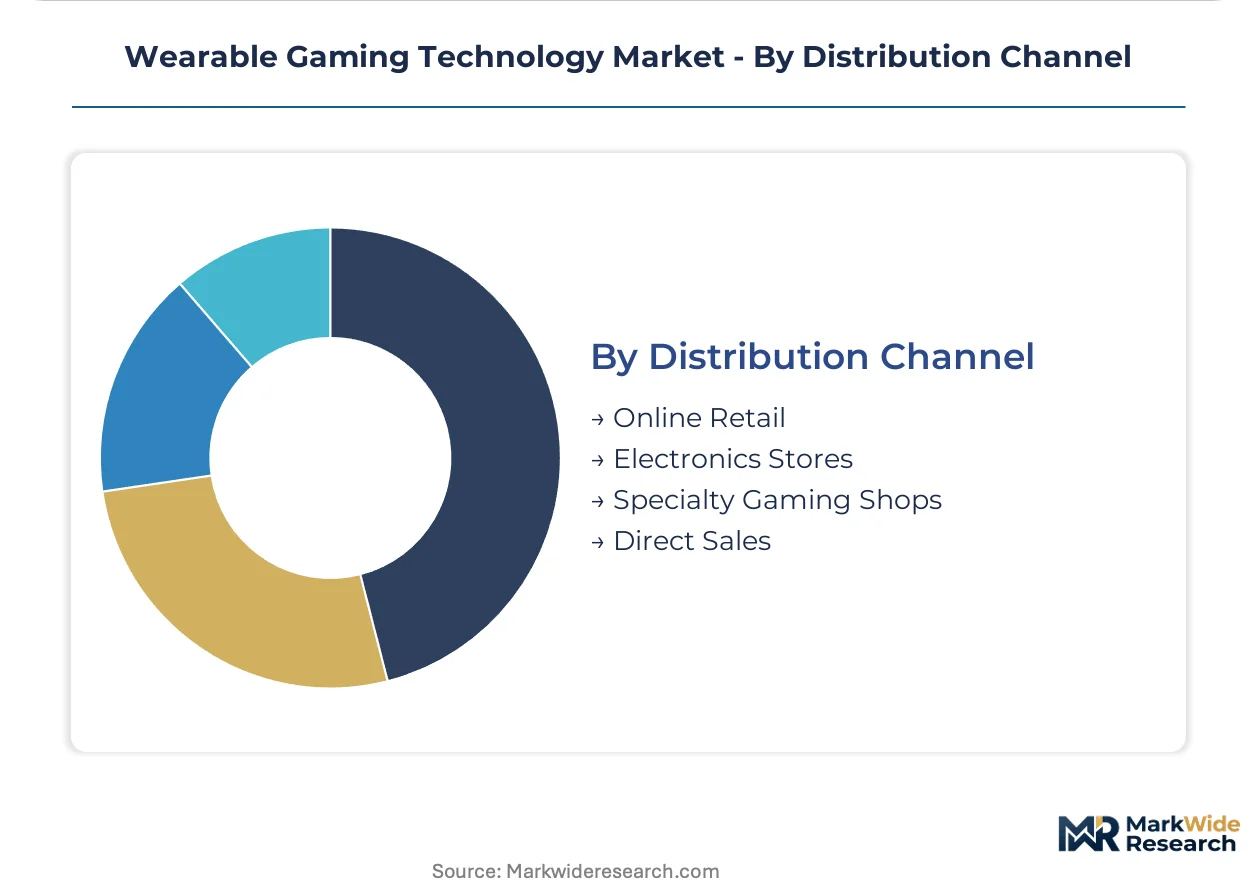
Distribution Channel:
Margin capture shifts from retail intermediaries toward platform operators controlling software distribution and payment rails.
- Online Retail:Subscription bundling of cloud gaming libraries with hardware financing displaces outright purchase patterns among younger demographic cohorts. Procurement concentrates in US West Coast and South Korean metropolitan markets where fiber infrastructure supports streaming latency requirements.
- Direct Sales:Proprietary ecosystem lock-in enables recurring revenue capture beyond initial device transactions. Apple's closed-loop integration and Sony's PlayStation ecosystem anchor software-hardware monetization across living-room and portable formats.
- Electronics Stores:Physical demonstration requirements sustain relevance for premium VR headset trials.
- Specialty Gaming Shops:Enthusiast community access and tournament sponsorship integration sustain niche positioning.
Transaction volume flows through Online Retail; Direct Sales gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of VR headset optical modules and MEMS sensors, while the United States and South Korea absorb the highest per-capita consumption of cloud-gaming-enabled wearables.
United States
Competitive esports venues and fiber-rich metropolitan corridors drive hardware procurement. FCC Part 15 certification governs radio-frequency emissions for wireless wearables. Seattle and Austin anchor software-hardware integration labs for cloud-native gaming ecosystems.
China
Shenzhen's vertical integration of MEMS foundries and optical suppliers compresses prototyping cycles for domestic and export markets. MIIT enforces GB standards on wireless transmission power that shape antenna design constraints. The Pearl River Delta cluster dominates micro-OLED panel assembly for mid-tier VR headsets.
South Korea
Internet cafe culture and 5G infrastructure penetration accelerate subscription-based wearable adoption. The Ministry of Science and ICT oversees electromagnetic compatibility certification. Seoul's Gangnam district hosts the densest concentration of location-based VR entertainment venues globally.
Germany
Industrial rehabilitation clinics and corporate wellness programs procure biometric-integrated smartwatches. CE marking under the EU Radio Equipment Directive mandates safety testing for European market access. Bavaria's Munich-Stuttgart corridor anchors automotive-to-gaming haptic technology transfer.
Japan
Arcade heritage and aging demographics create demand for therapeutic gaming wearables. METI coordinates standards alignment between domestic JIS requirements and international IEC frameworks. Tokyo's Akihabara district sustains specialty retail channels for enthusiast-grade VR peripherals.
Wearable Gaming Technology Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the wearable gaming stack. Foundry-dependent players face margin compression from OLED microdisplay supply constraints, while vertically integrated ecosystem operators capture recurring software revenue. Three archetypes dominate: closed-loop platform integrators, component-specialist suppliers, and cloud-native service bundlers. Capacity expansion in Shenzhen MEMS foundries and strategic patent licensing around motion-to-photon latency reduction constitute the primary competitive moves.
Among platform-integrated technology conglomerates, Apple Inc. and Sony Corporation exemplify closed-loop ecosystem strategies that bind hardware sales to proprietary content distribution. Samsung Electronics occupies a position bridging display component supply and finished device assembly. These three entities represent divergent responses to the cloud gaming transition—subscription anchoring, hardware-software fusion, and panel technology leverage respectively.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics |
| Microsoft Corporation |
| Sony Corporation |
| HTC Corporation |
| Google Inc. |
| Oculus VR |
| Razer Inc. |
| Garmin Ltd. |
| Others |
Value Chain & Pricing Dynamics
Captive MEMS foundry operations in Shenzhen anchor both component supply security and margin retention for VR headset manufacturers serving export markets. This backward integration into sensor production shields pricing power from Korean and Japanese OLED microdisplay supply bottlenecks while compressing unit economics for mid-tier hardware.
Pricing Analysis
Margin tightening in mid-tier VR headsets traces to Korean and Japanese OLED microdisplay supply constraints that inflate bill-of-materials costs. Three-tier pricing structure across premium, standard, and economy levels separates proprietary silicon-integrated ecosystems from white-label alternatives. Cost-down pressure on economy-tier wearables accelerates because Shenzhen assembly houses compete on volume throughput. Casual gamers exhibit highest price sensitivity; competitive esports venues accept premium telemetry capabilities.
Supply Chain Analysis
Freight cost volatility from Shenzhen to US West Coast distribution centers compresses margin buffers for hardware financing bundles. Component sourcing concentrates in China for MEMS sensors and optical modules, South Korea for OLED microdisplay panels, and Japan for precision optical coatings. Raw material dependencies span gallium nitride for RF power amplifiers, rare earth elements for magnet assemblies, and specialized polymers for pancake lens substrates. Single-source vulnerability in OLED microdisplay supply creates inventory risk. Distribution runs through platform-operator direct channels and online retail financing partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wearable gaming technology market functions as a vertical-integration race where control over MEMS sensor production and optical module assembly determines margin capture against cloud-native platform competitors.
For Market Incumbents: Deploy firmware-layer biometric explainability features to preempt EU AI Act compliance runway extensions against late-entrant challengers. Anchor proprietary silicon roadmaps to sub-20ms motion-to-photon latency specifications that generic chipsets cannot match. Deepen captive supply of haptic feedback actuators to absorb rendering complexity previously handled by visual systems alone. For New Entrants and Emerging Players: The premium-to-economy price-point gap in biometric-integrated smartwatches offers white-space entry for health-gaming hybrid applications. Target European rehabilitation clinics subject to EU AI Act governance protocols where incumbent compliance infrastructure remains underdeveloped. Pursue gesture recognition controller displacement in location-based entertainment venues as the most penetrable application vertical. For Investors and Strategic Acquirers: Exit pathways concentrate in platform-operator acquisition of MEMS foundry and optical module specialists. Long-term viability hinges on recurring software revenue capture beyond initial hardware transactions. Monitor cloud gaming subscription attach rates as the inflection signal for hardware-agnostic monetization maturity.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Foundry Capacity Expansion | Shenzhen vertical integration compresses prototyping cycles for VR headset sensor arrays. |
| EU AI Act Compliance Infrastructure | Firmware-layer audit trails create defensive moats against biometric data governance penalties. |
| Cloud Gaming Subscription Bundling | Platform-operator financing partnerships displace retail margin capture among younger demographics. |
| Gesture Recognition SDK Development | Computer vision pipelines eliminate handheld peripheral dependencies in fitness gaming verticals. |
| Optical Module Assembly Partnership | Korean and Japanese panel supplier alliances secure micro-OLED allocation for premium headset tiers. |
Study Parameters
SEC filings from hardware manufacturers, customs trade databases tracking MEMS sensor flows, and hyperscaler cloud gaming capex disclosures formed the secondary backbone. Primary interviews with VR hardware engineering leads, esports venue procurement managers, rehabilitation clinic biomedical directors, and FCC certification consultants combined with bottom-up and top-down triangulation across the analysis window.
Historical trendline analysis of unit shipments and average selling prices informed projection modeling across hardware form factors, sensory technology layers, end-user sophistication tiers, and distribution channel economics. CAGRs derived from segment-level growth rate reconciliation with macro technology adoption curves. Forecast inputs incorporated cloud gaming infrastructure latency improvements and biometric sensor MEMS foundry capacity expansion.
Underlying measurement precision varies by segment; VR headset optical stack cost data carries tighter precision than emerging gesture recognition application estimates. Forecasts reflect assumptions about FCC Part 15 certification timeline normalization and EU AI Act implementation consistency. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Technology
Smart Band Market
Wearable Technology
Kids GPS Trackers and Wearables Market
Wearable Technology
Android Smartwatch Market
Wearable Technology
Global Smart Watch Market
Wearable Technology
Wearable Technology and IoT Wearable Device Market
Wearable Technology
Global Smartwatch Battery Market
Wearable Technology
Wearable Technology Market
Wearable Technology
Global Smart Wearable Market
Wearable Technology
Wearable Gaming Devices Market
Wearable Technology
Bluetooth Wearable Scanner Market
Wearable Technology
Smart Pet Wearable Product Market
Wearable Technology
Wearable Electronics Market
Wearable Technology
Global Smart Ring Market
Wearable Technology
Wearable Communicator Market
Wearable Technology
Adult Smartwatch Market
Wearable Technology
Smart Bra Market