
 Global in-Store Analytics Market | 2026-2036
Global in-Store Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Global in-Store Analytics Market Foresight
The in-store analytics sector is consolidating around two distinct performance tiers. Premium deployments integrate real-time video analytics with POS systems and AI-driven demand forecasting, while commodity offerings deliver basic footfall counting and heat mapping. SAP SE leverages its enterprise ERP footprint to anchor complex multi-store rollouts. Zebra Technologies Corp. dominates ruggedized hardware endpoints that sustain edge computing workloads in high-traffic retail environments.
In-store analytics encompasses sensor networks, computer vision systems, and data integration platforms that capture, process, and visualize shopper behavior within physical retail environments, typically processing video feeds at 15-30 frames per second with sub-meter positional accuracy to enable real-time decision support. Customer Behavior Analytics and Traffic Pattern Analysis lead solution offerings as retailers prioritize conversion optimization over raw footfall metrics. Video Analytics and Wi-Fi Analytics compete as primary technology anchors, with Bluetooth Beacons gaining ground in boutique formats requiring precise micro-location engagement. Department Stores and Supermarkets occupy the largest customer type positions, though Fashion Boutiques generate disproportionate margin pools through high-frequency assortment turnover demands.
FCC guidelines on wireless spectrum usage shape Bluetooth Beacon and Wi-Fi sensor deployments across US retail chains, while GDPR and the EU AI Act impose strict consent and algorithmic transparency requirements that favor on-premise processing architectures over cloud-dependent alternatives. ISO standards for data security and privacy management provide baseline compliance frameworks that vendors must navigate for cross-border deployments. Stakeholders must monitor evolving biometric consent regulations and edge AI chip efficiency trajectories to determine build-versus-partner strategies for next-generation inference engines.
Market Dynamics
Edge AI inference is compressing decision latency from minutes to milliseconds, forcing retailers to choose between cloud-dependent architectures and on-premise processing stacks that satisfy tightening biometric consent frameworks.
Growth Catalysts
- EU AI Act compliance mandates:European retailers accelerate on-premise video analytics deployments to avoid algorithmic transparency penalties and cross-border data transfer restrictions.
- Specialty retail format expansion:Fashion boutiques and premium grocers deploy Wi-Fi tracking and Bluetooth beacon networks to optimize micro-location engagement and conversion funnel analysis.
- Computer vision chip efficiency:New edge AI processors enable 15-30 frame-per-second video analysis at sub-meter accuracy without cloud dependency, reducing bandwidth costs for high-traffic stores.
Market Restraints
- GDPR biometric consent friction:Strict European requirements for explicit shopper consent limit camera-based analytics deployment in public retail zones, favoring anonymized sensor alternatives.
- Edge hardware capex concentration:Ruggedized endpoints with embedded inference engines carry 3-5x upfront cost premiums versus cloud-tethered alternatives, slowing mid-market adoption.
- Wi-Fi spectrum congestion:FCC guidelines on 2.4GHz and 5GHz channel allocation restrict sensor density in dense urban retail clusters, degrading positional accuracy.
Strategic Opportunities
- India organized retail modernization:Reliance Retail and Tata Trent chains deploy footfall analytics across Tier-2 and Tier-3 cities where modern trade penetration remains below 10%.
- POS-integration convergence:Unified platforms combining real-time video analytics with transaction data enable aisle-level demand forecasting and dynamic inventory positioning.
- ISO 27701 privacy certification:Early compliance with international privacy management standards opens enterprise procurement channels with data-sensitive pharmacy and financial services retailers.
Industry Challenges
- Computer vision talent scarcity:Shortage of engineers skilled in edge optimization and low-light inference tuning delays rollout timelines for mid-size retail chains.
- Legacy POS integration complexity:Proprietary data formats from incumbent point-of-sale vendors require expensive middleware development for unified analytics dashboards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global in-Store Analytics Market |
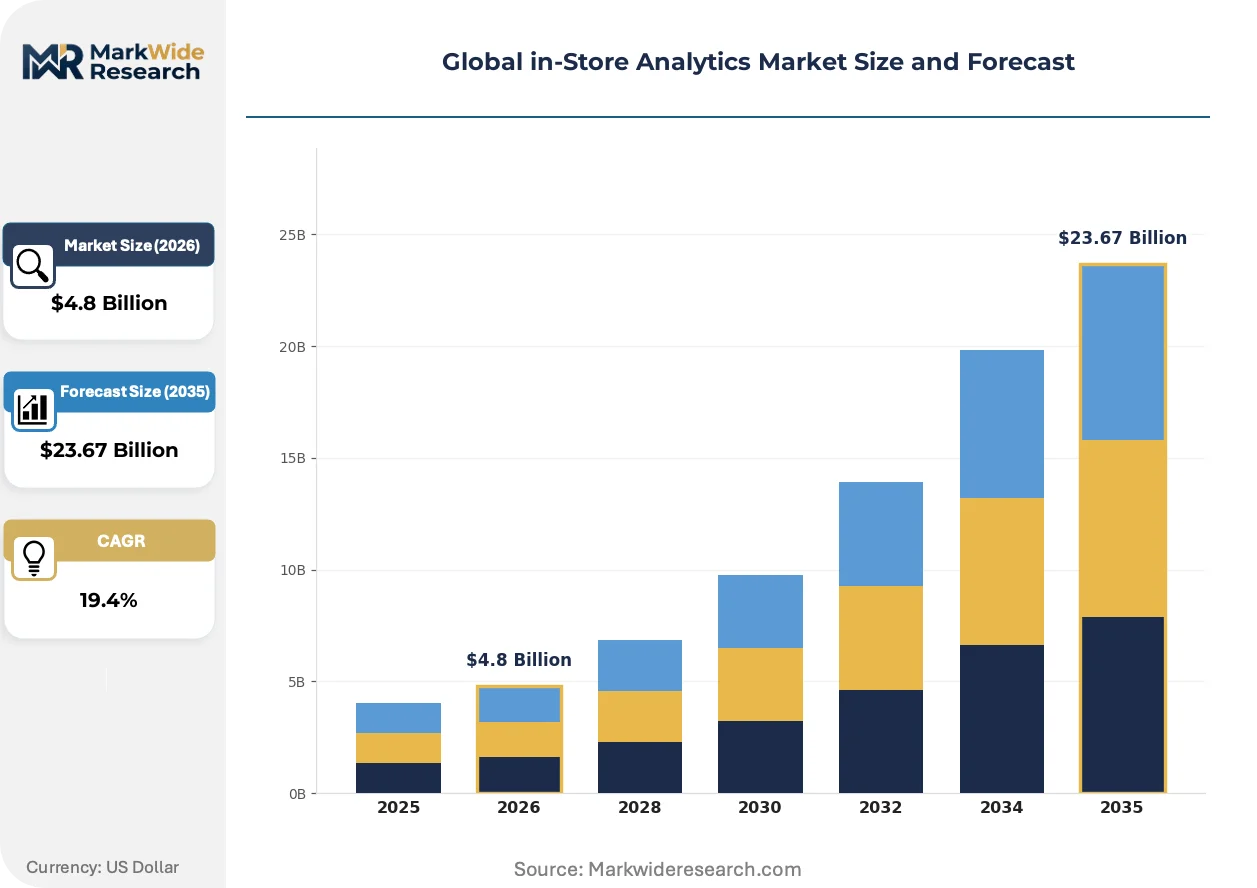
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $23.67 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Offering: Customer Behavior Analytics, Traffic Pattern Analysis, Sales Conversion Tracking, Dwell Time Measurement, Queue Management, Inventory Insights Technology: Video Analytics, Wi-Fi Analytics, Bluetooth Beacons, RFID Sensors, Infrared Sensors, Point of Sale Integration Application: Footfall Analysis, Shopper Path Optimization, Shelf Engagement, Personalized Promotions, Demand Forecasting, Visual Merchandising Customer Type: Department Stores, Specialty Shops, Supermarkets, Convenience Stores, Outlet Centers, Fashion Boutiques |
| Companies Covered | RetailNext, Inc., Capillary Technologies India Limited, SAP SE, Honeywell International, Inc., Microsoft Corporation, Sensormatic Solutions, Trax Retail, Zebra Technologies Corp., LTIMindtree Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global in-Store Analytics Market Shifts & Advancements
Retail analytics is pivoting from retrospective reporting to real-time intervention systems, with sensor fusion and privacy-preserving architectures commanding R&D priority.
On-premise edge inference is overtaking cloud-dependent video processing as the dominant architecture for computer vision deployments. High-traffic supermarket chains in Germany and France now mandate local processing to satisfy CNIL and BfDI guidance on facial recognition restrictions. This shift compresses vendor margins on recurring SaaS revenue while expanding hardware and systems integration contract values.
GDPR Article 35 data protection impact assessments and EU AI Act risk classification rules are forcing algorithmic documentation standards on retail analytics vendors. Systems processing biometric data now require technical file submissions demonstrating proportionality and accuracy thresholds. French and Italian retailers have paused camera-based emotion detection pilots pending national regulator clarifications.
Buyer preference for outcome-based engagement models is displacing traditional per-sensor licensing in enterprise retail accounts. Walmart and Target-style chains now negotiate conversion-rate improvement guarantees rather than paying for raw data feeds. This compression of the commercial model is visible most acutely in North American department store renewals, where vendors absorb hardware costs in exchange for performance-tied fees.
Global in-Store Analytics Market Segmentation
Retailers select in-store analytics components based on data sensitivity requirements, integration complexity with legacy infrastructure, and the specific shopper journey friction points each format must resolve. Segmentation choices directly determine whether deployments satisfy GDPR biometric consent rules or fall under lighter sensor-based regulatory treatment.
Solution Offering:
ISO 27701 privacy certification requirements apply differentially across solution types, with biometric-adjacent offerings demanding extensive documentation while anonymized sensor analytics face lighter compliance burdens.
- Customer Behavior Analytics:Systems correlate dwell patterns with transaction data to identify conversion blockers. Department stores in Germany and France prioritize these tools for aisle-level optimization under CNIL guidance limiting facial recognition use. GDPR Article 35 data protection impact assessments are mandatory when biometric inference is involved.
- Traffic Pattern Analysis:Heat mapping and flow visualization tools process 15-30 frame-per-second video feeds at sub-meter accuracy. High-traffic supermarket chains deploy these for queue prediction and staffing optimization, with edge processing architectures satisfying BfDI restrictions on cloud data transfers.
- Sales Conversion Tracking:POS-integrated platforms linking behavioral signals to transaction completion. Fashion boutiques leverage these for fitting-room-to-purchase funnel analysis.
- Dwell Time Measurement:Shelf-zone timing analytics using infrared or beacon proximity detection. Convenience stores deploy these for promotional effectiveness verification.
- Queue Management:Real-time line-length monitoring triggering staff reallocation alerts. Outlet centers use these during peak traffic windows.
- Inventory Insights:Shelf-stock visibility through computer vision or RFID correlation. Specialty grocers prioritize these for fresh-category rotation optimization.
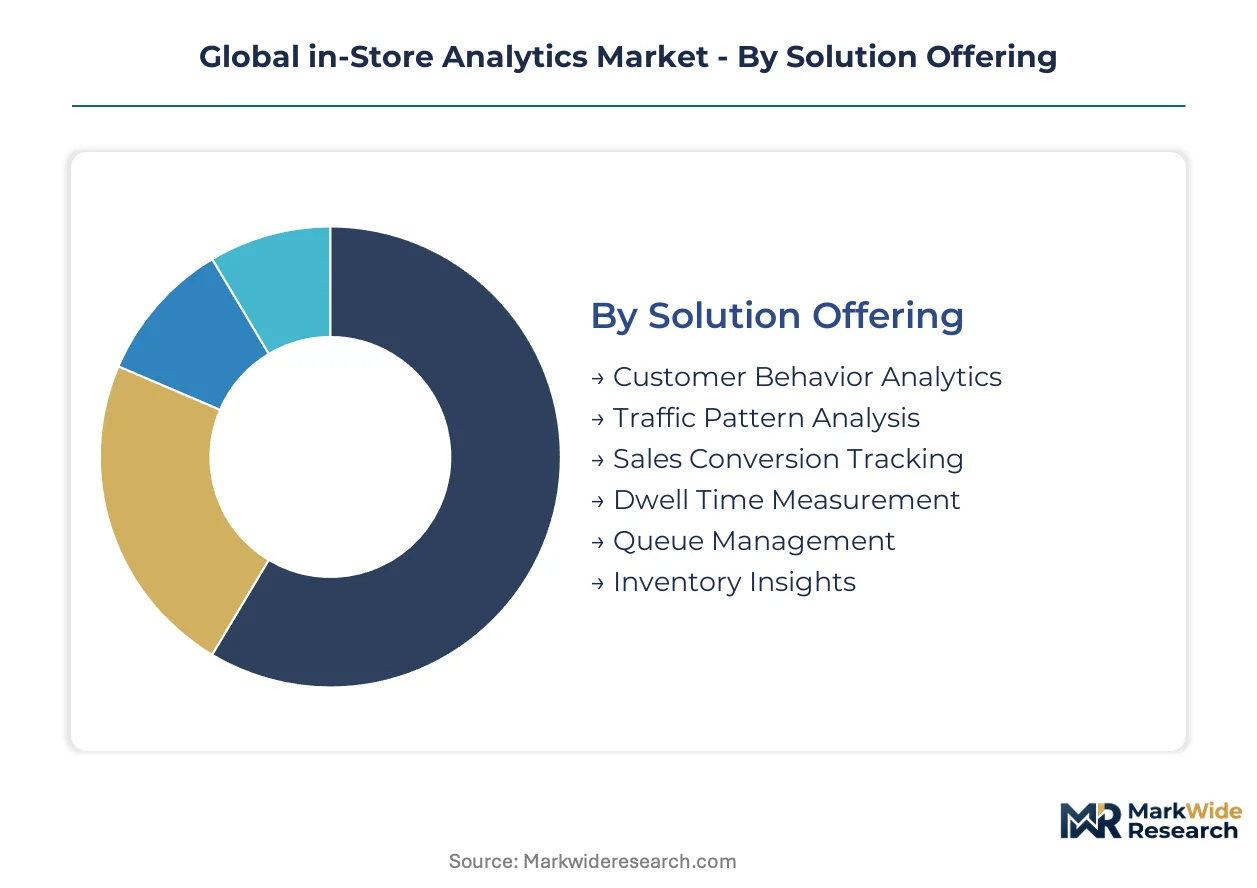
Traffic Pattern Analysis sits at the top of the volume ranking, with Customer Behavior Analytics climbing the fastest as retailers shift from footfall counting to conversion-focused investment.
Technology:
Hardware selection determines whether retailers absorb 3-5x upfront cost premiums for ruggedized edge endpoints or accept cloud-dependency risks under tightening biometric consent frameworks.
- Video Analytics:Computer vision systems processing real-time feeds for demographic inference and emotion detection. EU AI Act risk classification rules now mandate technical file submissions for these deployments, with French and Italian retailers pausing emotion detection pilots pending national regulator clarifications.
- Wi-Fi Analytics:Probe request tracking for device-level journey mapping without camera dependency. FCC guidelines on 2.4GHz and 5GHz channel allocation restrict sensor density in dense urban US retail clusters.
- Bluetooth Beacons:Micro-location engagement triggers for personalized promotions. Fashion boutiques favor these for precise in-aisle messaging with minimal privacy friction.
- RFID Sensors:Item-level inventory tracking integrated with loss prevention systems. Department stores deploy these for high-value merchandise zones.
- Infrared Sensors:Anonymous thermal detection for occupancy and flow measurement. Convenience stores prefer these for low-cost footfall verification.
- Point of Sale Integration:Transaction-behavior data fusion enabling aisle-level demand forecasting. Enterprise retailers negotiate outcome-based contracts tied to conversion improvement guarantees.
Video Analytics commands the largest installed base, with Bluetooth Beacons expanding most quickly in boutique formats seeking precise engagement without biometric consent complexity.
Application:
Application prioritization reflects whether retailers optimize for immediate operational intervention or longer-range strategic planning, with real-time systems commanding premium pricing.
- Footfall Analysis:Entry-counting and occupancy monitoring forming the baseline analytics layer. Tier-2 and Tier-3 cities in India see rapid deployment as Reliance Retail and Tata Trent modernize organized trade penetration.
- Shopper Path Optimization:Route analysis for floor layout and category adjacency refinement. Supermarkets leverage these for high-margin zone placement.
- Shelf Engagement:Interaction detection with specific product displays. Specialty retailers deploy these for promotional effectiveness measurement.
- Personalized Promotions:Real-time offer delivery based on location and behavioral triggers. Fashion boutiques generate disproportionate margin pools through high-frequency assortment turnover demands.
- Demand Forecasting:Predictive inventory positioning using behavioral-transaction fusion. Enterprise chains absorb hardware costs in exchange for performance-tied fees.
- Visual Merchandising:Display effectiveness verification through engagement correlation. Department stores prioritize these for seasonal campaign optimization.
Footfall Analysis retains the highest deployment volume, with Demand Forecasting gaining share fastest as POS-integration convergence accelerates.
Customer Type:
Customer type determines solution complexity thresholds, with enterprise chains demanding unified multi-store platforms while independent operators prioritize standalone, rapid-deploy configurations.
- Department Stores:Multi-floor, high-SKU environments requiring integrated video, Wi-Fi, and POS fusion. These accounts drive enterprise-scale vendor consolidation around SAP SE and Zebra Technologies Corp. footprints.
- Specialty Shops:Focused-format retailers deploying Wi-Fi tracking and Bluetooth beacon networks for micro-location engagement. These segments show strongest appetite for outcome-based commercial models.
- Supermarkets:High-traffic, low-margin operations prioritizing queue management and inventory insights. Edge AI inference adoption is most advanced here due to real-time operational pressure.
- Convenience Stores:Limited footprint operators favoring low-cost infrared and beacon solutions for basic occupancy and flow data.
- Outlet Centers:Open-format properties requiring weather-resistant hardware and cross-tenant journey analytics.
- Fashion Boutiques:Premium-format retailers with highest per-square-meter analytics spend, prioritizing personalized promotions and shelf engagement for rapid assortment turnover.
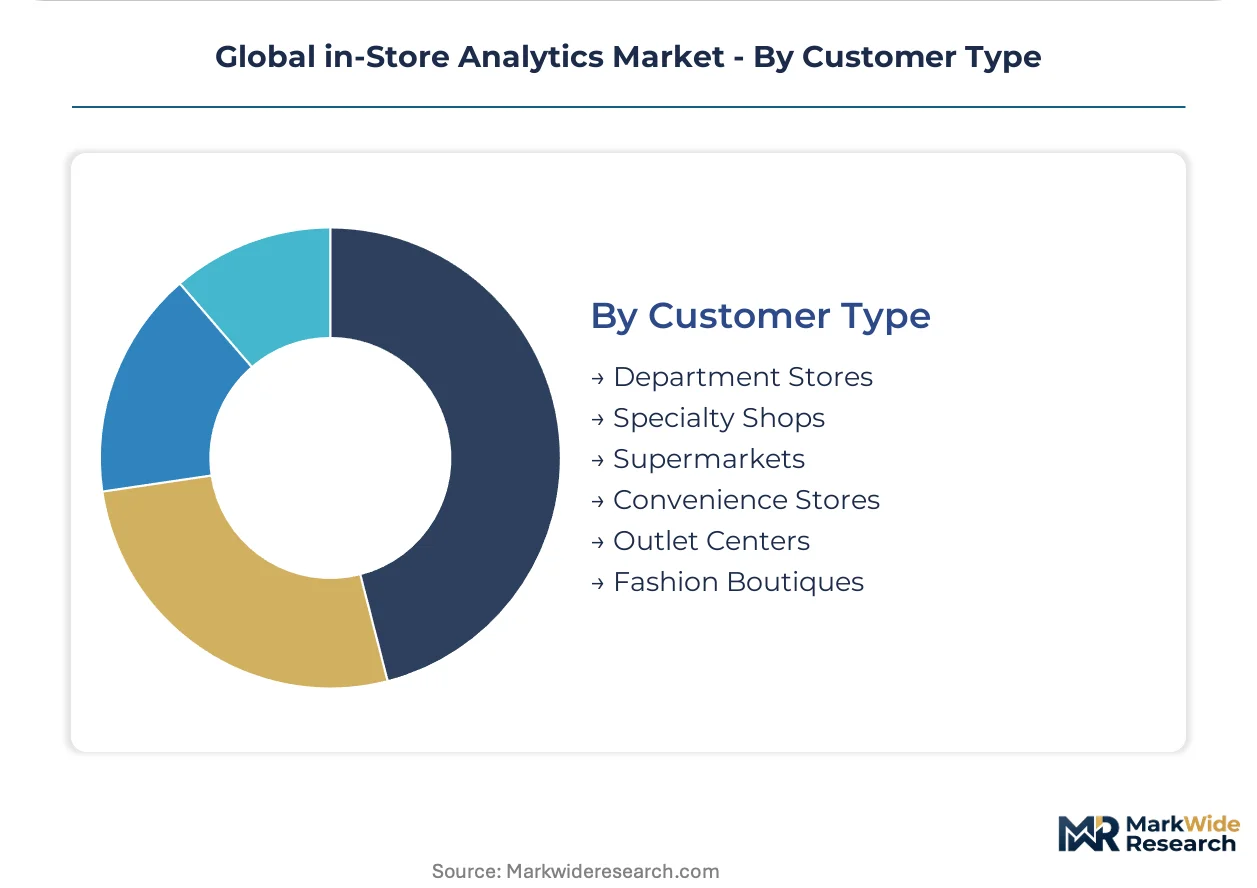
Department Stores anchor current revenue concentration, with Fashion Boutiques showing the steepest expansion trajectory as premium retail formats multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineers specializing in edge AI optimization concentrate in Germany's industrial corridors and India's technology hubs, anchoring solution development for privacy-preserving retail analytics.
United States
Walmart, Target, and Kroger chains drive enterprise-scale deployments across suburban retail corridors. FCC guidelines on 2.4GHz and 5GHz spectrum allocation shape Wi-Fi sensor density in dense urban clusters like New York and Chicago. Silicon Valley hardware startups partner with Midwestern supermarket chains to test sub-meter accuracy video analytics.
Germany
High-traffic supermarket chains in Bavaria and North Rhine-Westphalia mandate local edge processing to satisfy BfDI restrictions on cloud data transfers. The EU AI Act risk classification rules force algorithmic documentation standards on vendors deploying biometric-adjacent systems. Berlin-based retail technology consultancies advise French and Italian retailers on CNIL-compliant camera deployments.
France
Department stores in Île-de-France prioritize Customer Behavior Analytics for aisle-level optimization under CNIL guidance limiting facial recognition use. GDPR Article 35 data protection impact assessments are mandatory when biometric inference is involved. Retailers in Lyon and Marseille have paused camera-based emotion detection pilots pending national regulator clarifications.
India
Reliance Retail and Tata Trent chains deploy footfall analytics across Tier-2 and Tier-3 cities where modern trade penetration remains below 10 percent. BIS standards for electronics manufacturing shape hardware procurement specifications for domestic deployments. Bangalore-based systems integrators build middleware connecting legacy POS infrastructure to unified analytics dashboards.
United Kingdom
Fashion boutiques in London generate disproportionate margin pools through high-frequency assortment turnover demands and precise micro-location engagement. The Information Commissioner's Office guidance on biometric data processing influences camera-based analytics deployment decisions. Manchester and Birmingham retail parks test Bluetooth beacon networks for personalized promotion delivery.
Global in-Store Analytics Market Competitive Landscape
Top-tier vendors anchor enterprise ERP-integrated deployments, while mid-tier specialists focus on standalone rapid-configure solutions for independent operators. The vendor base stratifies across three functional tiers: full-stack platform providers, hardware-centric edge computing specialists, and regional systems integrators. Dominant competitive moves include outcome-based commercial model adoption and privacy certification acceleration to unlock enterprise procurement channels.
Within the enterprise platform tier, SAP SE and Microsoft Corporation exemplify the ERP-anchored archetype, leveraging existing customer footprints to drive multi-store analytics rollouts. Zebra Technologies Corp. occupies a position among hardware-centric specialists, with its ruggedized endpoint focus aligning with high-traffic retail environment requirements. Sensormatic Solutions and RetailNext, Inc. represent the dedicated retail analytics pure-play segment, concentrating on sector-specific workflow integration.
| Leading Market Players |
|---|
| RetailNext, Inc. |
| Capillary Technologies India Limited |
| SAP SE |
| Honeywell International, Inc. |
| Microsoft Corporation |
| Sensormatic Solutions |
| Trax Retail |
| Zebra Technologies Corp. |
| LTIMindtree Limited |
| Others |
Supply & Pricing Matrix
Captive integration into edge AI chip fabrication anchors supply positioning for vendors serving GDPR-sensitive European deployments. This vertical control over inference hardware production enables premium pricing for on-premise processing stacks while cloud-dependent alternatives face margin compression from bandwidth cost volatility.
Pricing Analysis
Bundled hardware-plus-software contracts dominate enterprise retail accounts, while unbundled per-sensor licensing persists among independent operators. Three-tier pricing structure across premium, standard, and economy levels separates full-stack ERP-integrated platforms from standalone rapid-configure solutions. Cost compression in the mid-market tier is intensifying because outcome-based commercial models now tie vendor compensation to conversion-rate guarantees. Independent fashion boutiques exhibit highest price sensitivity, whereas Walmart-style enterprise chains absorb upfront hardware capex in exchange for performance-tied fee structures.
Supply Chain Analysis
Regional distribution centers in Taiwan, South Korea, and Germany anchor component warehousing for edge AI processor and ruggedized camera module procurement. Manufacturing draws from specialized semiconductor foundries, precision optics suppliers, and industrial enclosure fabricators. Single-source vulnerability concentrates around advanced node GPU supply for computer vision inference engines. Distribution runs through systems integrator networks that configure on-premise processing stacks for CNIL-compliant French and BfDI-compliant German supermarket chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU AI Act algorithmic transparency mandates and GDPR biometric consent frameworks accelerate demand for privacy-preserving on-premise architectures.
For Market Incumbents: To counter margin erosion from outcome-based commercial models, deepen backward integration into edge AI chip design and expand ISO 27701 certification coverage to unlock pharmacy and financial services procurement channels. SAP SE and Zebra Technologies Corp. should prioritize multi-store ERP-integrated rollout capacity over standalone sensor sales.
For New Entrants and Emerging Players: Launch via regional systems integrator partnerships targeting Tier-2 and Tier-3 Indian cities where Reliance Retail and Tata Trent modernization drives footfall analytics demand with minimal incumbent saturation. Fashion boutiques in London and Paris present the most penetrable segment given their appetite for Bluetooth beacon micro-location engagement without biometric consent complexity.
For Investors and Strategic Acquirers: Roll-up economics work for dedicated retail analytics pure-plays because enterprise procurement consolidation favors sector-specific workflow integration over generalist platform vendors. Long-term viability hinges on privacy certification moats and POS-integration convergence capabilities. Watch for edge AI chip efficiency inflections that compress cloud-versus-on-premise total cost of ownership gaps.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 27701 Privacy Certification | Unlocks enterprise procurement channels with data-sensitive pharmacy retailers under GDPR Article 35. |
| POS-Integration Convergence | Enables aisle-level demand forecasting for Walmart-style chains through transaction-behavior data fusion. |
| Edge AI Processor Development | Reduces bandwidth costs for German supermarket chains under BfDI cloud transfer restrictions. |
| Outcome-Based Commercial Models | Aligns vendor compensation with conversion improvement guarantees in North American department store renewals. |
| Regional Systems Integrator Partnership | Accelerates deployment across Tier-2 Indian cities where Bangalore-based middleware builders connect legacy POS infrastructure. |
Research Methodology
Multiple input streams — executive interviews with retail technology vendors, procurement discussions with supermarket chain CIOs, and regulatory filings with CNIL and BfDI — were reconciled against secondary validation from SEC filings, hyperscaler capex disclosures, and customs records for edge hardware imports. Primary fieldwork captured CTO perspectives at department store headquarters and integration specialist viewpoints at Berlin-based retail technology consultancies. Bottom-up sensor deployment counts and top-down ERP-integrated platform revenue estimates underwent cross-triangulation.
Data-stream reconciliation anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include solution offering type, technology anchor, application priority, and customer format scale. CAGRs were derived from fitted growth curves applied to vendor-reported deployment trajectories. Industry-specific forecast inputs incorporated FCC spectrum allocation guidance shaping Wi-Fi sensor density and EU AI Act risk classification timelines affecting biometric-adjacent system rollouts.
Forecast precision tightens around the base case; tail outcomes carry wider variance under biometric consent regulation tightening or edge AI chip supply disruption scenarios. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Asia-Pacific HR Analytics Market
Analytics
Global Healthcare Cloud Based Analytics Market
Analytics
Lead Intelligence Software Market
Analytics
Imagery Analytics Market
Analytics
Global Subscription Analytics Software Market
Analytics
Europe HR Analytics Market
Analytics
Predictive Analytics Market
Analytics
France Contact Center Analytics Market
Analytics
Global Web Analytics Software Market
Analytics
Weather Data Services Market
Analytics
Asia-Pacific Crowd Analytics Market
Analytics
UAE Geospatial Analytics Market
Analytics
Sentiment Analytics Market
Analytics
Global Sentiment Analytics Software Market
Analytics
Automated Analytics Market
Analytics
Japan Geospatial Analytics Market