
 Global Toys Market | 2026-2036
Global Toys Market Size, Share, and Industry Trends Forecast 2026-2036
Global Toys Market Outlook
Preschool educational demand is hardening as parents and institutional buyers prioritize STEM-aligned play systems over passive entertainment. Mattel sustains its position through deep catalog breadth across dolls and infant categories, while The LEGO Group anchors premium construction play with captive manufacturing discipline. Hasbro competes across licensed action figures and board games, leveraging entertainment IP tie-ins that extend retail shelf life.
Toys comprise physical play objects manufactured from plastic polymers, wood composites, fabric textiles, or metal alloys, typically designed with dimensional tolerances under 0.5 millimeters for safety-critical small parts, serving developmental, recreational, and educational purposes for children from infancy through adolescence. Building Sets command the highest margin pools due to complexity premiums and repeat-purchase expansion sets, while Online Retail captures the fastest-growing transaction volume as direct-to-consumer platforms displace traditional department store foot traffic. Plastic remains the dominant Material by volume, though Wood segments gain traction among sustainability-positioned buyers in European and North American markets.
The US Consumer Product Safety Commission enforces ASTM F963 toy safety standards that govern mechanical properties, flammability, and chemical content, while the EU Toy Safety Directive and REACH regulate phthalate restrictions and migration limits for heavy elements in imported products. China's SAMR implements GB standards for domestic toy circulation, creating a three-jurisdiction compliance burden for multinational suppliers. Stakeholders must monitor evolving chemical substance restrictions and digital privacy requirements for connected toys as regulatory fragmentation intensifies certification costs.
Market Dynamics
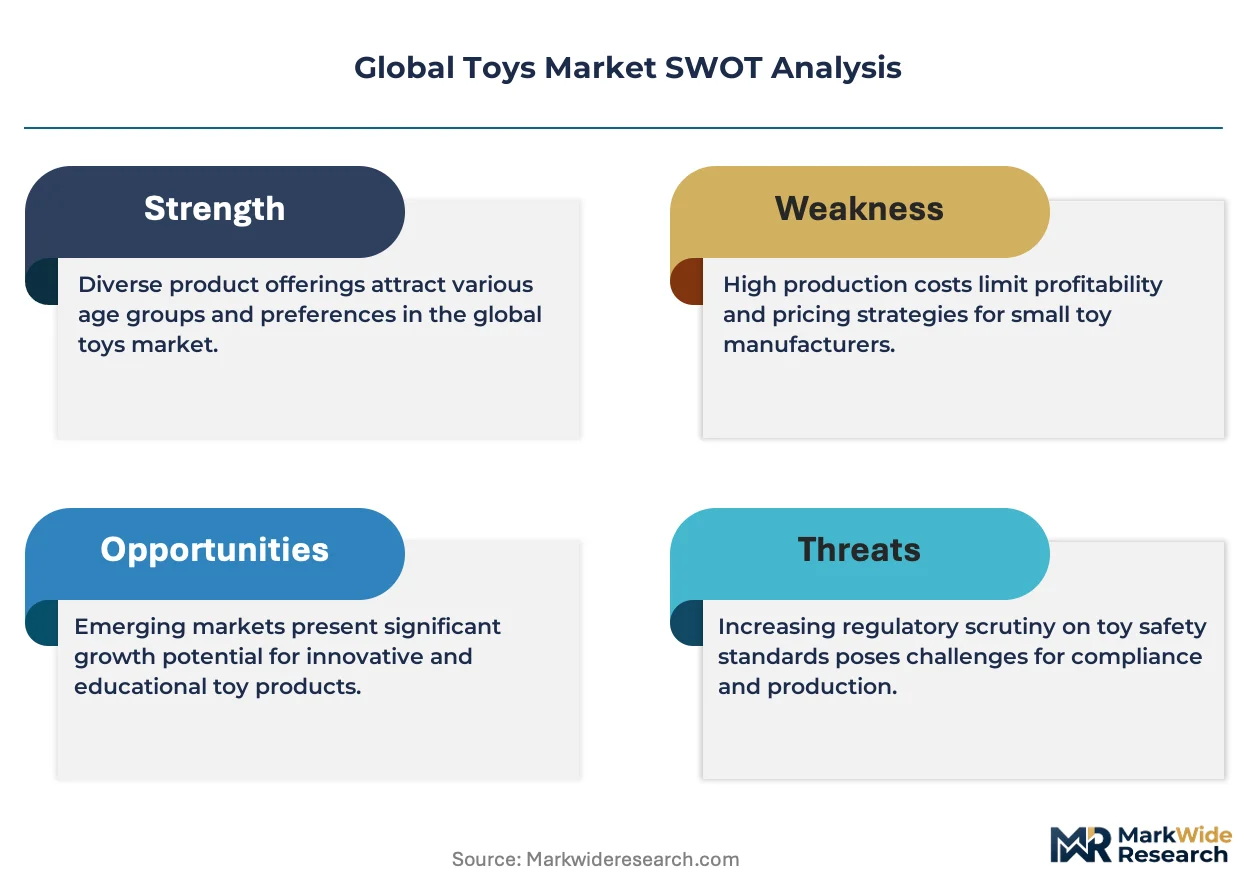
STEM-aligned developmental play systems are hardening parental purchasing criteria, compressing shelf space for passive entertainment formats while elevating compliance burdens across multi-jurisdiction supply chains.
Growth Catalysts
- EU REACH chemical restrictions:Phased phthalate bans and heavy-element migration limits are accelerating material substitution investments, opening premium positioning for compliant suppliers.
- Preschool institutional procurement:Early childhood education centers in OECD markets are formalizing toy acquisition standards around developmental milestones.
- Connected toy architectures:Embedded sensors and companion apps are extending product lifecycles through subscription content and parental analytics dashboards.
Market Restraints
- Petrochemical input volatility:ABS and polypropylene resin prices fluctuate with crude oil benchmarks, compressing margin predictability for molded plastic categories.
- Guangdong production concentration:Overreliance on the Pearl River Delta cluster exposes supply continuity to regional energy rationing and labor mobility constraints.
- Digital-native entertainment substitution:Tablet-based gaming and streaming platforms capture discretionary spending hours from traditional physical play.
Strategic Opportunities
- India's organized retail expansion:Modern trade formats in tier-two cities create first-mover positioning for quality-assured import brands.
- EU Green Deal circularity mandates:Ecodesign requirements for recyclable packaging and take-back schemes favor reusable construction systems.
- Direct-to-consumer platform integration:Proprietary e-commerce channels bypass wholesale markups while capturing first-party behavioral data.
Industry Challenges
- Cross-jurisdiction certification timelines:Simultaneous ASTM F963, EN 71, and GB 6675 testing protocols extend product launch windows by eight to fourteen months.
- Licensed IP negotiation complexity:Entertainment franchise agreements require minimum guarantee structures that strain working capital for mid-scale manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Toys Market |
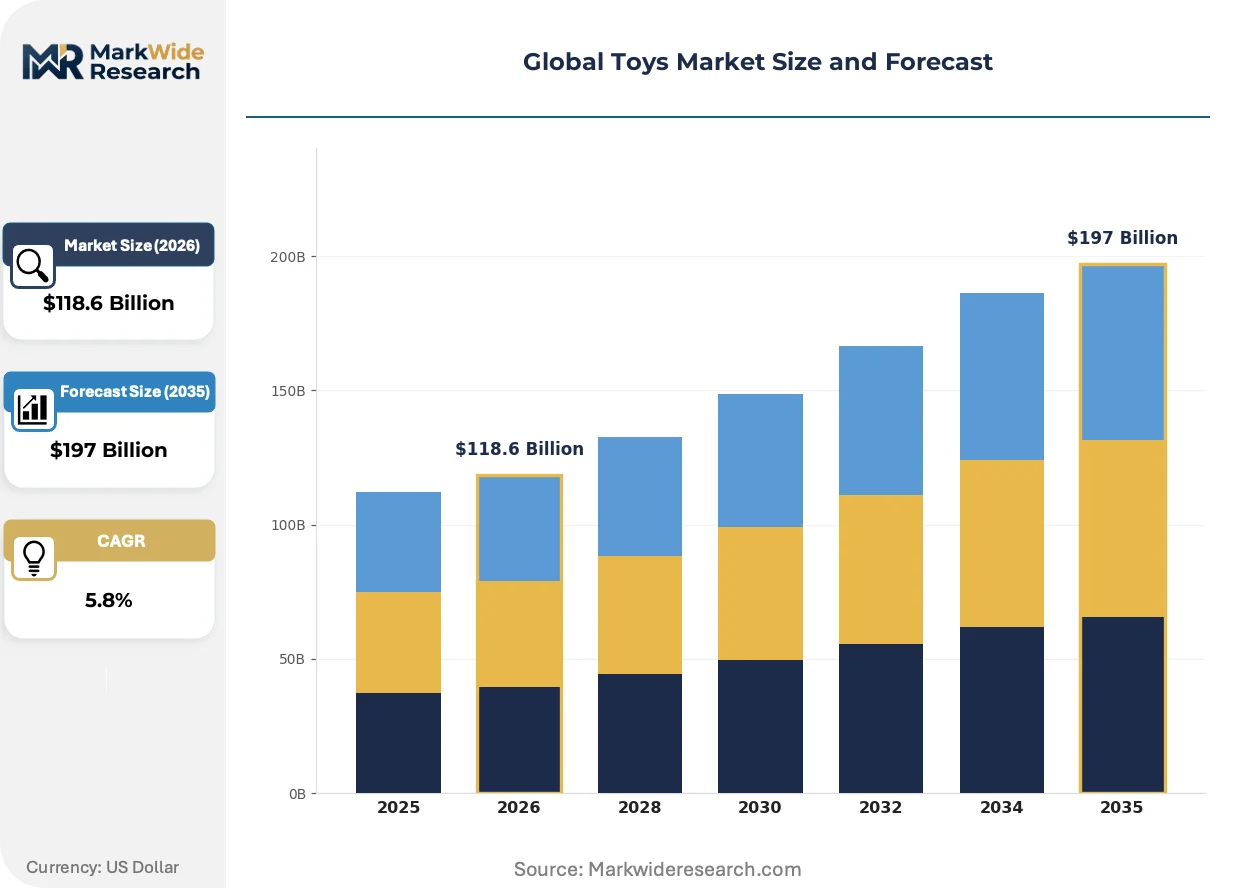
| Market Size in 2026 | $118.6 Billion |
| Market Size in 2035 | $197 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Action Figures, Dolls, Building Sets, Puzzles Age Group: Infants, Toddlers, Preschool, Teens Distribution Channel: Online Retail, Department Stores, Specialty Stores, Supermarkets Material: Plastic, Wood, Fabric, Metal |
| Companies Covered | The LEGO Group, Mattel, Hasbro, Spin Master, Bandai Namco Holdings Inc., MGA Entertainment, JAKKS Pacific, Funko, VTech Holdings Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Toys Market Strategic Shifts
Physical-digital hybrid play experiences are redefining value capture models, while regulatory chemical restrictions and direct-to-consumer channel migration reshape competitive requirements across manufacturing and distribution functions.
Programmable robotics kits is modularizing construction play by integrating microcontroller boards with interchangeable mechanical components. STEM-focused parents and extracurricular learning centers are adopting these systems at accelerating rates. The technology is modularizing supplier ecosystems, enabling specialist firms to compete without full vertical manufacturing scope.
REACH Annex XVII phthalate restrictions are eliminating legacy plasticizers from mouth-contact toys across EU import channels. Manufacturers are reformulating with bio-based citrate and adipate alternatives at 15-40% cost premiums. The infant and toddler segment is absorbing these input costs through selective price escalation rather than margin compression.
Subscription box curation is replacing episodic retail purchasing for developmental toy categories. Direct-to-consumer platforms are displacing department store toy departments as the primary discovery channel. This behavioral shift is most visible in North American and Western European urban markets where delivery density supports economical last-mile economics.
Global Toys Market Segmentation
Toy market segmentation reveals divergent compliance intensities across product categories. Certification requirements from ASTM F963, EN 71, and GB 6675 cluster differently by material composition and intended age group, creating distinct margin architectures for suppliers.
Product Type:
ASTM F963 mechanical testing applies universally, while EN 71 chemical migration limits hit mouth-contact categories hardest. Small parts regulations intensify for segments targeting children under three years.
- Action Figures:Articulated joints and painted surfaces require phthalate-free formulations under REACH Annex XVII. Licensed entertainment IP drives procurement from North American collectors and Asian export markets, though minimum guarantee structures strain working capital for mid-scale manufacturers.
- Building Sets:Interlocking plastic bricks and expansion modules command complexity premiums through dimensional tolerances under 0.5 millimeters. Repeat-purchase expansion sets concentrate demand among STEM-focused parents in OECD markets, with EU Green Deal circularity mandates favoring reusable construction architectures.
- Dolls:Fabric textiles and synthetic hair fibers face flammability testing under CPSC guidelines.
- Puzzles:Cardboard and wood composite substrates carry lower chemical compliance burdens than molded plastics.
Leading the category by volume: Building Sets. Growing fastest: Action Figures.
Age Group:
Regulatory stringency escalates inversely with child age, with infant categories facing the heaviest multi-jurisdiction testing protocols.
- Infants:Mouth-contact exposure mandates bio-based plasticizer alternatives at 15-40% cost premiums. Institutional procurement from early childhood education centers in Germany and France absorbs these input costs through selective price escalation rather than margin compression.
- Toddlers:ASTM F963 small parts regulations and EN 71-1 mechanical safety standards govern dimensional specifications. Parental analytics dashboards from connected toy architectures are extending product lifecycles through subscription content in North American urban markets.
- Preschool:STEM-aligned developmental play systems are hardening acquisition standards around milestone-based curricula.
- Teens:Collectible categories and hobby-grade robotics kits bypass the strictest chemical migration limits.
Preschool captures the steepest expansion trajectory as institutional buyers formalize procurement standards. Infants retain the highest margin pools due to compliance barriers.
Distribution Channel:
Channel selection determines working capital intensity and data capture capabilities, with direct-to-consumer platforms displacing legacy wholesale relationships.
- Online Retail:Proprietary e-commerce channels bypass wholesale markups while capturing first-party behavioral data for personalization algorithms. Delivery density in London, New York, and Tokyo supports economical last-mile economics for subscription box curation.
- Department Stores:Foot traffic compression in North American and Western European markets has reduced shelf space allocation for passive entertainment formats.
- Specialty Stores:Curated assortments and staff expertise sustain premium positioning for construction and hobby categories.
- Supermarkets:High-velocity impulse categories dominate, with price points constrained by private-label competition.
Online Retail is climbing the fastest as direct-to-consumer platforms displace traditional department store discovery. Specialty Stores defend the highest margin position through expertise differentiation.
Material:
REACH chemical restrictions and EU Green Deal mandates are accelerating substitution investments across substrate categories.
- Plastic:ABS and polypropylene resin prices fluctuate with crude oil benchmarks, compressing margin predictability for Guangdong-based molders. Phthalate bans are eliminating legacy plasticizers from mouth-contact applications, opening premium positioning for compliant suppliers with bio-based citrate formulations.
- Wood:Sustainability-positioned buyers in Germany, Sweden, and the Netherlands are absorbing 20-35% cost premiums for FSC-certified substrates. Ecodesign requirements for recyclable packaging favor wood's end-of-life circularity profile.
- Fabric:Textile flammability standards under ASTM F963 govern plush and soft-bodied categories.
- Metal:Die-cast alloys face heavy-element migration testing under EN 71-3 for painted and plated surfaces.
Plastic retains volume leadership through cost scalability. Wood is gaining share fastest among European sustainability-positioned buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shantou's Chenghai District anchors global toy manufacturing through its specialized economic zone status, concentrating mold-making, electronics assembly, and packaging logistics within a 50-kilometer radius. This clustering generates cost efficiencies that sustain export competitiveness despite rising labor costs.
United States
Subscription box curation and direct-to-consumer platforms are displacing department store discovery channels in New York, Los Angeles, and Chicago metro areas. ASTM F963 standards enforced by the CPSC govern mechanical safety and chemical content for all imported products. El Segundo and Pawtucket host headquarters operations for major catalog holders, with distribution gravity shifting toward Dallas-Fort Worth logistics hubs.
Germany
Institutional procurement from early childhood education centers in Berlin and Munich is formalizing acquisition standards around developmental milestones. REACH Annex XVII phthalate restrictions and EU Green Deal circularity mandates are accelerating material substitution investments. Nuremberg's annual toy fair remains the decisive product launch venue for European market entry.
China
Domestic consumption in Shanghai, Beijing, and Guangzhou is hardening around STEM-aligned educational categories. SAMR implements GB 6675 standards for domestic circulation, creating dual compliance burdens for export-oriented manufacturers. The Pearl River Delta cluster in Guangdong Province concentrates 70% of global molded plastic toy output, though energy rationing periodically disrupts production continuity.
India
Modern trade formats in Mumbai, Delhi-NCR, and Bangalore's tier-two satellite cities are creating first-mover positioning for quality-assured import brands. BIS certification requirements for toys are tightening import inspection protocols at major container ports. The Maharashtra Industrial Development Corporation is soliciting toy manufacturing investments through production-linked incentive schemes.
Japan
Collectible categories and hobby-grade robotics kits sustain premium positioning in Tokyo, Osaka, and Nagoya metropolitan markets. METI oversees product safety through the Consumer Product Safety Act, with JIS standards governing mechanical specifications. Akihabara's retail cluster continues to anchor domestic distribution for character-licensed merchandise and construction systems.
Global Toys Market Competitive Environment
Top-tier vendors anchor catalog breadth across multiple product categories, while mid-scale specialists compete through licensed entertainment tie-ins and regional manufacturing scale. The market structure concentrates around construction systems, dolls, and action figures as the three dominant product archetypes. Strategic moves center on direct-to-consumer platform integration and material compliance investments that satisfy multi-jurisdiction chemical restrictions.
Within the construction systems tier, The LEGO Group exemplifies captive manufacturing discipline and dimensional precision standards. Mattel occupies a position representing catalog breadth across dolls and infant categories. Hasbro sits within the licensed entertainment vector, leveraging franchise agreements that extend retail shelf life for action figures and board games.
| Leading Market Players |
|---|
| The LEGO Group |
| Mattel |
| Hasbro |
| Spin Master |
| Bandai Namco Holdings Inc. |
| MGA Entertainment |
| JAKKS Pacific |
| Funko |
| VTech Holdings Ltd. |
| Others |
Value Chain & Pricing Dynamics
REACH Annex XVII phthalate mandates are forcing material reformulation across mouth-contact toy categories, compelling Guangdong molders to absorb 15-40% input cost premiums or pass escalation to German and French institutional buyers. This specification pressure stratifies supplier tiers between compliant premium-positioned manufacturers and legacy operators facing margin compression.
Pricing Analysis
Short lead-time premiums dominate procurement negotiations as EU toy fair launch cycles compress planning windows. Three-tier pricing structure across premium, standard, and economy levels separates FSC-certified wood substrates from conventional ABS molded products, with certification grade and volume scale as primary differentiation drivers. Cost compression in economy plastic tiers is intensifying because of petrochemical input volatility. Mass-market retail buyers exhibit highest price sensitivity, while early childhood education centers in OECD markets absorb selective escalation.
Supply Chain Analysis
Dual-sourcing qualification requirements from Mattel and Hasbro procurement teams are fragmenting mold-making contracts across Chenghai District and emerging Vietnam facilities. Supply concentration centers on China, Vietnam, and India, with ABS resin, polypropylene, and bio-based citrate plasticizers as critical input dependencies. Single-source vulnerability persists in precision mold fabrication capabilities. Distribution runs through direct-to-consumer platforms and Dallas-Fort Worth logistics hubs serving North American retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global toys market sits in a physical-digital hybrid transition, with programmable robotics kits and subscription analytics platforms displacing passive entertainment formats.
For Market Incumbents: Anchor catalog breadth through captive manufacturing discipline in construction systems while accelerating REACH-compliant material substitution ahead of regulatory deadlines. Vertical integration into bio-based plasticizer supply hedges against ECHA restriction expansion. Direct-to-consumer platform control preserves margin pools eroding in wholesale channels.
For New Entrants and Emerging Players: Capture white-space in India's tier-two modern trade expansion and EU Green Deal circularity-compliant wood construction segments. Subscription box curation in North American urban markets offers the most penetrable entry vector. Partner with specialty retail staff expertise channels to bypass incumbent shelf-space dominance.
For Investors and Strategic Acquirers: The window for entry favors mid-scale manufacturers with licensed IP negotiation capabilities and compliant material portfolios. Long-term viability hinges on direct-to-consumer data capture infrastructure and STEM-aligned product architectures. Watch connected toy subscription attach rates as the inflection signal for platform transition maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Platform Launch | Proprietary channels bypass wholesale markups while capturing behavioral data for personalization algorithms. |
| REACH-Compliant Material Reformulation | Bio-based plasticizer investments open premium positioning in EU import channels facing Annex XVII enforcement. |
| Subscription Box Curation Model | Recurring revenue structures extend product lifecycles through expansion set discovery in North American metros. |
| India Modern Trade Distribution Expansion | Tier-two city retail formats create first-mover positioning for quality-assured import brands ahead of BIS tightening. |
| Licensed Entertainment IP Acquisition | Franchise agreements extend retail shelf life for action figure categories despite minimum guarantee capital intensity. |
Study Parameters
Independent corroboration across procurement directors at major toy retailers, regulatory affairs leads at EU import distributors, and plant managers at Guangdong molding facilities underwrites the qualitative findings. Primary interviews with early childhood education center administrators in Berlin and Mumbai supplemented secondary validation from CPSC enforcement databases, ECHA restriction updates, and customs trade flow records. Bottom-up SKU-level demand modeling triangulates against top-down category value estimates.
Historical reference periods spanning pre-pandemic baseline through post-supply-shock recovery anchor the projection horizon. The analytical framework segments volume and value across product type, age group, material composition, and distribution channel, with regional regulatory cluster as an additional dimension. CAGRs derive from trend extrapolation moderated by petrochemical input volatility and institutional procurement standardization rates.
The model holds under stable REACH enforcement intensity and intact Pearl River Delta production continuity; deviation in energy rationing severity or phthalate restriction expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Toys and Games
Dartboard Market
Toys and Games
Ride-Ons Market
Toys and Games
Global Educational Toy Market
Toys and Games
Board Games and Puzzles Market
Toys and Games
LAMEA Action Figure Toys Market
Toys and Games
Kids Toys Market
Toys and Games
Wooden Toys Market
Toys and Games
Snooker Tables Market
Toys and Games
Eco-Friendly Toys Market
Toys and Games
Microwaveable Stuffed Animal Toys Market
Toys and Games
Toy Kitchens and Play Food Market
Toys and Games
Autonomous Robot Toys Market
Toys and Games
Connected Toys Market
Toys and Games
Toy Collectibles Market
Toys and Games
United States Toys Market
Toys and Games
Bounce House Market