
 Ride-Ons Market | 2026-2036
Ride-Ons Market Size, Share, and Industry Trends Forecast 2026-2036
Ride-Ons Market Analytics
ASTM F963 toy safety compliance is collapsing the supplier base as smaller manufacturers struggle with third-party testing costs and traceability mandates. Mattel, Inc. leverages its in-house testing laboratories to accelerate certification cycles across multiple product lines. Peg Pérego anchors European demand through its specialized electric ride-on segment with integrated battery management systems. Little Tike differentiates via rotomolded plastic durability and exclusive big-box retail placement in North America.
Ride-ons are wheeled mobility toys designed for children, typically incorporating electric motors with voltages ranging from 6V to 24V, pedal drivetrains, or push-assist frames, constructed from blow-molded polyethylene, steel tubing, or laminated wood composites for indoor and outdoor recreational use. Electric Ride-Ons lead volume as lithium-ion battery costs decline and parents prioritize motorized experiences, while Balance Bikes represent the fastest-growing category as early childhood cycling programs expand in preschool curricula. The Premium price tier captures disproportionate margin pools through licensed automotive branding and app-connected features, whereas Budget tier sales concentrate in seasonal retail windows with high inventory turnover.
The Consumer Product Safety Commission enforces mandatory reporting and recall protocols for ride-on products, while the EPA regulates battery disposal and lead-acid material restrictions, and California's Proposition 65 mandates chemical labeling that shapes material selection across supply chains. Stakeholders must monitor evolving state-level right-to-repair legislation that could mandate replaceable battery access and extend product lifecycle expectations.
Market Dynamics
ASTM F963 compliance costs are consolidating supplier tiers as third-party testing mandates eliminate marginal producers, while lithium-ion battery economics simultaneously democratize motorized ride-on access across income brackets.
Growth Catalysts
- Preschool Curriculum Integration:Early childhood cycling programs in suburban United States school districts are institutionalizing balance bike procurement as mandatory physical education equipment.
- REACH Chemical Transparency:European Union material disclosure requirements are accelerating substitution of phthalate-laden plastics with bio-based polyethylene alternatives.
- Suburban Retail Corridors:Indoor play venue chains in Texas, Florida, and California are expanding dedicated ride-on zones to capture recurring family entertainment spend.
Market Restraints
- Lithium Supply Concentration:Battery cell manufacturing concentrates in China, exposing price volatility from export licensing shifts and raw material processing bottlenecks.
- Lead-Acid Disposal Friction:EPA hazardous waste protocols impose collection infrastructure costs that compress margins on entry-level electric ride-on models.
- Rotomolding Capacity Scarcity:Specialized polyethylene blow-molding equipment requires 18-24 month lead times, constraining rapid volume scaling for seasonal demand surges.
Strategic Opportunities
- App-Connected Feature Convergence:Bluetooth parental controls and geofencing are merging with licensed automotive branding to command premium positioning.
- Right-to-Repair Legislation:Proposed state-level battery access mandates in California and New York would extend product lifecycles and create aftermarket service revenue pools.
- India Tier-2 Urbanization:Rising disposable income in Pune, Ahmedabad, and Hyderabad is generating first-time motorized ride-on demand outside traditional metro markets.
Industry Challenges
- Certification Timeline Compression:ASTM F963 electrical testing protocols now require 14-16 week validation cycles, misaligning with seasonal retail procurement windows.
- Licensed IP Negotiation Complexity:Automotive brand partnerships demand minimum volume guarantees and royalty structures that strain working capital for mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ride-Ons Market |
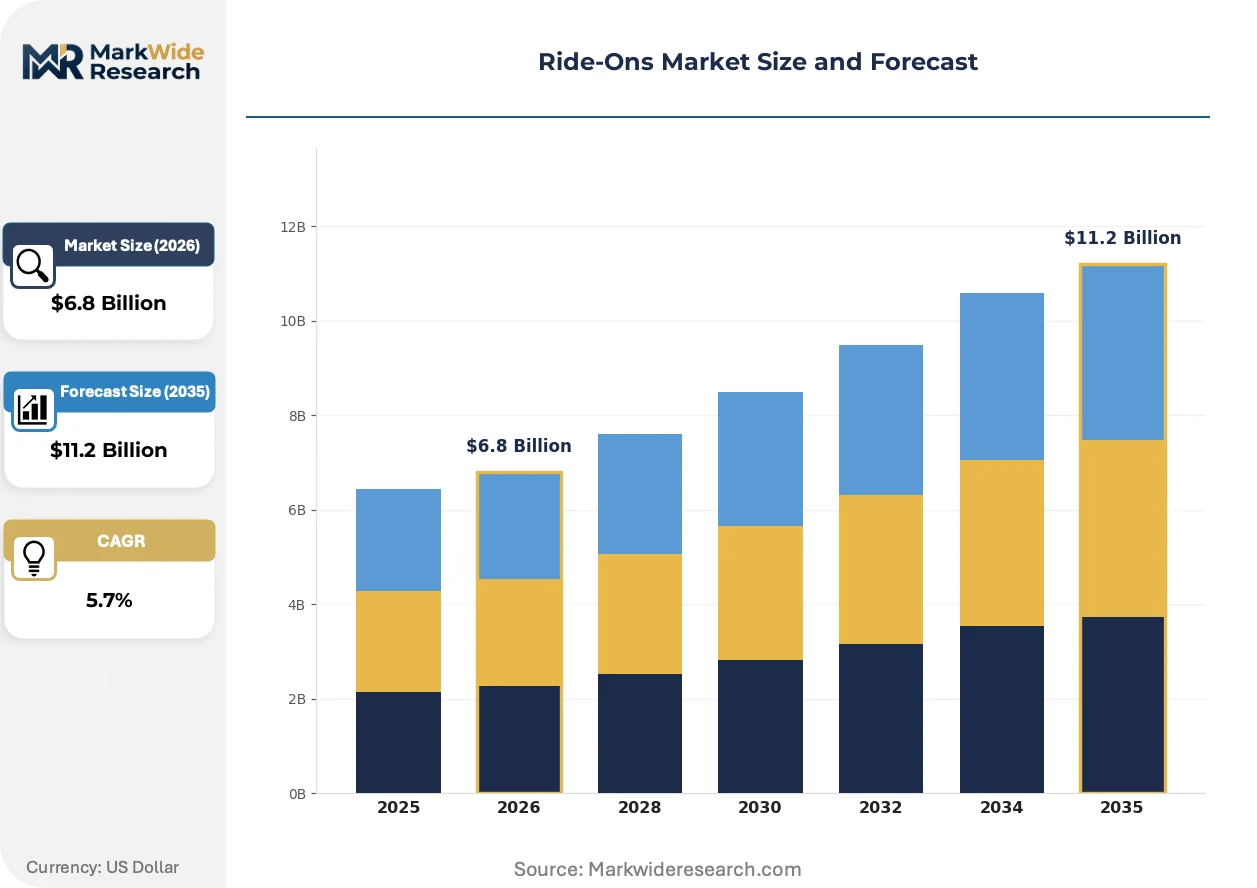
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Ride-Ons, Pedal Ride-Ons, Push Ride-Ons, Balance Bikes Age Group: Toddlers, Preschoolers, Early School Age, Older Kids Material: Plastic, Metal, Wood, Composite Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | Peg Pérego, Mattel, Inc., Little Tikes, Fisher-Price, Jakks Pacific, Inc., Toy House, Inc., Razor, Kid Motorz, Toyzone Impex Private Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ride-Ons Market Evolving Landscape
Digital connectivity and sustainable materials are redefining product architecture, while regulatory disclosure mandates reshape competitive differentiation beyond traditional safety compliance.
Lithium iron phosphate battery chemistry is displacing legacy lead-acid and standard lithium-ion configurations in premium electric ride-ons. Suburban parents purchasing 24V motorized vehicles for children aged 5-8 are prioritizing thermal stability and extended cycle life over upfront cost. This chemistry shift is compressing warranty liability exposure for manufacturers while enabling faster charge rates that support venue fleet utilization models.
California's Proposition 65 enforcement expansion is mandating explicit chemical labeling for chromium and bisphenol traces in plastic components. Manufacturers serving the United States market are reformulating masterbatch compounds and redesigning supply contracts to exclude flagged substances. The premium licensed segment bears disproportionate compliance burden as brand licensors enforce reputational risk clauses above statutory minimums.
Direct-to-venue procurement is consolidating purchase authority away from traditional toy distributors. Indoor entertainment chains in the United States are negotiating multi-year fleet refresh contracts with integrated maintenance provisions, bypassing seasonal retail intermediaries. This channel compression concentrates volume with manufacturers possessing dedicated account management and rapid spare parts fulfillment infrastructure.
Ride-Ons Market Segmentation
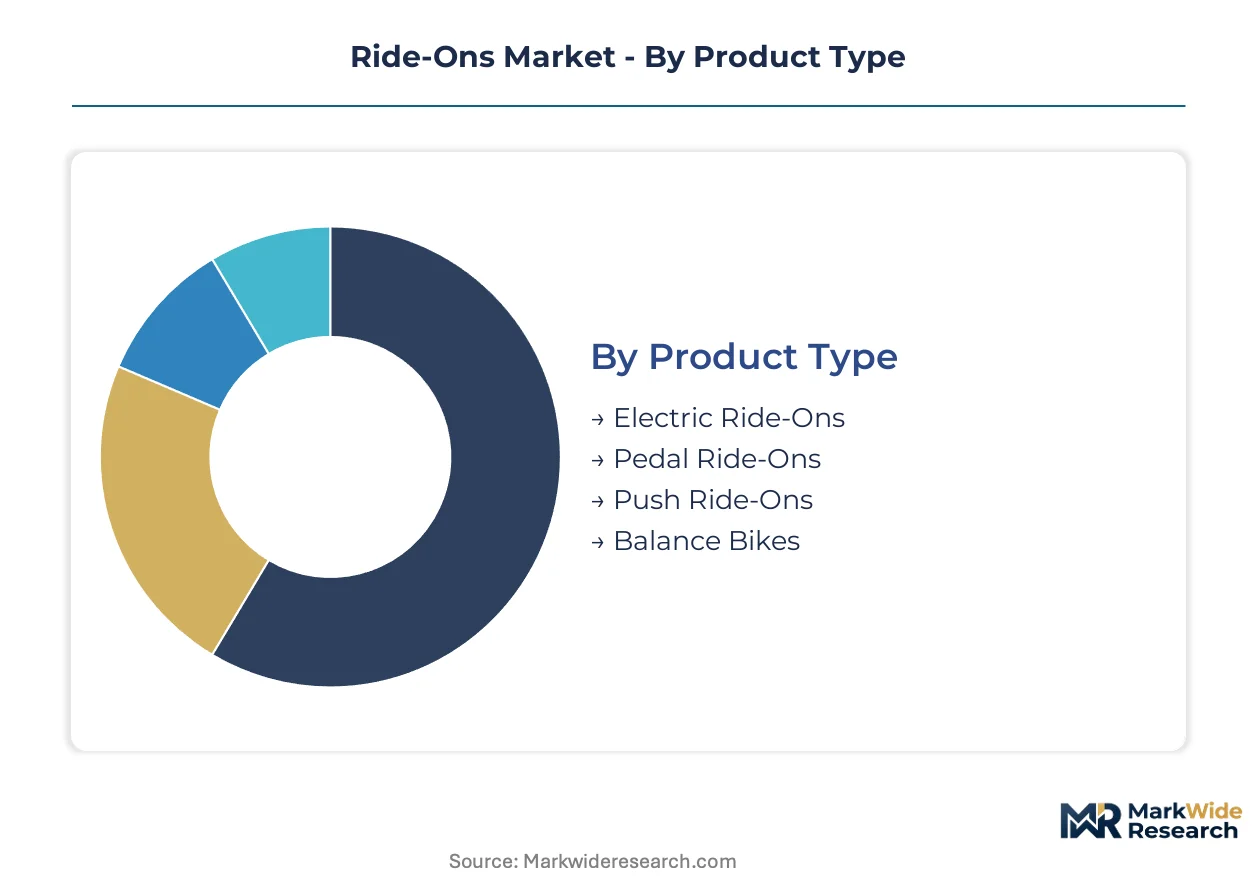
Ride-ons segmentation reveals how regulatory pressure, material economics, and channel dynamics fragment procurement patterns. ASTM F963 electrical testing mandates and Proposition 65 chemical disclosure create divergent compliance burdens across product architectures.
Product Type:
ASTM F963 electrical testing protocols impose 14-16 week validation cycles on motorized variants, while mechanical categories face lighter third-party certification burdens.
- Electric Ride-Ons:These incorporate 6V to 24V lithium-ion or lead-acid battery systems with integrated motor controllers and thermal management. Demand concentrates in suburban United States retail corridors where parents prioritize motorized experiences for children aged 3-8. Lithium iron phosphate chemistry is displacing legacy configurations as thermal stability becomes a procurement priority for venue fleet operators.
- Balance Bikes:Pedal-free frames with low-center-of-gravity geometry train proprioceptive balance before transitioning to bicycles. Early childhood cycling programs in Texas, Florida, and California school districts are institutionalizing procurement as mandatory physical education equipment. This segment is gaining share fastest as preschool curricula expand cycling literacy requirements.
- Pedal Ride-Ons:Chain or direct-drive drivetrains with adjustable seat posts accommodate growth spurts across 2-6 year age spans.
- Push Ride-Ons:Parent-assisted frames with grab handles and anti-tip wheelbases target 12-24 month developmental stages.
Established volume favors Electric Ride-Ons; emerging adoption favors Balance Bikes.
Age Group:
Physical scale requirements and supervision liability shape product liability exposure across developmental stages.
- Preschoolers:3-5 year capacity range drives peak unit velocity as motor skill acquisition coincides with independent play expectations. ASTM F963 small parts testing and pinch-point regulations concentrate compliance investment here. Licensed automotive branding commands disproportionate pricing power in this cohort.
- Toddlers:12-36 month low-speed push categories prioritize tip-resistant wheelbases and parent retention tethers. Indoor play venue chains in the United States specify commercial-grade durability for this segment to withstand repetitive use.
- Early School Age:5-7 year demand shifts toward 24V motorized performance and bicycle-transition products.
- Older Kids:8-12 year segment contracts as product differentiation blurs into youth bicycle and ATV categories.
Procurement volume peaks with Preschoolers; product innovation concentrates on Toddlers.
Material:
REACH chemical transparency and California Proposition 65 enforcement are accelerating substitution away from phthalate-laden formulations.
- Plastic:Rotomolded polyethylene and blow-molded chassis dominate mass-market production. Rotomolding capacity scarcity—18-24 month equipment lead times—constrains seasonal surge response. Bio-based polyethylene alternatives are penetrating premium tiers as brand licensors enforce reputational risk clauses above statutory minimums.
- Metal:Steel tubing frames with powder-coated finishes serve commercial venue fleets requiring crash durability beyond consumer-grade specifications. Texas and Florida indoor play chains specify metal construction for high-frequency rotation schedules.
- Wood:Laminated birch and marine-ply configurations target sustainability-positioned premium segments with shorter replacement cycles.
- Composite:Glass-reinforced nylon and carbon fiber hybrid structures appear in performance-oriented balance bike categories.
Unit economics favor Plastic; sustainability positioning favors Wood.
Price Tier:
Channel placement and intellectual property licensing structures stratify margin capture across retail formats.
- Premium:App-connected features, Bluetooth parental controls, and geofencing merge with licensed automotive branding to command positioning above mass-market alternatives. California and New York right-to-repair proposals would extend lifecycle expectations and create aftermarket service revenue pools for this tier.
- Budget:Seasonal retail windows with high inventory turnover concentrate in big-box placement. EPA lead-acid disposal protocols compress margins as hazardous waste collection infrastructure costs flow through to entry-level electric models.
- Mid-Range:Feature-stripped variants of premium platforms without connectivity or licensed IP.
- Luxury:Hand-finished wood and limited-run collaborations with design houses serve gift-market occasions.
Margin concentration sits with Premium; velocity concentration sits with Budget.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Suburban retail corridors and indoor play venue chains in the United States concentrate procurement authority for motorized and balance bike categories. Institutional buyers in early childhood education and commercial entertainment sectors now drive volume commitments ahead of seasonal consumer patterns.
United States
Texas, Florida, and California indoor play chains are expanding dedicated ride-on zones to capture recurring family entertainment spend. The Consumer Product Safety Commission enforces mandatory reporting and recall protocols that extend certification timelines. ASTM F963 electrical testing protocols in suburban retail corridors now require 14-16 week validation cycles.
Germany
REACH chemical transparency requirements are accelerating substitution of phthalate-laden plastics with bio-based polyethylene alternatives. ECHA disclosure mandates reshape material selection across supply contracts. Bavaria-based manufacturing clusters specialize in precision battery management systems for premium electric ride-on segments.
China
Battery cell manufacturing concentrates in coastal provinces, exposing price volatility from export licensing shifts. MIIT regulations govern lithium-ion production standards and raw material processing protocols. Shenzhen and Dongguan industrial zones supply integrated motor controllers to global ride-on assemblers.
India
Rising disposable income in Pune, Ahmedabad, and Hyderabad is generating first-time motorized ride-on demand outside traditional metro markets. BIS safety standards for electrical toys are tightening import inspection regimes. Maharashtra and Gujarat manufacturing corridors are developing domestic rotomolding capacity for plastic chassis production.
United Kingdom
Early childhood cycling programs in Greater London and Southeast England school districts are institutionalizing balance bike procurement. The country's national toy safety regulator enforces compliance with EU-derived electrical and chemical standards. Midlands distribution hubs coordinate seasonal inventory flows to European retail networks.
Ride-Ons Market Competitive Landscape
Player mix skews toward diversified toy conglomerates with in-house testing infrastructure and specialized regional manufacturers with battery system expertise. Market structure consolidates around ASTM F963 compliance capabilities as third-party testing costs eliminate marginal producers. Three archetypes dominate: legacy toy conglomerates with licensed automotive partnerships, European specialists in electric drivetrain integration, and Asian contract manufacturers with rotomolding scale. Competitive moves concentrate on certification acceleration and direct-to-venue channel compression.
Within the legacy conglomerate tier, Mattel, Inc. and Fisher-Price occupy positions defined by in-house laboratory infrastructure and exclusive big-box retail placement. Peg Pérego exemplifies the European specialist archetype with its incorporated geographic origin signaling battery management system capabilities. These three entities represent contrasting strategic postures: testing autonomy, retail channel capture, and drivetrain specialization.
| Leading Market Players |
|---|
| Peg Pérego |
| Mattel, Inc. |
| Little Tikes |
| Fisher-Price |
| Jakks Pacific, Inc. |
| Toy House, Inc. |
| Razor |
| Kid Motorz |
| Toyzone Impex Private Limited |
| Others |
Value Network & Pricing Analysis
Eighteen-to-twenty-four-month lead times for rotomolding equipment compress pricing power for seasonal surges while concentrating margin capture with manufacturers possessing captive polyethylene processing capacity. ASTM F963 certification timelines and lithium-ion battery indexation clauses reshape contract structures across motorized and mechanical categories alike.
Pricing Analysis
Cost-plus contracts with lithium carbonate indexation dominate battery procurement agreements between ride-on assemblers and cell suppliers. Pricing stratifies across premium licensed tiers with app-connected features, mid-range stripped variants, and budget seasonal retail placement. Cost compression in entry-level electric models intensifies because EPA lead-acid disposal protocols flow hazardous waste infrastructure costs downstream. Mass-market big-box buyers exhibit acute price sensitivity; venue fleet operators with multi-year refresh contracts show markedly lower elasticity.
Supply Chain Analysis
China anchors battery cell manufacturing and integrated motor controller production for global ride-on assembly. Polyethylene resin draws from Saudi Arabian and Qatari petrochemical complexes; rotomolded chassis fabrication clusters in Dongguan and Ahmedabad. Single-source vulnerability concentrates in lithium processing capacity subject to export licensing volatility. Distribution runs through direct-to-venue procurement channels that bypass traditional toy distributors for indoor entertainment chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ride-ons market sits in early-cycle expansion as preschool curriculum mandates institutionalize balance bike procurement across suburban United States school districts. This tailwind extends replacement cycles and concentrates purchase authority with institutional buyers ahead of seasonal consumer patterns.
For Market Incumbents: Fortify ASTM F963 compliance infrastructure against certification timeline compression that misaligns with retail procurement windows. Accelerate in-house electrical testing capacity to compress 14-16 week validation cycles. Deepen backward integration into rotomolding equipment to secure polyethylene processing capacity against 18-24 month lead time scarcity.
For New Entrants and Emerging Players: Differentiate on right-to-repair service architecture targeting California and New York battery access mandates. White-space opportunities concentrate in India tier-2 urbanization corridors—Pune, Ahmedabad, Hyderabad—where first-time motorized demand outpaces domestic supply. Pursue direct-to-venue fleet contracts with integrated maintenance provisions to bypass entrenched retail distributor relationships.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance premium play because ASTM F963 testing capabilities consolidate supplier tiers and concentrate margin pools with certified manufacturers. Acquisition targets should exhibit dedicated account management infrastructure and rapid spare parts fulfillment for venue chains. Monitor state-level right-to-repair legislation passage as inflection signal for aftermarket service revenue expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| ASTM F963 Certification Acceleration | In-house testing laboratories compress 14-16 week electrical validation cycles ahead of seasonal retail windows. |
| Lithium Iron Phosphate Chemistry Transition | Thermal stability specifications from Texas and Florida venue chains displace legacy lead-acid configurations. |
| Direct-to-Venue Channel Compression | Multi-year fleet refresh contracts with indoor play chains bypass traditional toy distributor margins. |
| Right-to-Repair Service Infrastructure | California battery access mandates extend product lifecycles and create recurring aftermarket revenue pools. |
| India Tier-2 Manufacturing Localization | Maharashtra and Gujarat rotomolding capacity addresses first-time motorized demand outside metro markets. |
Research Methodology
Desk research of customs trade records, BIS safety standard filings, and indoor entertainment chain procurement disclosures preceded structured interviews with rotomolding equipment suppliers, preschool physical education coordinators, venue fleet procurement managers, and lithium-ion battery sourcing leads. Secondary validation drew from EPA hazardous waste protocol documents, ASTM F963 testing laboratory accreditations, and state legislative tracking databases. Bottom-up unit shipment estimates triangulated against top-down retail audit data across the analysis window.
Variance decomposition across product type, age group, material formulation, price tier, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from segmented growth rate reconciliation against macroeconomic drivers. Forecast inputs incorporated lithium carbonate price index trajectories, rotomolding capacity expansion pipelines, and preschool curriculum adoption timelines by United States school district.
Decision-makers should treat outputs as directional under assumptions of stable ASTM F963 enforcement intensity and lithium export licensing continuity; material deviation in battery supply concentration or regulatory timeline compression would warrant model refresh. Recalibration cycles align with material shifts in state-level right-to-repair legislation and preschool procurement mandate expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Toys and Games
Claw Crane Machine Market
Toys and Games
Decompression Toys Market
Toys and Games
Microwaveable Stuffed Animal Toys Market
Toys and Games
Remote Control Toys Market
Toys and Games
Drone for Kids Market
Toys and Games
Plush Toy Market
Toys and Games
Dildo Sex Toy Market
Toys and Games
Blind Box Toys Market
Toys and Games
Coaster Market
Toys and Games
Indoor Bumper Cars Market
Toys and Games
Board Games and Puzzles Market
Toys and Games
Bubble Blower Market
Toys and Games
Global Toys Market
Toys and Games
Smart/AI Toys Market
Toys and Games
Fabric Toys Market
Toys and Games
Playing Cards and Board Games Market