
 Toy Kitchens and Play Food Market | 2026-2036
Toy Kitchens and Play Food Market Size, Share, and Industry Trends Forecast 2026-2036
Toy Kitchens and Play Food Market Analytics
Modular kitchen sets with interchangeable appliance inserts and expandable counter modules is repositioning how parents evaluate long-term play value against single-unit alternatives. Hape leverages its vertically integrated bamboo sourcing to dominate sustainable wood segments across European retail channels. Melissa & Doug sustains its position through specialty store partnerships and fabric-based food sets that differentiate from plastic-heavy competitors. Little Tikes anchors volume in the mass-market tier through rotomolded outdoor kitchen configurations built for weather durability.
Toy kitchens and play food encompass scaled domestic environment replicas and simulated food items constructed from injection-molded plastics, sustainably harvested timber, sewn textiles, or stamped metals, designed to facilitate imaginative role-play, fine motor development, and social interaction in children aged six months to ten years. Indoor kitchens and play food sets command the largest revenue share as apartment-dwelling families prioritize space-efficient vertical designs with integrated storage, while outdoor kitchens represent the fastest-expanding category driven by backyard entertainment trends and all-weather material innovations. Wooden products capture premium margin pools through parental preference for heirloom durability and non-toxic finishes, though plastic maintains volume leadership via lower price points and character licensing compatibility.
ASTM F963 governs mechanical and chemical safety requirements for toys sold in the United States, while REACH restricts hazardous substances in European-manufactured and imported products, collectively elevating compliance costs but creating market access barriers for uncertified suppliers. China's GB standards and the EU Toy Safety Directive further fragment testing protocols, forcing manufacturers to maintain multiple certification streams or abandon specific geographies. Stakeholders must monitor evolving extended producer responsibility frameworks and bioplastic substitution economics as regulatory pressure on petroleum-based polymers intensifies without warning.
Market Dynamics
ASTM F963 and REACH compliance costs are compressing margins for petroleum-based plastic producers while accelerating biopolymer and certified timber substitution across manufacturing footprints.
Growth Catalysts
- REACH chemical restrictions:Phthalate bans in European markets are redirecting R&D spending toward plant-based polymers and water-based finishes that command parental premium willingness.
- Preschool curriculum integration:Early learning centers in the United States now mandate role-play stations as developmental standards, institutionalizing bulk procurement channels.
- Bamboo sourcing clusters:Vertically controlled supply networks in Zhejiang province are reducing raw material lead times for sustainable wood product lines.
Market Restraints
- Petrochemical input volatility:Polypropylene and ABS resin pricing fluctuations are destabilizing cost forecasting for injection-molded kitchen components.
- Multi-jurisdiction certification burden:Manufacturers must maintain parallel testing streams for ASTM F963, EU Toy Safety Directive, and China's GB standards to access major markets.
- Digital play substitution:Tablet-based cooking simulation applications are capturing attention minutes from traditional physical role-play among school-age children.
Strategic Opportunities
- Extended producer responsibility frameworks:Emerging take-back mandates in Germany and France create first-mover advantage for closed-loop material recovery systems.
- Outdoor kitchen expansion:Weather-resistant rotomolded configurations are penetrating suburban backyard entertainment segments previously unserved by indoor-focused suppliers.
- Bioplastic cost convergence:Polylactic acid price parity with conventional plastics is imminent, enabling mass-market tiering without margin sacrifice.
Industry Challenges
- Toxicology testing bottlenecks:Third-party laboratory capacity constraints are extending ASTM F963 certification timelines from twelve to twenty weeks.
- Heirloom-grade craftsmanship scarcity:Fine woodworking skills required for premium bamboo joinery are concentrated among aging artisan populations in Guangdong and Fujian provinces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Toy Kitchens and Play Food Market |
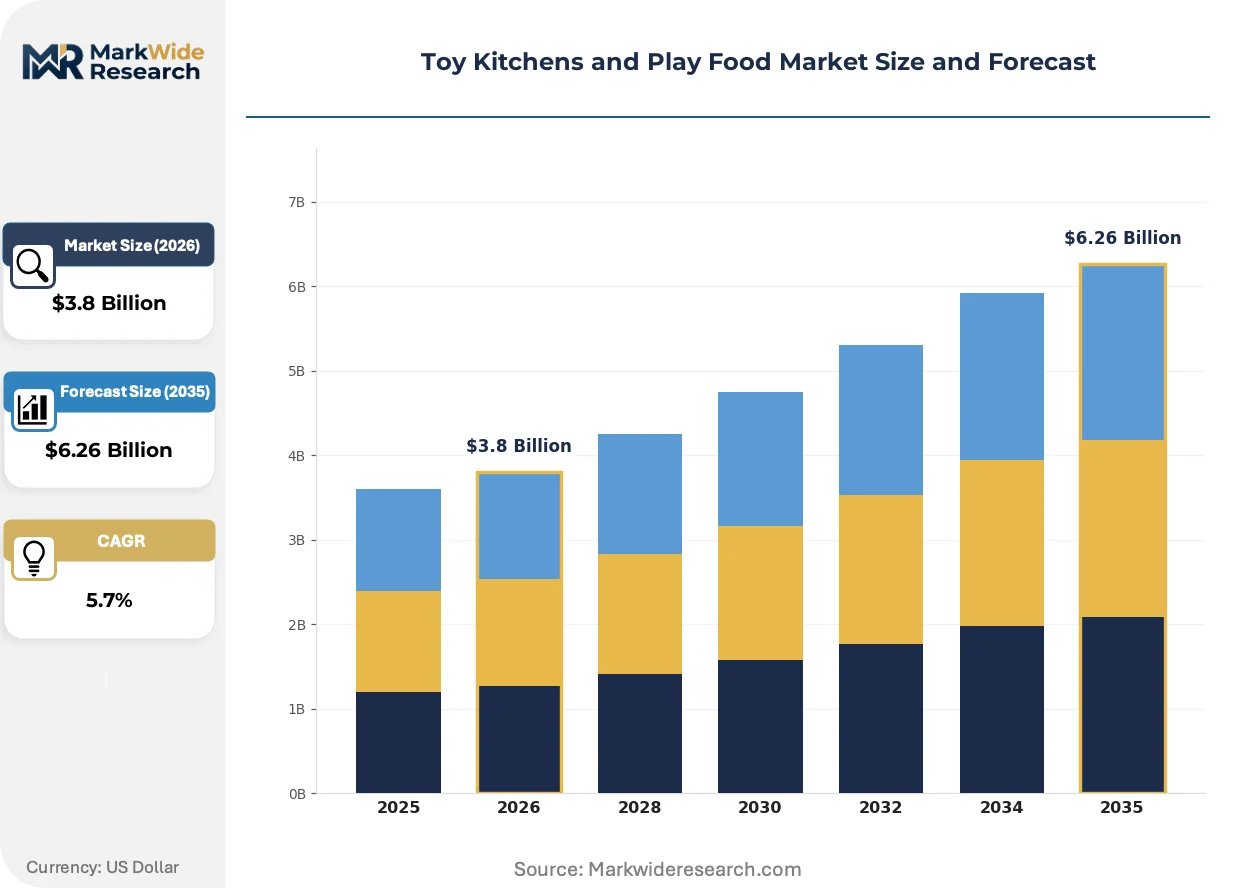
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor Kitchens, Outdoor Kitchens, Play Food Sets, Kitchen Accessories Age Group: Infants, Toddlers, Preschoolers, School-Aged Children Material: Plastic, Wood, Fabric, Metal Sales Channel: Online Retail, Toy Stores, Department Stores, Specialty Stores |
| Companies Covered | Lalo, IKEA, KidKraft, PoshPo, Melissa & Doug, Step2, Little Tikes, FAO Schwarz, Hape, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Toy Kitchens and Play Food Market Evolving Landscape
Material science breakthroughs and regulatory chemistry restrictions are converging to reshape product architecture, while distribution channels fragment between specialty retail consolidation and direct-to-parent digital platforms.
Near-field communication chips embedded in play food items are integrating digital recipe apps with physical kitchen play, enabling hybrid screen-toy experiences. Preschool technology coordinators in Nordic countries are piloting these connected sets at accelerated procurement cycles. The structural result is integrating data-capture capabilities into previously analog product categories, compressing replacement cycles through software update dependencies.
REACH Annex XVII phthalate restrictions are eliminating soft-PVC from teething-compatible play food components across European supply chains. Manufacturers serving Germany and France must reformulate or exit the infant-directed segment entirely. Wooden and silicone alternatives are capturing shelf space as retailers preempt enforcement actions.
Parental purchasing is migrating toward subscription-based toy rotation services that curate modular kitchen expansions quarterly. Specialty retail partnerships in the United States are losing volume to direct-to-consumer platforms offering customization tools. This channel rotation is most visible among urban apartment-dwelling families prioritizing storage-minimal consumption models.
Toy Kitchens and Play Food Market Segmentation
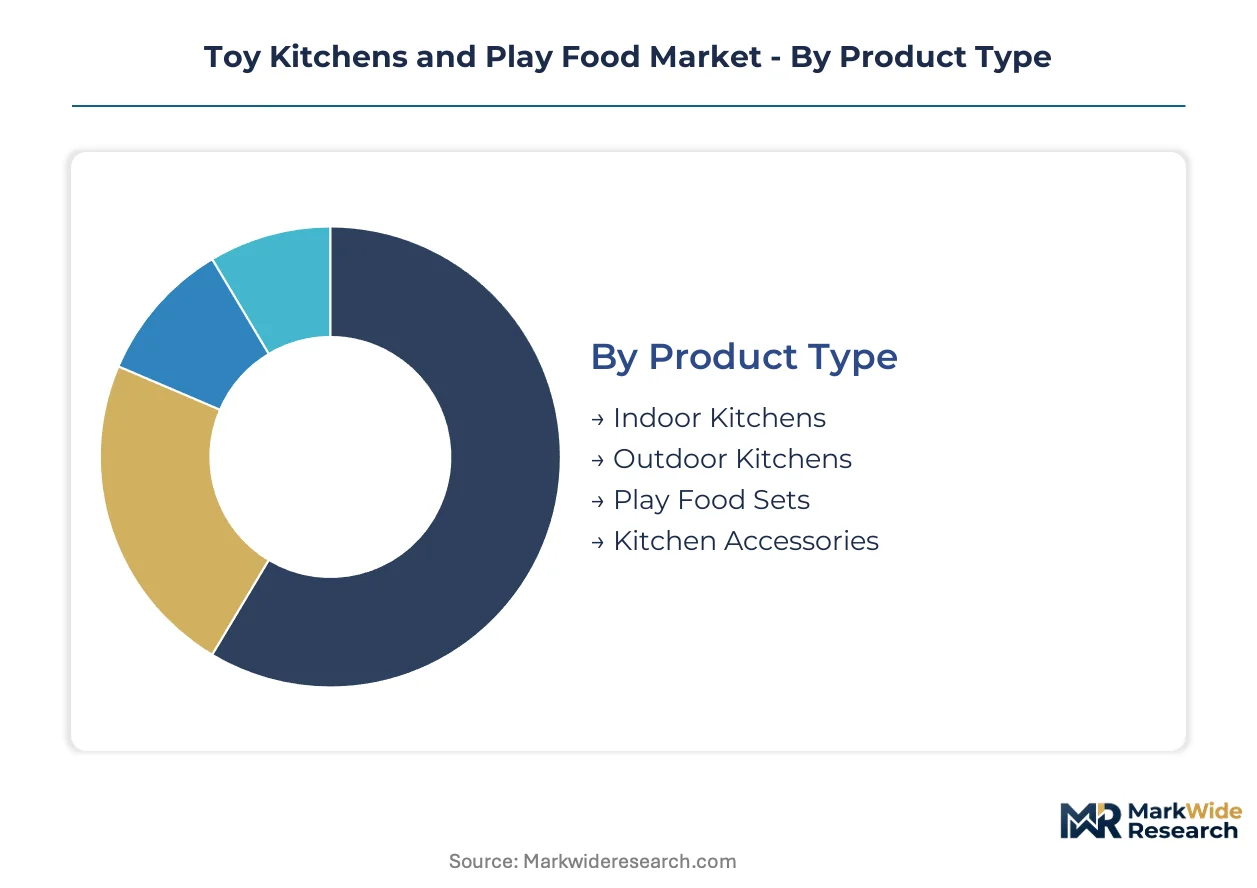
Segmentation in toy kitchens and play food determines procurement patterns across institutional buyers and retail channels. Upgrade cycles vary dramatically by material durability and age-appropriate design complexity.
Product Type:
Replacement frequency diverges sharply between weather-exposed outdoor installations and compact indoor systems designed for apartment storage constraints.
- Indoor Kitchens:Vertical configurations with integrated storage dominate urban apartment procurement in the United States and Germany. Space-efficient footprints command parental premium willingness as square footage constraints intensify in metropolitan housing markets.
- Outdoor Kitchens:Rotomolded polyethylene constructions withstand UV exposure and precipitation across suburban backyards. Weather-resistant material specifications are penetrating previously unserved entertainment segments in the United States and Australia.
- Play Food Sets:Fabric and silicone alternatives displace PVC in infant-directed segments under REACH Annex XVII pressure.
- Kitchen Accessories:Modular appliance inserts extend product lifecycles through interchangeable component economics.
Volume placements concentrate in Indoor Kitchens; the faster expansion belongs to Outdoor Kitchens.
Age Group:
Developmental milestone alignment determines safety certification requirements and material selection rigor across manufacturing footprints.
- Infants:Teething-compatible silicone and untreated wood constructions dominate under stringent phthalate restrictions.
- Toddlers:Rounded-edge wooden sets with non-toxic water-based finishes capture premium positioning in European specialty retail.
- Preschoolers:Curriculum-mandated role-play stations in United States early learning centers institutionalize bulk procurement at scale.
- School-Aged Children:Complex multi-appliance configurations with NFC-enabled recipe integration are gaining share fastest among digitally fluent demographics.
Procurement scale peaks with Preschoolers; School-Aged Children show the steepest technology-driven expansion trajectory.
Material:
Cost tier stratification separates petroleum-based volume production from certified timber premium positioning.
- Plastic:Injection-molded polypropylene and ABS maintain mass-market leadership through character licensing compatibility and price accessibility.
- Wood:FSC-certified bamboo and birch constructions command heirloom durability premiums in German and United States specialty channels.
- Fabric:Sewn textile food sets differentiate through tactile sensory development and machine-washable maintenance.
- Metal:Stamped stainless steel accessories anchor realistic cooking simulation for upper age brackets.
Unit economics favor Plastic at volume; Wood captures margin expansion as sustainability preferences harden.
Sales Channel:
Channel migration patterns reflect urban consumption shifts toward storage-minimal subscription models and direct customization.
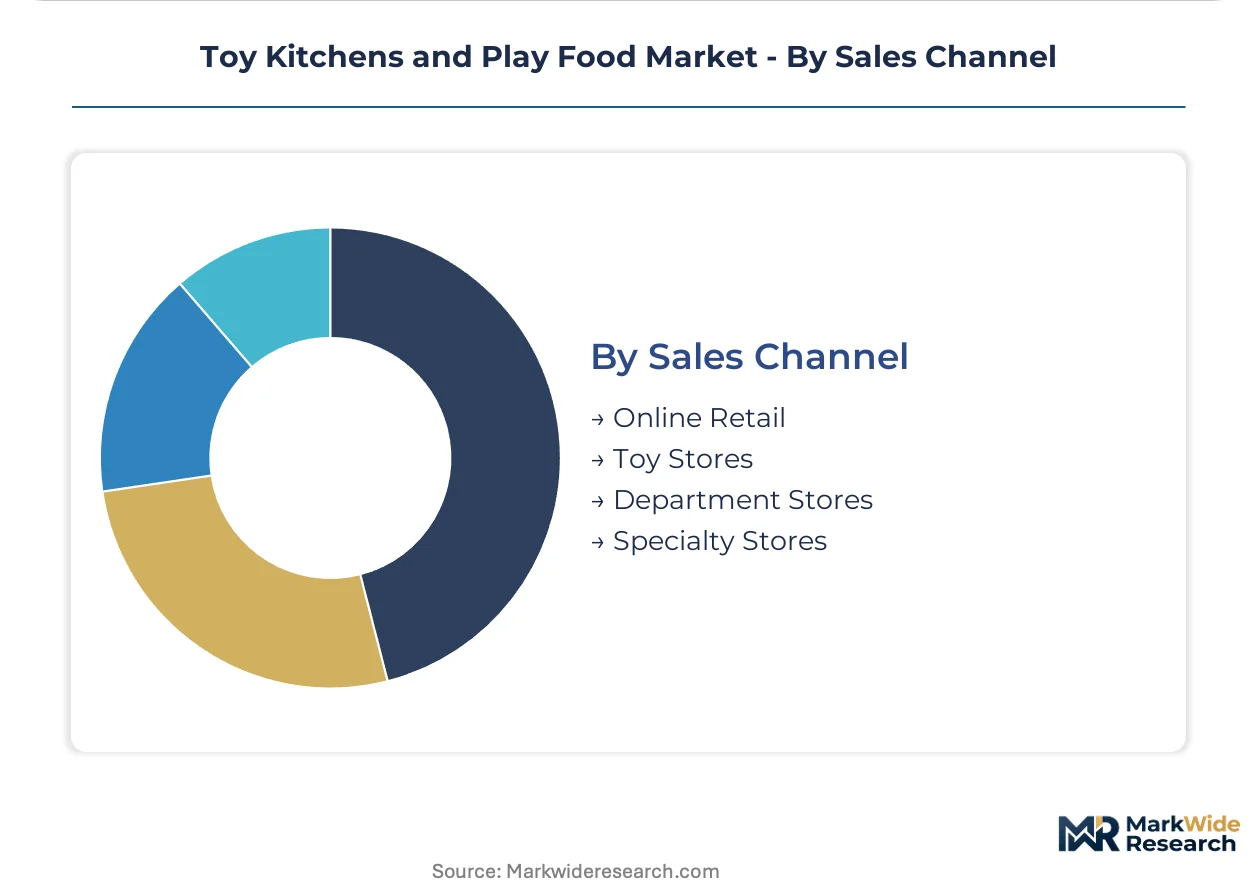
- Online Retail:Direct-to-parent platforms with quarterly rotation subscriptions are displacing traditional inventory ownership in United States metropolitan markets.
- Toy Stores:Mass-market chains maintain volume throughput through licensed character kitchen configurations and seasonal promotional cycles.
- Department Stores:Mid-tier wooden set assortments serve gift-purchase occasions with moderate price elasticity.
- Specialty Stores:Curated premium bamboo lines with artisan joinery credentials defend margin pools in European urban centers.
Transaction velocity concentrates in Online Retail; Specialty Stores retain the highest per-unit margin realization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in China's coastal provinces while consumption concentrates in wealthy Western markets with stringent chemical safety mandates. This production-consumption divide shapes logistics networks and certification requirements across the value chain.
United States
Preschool curriculum mandates for role-play stations are institutionalizing bulk procurement through early learning centers. ASTM F963 compliance requirements elevate testing costs but screen out uncertified imports. Los Angeles and New York metropolitan areas concentrate specialty retail distribution for premium wooden assortments.
Germany
Parental preference for heirloom-durable FSC-certified bamboo constructions sustains premium positioning in specialty channels. REACH Annex XVII phthalate restrictions are eliminating soft-PVC from infant-directed segments entirely. Bavaria hosts the densest concentration of artisan woodcraft workshops supplying joinery-intensive kitchen configurations.
China
Vertically controlled bamboo sourcing networks in Zhejiang province are compressing raw material lead times for sustainable wood product lines. GB standards compliance creates parallel certification burdens distinct from Western protocols. Guangdong province anchors injection-molded plastic volume production for mass-market export tiers.
France
Emerging extended producer responsibility frameworks are creating first-mover advantages for closed-loop material recovery systems. ANSM enforces chemical migration limits stricter than baseline EU requirements. Paris and Lyon metropolitan areas concentrate subscription-based toy rotation service adoption among space-constrained urban families.
Australia
Backyard entertainment trends are accelerating weather-resistant rotomolded outdoor kitchen penetration in suburban markets. TGA-aligned toy safety enforcement maintains rigorous surface coating and small parts testing. Sydney and Melbourne anchor direct-to-consumer platform growth for modular kitchen expansion sets.
Toy Kitchens and Play Food Market Competitive Landscape
The competitive structure tilts toward vertically integrated timber specialists and mass-market rotomolded plastic fabricators. Player concentration remains moderate with no dominant share holder, though specialty retail partnerships create regional moats for curated brands. Three archetypes define positioning: sustainable wood craftsmen, licensed character plastic molders, and hybrid digital-physical integrators. Capacity expansion in Zhejiang bamboo processing and strategic partnerships between Nordic design houses and Chinese manufacturing assets represent the dominant competitive vectors.
Among the sustainable wood archetype, Hape exemplifies vertically controlled supply chain positioning while Melissa & Doug occupies the specialty retail partnership tier. Little Tikes anchors mass-market rotomolded volume through weather-durable outdoor configurations. These three companies represent distinct competitive postures without implying specific strategic actions or market share claims.
| Leading Market Players |
|---|
| Lalo |
| IKEA |
| KidKraft |
| PoshPo |
| Melissa & Doug |
| Step2 |
| Little Tikes |
| FAO Schwarz |
| Hape |
| Others |
Value Network & Pricing Analysis
Polypropylene resin feedstock costs cascade through injection-molded kitchen component pricing, compressing margins at mass-market tiers while amplifying premiums for FSC-certified bamboo alternatives in German and United States specialty channels.
Pricing Analysis
Margin tightening in rotomolded outdoor configurations reflects polypropylene price volatility and UV-stabilizer additive costs. Three-tier pricing structure across premium heirloom wood, mid-market modular plastic, and economy licensed-character tiers separates buyers by durability expectations and certification sensitivity. REACH compliance investments elevate European price floors above United States mass-market baselines. Institutional procurement through United States preschools shows lowest price elasticity; subscription-based direct-to-consumer buyers exhibit highest sensitivity to quarterly rotation fees.
Supply Chain Analysis
Direct-to-specialty-retail channels handle premium bamboo kitchen demand through Bavarian artisan workshops and Zhejiang province vertically controlled sourcing clusters. Manufacturing concentrates in China's Guangdong injection-molding corridor and Fujian fine-woodworking regions, with raw material dependencies on Zhejiang bamboo plantations, Saudi petrochemical feedstocks, and German water-based finish formulations. Single-source vulnerability concentrates in aging artisan populations across Guangdong and Fujian provinces. Distribution runs through mass-market toy chains for volume, direct-to-parent platforms for urban subscription adopters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fine woodworking artisan scarcity across China's aging Guangdong and Fujian craft bases props premium-tier pricing, constraining heirloom-grade bamboo kitchen expansion regardless of downstream demand signals.
For Market Incumbents: Deepen backward integration into Zhejiang bamboo plantations to secure raw material priority against emerging biopolymer competitors. Invest in automated joinery equipment to offset artisan scarcity before capacity bottlenecks harden. Anchor specialty retail partnerships in German urban centers where REACH compliance creates defensible moats against uncertified imports. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription platforms targeting space-constrained United States metropolitan families with modular kitchen expansion sets. Exploit underpenetrated Australian outdoor kitchen segments where weather-resistant rotomolded demand outpaces incumbent supply. Prioritize bioplastic formulation partnerships to capture imminent polylactic acid cost parity moments. For Investors and Strategic Acquirers: Polylactic acid price convergence with conventional plastics is the leading indicator that biopolymer-based kitchen lines will achieve mass-market viability without margin sacrifice. Five-to-ten-year viability favors vertically integrated timber specialists with captive Zhejiang sourcing over pure-brand licensing plays. Monitor third-party laboratory capacity expansion in China as the signal for whether ASTM F963 certification timelines will normalize or remain extended.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bamboo Plantations | Captive Zhejiang sourcing secures raw material priority against biopolymer substitution threats. |
| Automated Joinery Equipment Deployment | Machine precision offsets Guangdong artisan scarcity constraining heirloom-grade production expansion. |
| Bioplastic Formulation Partnership | Polylactic acid readiness positions mass-market tiers for imminent cost parity transitions. |
| Direct-to-Consumer Subscription Launch | Quarterly rotation models capture urban United States families prioritizing storage-minimal consumption. |
| REACH Compliance Certification Investment | Phthalate-free credentials unlock German specialty retail channels blocking uncertified competitors. |
Research Methodology
Document review covered customs trade records, ASTM F963 certification databases, and ECHA REACH enforcement actions, complemented by interviews with toy manufacturing executives, early learning center procurement coordinators, specialty retail category buyers, and bamboo plantation operations managers across Zhejiang province. Secondary sources included Nielsen retail audit data for United States toy channels, EU Toy Safety Directive compliance registries, and Chinese GB standards documentation. Bottom-up demand modeling triangulated against top-down manufacturing capacity assessments.
Historical shipment volumes cross-referenced against panel input from preschool curriculum directors and subscription platform operators informed projection parameters. Segmentation dimensions spanned product type, age group, material composition, and sales channel across the analysis window. CAGRs derived from fitted growth curves applied to certified timber premium tier and injection-molded mass-market tier separately. Forecast inputs incorporated bioplastic substitution elasticity estimates and extended producer responsibility framework adoption timelines.
The model assumes a particular technology adoption path for near-field communication chip integration; alternative pathways for analog-digital hybrid play would alter the outlook for school-aged segment replacement cycles. Forecasts reflect base-case assumptions regarding REACH enforcement stringency and artisan labor availability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Toys and Games
Air Hockey Table Market
Toys and Games
Die-Cast Toys Market
Toys and Games
Indoor Soft Play Market
Toys and Games
Drone for Kids Market
Toys and Games
Kids Fuse Beads Market
Toys and Games
Games and Puzzles Market
Toys and Games
Global Educational Toy Market
Toys and Games
Robot Toys for Children Market
Toys and Games
United States Toys Market
Toys and Games
Ferret Toys Market
Toys and Games
Anime Figure Blind Box Market
Toys and Games
Glow Sticks Market
Toys and Games
Eco-Friendly Toys Market
Toys and Games
Coaster Market
Toys and Games
Toys and Games Market
Toys and Games
Traditional Toys and Games Market