
 Wooden Toys Market | 2026-2036
Wooden Toys Market Size, Share, and Industry Trends Forecast 2026-2036
Wooden Toys Market Intelligence
A shift toward sustainably-sourced and certified wood is rotating the market toward higher-value, premium product categories. This emphasis on eco-friendly materials and transparent, ethical production creates clear differentiation opportunities for specialized brands. Hape International specializes in toys made from bamboo and other sustainable materials, anchoring its brand in environmental responsibility. Melissa & Doug leverages its strong brand recognition and extensive distribution network to compete across both specialty and mass-market channels.
Wooden toys are playthings constructed from natural woods like beech, maple, and rubberwood, finished with non-toxic, water-based paints to ensure child safety. Their core purpose is to facilitate open-ended, imaginative play while supporting the development of cognitive, sensory, and fine motor skills. Analysis of product types shows building blocks and puzzles remain foundational categories that drive significant market volume. The preschooler and toddler age groups constitute the primary consumer base, with sales channels seeing a definitive shift toward online retailers.
Product safety and material standards are governed by stringent regulatory frameworks that vary by geography. The EU's Toy Safety Directive, enforced via CE marking, and Consumer Product Safety Commission standards in the United States mandate rigorous testing. These regulations directly impact material selection, manufacturing processes, and supply chain verification. Future vendor success hinges on managing certified wood procurement and communicating safety credentials to an increasingly discerning consumer base.
Market Dynamics
The primary structural force is a consumer-led pivot toward educational and sustainable play, directly influenced by stringent safety standards. This dynamic favors certified, non-toxic materials, concentrating demand on premium, developmentally-focused product segments over mass-market plastics.
Growth Catalysts
- Regulatory Mandates:The EU's Toy Safety Directive, enforced via CE marking, mandates rigorous testing for toxins, favoring certified wooden toys over many plastic alternatives.
- Educational Philosophy Adoption:The expansion of Montessori methods in preschools boosts demand for tactile, open-ended materials like wooden blocks and puzzles.
- Sustainable Sourcing:Consumer preference in Germany and Sweden for products with Forest Stewardship Council (FSC) certification supports the premium wooden toy segment.
Market Restraints
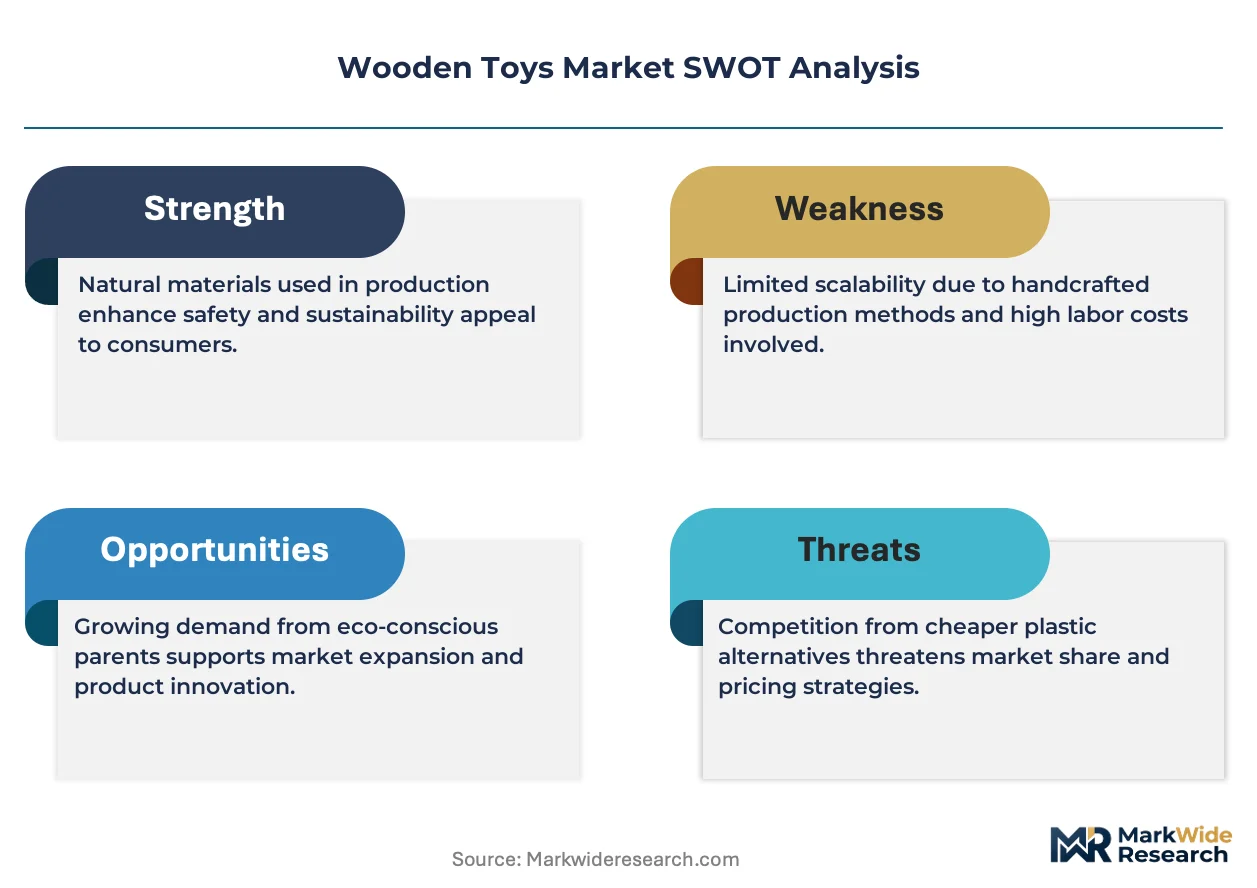
- Higher Production Costs:Certified hardwoods like beech and non-toxic paints have a higher cost basis than plastics, limiting price competitiveness in mass-market channels.
- Raw Material Volatility:Dependence on specific woods like rubberwood introduces supply risks tied to forestry yields and logistics from key Southeast Asian producers.
- Competition from Substitutes:Low-cost plastic toys featuring licensed characters dominate mass-market retail, presenting a significant substitution threat and limiting shelf space.
Strategic Opportunities
- Emerging Market Penetration:Expanding into middle-class markets in Brazil and India, where consumer spending on educational children's products is increasing.
- Hybrid "Smart" Toys:Integrating simple electronic components for light and sound into traditional wooden designs to create a new product category.
- Direct-to-Consumer Models:Launching curated subscription boxes that deliver age-appropriate toys, bypassing traditional retail and building recurring revenue.
Industry Challenges
- Complex Compliance Burden:Managing different testing protocols and documentation required by the EU's CE marking and US Consumer Product Safety Commission standards is costly and time-consuming.
- Counterfeit Product Proliferation:The growth of third-party sellers on online marketplaces facilitates the sale of low-quality, unsafe counterfeit wooden toys, eroding consumer trust and brand value.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wooden Toys Market |
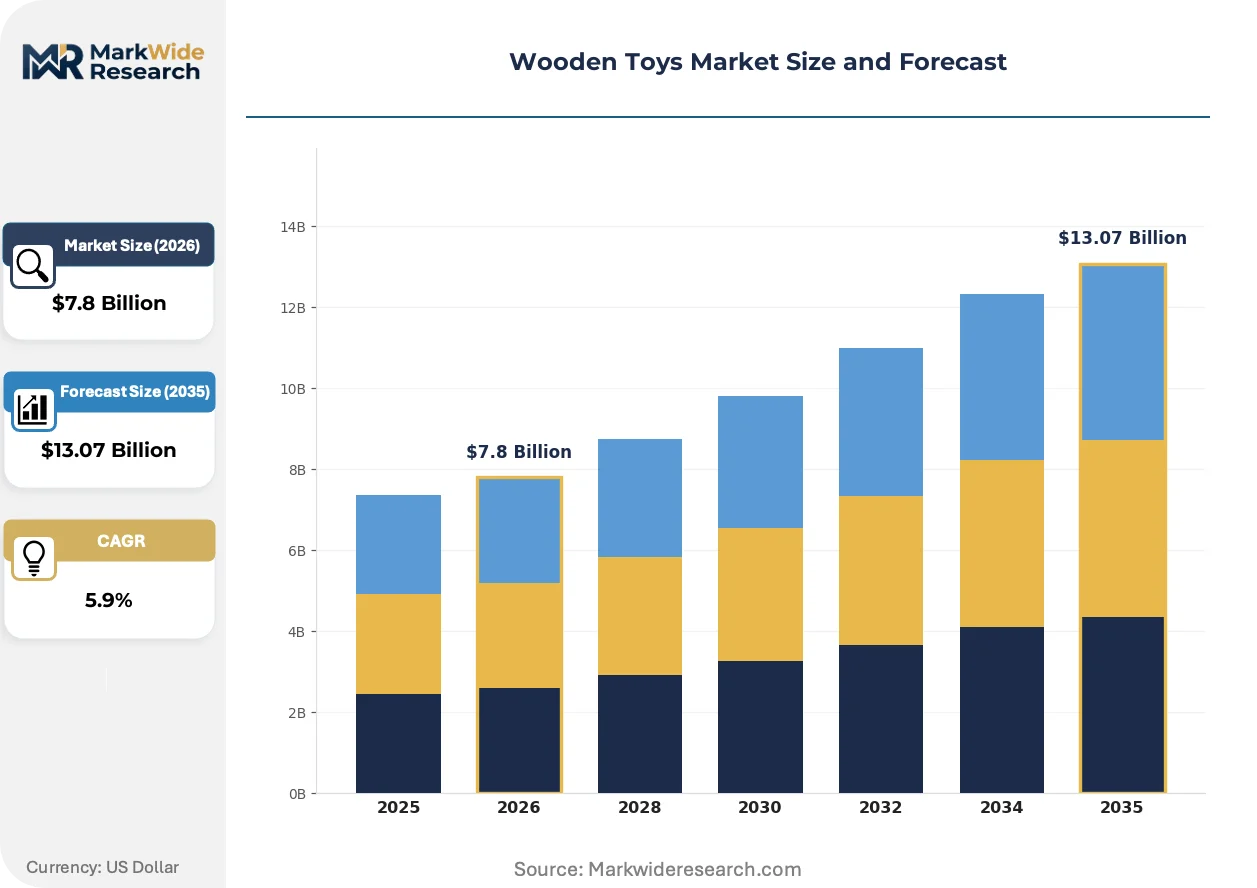
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.07 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Building Blocks, Puzzles, Ride-On Toys, Educational Kits, Dollhouses, Art & Craft Sets Age Group: Infants, Toddlers, Preschoolers, Early School Age, Tweens Material Type: Beech Wood, Maple Wood, Pine Wood, Rubberwood, Bamboo, Teak Wood Sales Channel: Specialty Stores, Online Retailers, Toy Wholesalers, Department Stores, Gift Shops |
| Companies Covered | KidKraft, Tegu, Melissa & Doug, Fisher-Price, Bigjigs Toys, Hape International, BRIO AB, Wonderworld Toys, PlanToys, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wooden Toys Market Strategic Shifts & Innovations
Material innovation and digital integration are reshaping product development in the wooden toy sector. The market is moving beyond simple passive playthings toward items that blend natural aesthetics with enhanced developmental and interactive features.
Embedded electronic modules are adding simple interactive elements like sounds and lights to traditional wooden toys. Parents seeking a balance between digital and physical play are adopting these hybrid products for preschoolers. This integration of micro-components is miniaturizing the "smart toy" concept, embedding technology invisibly within natural materials rather than creating a separate device.
Heightened enforcement by the United States Consumer Product Safety Commission (CPSC) on standards for lead and phthalates is a key regulatory driver. This compels manufacturers to maintain meticulous supply chain documentation and conduct third-party testing for all paints and finishes. The regulation most impacts smaller importers, who must now invest heavily in compliance verification to access the US market.
Consumer purchasing behavior is shifting from event-driven, one-time buys to subscription-based models for developmental products. This trend disrupts the dominance of large toy stores and general e-commerce platforms by favoring specialized direct-to-consumer services. The model, most visible among millennial parents in North American and European cities, provides curated, age-appropriate wooden toys on a recurring basis.
Wooden Toys Market Segmentation
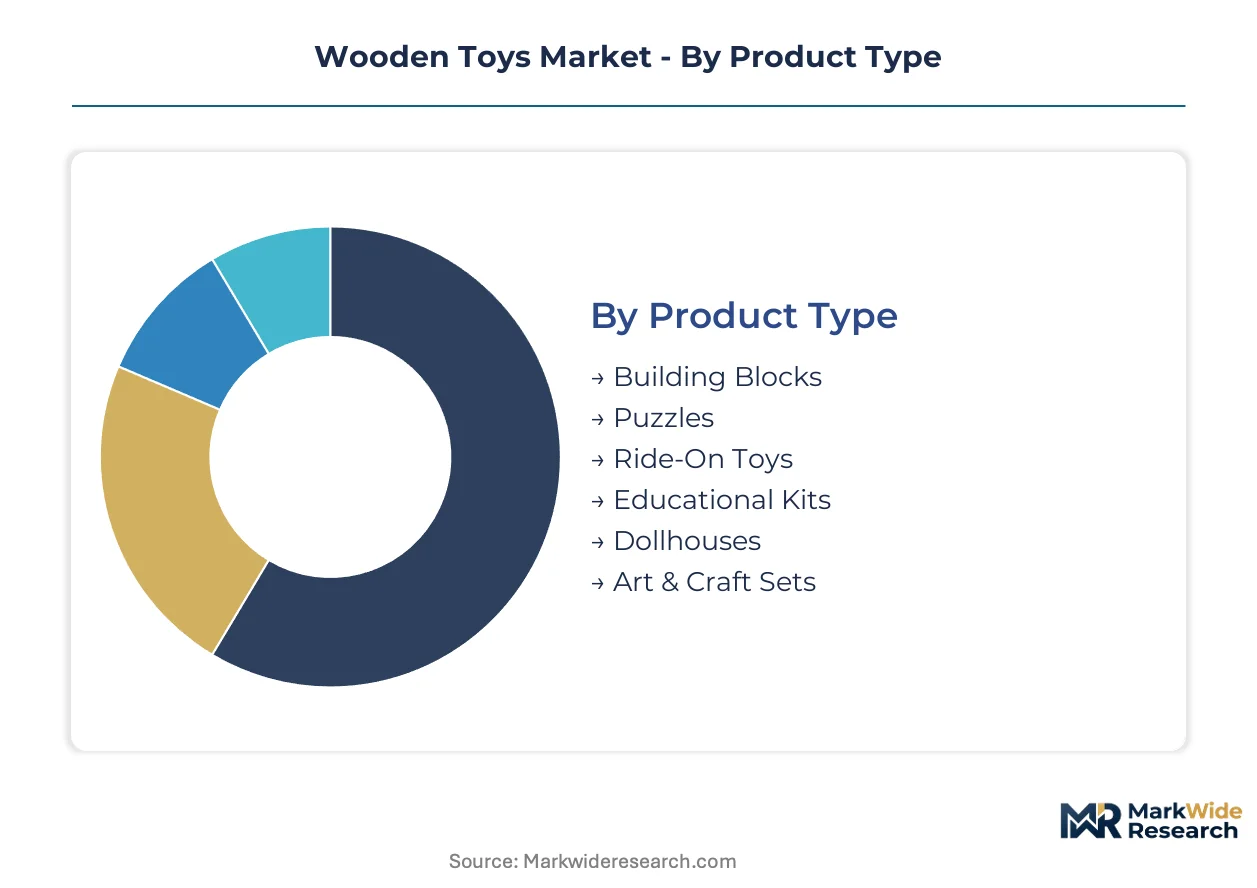
Market segmentation for wooden toys delineates distinct consumer preferences and operational dynamics that influence product development and distribution strategies. Understanding these segments helps companies tailor offerings to specific age groups, material choices, and purchasing channels. This granular analysis is crucial for identifying areas of concentrated demand and optimizing resource allocation within the wooden toy sector.
Product Type:
Margin pools for wooden toys often concentrate in product types that offer complex developmental benefits or premium craftsmanship.
- Building Blocks:These foundational sets facilitate open-ended construction and creative play, frequently crafted from solid beech or maple wood. Demand is consistently high in preschools and Montessori centers due to their proven benefits for cognitive and fine motor skill development.
- Puzzles:Ranging from simple knob puzzles for toddlers to intricate multi-piece jigsaws for older children, these are typically made from plywood or solid wood. Demand is strong within educational kits for preschoolers, supporting problem-solving abilities and hand-eye coordination.
- Ride-On Toys:Durable wooden structures designed to support gross motor skill development and balance in young children.
- Educational Kits:Curated collections combining various wooden elements to teach specific concepts like numbers, letters, or early science.
- Dollhouses:Intricate miniature structures, often handcrafted, fostering imaginative role-play and narrative development.
- Art & Craft Sets:Wooden components for creative activities, such as painting, stamping, or building small decorative models.
Building Blocks holds installed capacity. Puzzles is rotating up the share rankings.
Age Group:
Application-specific design considerations drive differentiation across various age groups, impacting material choices and safety features.
- Toddlers:Toys designed for children aged 1-3 emphasize safety, durability, and the development of gross motor skills and sensory exploration. Demand is particularly high for push-pull toys and simple stackers in Western Europe, where early childhood development is a priority.
- Preschoolers:Products for children aged 3-5 focus on cognitive development, imaginative play, and refining fine motor skills through more complex interactions. Demand is significant for building sets and role-play items, especially with the global expansion of educational philosophies.
- Infants:Soft-edged, non-toxic wooden toys suitable for early sensory exploration and safe mouthing.
- Early School Age:More complex puzzles, construction sets, and craft kits that challenge developing minds.
- Tweens:A niche market for intricate models, brain teasers, or advanced craft kits appealing to older children.
The Toddlers segment maintains significant market volume. Preschoolers represents the fastest-growing trajectory.
Material Type:
Supply concentration for specific wood types directly influences production costs and sustainability claims within the market.
- Beech Wood:A dense, fine-grained hardwood known for its exceptional durability and smooth finish, making it ideal for high-quality, long-lasting toys. Demand is strong in Germany and Scandinavia due to its aesthetic appeal and compliance with stringent safety standards.
- Rubberwood:A sustainable hardwood sourced from rubber tree plantations, offering good strength, workability, and a light color. Demand is prevalent in mass-produced wooden toys due to its eco-friendly credentials and lower cost basis from key Southeast Asian producers.
- Maple Wood:Hard, light-colored wood valued for its strength and resistance to splintering, often used in premium, heirloom-quality toys.
- Pine Wood:A softer, more affordable wood, frequently utilized for larger, less intricate wooden toy components and structures.
- Bamboo:A rapidly renewable material offering a lightweight and eco-conscious alternative for various toy constructions.
- Teak Wood:Durable, water-resistant wood, less common for toys due to cost, but used for specialized or outdoor wooden items.
Beech Wood commands premium pricing. Rubberwood drives significant volume.
Sales Channel:
Customer purchasing behavior dictates the effectiveness of various sales channels, favoring convenience and specialized product access.
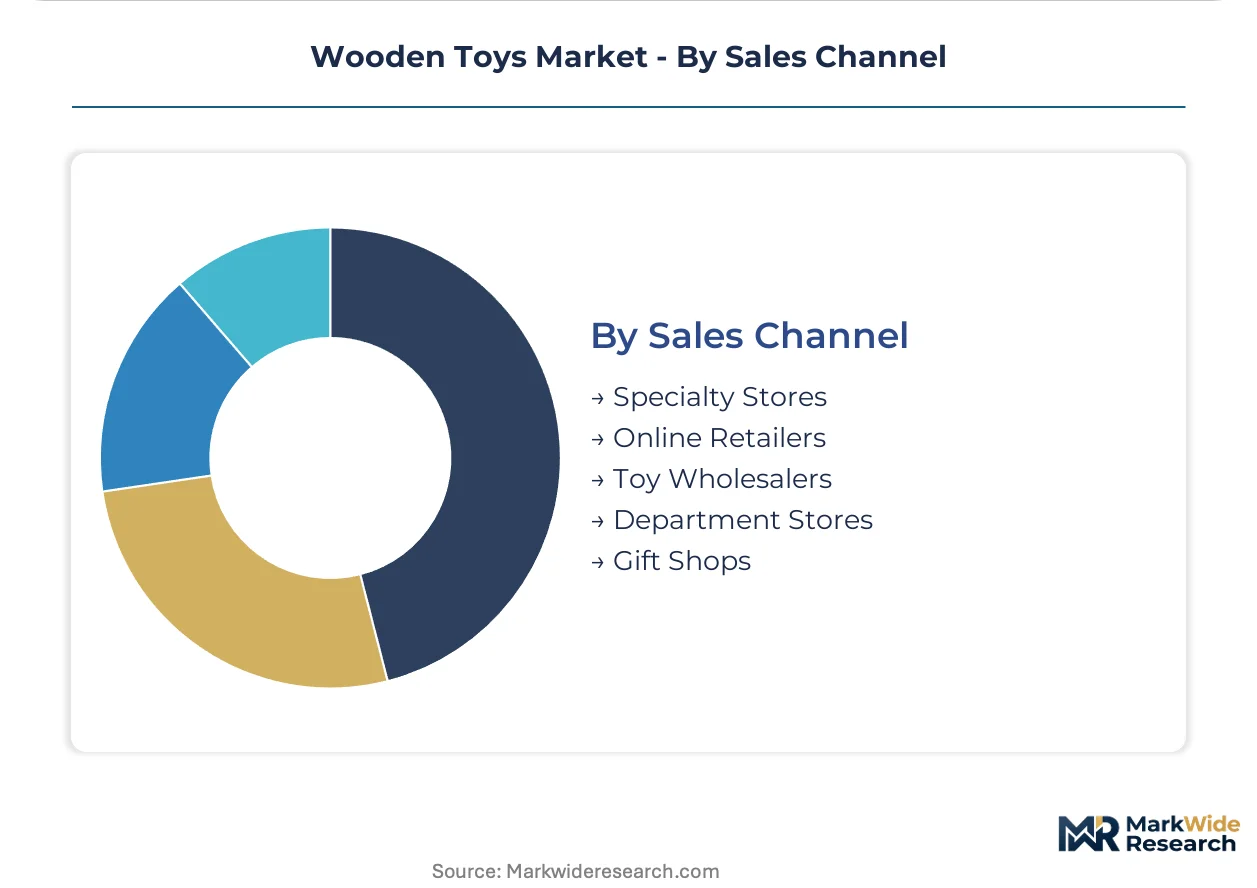
- Online Retailers:E-commerce platforms provide extensive product catalogs, price comparison tools, and direct-to-consumer shipping options. Demand is accelerating globally, particularly among millennial parents in urban centers seeking curated, sustainable toy options.
- Specialty Stores:Brick-and-mortar outlets offering curated selections, product expertise, and often community engagement events. Demand remains robust in Northern European countries where consumers value personalized service and unique, high-quality wooden toys.
- Toy Wholesalers:Intermediaries distributing large volumes of wooden toys to various retail outlets, including smaller independent stores.
- Department Stores:Large retail chains offering a broad range of products, typically including a dedicated toy section with established brands.
- Gift Shops:Smaller retail spaces focusing on unique, often artisanal, wooden toys suitable for special occasions or souvenirs.
Specialty Stores historically dominated distribution. Online Retailers are rapidly gaining market share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentration for certified hardwoods and non-toxic paints significantly influences the global wooden toy market. This dynamic shapes pricing structures and availability across key consumer geographies. Manufacturers navigate diverse regulatory landscapes to meet sustainability and safety demands.
Germany
German consumers demonstrate robust demand for premium, sustainably sourced wooden toys. The EU Toy Safety Directive, enforced via CE marking, mandates rigorous testing, favoring certified materials. Berlin and Munich-based specialty retailers anchor demand for heirloom-quality products, emphasizing educational value.
Sweden
Swedish parents prioritize eco-friendly and developmental playthings, driving strong demand for wooden toys. Forest Stewardship Council (FSC) certification supports the premium segment, aligning with national environmental policies. Stockholm and Gothenburg act as centers for innovative design and direct-to-consumer models.
United States
American households increasingly seek wooden toys for their developmental benefits and safety attributes. The Consumer Product Safety Commission (CPSC) standards on lead and phthalates compel meticulous supply chain documentation. New York and California metropolitan areas lead adoption of subscription-based models for curated children's products.
Brazil
Brazilian middle-class families show rising interest in educational children's products, boosting wooden toy sales. ANVISA, the national health surveillance agency, oversees product safety and material compliance for imported goods. São Paulo and Rio de Janeiro represent key urban centers for market penetration and retail expansion.
India
Indian parents are increasingly investing in durable and educational toys for early childhood development. The Bureau of Indian Standards (BIS) establishes quality and safety benchmarks for toys sold domestically. Bengaluru and Mumbai serve as growing hubs for online retailers catering to discerning consumers.
Wooden Toys Market Key Industry Players
Concentration sits with established brands leveraging extensive distribution networks and strong consumer trust. The market structure exhibits a tiered consolidation, featuring global brand leaders and specialized niche manufacturers. Key archetypes include those focused on mass-market accessibility and those emphasizing premium, sustainable offerings. Dominant competitive moves involve portfolio diversification into educational kits and strategic geographic expansion into emerging markets.
Within the global brand leader archetype, Melissa & Doug leverages its strong brand recognition and extensive distribution network across both specialty and mass-market channels. This company represents a broad appeal across diverse consumer segments. Hape International exemplifies the eco-conscious specialist, anchoring its brand in environmental responsibility with toys made from bamboo and other sustainable materials. This approach resonates with consumers prioritizing sustainable sourcing. Similarly, BRIO AB, a Swedish company, occupies a position focused on classic design and durable wooden products, appealing to consumers seeking heirloom quality and traditional play experiences.
| Leading Market Players |
|---|
| KidKraft |
| Tegu |
| Melissa & Doug |
| Fisher-Price |
| Bigjigs Toys |
| Hape International |
| BRIO AB |
| Wonderworld Toys |
| PlanToys |
| Others |
Cost & Logistics Intelligence
Long-term procurement contracts for certified wood lock in both supply access and price visibility for premium wooden toy manufacturers. This structure insulates them from short-term commodity fluctuations.
Pricing Analysis
The EU Toy Safety Directive dictates the pricing tier structure for wooden toys, mandating rigorous testing that adds cost. Value-based pricing dominates the premium segment, driven by FSC certification and heirloom quality. Price differentiation stems from material grade and brand reputation. Cost compression in mass-market channels is intensifying due to competition from lower-priced plastic alternatives. Mass-market consumers exhibit higher price sensitivity, while discerning parents in Northern Europe prioritize safety and sustainability over cost.
Supply Chain Analysis
Southeast Asian countries, particularly Malaysia and Thailand, anchor rubberwood production, a key material for wooden toys. The supply chain draws from specific woods like beech, maple, and rubberwood, alongside non-toxic, water-based paints. A structural risk involves raw material volatility tied to forestry yields and logistics from these key producers. Downstream distribution primarily runs through online retailers and specialized brick-and-mortar stores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wooden toys market exhibits a capability scarcity in navigating complex, multi-jurisdictional product safety and material certification. This gap creates both barriers and opportunities for market participants.
For Market Incumbents: Secure long-term contracts with certified wood suppliers to mitigate raw material volatility. Diversify product portfolios into hybrid "smart" wooden toys to counter competition from purely digital alternatives. Invest in robust digital platforms to enhance direct-to-consumer engagement and combat counterfeit product proliferation. This approach reinforces brand trust and market share against mass-market plastic substitutes.
For New Entrants and Emerging Players: CE marking fast-track programs offer a pathway to market entry for innovative wooden toy designs. Target the rapidly growing subscription box segment for preschoolers in North American and European urban centers. Focus on educational kits for middle-class families in emerging markets like Brazil and India. A direct-to-consumer online model with transparent sustainability credentials provides a strong go-to-market angle.
For Investors and Strategic Acquirers: Niche manufacturers specializing in FSC-certified wooden toys or Montessori-aligned educational products present attractive acquisition targets. The long-term viability of this market is underpinned by sustained consumer preference for safe, sustainable, and developmental play. A signal to watch is the increasing enforcement of toy safety regulations in previously under-regulated emerging markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Deepen Supply Chain Transparency | Ensures compliance with stringent safety regulations and builds consumer trust in product origins. |
| Expand Hybrid "Smart" Toy Portfolio | Captures demand from parents seeking a balance between digital and physical developmental play. |
| Launch Curated Subscription Boxes | Establishes recurring revenue streams and bypasses traditional retail channels for direct engagement. |
| Obtain FSC Certification for All Products | Reinforces brand positioning in the premium, eco-conscious segment, particularly in Northern Europe. |
| Penetrate Emerging Middle-Class Markets | Accesses new consumer bases with growing disposable income and demand for educational children's products. |
Research Approach
Desk research of regulatory documents, trade association reports, and company financial filings preceded structured interviews with toy manufacturers' R&D heads, specialty store owners, and regulatory compliance officers. This approach combined primary insights with secondary validation from sources like the EU Toy Safety Directive and national trade statistics. Bottom-up data collection was triangulated with top-down market sizing for comprehensive coverage.
Variance decomposition of market growth drivers underpins the forecast framework, analyzing contributions from product innovation and regional demand shifts. Market segmentation dimensions modeled include product type, age group, material type, and sales channel across the analysis window. Compound annual growth rates were derived from historical trends and projected future demand. Key forecast inputs include adoption rates of educational philosophies and consumer preference for sustainable materials.
Decision-makers should treat outputs as directional under assumptions of a stable regulatory environment and consistent consumer focus on child safety; material deviation would warrant model refresh. Forecasts reflect these base assumptions and current market dynamics. Unforeseen shifts in raw material supply or rapid changes in international toy safety regulations represent key risk factors. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Toys and Games
Remote Control Products - Hobby Market
Toys and Games
Bath Toy Market
Toys and Games
Global Fidget Toys Market
Toys and Games
Global Educational Toy Market
Toys and Games
Male Sex Toys Market
Toys and Games
China Playing Cards & Board Games Market
Toys and Games
Toy Kitchens and Play Food Market
Toys and Games
Dildo Sex Toy Market
Toys and Games
LAMEA Action Figure Toys Market
Toys and Games
Toy Collectibles Market
Toys and Games
Air Hockey Table Market
Toys and Games
Table Top Games Market
Toys and Games
Indoor Soft Play Market
Toys and Games
Dartboard Market
Toys and Games
Smart/AI Toys Market
Toys and Games
Cat Toys Market