
 Kids Toys Market | 2026-2036
Kids Toys Market Size, Share, and Industry Trends Forecast 2026-2036
Kids Toys Market Analysis
The gap between premium collectible-grade toys and mass-market commodity playthings is shifting toward design complexity and material traceability rather than price alone. The LEGO Group leverages its captive resin-molding facilities and in-house polymer science labs to sustain margin control across European and Asian markets. Mattel anchors its competitive stance through deep licensing partnerships with entertainment studios, while Spin Master differentiates via rapid design-to-shelf cycles in the action figure segment.
Kids toys encompass manufactured play objects engineered from polymers, timber, textiles, or alloys, designed to stimulate cognitive, motor, or social development in children from infancy through early adolescence; specifications cover tensile strength, phthalate thresholds, and small-part choking hazards under ISO 8124 and ASTM F963 protocols. Educational toys command expanding shelf space as parents prioritize STEAM-aligned skill building, while plastic-based products face margin compression from petroleum feedstock volatility and regulatory scrutiny on additive chemistries. Online retail channels are capturing volume growth from subscription-box models and direct-to-parent influencer marketing, though toy stores retain destination status for experiential purchasing.
The US Consumer Product Safety Commission enforces mandatory third-party testing under the Consumer Product Safety Improvement Act, while the EU REACH regulation restricts cadmium and lead content in polymer substrates, and China's SAMR administers the GB 6675 national standard series for mechanical and flammatory properties. These frameworks elevate compliance costs for smaller exporters but create barriers that favor scaled manufacturers with dedicated certification teams. Stakeholders must monitor evolving chemical restriction lists and digital privacy rules for connected toys to anticipate which product categories will face exclusion or accelerated redesign cycles.
Market Dynamics
Parental prioritization of STEAM-aligned skill development is redistributing shelf space toward educational play objects, while polymer feedstock volatility and China's GB 6675 safety enforcement compress margins for commodity manufacturers lacking captive resin supply.
Growth Catalysts
- EU REACH chemical restrictions:Cadmium and phthalate thresholds in polymer substrates are accelerating material substitution toward bio-based alternatives, creating first-mover advantage for certified suppliers.
- Guangdong manufacturing cluster concentration:Integrated mold-making and component assembly ecosystems in southern China reduce design-to-tooling lead times for export-oriented producers.
- Subscription-box direct-to-parent models:Curated monthly toy deliveries bypass traditional retail markups while capturing recurring revenue streams and granular consumption data.
Market Restraints
- Petroleum-based resin price volatility:Crude oil fluctuations directly compress margins for ABS and polypropylene-dependent product lines without long-term supply contracts.
- Third-party testing cost escalation:US Consumer Product Safety Improvement Act mandates elevate compliance burdens disproportionately for sub-scale exporters lacking in-house certification teams.
- Digital screen substitutes:Tablet and smartphone applications displace traditional physical play time among school-age demographics in urban households.
Strategic Opportunities
- India's organized retail corridor expansion:Modern trade formats in Mumbai, Delhi, and Bangalore create branded shelf space previously dominated by unorganized local manufacturers.
- Connected toy digital privacy rule evolution:Anticipatory compliance with emerging data protection frameworks positions vendors for category leadership as voice-enabled and app-integrated products proliferate.
- Timber-textile hybrid material convergence:FSC-certified wood combined with organic cotton addresses parental skepticism toward petroleum-derived polymers in infant and toddler segments.
Industry Challenges
- Polymer science talent scarcity:Formulation chemists capable of balancing mechanical durability with phthalate-free compliance command premium compensation in competitive labor markets.
- Multi-jurisdiction certification timeline compression:Simultaneous pursuit of ASTM F963, ISO 8124, and GB 6675 approvals strains quality assurance bandwidth during seasonal product launches.
- Licensing agreement renegotiation complexity:Entertainment studio IP holders increasingly demand revenue participation and minimum volume guarantees that constrain design flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kids Toys Market |
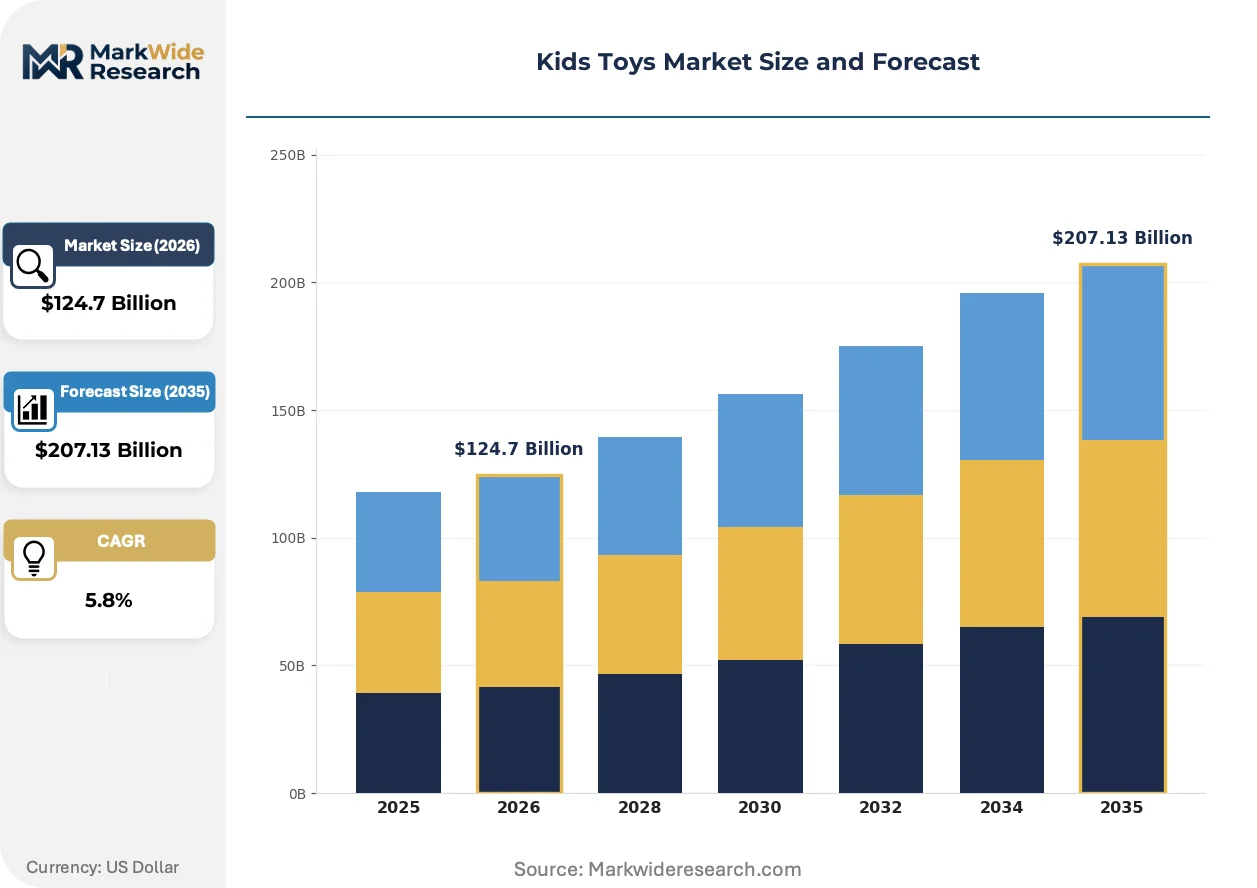
| Market Size in 2026 | $124.7 Billion |
| Market Size in 2035 | $207.13 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Action Figures, Dolls, Vehicles, Educational Toys Age Group: Infants, Toddlers, Preschoolers, School Age Material: Plastic, Wood, Fabric, Metal Sales Channel: Online Retail, Toy Stores, Department Stores, Discount Retailers |
| Companies Covered | Hasbro, MGA Entertainment, The LEGO Group, Jakks Pacific, TOMY Company, Bandai Namco, Spin Master, Funko, Mattel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kids Toys Market Emerging Trajectories
Computational design tools and material science advances are compressing prototyping cycles while regulatory chemical restrictions and direct-to-parent distribution models simultaneously reshape competitive positioning.
AI-assisted generative design software is automating topology optimization for interlocking plastic components, reducing mold iteration counts from twelve to three for complex building sets. Mid-tier manufacturers in Zhejiang province are adopting these cloud-based platforms to narrow the engineering gap with vertically integrated competitors. The technology is automating geometric stress-testing that previously required weeks of physical prototyping, collapsing development timelines for seasonal product releases.
China's SAMR enforcement of updated GB 6675 mechanical and flammability standards is forcing redesigns of battery-compartment access mechanisms across the remote-control vehicle segment. Domestic manufacturers in Shantou and Chenghai districts are consolidating supplier relationships to ensure batch-level traceability for polymer sourcing. The regulation most acutely affects small-motorized toys exported to European markets where REACH alignment creates dual-compliance pressure.
Parents are prioritizing open-ended play patterns over single-purpose electronic features, redirecting procurement toward modular construction systems and craft kits. Specialty toy stores in Germany and France are responding with experiential in-store demonstration zones that online channels cannot replicate. This behavioral pivot is most pronounced among millennial caregivers in Scandinavian markets where sustainability certifications influence purchase decisions at parity with price.
Kids Toys Market Segmentation
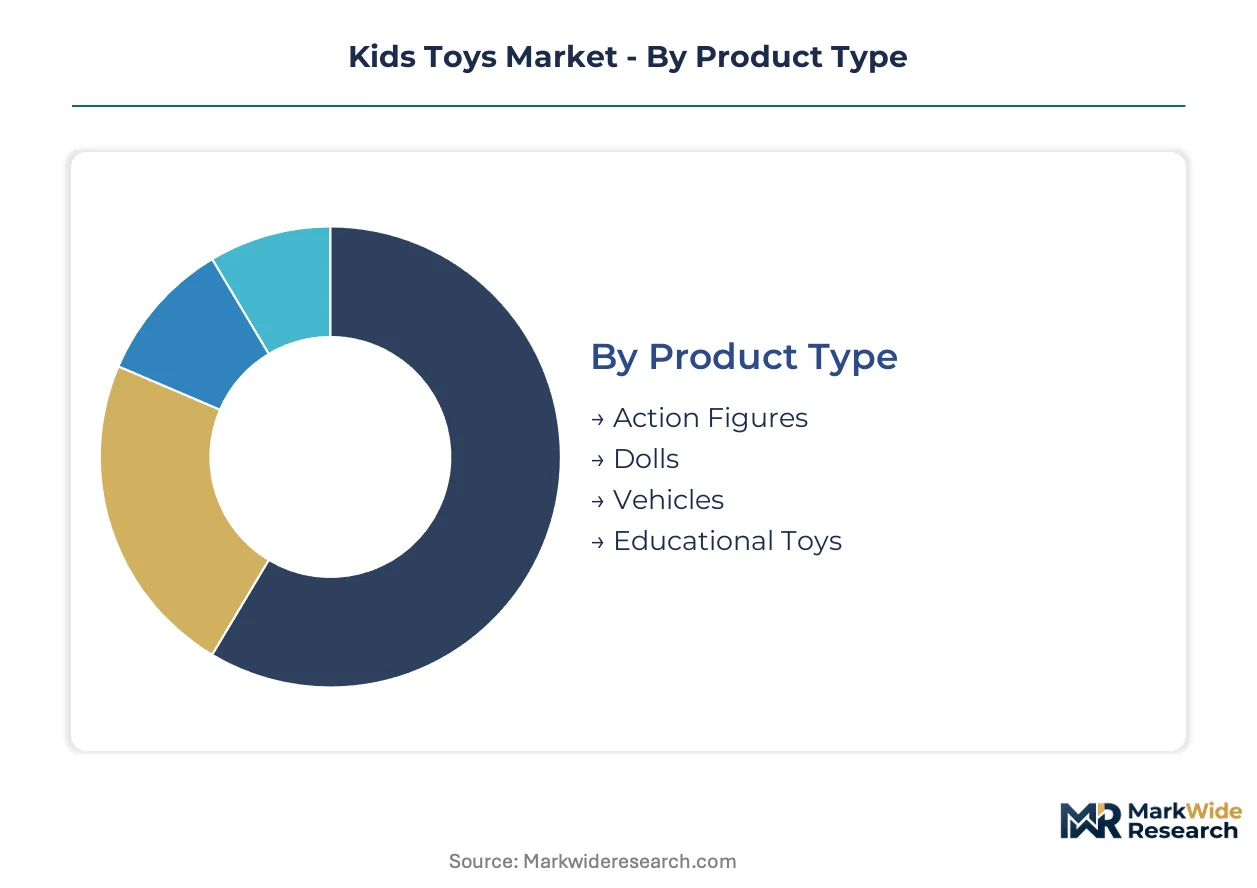
Segmentation in the Kids Toys Market reveals how material specifications, age-appropriate design protocols, and channel economics fragment procurement patterns. Manufacturers configure production lines around these axes to align with divergent safety standards and margin structures.
Product Type:
Product specifications determine mold complexity, licensing requirements, and inventory turnover velocity across manufacturing facilities.
- Action Figures:Articulated joints and accessory ecosystems demand precision injection molding with ABS and PVC blends. Demand concentrates in North American collector markets and Southeast Asian export manufacturing where entertainment licensing agreements drive SKU proliferation.
- Dolls:Rooted hair implantation and textile garment integration require hybrid assembly lines combining polymer molding with sewing operations. European Union REACH compliance on phthalate content elevates material costs for hair fiber and skin-tone polymers.
- Vehicles:Die-cast metal chassis and remote-control electronics span multiple production disciplines.
- Educational Toys:STEAM-aligned construction sets and coding kits prioritize modular design for skill progression.
Educational Toys leads on scale; Action Figures leads on momentum.
Age Group:
Developmental psychology research shapes safety thresholds and cognitive complexity benchmarks for each demographic band.
- Infants:Rounded geometries and single-piece construction eliminate choking hazards under ISO 8124 small-part protocols. German and French specialty retailers command premium positioning for organic cotton and FSC-certified wood offerings.
- Toddlers:Gross motor stimulation through push-pull mechanisms and stacking systems dominates design briefs. China's GB 6675 mechanical testing requirements for drop resistance and torque strength filter out subscale suppliers.
- Preschoolers:Symbolic play and early numeracy features expand average selling prices in organized retail channels.
- School Age:Competitive gaming and collectible dimensions extend product lifecycles through community-driven demand.
Infants commands margin premiums; Preschoolers shows steepest expansion trajectory.
Material:
Feedstock sourcing and regulatory chemistry compliance differentiate cost structures and brand positioning.
- Plastic:Polypropylene and ABS formulations offer color consistency and impact resistance for high-volume production. Petroleum price volatility compresses margins for manufacturers lacking long-term resin contracts with Sinopec or Saudi Aramco suppliers.
- Wood:FSC chain-of-custody certification addresses parental skepticism toward synthetic materials in Nordic and German markets. CNC routing and laser engraving enable mass customization previously restricted to artisan production.
- Fabric:Organic cotton and recycled polyester blends serve plush and textile-based play patterns.
- Metal:Zinc alloy die-casting supports vehicle chassis and structural components requiring heft and durability.
Plastic dominates unit economics; Wood gains share fastest on sustainability positioning.
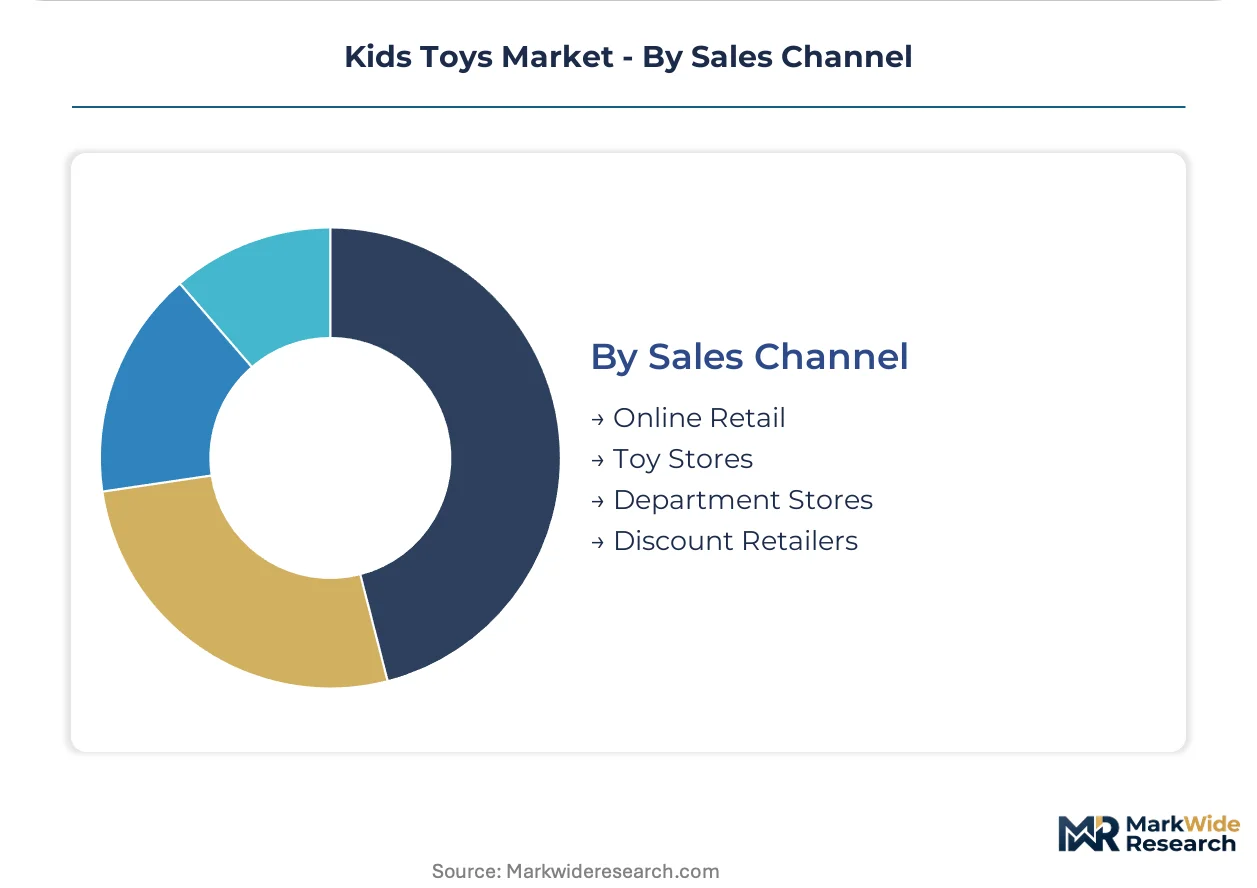
Sales Channel:
Channel configuration determines pricing architecture, return logistics, and customer data capture capabilities.
- Online Retail:Direct-to-parent subscription models and algorithmic recommendation engines bypass wholesale markups. Amazon and specialized toy platforms capture granular consumption data for predictive inventory positioning.
- Toy Stores:Experiential demonstration zones and seasonal inventory depth sustain destination status despite digital competition. Hamleys and specialty chains in London and Paris anchor brand discovery for premium positioning.
- Department Stores:Curated toy departments within broader retail footprints serve gift-purchase occasions.
- Discount Retailers:Volume commitments and simplified packaging specifications serve price-sensitive mass markets.
Online Retail captures volume growth; Toy Stores defends margin through experience differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer science talent pools in Germany, China, and the United States anchor the industry's technical workforce, with formulation chemists commanding premium compensation across these manufacturing centers.
United States
Millennial parental prioritization of STEAM-aligned educational toys and subscription-box direct-to-parent models drive procurement shifts. The Consumer Product Safety Commission enforces mandatory third-party testing under the Consumer Product Safety Improvement Act. Los Angeles and New York media corridors concentrate entertainment licensing negotiations that shape action figure and doll development cycles.
Germany
Scandinavian-influenced sustainability preferences elevate demand for FSC-certified wood and organic cotton offerings in infant segments. ECHA administers REACH chemical restrictions on cadmium and phthalate thresholds in polymer substrates. Nuremberg and Stuttgart specialty retail clusters sustain experiential toy store formats that online channels cannot replicate.
China
Guangdong province's integrated mold-making ecosystems reduce design-to-tooling lead times for export-oriented producers. SAMR enforces updated GB 6675 national standards for mechanical and flammability properties. Shantou and Chenghai districts consolidate supplier relationships to ensure batch-level polymer traceability for dual-compliance with REACH-aligned European markets.
India
Organized retail expansion in Mumbai, Delhi, and Bangalore creates branded shelf space previously dominated by unorganized local manufacturers. BIS certification requirements for toy safety elevate entry barriers for sub-scale domestic producers. Tamil Nadu and Maharashtra emerging manufacturing corridors attract contract molding investments serving Middle East export demand.
Japan
Collector-grade quality expectations sustain premium positioning for precision-articulated action figures and character goods. METI oversees product safety standards alignment with international ISO 8124 protocols. Tokyo and Osaka design studios anchor character IP development that feeds licensed toy production across Asian supply chains.
Kids Toys Market Vendor Landscape
Top-tier vendors anchor premium collectible and entertainment-licensed tiers, while mid-scale specialists occupy rapid design-to-shelf niches and regional fabricators serve price-sensitive mass markets. The vendor base clusters around three strategic archetypes: vertically integrated polymer science leaders, IP-dependent licensing specialists, and agile design-cycle operators. Dominant competitive moves include entertainment studio partnership renegotiations and captive resin supply consolidation.
Within the vertically integrated archetype, The LEGO Group exemplifies margin control through in-house polymer science capabilities. Mattel occupies a position as an IP-dependent licensing anchor with deep entertainment studio relationships. Spin Master represents the agile design-cycle operator, differentiating through rapid prototyping in action figure segments.
| Leading Market Players |
|---|
| Hasbro |
| MGA Entertainment |
| The LEGO Group |
| Jakks Pacific |
| TOMY Company |
| Bandai Namco |
| Spin Master |
| Funko |
| Mattel |
| Others |
Supply Flow & Price Mechanics
EU REACH cadmium and phthalate restrictions gate qualified polymer supply and premium-tier pricing access, forcing manufacturers to either absorb certification costs or segment offerings across compliance-grade tiers. Buyers in Nordic and German markets pay measurable premiums for REACH-aligned products while commodity tiers face margin compression from petroleum feedstock volatility.
Pricing Analysis
Subscription-box bundling versus transactional unbundling splits the market between recurring revenue models and traditional retail markups. Three-tier pricing structure across premium collectible, standard branded, and economy private-label levels differentiates by certification grade and material traceability. Cost compression in economy tiers is intensifying because petroleum resin volatility transfers directly to ABS and polypropylene-dependent lines. Mass-market discount retailers exhibit highest price sensitivity while collector-grade buyers in Japan and the United States demonstrate inelastic demand for limited-edition releases.
Supply Chain Analysis
Direct-to-parent subscription channels handle millennial caregiver demand while traditional wholesale routes serve experiential retail destinations. Manufacturing concentrates in China's Guangdong province, India's Tamil Nadu corridor, and Vietnam's emerging molding clusters. Formulation chemists, FSC-certified timber, and rare-earth magnet components constitute critical input dependencies. Single-source vulnerability in Guangdong's mold-making ecosystem poses structural risk given dual-compliance pressure from REACH-aligned European markets and China's GB 6675 enforcement. Distribution runs through integrated e-commerce platforms, specialty toy store networks, and organized retail formats in India's metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through bio-based material substitution that commands premium positioning in sustainability-sensitive segments while reducing petroleum feedstock exposure.
For Market Incumbents: Anchor polymer science capabilities through captive resin formulation or long-term Sinopec supply contracts to defend against petroleum volatility. Consolidate certification teams to compress multi-jurisdiction approval timelines for ASTM F963, ISO 8124, and GB 6675 alignment. Licensing agreement renegotiations with entertainment studios represent the priority threat given escalating revenue participation demands.
For New Entrants and Emerging Players: Capture white space in India's organized retail corridor where branded shelf space is displacing unorganized local manufacturers. Target timber-textile hybrid segments in German and Scandinavian infant markets where sustainability certifications drive purchase decisions. Deploy direct-to-parent subscription models to bypass wholesale markups and capture granular consumption data.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale agile design-cycle operators because entertainment licensing concentration creates acquisition targets with embedded IP relationships. Five-to-ten year viability hinges on connected toy digital privacy compliance positioning. Watch for SAMR enforcement intensity in China's GB 6675 updates as the inflection signal for consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Bio-based Material Transition | REACH-aligned phthalate-free polymers command premium positioning in EU and Nordic markets. |
| Direct-to-Consumer Subscription Launch | Monthly curated deliveries bypass retail markups while capturing recurring revenue and consumption data. |
| Certification Investment Acceleration | Simultaneous ASTM F963, ISO 8124, and GB 6675 approvals compress seasonal launch timelines. |
| Entertainment Licensing Partnership | Studio IP relationships anchor action figure and doll development cycles in Los Angeles and New York corridors. |
| India Organized Retail Expansion | Modern trade formats in Mumbai, Delhi, and Bangalore create branded shelf space for premium positioning. |
Methodological Framework
Coverage spans the United States, Germany, China, India, and Japan, with primary inputs from each market cluster combining interviews with toy brand managers, retail category buyers, polymer formulation chemists, and supply chain planners. Secondary validation draws from CPSC enforcement records, ECHA REACH restriction updates, SAMR GB 6675 compliance bulletins, and customs trade data. Bottom-up SKU-level modeling triangulates against top-down macroeconomic drivers.
Granularity extends to product type, age group, material composition, and sales channel dimensions across the projection horizon. CAGRs derive from segment-level volume trajectories weighted by pricing tier mix. Forecast inputs incorporate petroleum resin futures curves, entertainment licensing pipeline visibility, and regulatory enforcement intensity indices.
Petroleum price volatility, entertainment studio IP renegotiation cycles, and digital privacy rule evolution for connected toys are the dominant revision risks. Forecasts reflect assumptions on parental STEAM prioritization persistence and subscription-box adoption curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Toys and Games
United States Toys Market
Toys and Games
Decompression Toys Market
Toys and Games
Smart/AI Toys Market
Toys and Games
Bounce House Market
Toys and Games
Baby Toys Market
Toys and Games
Drone for Kids Market
Toys and Games
Snooker Tables Market
Toys and Games
Bath Toy Market
Toys and Games
Toy Collectibles Market
Toys and Games
Claw Machine Market
Toys and Games
Cat Toys Market
Toys and Games
Kids Recreational Services Market
Toys and Games
Kid's Microphone Market
Toys and Games
Remote Control Products - Hobby Market
Toys and Games
Toy Building Blocks Market
Toys and Games
Global Educational Toy Market