
 United States Toys Market | 2026-2036
United States Toys Market Size, Share, and Industry Trends Forecast 2026-2036
United States Toys Market Outlook
The Consumer Product Safety Improvement Act is expanding compliance obligations across domestic toy supply chains. Hasbro leverages its in-house manufacturing footprint to absorb testing costs without retail price escalation. Mattel sustains market presence through backward integration into recycled plastic feedstocks. LEGO Group USA dominates the construction category through captive resin formulation expertise.
Toys comprise play objects engineered from polymers, timber substrates, textile composites, or alloy components, designed to stimulate cognitive, motor, or social development in users from infancy through adolescence; injection molding and rotational casting remain dominant fabrication methods, with ASTM F963 serving as the baseline safety specification for mechanical and chemical properties. Educational Toys anchors margin pools as parents prioritize developmental outcomes over entertainment value alone. Plastic materials lead volume throughput due to cost scalability, though Wood segments occupy premium positioning in specialty retail channels. Online Retailers compete most aggressively on price transparency, while Specialty Stores control discovery-driven purchases.
The Consumer Product Safety Commission enforces mandatory third-party testing for lead content and phthalate exposure, compelling manufacturers to maintain redundant laboratory relationships. ASTM International publishes voluntary standards that retailers treat as de facto procurement prerequisites, filtering market access for smaller importers. California's Proposition 65 adds state-level chemical disclosure burdens that national distributors must harmonize across SKUs. Stakeholders should monitor how state-level chemical restrictions proliferate beyond federal baselines.
Market Dynamics
The Consumer Product Safety Improvement Act is compressing product development timelines while simultaneously elevating testing overhead, forcing manufacturers to restructure laboratory partnerships and absorb compliance costs into margin structures rather than retail pricing.
Growth Catalysts
- STEM Curriculum Integration:School districts in Texas and California are mandating hands-on science modules, pulling construction toys and coding kits into institutional procurement channels.
- ASTM F963 Harmonization:Voluntary standards adopted by major retailers as de facto entry requirements are filtering out low-quality imports and consolidating shelf access for compliant domestic suppliers.
- Recycled Polymer Feedstocks:Mattel's backward integration into post-consumer plastic sourcing demonstrates scalable pathways for margin-positive sustainability positioning.
Market Restraints
- Resin Price Volatility:Captive formulation expertise at LEGO Group USA insulates against petrochemical input swings that strain smaller rotational molders.
- Laboratory Capacity Bottlenecks:Third-party testing backlogs under CPSC-mandated protocols extend lead times for seasonal product launches.
- Digital Entertainment Substitution:Tablet-based interactive content captures discretionary spending previously allocated to physical play objects in suburban households.
Strategic Opportunities
- Neurodivergent-Specific Design:Sensory-calibrated toy architectures for autism spectrum users remain underaddressed in mass retail assortments.
- California Proposition 65 Compliance Services:Chemical disclosure harmonization across SKUs creates advisory revenue streams for testing laboratories serving national distributors.
- Direct-to-Consumer Subscription Models:Curated monthly STEM kit deliveries bypass shelf-space competition and capture recurring revenue from millennial parents.
Industry Challenges
- Phthalate Testing Protocol Complexity:Redundant laboratory relationships required for CPSC compliance strain operational bandwidth at mid-tier manufacturers.
- Seasonal Demand Concentration:Q4 revenue compression forces working capital intensity that disadvantages non-vertically integrated suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Toys Market |
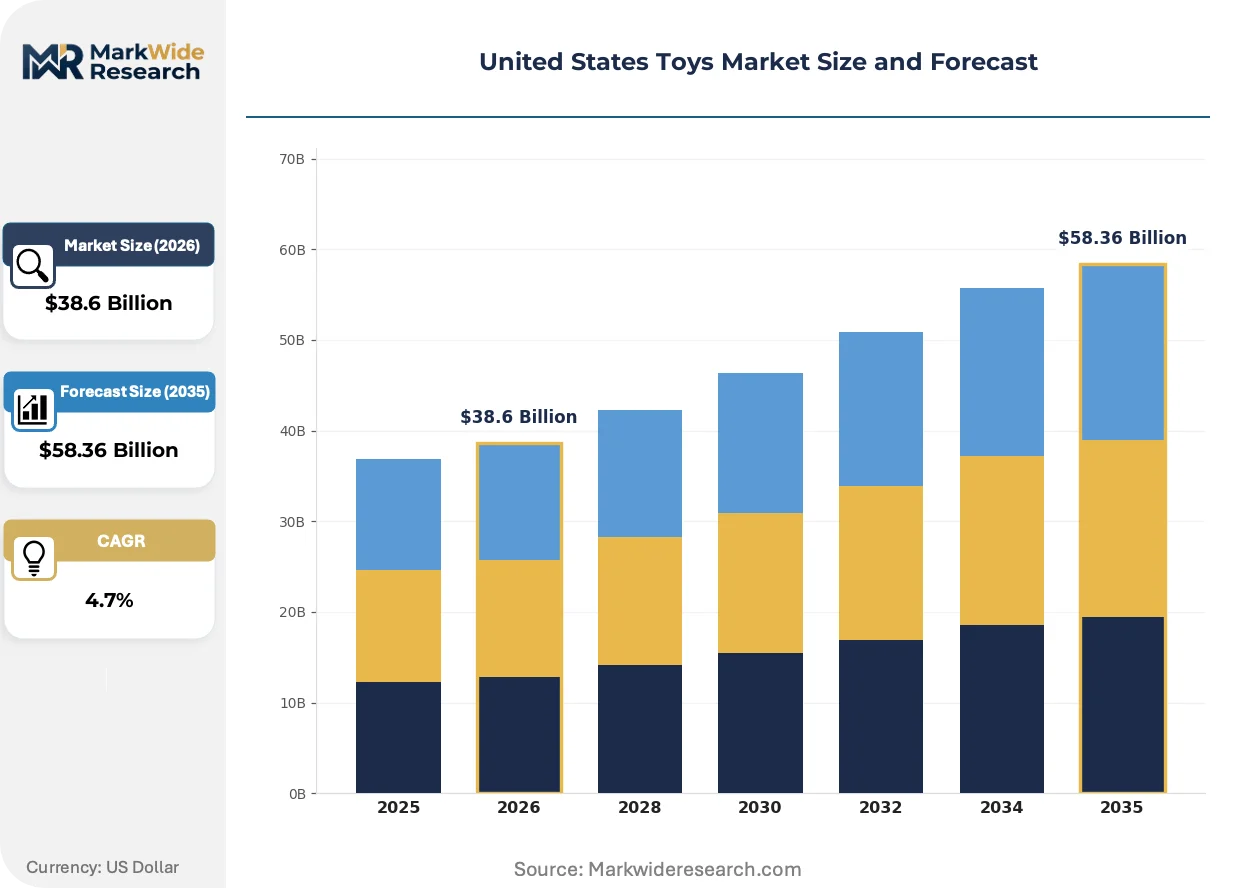
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $58.36 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Action Figures, Dolls, Educational Toys, Board Games Age Group: Infants, Toddlers, Preschoolers, Teens Material: Plastic, Wood, Fabric, Metal Sales Channel: Online Retailers, Supermarkets, Specialty Stores, Discount Stores |
| Companies Covered | Spin Master, Funko, Hasbro, Jakks Pacific, VTech, Mattel, MGA Entertainment, Melissa & Doug, LEGO Group USA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Toys Market Strategic Shifts
Digital-physical hybrid play systems are fragmenting traditional category boundaries, while regulatory chemical disclosure mandates and millennial parental preference for developmental outcomes over entertainment value are compressing legacy product lifecycles.
Biobased polymer formulations derived from agricultural waste streams are expanding into mainstream injection molding operations. Midwest compounders are adopting these materials at pilot scale to preempt California's escalating chemical restriction thresholds. The structural consequence is a bifurcation between premium-positioned sustainable SKUs and conventional petroleum-based economy lines.
California's Proposition 65 enforcement is intensifying warning label obligations for phthalate and lead content across national toy assortments. Retailers are treating state-level disclosure as the operational ceiling, applying California standards to inventory distributed nationwide. Small importers lacking compliance infrastructure are exiting mass-market channels entirely.
Millennial parents are prioritizing toys with explicit developmental outcome claims over entertainment-focused alternatives. Specialty stores in Texas metropolitan clusters are capturing this demand through staffed play-floor demonstrations that online retailers cannot replicate. The shift is most visible in higher-income suburban zip codes where educational attainment correlates with premium price tolerance.
United States Toys Market Segmentation
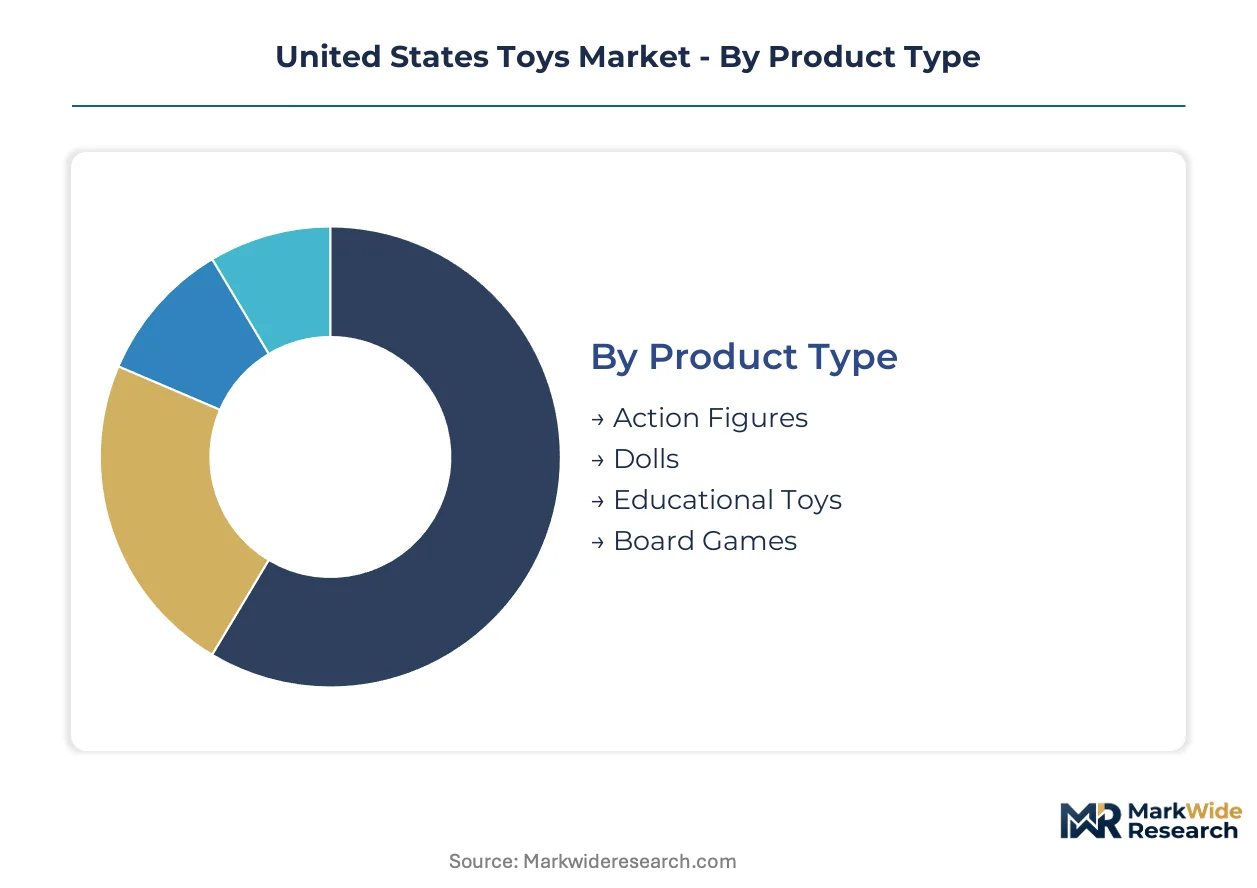
Toy manufacturers configure production lines around discrete demand clusters that dictate resin formulation, safety testing protocols, and distribution partnerships. Segmentation discipline determines which SKUs absorb compliance overhead efficiently and which channels warrant dedicated inventory positioning.
Product Type:
Educational Toys and Board Games demand the heaviest upfront investment in curriculum alignment testing and child-development certification infrastructure.
- Educational Toys:STEM-focused construction sets and coding kits require ASTM F963 compliance layered with state-level curriculum standards. Texas school districts and California entertainment corridor households concentrate institutional and premium consumer demand respectively. Millennial parents drive substitution away from entertainment-only SKUs.
- Board Games:Cardboard substrate printing and injection-molded playing pieces involve lower tooling costs than electronic alternatives but carry seasonal working capital intensity. Family-oriented suburban clusters in Texas metropolitan areas sustain core volume.
- Action Figures:Licensed character molds carry royalty burdens and rapid obsolescence cycles.
- Dolls:Textile-component sourcing and hair-fiber safety testing add SKU complexity.
Educational Toys absorb the bulk of installed capacity; Board Games is expanding most quickly through subscription-box channels.
Age Group:
Infants and Toddlers segments command the steepest safety-testing premiums due to mouthing behavior assumptions and choke-hazard protocols.
- Infants:Rigid polymer teethers and fabric sensory objects face CPSC-mandated third-party laboratory verification for phthalate and lead content. California Proposition 65 disclosure obligations apply uniformly to national assortments.
- Toddlers:Gross-motor development toys with push-pull mechanisms concentrate in specialty retail channels where staffed demonstrations validate parental purchase decisions.
- Preschoolers:Construction-category entry points bridge into Educational Toys with explicit developmental outcome marketing.
- Teens:Collectible and hobby-grade segments escape toy-safety jurisdiction but compete directly with digital entertainment substitutes.
Toddlers commands the highest per-unit compliance overhead; Preschoolers gains share fastest as STEM curriculum integration pulls demand forward.
Material:
Plastic and Wood segments diverge sharply in capital requirements—petrochemical feedstock contracts versus timber certification and CNC machining infrastructure.
- Plastic:Injection molding and rotational casting dominate fabrication with cost scalability across volume tiers. Mattel's backward integration into recycled polymer feedstocks demonstrates margin-positive sustainability pathways.
- Wood:Premium positioning in specialty retail channels relies on FSC certification and non-toxic finish compliance. Midwest compounders pilot agricultural-waste biobased alternatives to preempt California chemical restrictions.
- Fabric:Textile composites require flammability testing under CPSIA protocols.
- Metal:Alloy components concentrate in die-cast collectibles and mechanical puzzles with limited volume throughput.
Plastic holds the dominant installed base; Wood climbs the fastest on sustainability-premium pricing.
Sales Channel:
Specialty Stores and Online Retailers demand divergent inventory models—discovery-driven experiential staffing versus algorithmic price transparency.
- Specialty Stores:Staffed play-floor demonstrations in Texas metropolitan clusters and California entertainment corridor locations capture millennial parent demand for developmental outcome validation. Discovery-driven purchases tolerate premium pricing.
- Online Retailers:Price transparency and subscription-box curation bypass shelf-space competition. Direct-to-consumer STEM kit deliveries capture recurring revenue with lower customer acquisition costs than physical retail.
- Supermarkets:Impulse placement and seasonal promotional intensity compress margins.
- Discount Stores:Economy-tier SKUs with reduced safety-testing documentation face CPSC enforcement risk.
Specialty Stores anchor margin extraction; Online Retailers shows the steepest expansion trajectory on subscription-model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic production capacity concentrates in coastal manufacturing zones while consumption clusters track suburban household density and school district procurement budgets.
California
Millennial parents in Los Angeles and San Francisco metropolitan corridors prioritize STEM educational toys with explicit developmental outcome claims. Proposition 65 enforcement by the California Attorney General's office intensifies chemical disclosure obligations for phthalate and lead content across national toy assortments. The entertainment corridor spanning Burbank to Irvine anchors licensed character product development and specialty retail flagship locations.
Texas
Dallas-Fort Worth and Houston metropolitan retail clusters sustain volume throughput for construction toys and board games through family-oriented suburban demographics. School districts in Austin and San Antonio mandate hands-on science modules, pulling coding kits into institutional procurement channels. The state's franchise tax structure supports distribution center placement for direct-to-consumer fulfillment operations.
New York Metro
Greater New York's dense urban population drives demand for compact, apartment-friendly toy formats with storage-efficient packaging. The Consumer Product Safety Commission's Northeast regional office in Bethesda coordinates with New York State Department of Health on lead testing protocol enforcement. Specialty toy retail in Manhattan and Brooklyn captures discovery-driven purchases through staffed experiential floors.
Midwest Manufacturing Belt
Illinois, Michigan, and Ohio host rotational molding and injection molding operations serving private-label and branded toy production. Agricultural waste stream biopolymer pilot programs in Indiana and Iowa compounders preempt California chemical restriction thresholds. Chicago's logistics infrastructure supports seasonal inventory positioning for Q4 demand compression.
Pacific Northwest
Seattle and Portland households exhibit premium price tolerance for sustainably sourced wood toys with FSC certification and non-toxic finish compliance. Washington State's Department of Ecology administers additional chemical reporting requirements beyond federal CPSIA baselines. The region's tech sector density correlates with parental preference for digital-physical hybrid play systems.
United States Toys Market Competitive Environment
The competitive structure tilts toward diversified entertainment conglomerates with captive manufacturing footprints. Mid-tier specialists compete through curriculum-aligned educational positioning and sustainability-premium pricing. Three archetypes dominate: vertically integrated resin formulators, licensed-character portfolio managers, and direct-to-consumer subscription curators. Capacity expansion and backward integration into recycled feedstocks represent the dominant competitive moves.
Within the diversified entertainment tier, Hasbro and Mattel occupy positions that exemplify compliance-scale advantages under CPSC-mandated testing protocols. LEGO Group USA anchors the construction category through captive supply of specialized polymer formulations. Among mid-tier specialists, Spin Master and Funko represent archetypes of licensed-character portfolio management and pop-culture collectible positioning respectively.
| Leading Market Players |
|---|
| Spin Master |
| Funko |
| Hasbro |
| Jakks Pacific |
| VTech |
| Mattel |
| MGA Entertainment |
| Melissa & Doug |
| LEGO Group USA |
| Others |
Value Chain & Pricing Dynamics
Petrochemical resin contracts cascade through three pricing tiers based on compliance documentation depth and captive formulation capabilities. ASTM F963 certification overhead concentrates in premium SKUs where LEGO Group USA and Mattel absorb testing costs without retail escalation, while economy-tier imports face margin compression from CPSC-mandated laboratory redundancy.
Pricing Analysis
Developmental outcome claims anchor value-based pricing for STEM educational toys, with millennial parents tolerating premium positioning when curriculum alignment is explicit. Three-tier pricing structure across premium, standard, and economy levels separates FSC-certified wood assortments from conventional petroleum-based injection molding and discount-tier imports with reduced safety documentation. Price erosion runs through economy channels as California Proposition 65 compliance costs filter out small importers. Institutional procurement in Texas school districts exhibits lowest price sensitivity; discount retail channels face acute margin pressure.
Supply Chain Analysis
Specialty polymer feedstock supply rests on Gulf Coast petrochemical producers and Midwest compounders piloting agricultural-waste biobased alternatives. ABS and polypropylene resins, textile composites for plush components, and FSC-certified timber substrates constitute critical input dependencies. Single-source vulnerability concentrates in captive resin formulation expertise at construction-category leaders. Distribution runs through California entertainment corridor flagship locations, Texas metropolitan retail clusters, and direct-to-consumer fulfillment centers leveraging the state's franchise tax structure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Toys Market sits at a technology-transition inflection where digital-physical hybrid play systems displace legacy entertainment-only SKUs. App-based coding companions and augmented-reality construction overlays are capturing discretionary spending previously allocated to static play objects.
For Market Incumbents: To counter digital entertainment substitution, Hasbro and Mattel should deepen backward integration into recycled polymer feedstocks to sustain margin-positive sustainability positioning. Channel control through staffed experiential floors in Texas and California specialty retail locations defends discovery-driven purchase capture against algorithmic price transparency.
For New Entrants and Emerging Players: Capture neurodivergent-specific design white space where sensory-calibrated architectures for autism spectrum users remain underaddressed in mass retail assortments. Subscription-box curation of monthly STEM kit deliveries offers the most penetrable go-to-market angle, bypassing shelf-space competition while securing recurring revenue from millennial parents.
For Investors and Strategic Acquirers: Mattel's backward integration into post-consumer plastic sourcing is the leading indicator that sustainability-premium positioning will separate viable acquisition targets from stranded legacy assets. Mid-tier specialists with curriculum-aligned educational positioning and captive manufacturing footprints represent the preferred archetype. CPSC enforcement intensity against phthalate testing protocol violations warrants ongoing watch as a consolidation trigger.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Feedstocks | Mattel's polymer sourcing demonstrates scalable pathways for margin-positive sustainability positioning under California chemical restrictions. |
| Direct-to-Consumer Subscription Launch | Curated STEM kit deliveries capture recurring revenue with lower customer acquisition costs than physical retail shelf competition. |
| Neurodivergent-Specific Product Line Extension | Sensory-calibrated toy architectures address underserved autism spectrum demand in mass retail assortments. |
| California Proposition 65 Compliance Services | Chemical disclosure harmonization across SKUs creates advisory revenue streams for testing laboratories serving national distributors. |
| Institutional Procurement Channel Expansion | Texas school district science module mandates pull construction toys and coding kits into recurring educational procurement budgets. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews across toy manufacturing executives, CPSC compliance officers, retail category buyers, and curriculum development specialists at Texas and California school districts. Secondary validation drew from Consumer Product Safety Commission enforcement databases, ASTM International standard revision records, California Attorney General Proposition 65 settlement filings, and Nielsen retail audit data. Bottom-up SKU-level volume modeling triangulated against top-down segment aggregation.
Granularity-level modeling operated at product-type, age-group, material, and sales-channel dimensions, with additional resolution for state-level regulatory cluster variations. CAGRs were derived from trend-line extrapolation moderated by scenario-weighted elasticity assumptions across the projection horizon. Forecast inputs incorporated millennial parent preference surveys, school district procurement budget trajectories, and resin price volatility indices.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to digital entertainment substitution rates and California chemical restriction proliferation beyond federal baselines. Assumptions reflect documented stakeholder input and published regulatory trajectories. A small set of named triggers—CPSC enforcement intensity, biobased polymer scale economics, and subscription-model adoption curves—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Toys and Games
Games and Puzzles Market
Toys and Games
Drone for Kids Market
Toys and Games
Animation Toys Market
Toys and Games
Connected Toys Market
Toys and Games
Baby Toys Market
Toys and Games
Children Entertainment Centers Market
Toys and Games
Wooden Toys Market
Toys and Games
Ferret Toys Market
Toys and Games
Global Fidget Toys Market
Toys and Games
K-12 Instructive Toy Market
Toys and Games
Blind Box Toys Market
Toys and Games
Air Hockey Table Market
Toys and Games
China Toys Market
Toys and Games
Global Blind Boxes Market
Toys and Games
Model Train Market
Toys and Games
Inflatable Toys Market