
 Global Educational Toy Market | 2026-2036
Global Educational Toy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Educational Toy Market Analysis
The EU Green Deal is broadening sustainability requirements for plastic-intensive play products. LEGO Group leverages bio-based polyethylene formulations across its botanical elements line. Mattel anchors its supply chain through in-house recycled resin sourcing. Hasbro navigates shifting retailer procurement rules by phasing out PVC from core packaging.
An educational toy combines engineered materials with pedagogical design to develop cognitive, motor, or social competencies in children through structured play. Manufacturing typically involves injection-molded ABS or sustainably harvested wood with compliance testing for phthalate content and mechanical durability under EN 71 protocols. STEM-focused products lead volume contribution due to parental prioritization of science and mathematics readiness. Science Kits represent the fastest-expanding product type as schools outsource hands-on laboratory experiences to home environments. Wooden materials command premium positioning in European and North American channels where FSC certification drives purchasing decisions.
REACH governs chemical substance thresholds across European distribution channels while the EU Toy Safety Directive mandates mechanical and flammability testing for all consumer-facing play products. The US Consumer Product Safety Commission enforces ASTM F963 compliance through mandatory third-party laboratory certification for toys intended for children under twelve years. Stakeholders must monitor evolving extended producer responsibility frameworks in Germany and France where packaging recovery obligations now encompass e-commerce shipments of educational play products.
Market Dynamics
EU REACH chemical thresholds and the EU Toy Safety Directive are compressing formulation flexibility for plastic-intensive educational play products, forcing manufacturers toward bio-based polyethylene and FSC-certified wood substitutes.
Growth Catalysts
- STEM curriculum mandates:National education ministries in South Korea and Japan are embedding hands-on science kits into compulsory primary schooling, creating institutional procurement pipelines for laboratory-grade home learning equipment.
- REACH compliance premiums:European retailers are awarding shelf-space preference to phthalate-free certified inventory, accelerating material transitions across supplier bases serving German and French distribution channels.
- Seoul-Tokyo-Shanghai demand clustering:East Asian metropolitan preschool enrollment expansion is concentrating volume in high-density urban corridors where dual-income households prioritize structured cognitive development tools.
Market Restraints
- ABS resin price volatility:Petrochemical feedstock fluctuations are compressing margin buffers for injection-molded component producers serving mid-tier product lines.
- Single-origin wood sourcing risk:FSC-certified timber supply concentrates in Nordic and Baltic regions, creating geographic vulnerability for premium European and North American wooden toy manufacturers.
- ASTM F963 third-party certification timelines:Mandatory laboratory testing for US-market entry extends product launch cycles by four to six months, freezing working capital in pre-revenue inventory.
Strategic Opportunities
- Extended producer responsibility tailwinds:Germany's packaging recovery obligations now encompass e-commerce educational toy shipments, creating first-mover advantage for reverse-logistics-capable suppliers.
- AI-augmented personalization:Adaptive learning algorithms converging with physical manipulative design are opening premium price tiers for data-enabled play experiences in affluent East Asian households.
- Direct-to-educator channels:Subscription-based classroom replenishment models are bypassing traditional retail markups, capturing institutional procurement budgets in OECD member state school systems.
Industry Challenges
- EN 71 mechanical durability testing bottlenecks:Accredited laboratory capacity constraints in Europe are extending compliance verification queues, delaying seasonal product releases.
- Cross-border chemical documentation complexity:Divergent substance notification requirements between REACH, ASTM F963, and Japan's Food Sanitation Law are fragmenting formulation standardization efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Educational Toy Market |
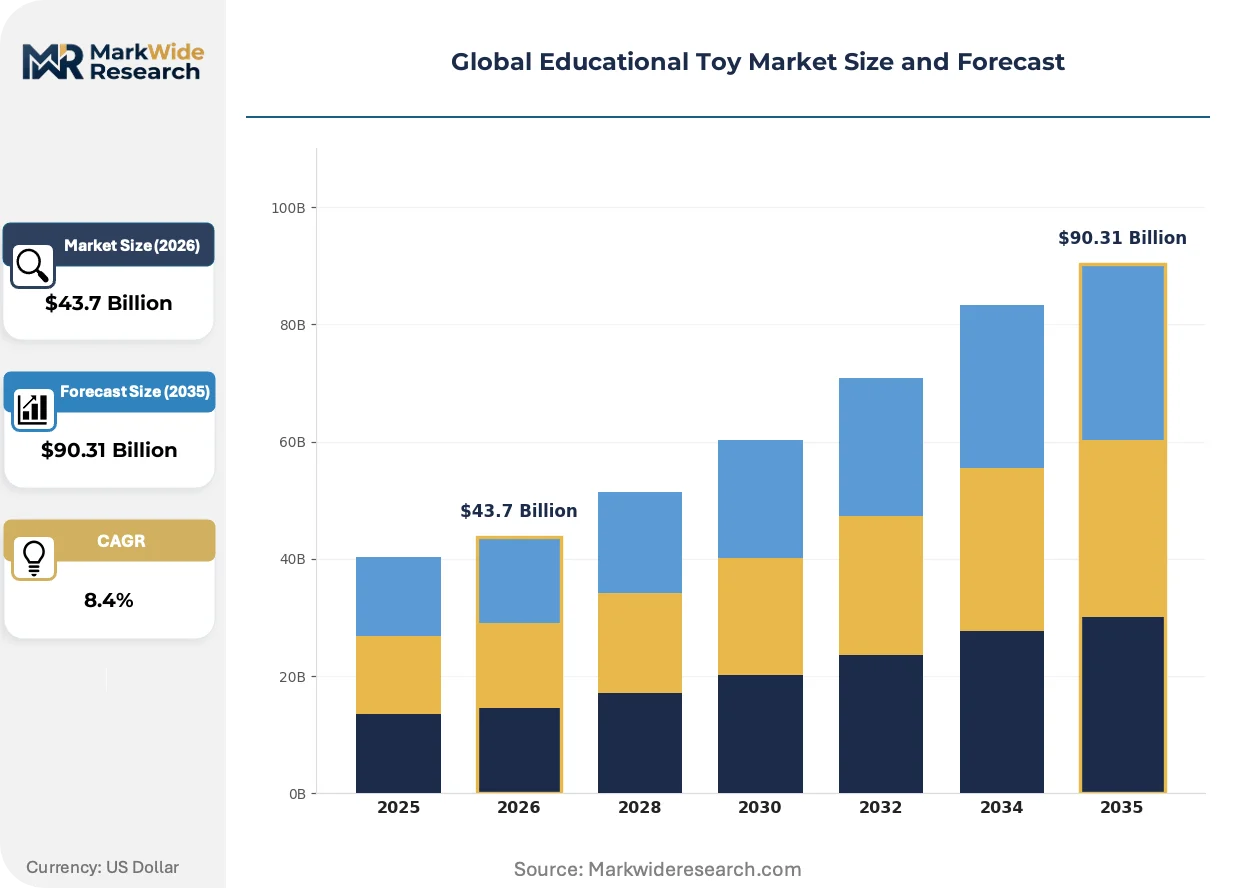
| Market Size in 2026 | $43.7 Billion |
| Market Size in 2035 | $90.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Building Blocks, Puzzles, Educational Games, Science Kits Age Group: Toddlers, Preschoolers, Primary School, Teens Learning Focus: STEM, Language Development, Creative Arts, Social Skills Material: Wood, Plastic, Metal, Fabric |
| Companies Covered | LEGO Group, Mattel, Hasbro, VTech Holdings Limited, Melissa & Doug, Spin Master, Ravensburger, TOMY Company, Bandai Namco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Educational Toy Market Emerging Trajectories
Educational toy architecture is fragmenting into interoperable component ecosystems, replacing monolithic product designs with upgradeable, curriculum-aligned module systems.
Embedded sensor arrays and microcontroller platforms are modularizing physical play experiences, enabling parents and educators to reconfigure STEM kits across multiple age brackets without full product replacement. South Korean after-school learning centers are adopting these systems at pace, compressing replacement cycles while expanding per-household lifetime value capture.
France's ANSM and Germany's KBA-aligned toy safety enforcement are tightening post-market surveillance protocols, requiring batch-level traceability documentation for all plastic-contact components. Manufacturers serving European Union distribution channels are responding by implementing blockchain-anchored supply chain records, with science kit producers facing the steepest compliance cost escalation due to chemical reagent inclusion.
Certification-driven purchasing is displacing price-first selection in North American specialty retail, with ASTM F963 third-party laboratory documentation now functioning as a binary shelf-access filter. Independent toy boutiques in California and New York metropolitan areas are prioritizing certified inventory, squeezing uncertified competitors toward discount e-commerce channels where documentation requirements remain enforcement-light.
Global Educational Toy Market Segmentation
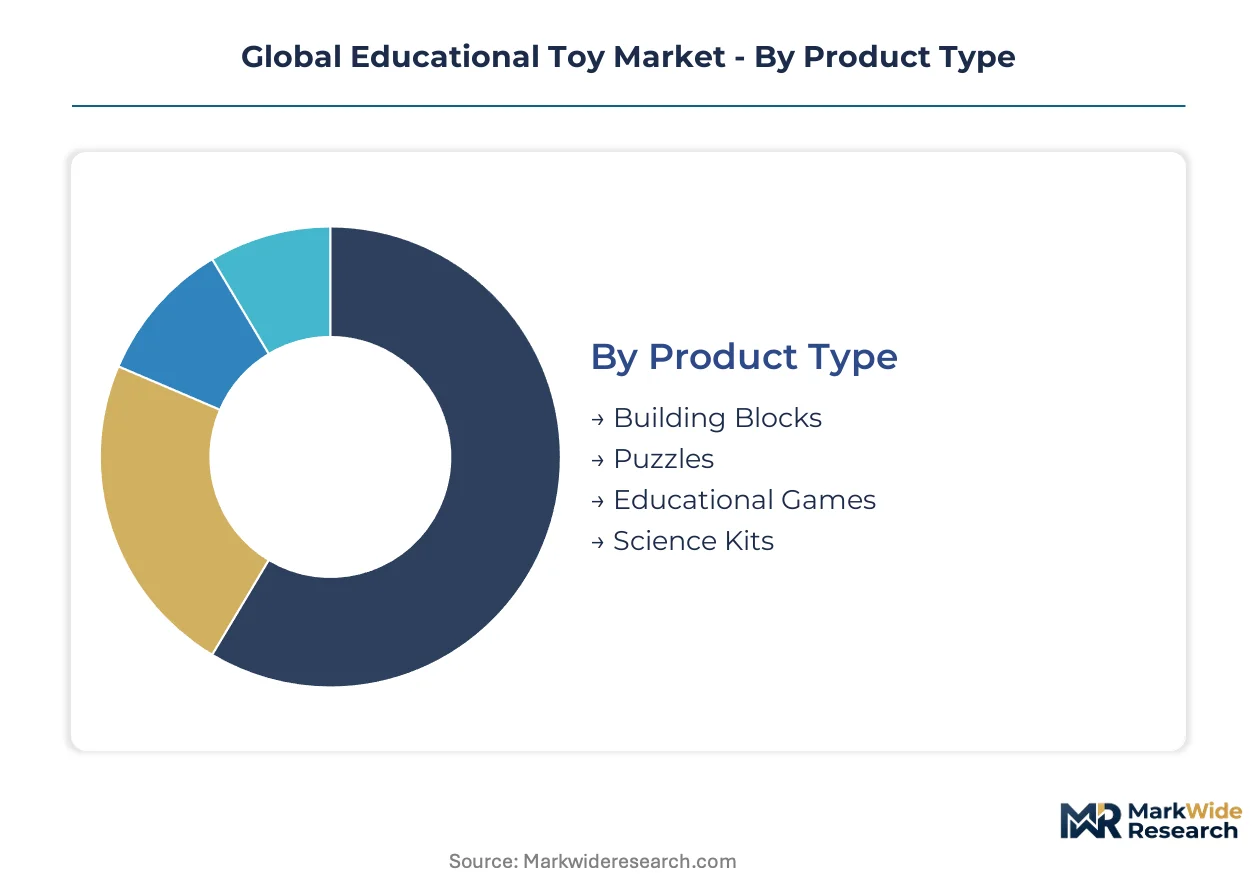
Educational toy segmentation reveals how pedagogical priorities, safety regulations, and material science converge to shape procurement patterns. Manufacturers configure product lines across multiple axes simultaneously, with material compliance and age-appropriate cognitive targeting driving portfolio architecture decisions.
Product Type:
Standardization dominates injection-molded formats while modular science kits demand extensive customization for curriculum alignment and regional safety documentation.
- Science Kits:Laboratory-grade chemical reagents and instrumentation components require batch-level traceability under France's ANSM and Germany's KBA post-market surveillance protocols. Seoul's after-school learning centers are adopting modular reconfigurable systems that compress replacement cycles while expanding per-household lifetime value capture.
- Building Blocks:Interlocking ABS or bio-based polyethylene elements with geometric precision tolerances. Tokyo metropolitan preschool enrollment expansion is concentrating volume in high-density corridors where dual-income households prioritize structured cognitive development tools.
- Puzzles:Die-cut cardboard or wooden assemblies with progressive difficulty gradients.
- Educational Games:Board-based or digital-physical hybrid formats incorporating adaptive learning algorithms.
Most installed capacity flows through Building Blocks. Expansion is steepest in Science Kits.
Age Group:
Margin structures widen with age as product complexity and certification burden escalate simultaneously.
- Preschoolers:Manipulative toys emphasizing fine motor development and early numeracy with EN 71 mechanical durability testing requirements. Shanghai's dual-income households are driving premium positioning for FSC-certified wooden formats in this bracket.
- Primary School:Curriculum-aligned STEM equipment with institutional procurement pathways through South Korean and Japanese education ministry mandates for hands-on science kit integration.
- Toddlers:Large-format, non-chokable elements with phthalate-free material certification under REACH thresholds.
- Teens:Advanced robotics and coding platforms with microcontroller integration.
Volume concentrates in Preschoolers. Value capture is climbing fastest in Primary School.
Learning Focus:
Customer procurement authority shifts from parental retail selection toward institutional budget allocation across this spectrum.
- STEM:Science, technology, engineering, and mathematics manipulatives combining physical components with embedded sensor arrays. Japan's METI curriculum guidelines are embedding laboratory-grade home learning equipment into compulsory primary schooling.
- Creative Arts:Open-ended material sets for aesthetic and tactile exploration with lower regulatory burden than chemical-inclusive science formats.
- Language Development:Phonetic and literacy tools with audio-integrated physical components.
- Social Skills:Cooperative play formats emphasizing turn-taking and emotional recognition.
STEM commands the largest installed base. Creative Arts is gaining share fastest among premium European channels.
Material:
Supply geography and certification cost structures fragment competitive positioning across this category.
- Plastic:Injection-molded ABS or bio-based polyethylene formulations with REACH phthalate compliance and ASTM F963 third-party laboratory certification for US-market entry. Mattel's in-house recycled resin sourcing and Hasbro's PVC phase-out from core packaging illustrate material transition strategies.
- Wood:FSC-certified timber from Nordic and Baltic regions with premium positioning in European and North American channels where certification drives purchasing decisions. Geographic concentration creates supply vulnerability for manufacturers dependent on single-origin sourcing.
- Metal:Precision-machined components for mechanical and structural applications in advanced STEM kits.
- Fabric:Textile-based manipulatives with lower durability requirements and reduced regulatory testing burden.
Plastic retains the deepest installed capacity. Wood is expanding most quickly in premium positioning strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Denmark pioneered mass-scale plastic brick manufacturing in the mid-twentieth century, establishing design and material science foundations that now diffuse across East Asian production clusters. Educational toy demand now concentrates in metropolitan corridors where dual-income households prioritize structured cognitive development tools.
United States
California and New York metropolitan specialty retailers filter inventory through ASTM F963 third-party laboratory certification requirements, squeezing uncertified competitors toward discount e-commerce channels. The Consumer Product Safety Commission enforces mandatory testing protocols for all play products targeting children under twelve years. Greater Boston's after-school learning center density drives institutional procurement of laboratory-grade home science equipment.
Germany
Baden-Württemberg and Bavaria host precision manufacturing clusters supplying FSC-certified wooden components to premium European channels. The country's packaging recovery obligations under extended producer responsibility frameworks now encompass e-commerce educational toy shipments, creating first-mover advantage for reverse-logistics-capable suppliers. KBA-aligned enforcement tightens post-market surveillance protocols requiring batch-level traceability documentation.
Japan
Tokyo and Osaka metropolitan preschool enrollment expansion concentrates volume in high-density corridors where METI curriculum guidelines embed hands-on science kits into compulsory primary schooling. The Food Sanitation Law imposes substance notification requirements that fragment formulation standardization efforts for chemical-inclusive products. Nagoya's manufacturing belt supplies precision-machined components for advanced robotics platforms.
South Korea
Seoul's after-school learning centers adopt modular reconfigurable STEM systems at pace, compressing replacement cycles while expanding per-household lifetime value capture. National education ministry mandates institutionalize procurement pipelines for laboratory-grade home learning equipment. Daegu-Gyeongbuk's injection-molding capacity serves mid-tier plastic component demand.
China
Shanghai and Yangtze River Delta dual-income households drive premium positioning for FSC-certified wooden formats in preschool brackets. GB standards and SAMR oversight govern domestic distribution while export-oriented producers navigate REACH and ASTM F963 divergence. Pearl River Delta manufacturing clusters supply bio-based polyethylene formulation capacity for botanical element lines.
Global Educational Toy Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across divergent margin structures in the educational toy sector. Injection-molding capacity and FSC-certified timber supply chains anchor consolidated positions among Nordic and East Asian manufacturers, while brand-focused enterprises outsource fabrication to capture design premiums. Three archetypes dominate: integrated material-science specialists controlling resin and wood sourcing, curriculum-aligned platform developers monetizing subscription replenishment, and licensed-character distributors leveraging entertainment IP. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with science kit producers seeking accredited laboratory alliances and wooden toy specialists locking Nordic timber offtake agreements.
Within the integrated material-science tier, LEGO Group and Mattel exemplify divergent bio-polymer strategies, while Hasbro occupies a position navigating retailer procurement rule evolution. Among East Asian platform developers, VTech Holdings Limited represents the electronics-integrated learning segment. Ravensburger and TOMY Company sit within the premium wooden and precision-manufactured archetypes respectively, each anchoring geographic sourcing advantages in European and Japanese distribution channels.
| Leading Market Players |
|---|
| LEGO Group |
| Mattel |
| Hasbro |
| VTech Holdings Limited |
| Melissa & Doug |
| Spin Master |
| Ravensburger |
| TOMY Company |
| Bandai Namco |
| Others |
Supply Flow & Price Mechanics
Tool-and-die engineering clusters in Guangdong and Zhejiang provinces anchor injection-molding capacity for mid-tier ABS components, creating labor-cost differentials that widen spreads between economy-grade science kits and laboratory-certified premium formats. These workforce concentrations compress margins at the standard tier while FSC-certified wooden toy specialists in Nordic regions capture pricing power through scarce certified timber offtake.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ASTM F963-certified laboratory-grade kits from EN 71-compliant mid-market formats and uncertified discount channels. Price differentiation hinges on certification grade and volume scale, with institutional procurement contracts commanding 40-60 unit minimums. Pricing pressure stems from ABS resin feedstock volatility eroding margin buffers in injection-molded segments. Economy-tier buyers in discount e-commerce channels exhibit highest price sensitivity, while German and French specialty retailers prioritize certified inventory regardless of premium positioning.
Supply Chain Analysis
Single-source vulnerability sits with Nordic and Baltic FSC-certified timber suppliers serving premium European and North American wooden toy manufacturers. Geographic supply concentration clusters in China, South Korea, and Germany, with Pearl River Delta bio-based polyethylene formulation feeding botanical element lines and Daegu-Gyeongbuk injection-molding serving mid-tier plastic demand. Raw material dependencies encompass ABS resin, bio-based polyethylene feedstocks, and FSC-certified hardwoods. Tariff exposure on US-bound shipments from Chinese manufacturing bases presents structural supply chain risk. Distribution runs through direct-to-educator subscription channels, traditional specialty retail, and e-commerce marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Educational Toy Market functions as a stable compounder anchored by OECD preschool enrollment expansion and institutional STEM procurement mandates that generate recurring replenishment demand.
For Market Incumbents: Cement control over FSC-certified timber offtake agreements in Nordic regions to defend against supply-constrained competitors. Lock in accredited laboratory capacity partnerships to compress EN 71 and ASTM F963 certification timelines that currently freeze working capital. Prioritize backward integration into bio-based polyethylene formulation to offset petrochemical feedstock volatility threatening mid-tier margin structures. For New Entrants and Emerging Players: Begin with modular reconfigurable science kit platforms targeting Seoul and Tokyo after-school learning centers, where institutional procurement pipelines remain underpenetrated by Western suppliers. Exploit white-space in direct-to-educator subscription replenishment models bypassing traditional retail markups. Position through curriculum-aligned content partnerships with South Korean and Japanese education ministries. For Investors and Strategic Acquirers: Curriculum-aligned platform developers with captive educator relationships are the most active acquirer target category in this space. Long-term viability rests on recurring revenue visibility from institutional subscription models rather than transactional retail cycles. Monitor extended producer responsibility framework expansion across EU member states as inflection signal for reverse-logistics capability premiums.| Strategic Initiative | Industry Significance |
|---|---|
| FSC-Certified Timber Offtake Agreement | Locks scarce Nordic supply for premium wooden toy positioning against competitors. |
| Accredited Laboratory Capacity Partnership | Compresses ASTM F963 certification timelines that delay US market entry. |
| Direct-to-Educator Subscription Launch | Bypasses retail markups to capture institutional procurement budgets in OECD school systems. |
| Bio-Based Polyethylene Formulation Investment | Aligns product lines with EU Green Deal sustainability requirements for plastic-intensive formats. |
| Curriculum Content Licensing Partnership | Secures institutional placement through South Korean and Japanese education ministry alignment. |
Methodological Framework
Coverage spans North America, Europe, and East Asia, with primary inputs from each region combining interviews with product development executives at toy manufacturers, procurement managers at German and French specialty retailers, curriculum directors at South Korean after-school learning centers, and regulatory affairs specialists navigating REACH and ASTM F963 compliance. Secondary validation draws from customs trade data, SEC 10-K filings of listed toy companies, OECD preschool enrollment statistics, and national education ministry procurement disclosures. Bottom-up segment sizing triangulates against top-down market value estimates.
Rate-of-change decomposition across the analysis window isolates volume drivers from pricing dynamics and mix shifts. Segmentation dimensions modeled include product type, age bracket, learning focus, and material composition alongside regional regulatory cluster differentiation. CAGRs derive from historical trajectory analysis adjusted for policy inflection points such as STEM curriculum mandates and extended producer responsibility expansions. Key inputs encompass petrochemical feedstock price indices, FSC-certified timber supply forecasts, and accredited laboratory capacity utilization rates.
Caveats apply where ABS resin price volatility, EN 71 testing bottleneck extensions, or divergent chemical documentation requirements between REACH and Japan's Food Sanitation Law could materially shift the outlook. Forecasts reflect documented assumptions about institutional procurement continuity and sustainability framework stringency trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Toys and Games
Bounce House Market
Toys and Games
Dildo Sex Toy Market
Toys and Games
Construction Toys Market
Toys and Games
Remote Control Toys Market
Toys and Games
Claw Crane Machine Market
Toys and Games
Baby Toys Market
Toys and Games
Toy Cars Market
Toys and Games
Model Train Market
Toys and Games
Decompression Toys Market
Toys and Games
Toy Kitchens and Play Food Market
Toys and Games
China Playing Cards & Board Games Market
Toys and Games
Board Games and Puzzles Market
Toys and Games
Eco-Friendly Toys Market
Toys and Games
Smart/AI Toys Market
Toys and Games
Australia Toys and Games Market
Toys and Games
United States Toys Market